
 Nordics Freight and Logistics Market | 2026-2036
Nordics Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Nordics Freight and Logistics Market Analytics
The capital-intensity divergence between asset-heavy and asset-light operators is bifurcating competitive dynamics across Nordic freight corridors. DSV A/S leverages its integrated road-sea network to sustain density on Denmark-Norway lanes. PostNord Sverige AB anchors last-mile coverage through its domestic Swedish infrastructure. NTG Nordic Transport Group competes via specialized project-cargo capabilities in renewable-energy logistics.
Nordics freight and logistics encompasses the physical movement of goods via multimodal networks—road, sea, air, and rail—coordinated through digital platforms with GPS tracking, warehouse automation, and IoT-enabled cargo monitoring, serving industrial supply chains and consumer delivery. Road Freight dominates volume flows between Scandinavian population centers, while Sea Freight captures margin pools on Baltic and North Atlantic routes. Warehouse Automation within the Technology segment attracts capital as labor costs rise across Denmark and Sweden.
Swedish regulators enforce carbon-emission standards for heavy-duty vehicles, while Norwegian authorities mandate shore-power connectivity at port terminals; both frameworks accelerate fleet electrification and terminal infrastructure spending. Danish maritime authorities coordinate with EU Green Deal vessel-fuel protocols, tightening access for non-compliant operators. Stakeholders must monitor how Nordic carbon-border adjustments reshape cross-border haulage economics and terminal investment priorities.
Market Dynamics
Sweden's carbon-emission standards for heavy-duty vehicles are forcing fleet operators across Denmark, Norway, and Finland to accelerate electrification timelines and restructure procurement budgets around battery-electric and hydrogen fuel-cell platforms.
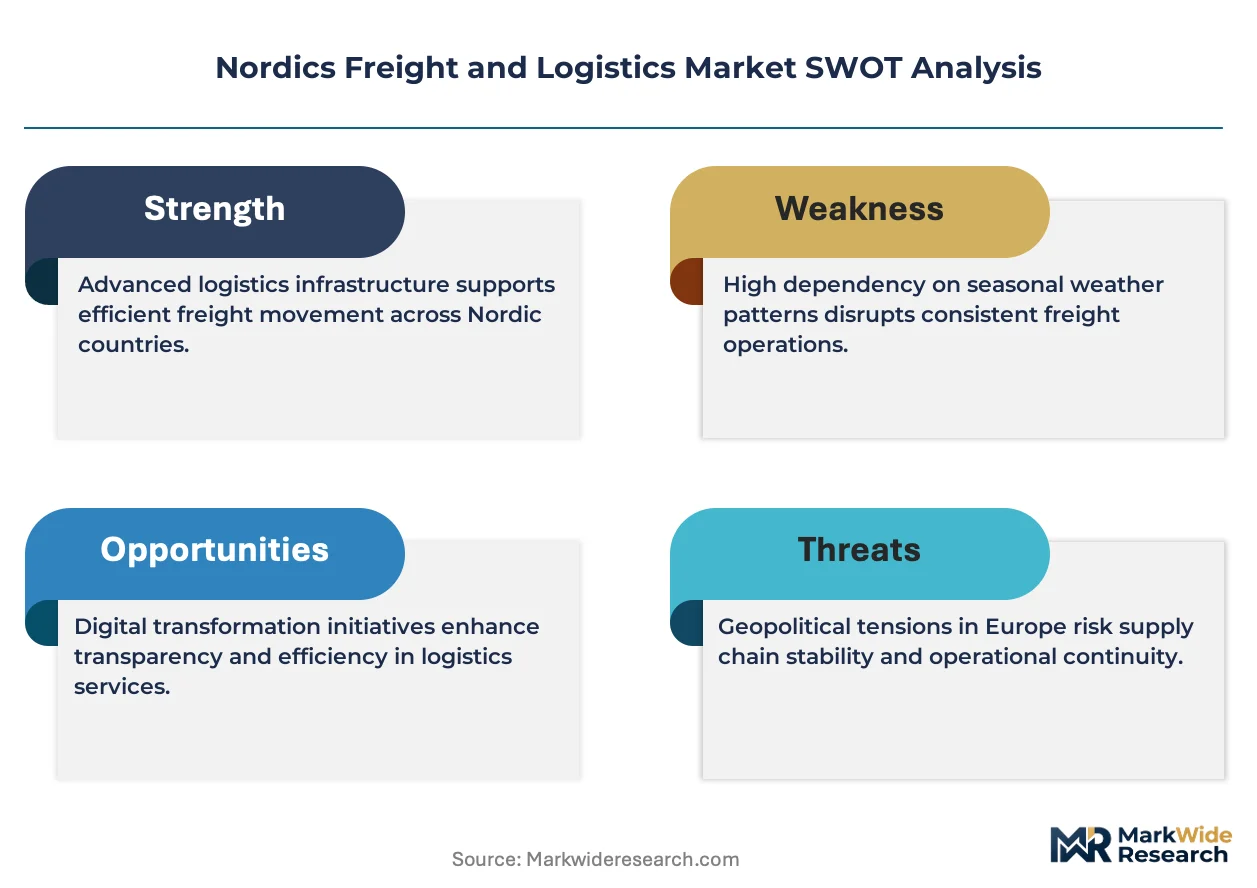
Growth Catalysts
- E-commerce fulfillment networks:Pharmaceutical distributors in Norway are expanding temperature-controlled last-mile capacity to serve remote coastal communities. Cold-chain infrastructure investments concentrate around Oslo and Bergen corridors.
- EU Green Deal vessel-fuel protocols:Danish maritime authorities are tightening berth access for non-compliant operators, redirecting capital toward shore-power retrofits at Copenhagen and Aarhus terminals.
- Renewable energy logistics:Offshore wind farm construction across the Kattegat and North Sea is generating specialized project-cargo demand for blade transport and foundation installation.
Market Restraints
- Electrification capex burden:Battery-electric truck acquisition costs run 2.5-3x above diesel equivalents, compressing margins for small fleet operators in Finland and rural Sweden.
- Charging infrastructure gaps:Norway's Arctic Highway and Sweden's E10 through Lapland lack high-capacity charging, limiting electric vehicle deployment on cross-border haulage routes.
- Skilled technician shortage:Maintenance networks for fuel-cell and high-voltage systems remain concentrated around Stockholm, Copenhagen, and Oslo, creating service deserts.
Strategic Opportunities
- Finnish-Russian border reconfiguration:Eastern logistics corridors are pivoting toward Baltic Sea shipping via Tallinn and Riga, creating demand for multimodal transshipment hubs in southern Finland.
- Autonomous platooning pilots:Sweden's Transport Agency is permitting driver-assist convoys on E4 motorway segments, opening regulatory space for technology validation before broader Nordic rollout.
- Green ammonia bunkering:Norwegian port authorities at Stavanger and Haugesund are developing fueling infrastructure for next-generation deep-sea vessels, attracting maritime service investment.
Industry Challenges
- Legacy warehouse management integration:Automated storage and retrieval systems from Swedish and Danish robotics suppliers require costly middleware to connect with incumbent ERP platforms.
- Cross-border customs friction:Post-Brexit documentation complexity for UK-Nordic freight is forcing operators to maintain dual compliance teams and redundant inventory positioning.
- Driver demographic compression:Retirement waves among heavy-goods vehicle operators in Denmark and Norway are outpacing training pipeline output, tightening capacity during peak seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordics Freight and Logistics Market |
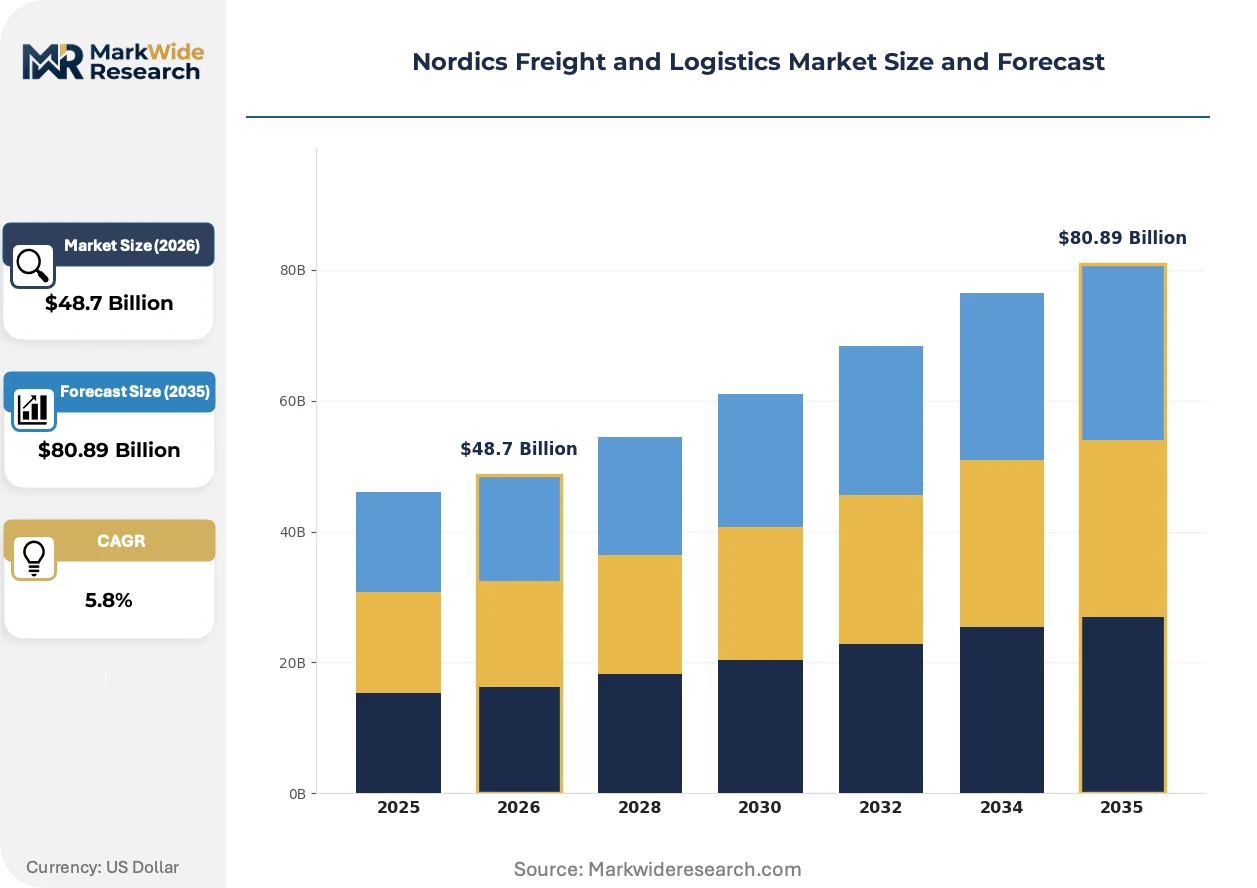
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
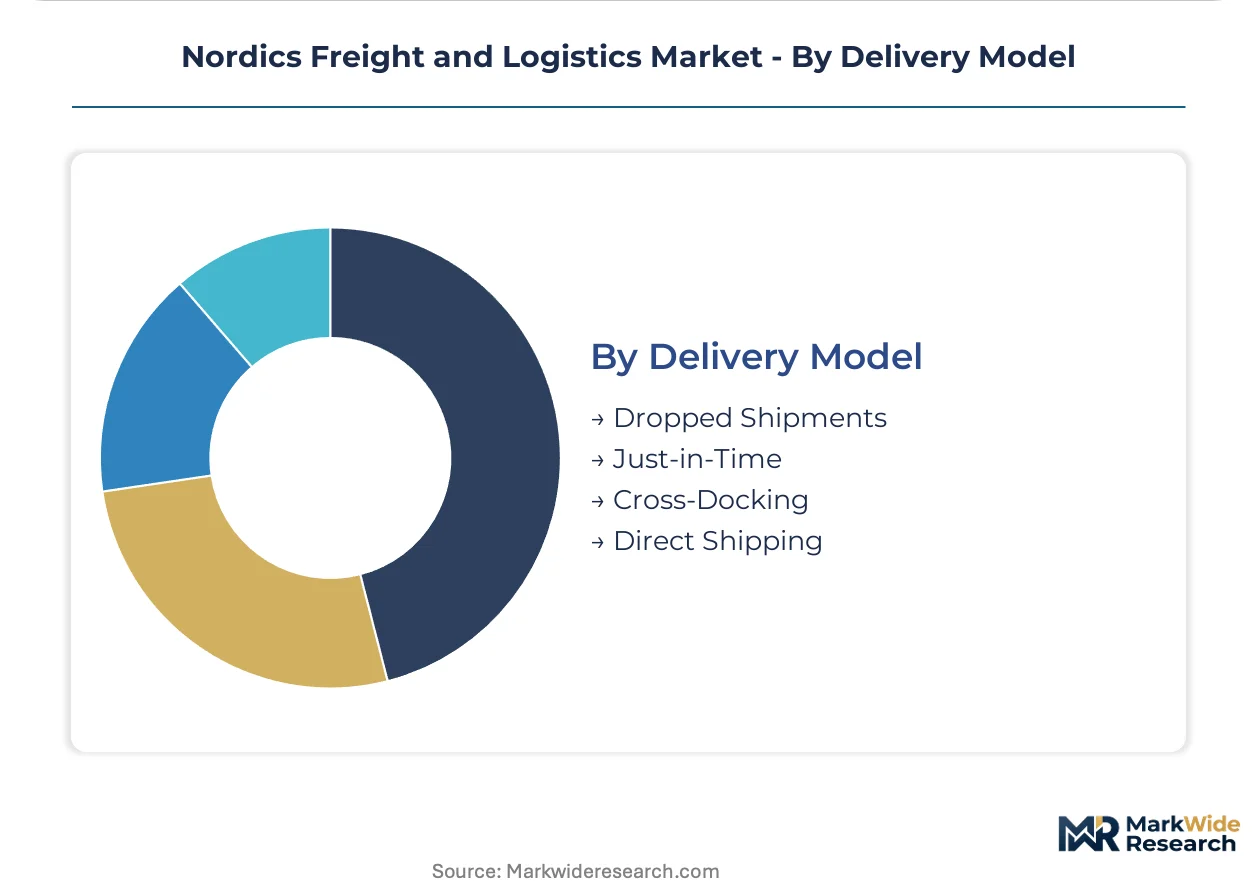
| Segmentation | Service Type: Road Freight, Air Cargo, Sea Freight, Rail Transport Customer Type: Retailers, Manufacturers, E-commerce, Distributors Technology: GPS Tracking, Warehouse Automation, Robotics, IoT Delivery Model: Dropped Shipments, Just-in-Time, Cross-Docking, Direct Shipping |
| Companies Covered | PostNord Sverige AB, NTG Nordic Transport Group, DSV A/S, CEVA Logistics, DB Schenker, A.P. Moller - Maersk, Kuehne+Nagel, Greencarrier, DHL Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordics Freight and Logistics Market Evolving Landscape
Digital freight matching platforms are compressing spot-market transaction cycles across Scandinavian road corridors, while port automation and predictive cargo monitoring reshape asset utilization benchmarks.
Blockchain-enabled bill-of-lading verification is decomposing traditional documentary trade finance structures in Baltic Sea container shipping. Danish and Swedish exporters are piloting paperless transfer systems through Copenhagen-Malmö port clusters. This distributed-ledger infrastructure is compressing settlement timelines from days to hours, reducing working capital requirements for mid-sized freight forwarders.
Norwegian authorities mandate shore-power connectivity at all state-owned terminals by 2026, accelerating terminal electrification investments. This framework forces vessel operators to retrofit shore-connection systems or face berth restrictions. Pharmaceutical and seafood cold-chain exporters using Oslo and Tromsø harbors are prioritizing compliant carriers to avoid demurrage penalties.
Shippers are consolidating vendor relationships around integrated logistics providers offering end-to-end carbon accounting. Swedish retail and industrial buyers now require Scope 3 emissions disclosure from road and sea carriers, displacing fragmented spot-market purchasing. This concentration trend is most visible in Gothenburg-to-Stockholm manufacturing supply chains, where annual contracting has replaced quarterly tendering.
Nordics Freight and Logistics Market Segmentation
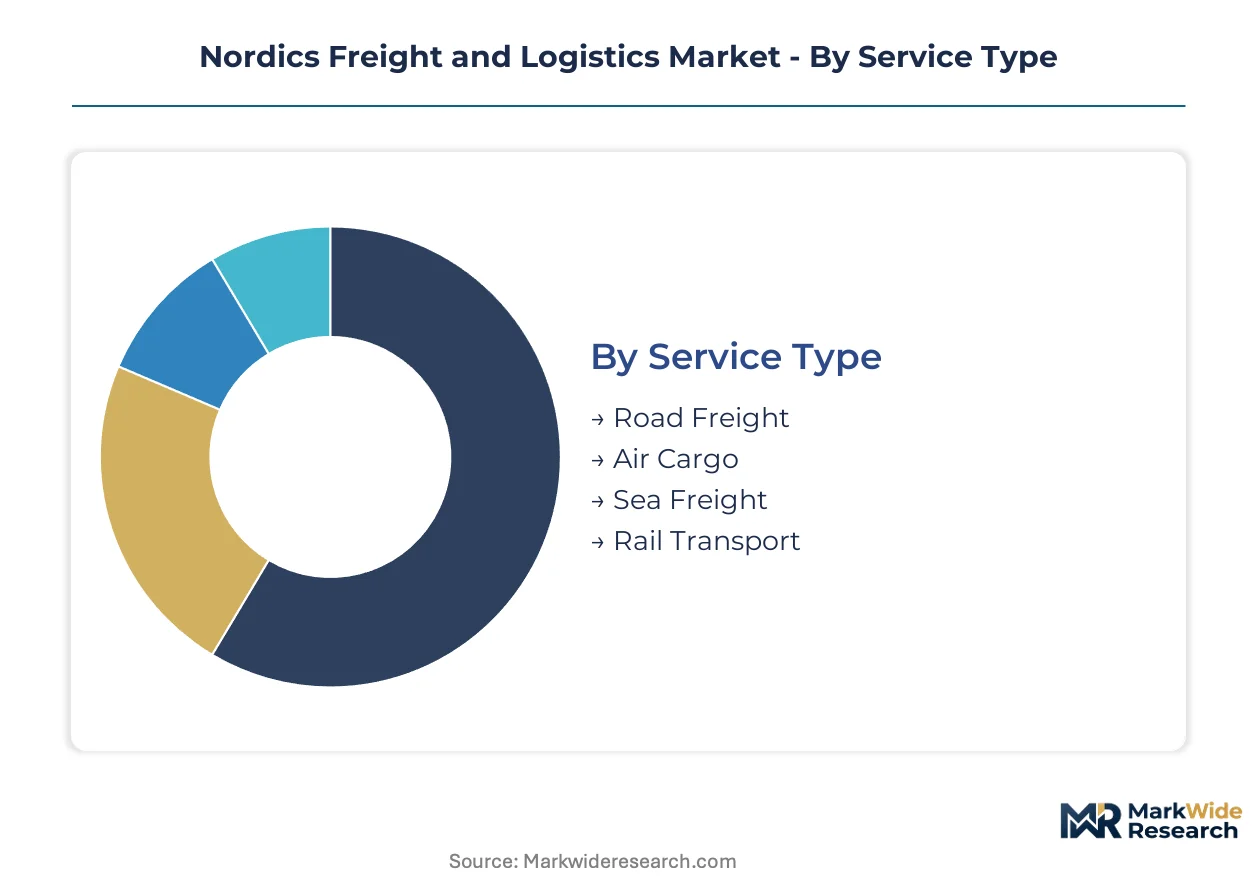
Nordic freight corridors exhibit divergent cost structures across transport modes and customer segments. Service differentiation increasingly hinges on carbon-accounting capabilities and digital integration depth rather than pure speed or price.
Service Type:
Road Freight faces substitution pressure from rail electrification on intra-Scandinavian corridors, while Sea Freight confronts modal competition from short-sea shipping optimization.
- Road Freight:Diesel and battery-electric heavy-duty vehicles move palletized and bulk cargo across the E4, E6, and E18 motorway networks. Swedish carbon-emission standards are compressing fleet procurement timelines for Copenhagen-Oslo and Stockholm-Gothenburg lanes.
- Sea Freight:Containerized and breakbulk movements traverse Baltic and North Atlantic routes via roll-on/roll-off and lift-on/lift-off vessels. Norwegian pharmaceutical cold-chain exporters prioritize compliant carriers serving Oslo and Bergen terminals to avoid demurrage penalties from shore-power mandates.
- Air Cargo:Temperature-sensitive and high-value shipments move through Copenhagen, Stockholm-Arlanda, and Oslo-Gardermoen hubs.
- Rail Transport:Intermodal block trains connect continental Europe to Nordic distribution centers via Malmö and Trelleborg gateways.
Road Freight anchors the volume base while Warehouse Automation gains share at the steepest rate.
Customer Type:
Procurement patterns diverge sharply between contract-logistics relationships and spot-market purchasing, with E-commerce platforms driving the most volatile capacity absorption.
- E-commerce:Direct-to-consumer fulfillment networks require same-day and next-day last-mile density across Danish, Swedish, and Norwegian urban corridors. Norwegian pharmaceutical distributors are expanding temperature-controlled capacity to serve remote coastal communities.
- Retailers:Big-box and grocery chains operate consolidated distribution centers with fixed-route replenishment schedules. Swedish retail buyers now require Scope 3 emissions disclosure from road and sea carriers, displacing fragmented spot-market purchasing in Gothenburg-to-Stockholm supply chains.
- Manufacturers:Industrial shippers manage inbound raw material flows and outbound finished goods distribution through integrated logistics providers.
- Distributors:Third-party logistics operators aggregate fragmented shipper demand across multiple trade lanes.
Retailers dominate contract value while E-commerce expands most quickly.
Technology:
Capital deployment concentrates on automation assets that reduce labor dependency, with GPS Tracking facing margin compression as commoditized fleet management tools.
- Warehouse Automation:Automated storage and retrieval systems, conveyor networks, and sortation equipment reduce fulfillment labor hours. Danish and Swedish robotics suppliers require costly middleware to connect with incumbent ERP platforms, creating integration friction for legacy operators.
- IoT:Sensor-enabled cargo monitoring tracks temperature, humidity, shock, and location across multimodal handoffs. Pharmaceutical and seafood cold-chain exporters using Oslo and Tromsø harbors prioritize IoT-compliant carriers to maintain chain-of-custody documentation.
- GPS Tracking:Real-time vehicle and container location systems provide fleet visibility and estimated-time-of-arrival updates.
- Robotics:Autonomous mobile robots and articulated arms handle picking, packing, and palletizing tasks in distribution centers.
Warehouse Automation captures the largest capital allocation while IoT climbs the fastest.
Delivery Model:
Inventory positioning strategies reflect working capital constraints, with Just-in-Time models facing renewed scrutiny after supply chain volatility.
- Just-in-Time:Synchronized inbound logistics minimize warehouse holding costs through precise arrival scheduling. Post-Brexit documentation complexity for UK-Nordic freight is forcing operators to maintain redundant inventory positioning alongside dual compliance teams.
- Cross-Docking:Direct freight transfer between inbound and outbound vehicles eliminates intermediate storage. Swedish Transport Agency permissions for driver-assist convoys on E4 motorway segments are opening regulatory space for cross-dock synchronization experiments.
- Dropped Shipments:Pre-staged trailer containers enable rapid tractor coupling and departure.
- Direct Shipping:Point-to-point movements bypass intermediate consolidation for high-priority or oversized cargo.
Just-in-Time retains the deepest operational footprint while Cross-Docking gains traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Denmark exhibit the highest price elasticity for standard freight services, while Norwegian pharmaceutical cold-chain corridors command premium tolerance due to regulatory stringency and remote delivery complexity.
Sweden
Swedish carbon-emission standards for heavy-duty vehicles are compressing fleet procurement timelines across Stockholm-Gothenburg and Copenhagen-Oslo lanes. The Swedish Transport Agency permits driver-assist convoy pilots on E4 motorway segments, opening regulatory space for autonomous platooning validation. Gothenburg anchors manufacturing supply chains where annual contracting has displaced quarterly tendering.
Norway
Pharmaceutical distributors are expanding temperature-controlled last-mile capacity to serve remote coastal communities. Norwegian port authorities mandate shore-power connectivity at state-owned terminals by 2026, forcing vessel retrofits or berth restrictions. Oslo and Bergen corridors concentrate cold-chain infrastructure investments as seafood and pharmaceutical exporters prioritize compliant carriers.
Denmark
Danish maritime authorities coordinate with EU Green Deal vessel-fuel protocols, tightening berth access for non-compliant operators at Copenhagen and Aarhus terminals. E-commerce fulfillment networks absorb volatile capacity across Danish urban corridors. Copenhagen-Malmö port clusters pilot blockchain-enabled bill-of-lading verification, compressing settlement timelines.
Finland
Eastern logistics corridors are pivoting toward Baltic Sea shipping via Tallinn and Riga, creating demand for multimodal transshipment hubs in southern Finland. Battery-electric truck acquisition costs run 2.5-3x above diesel equivalents, compressing margins for small fleet operators in rural areas. Helsinki anchors distribution networks serving reconfigured trade flows.
Nordics Freight and Logistics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Nordic freight corridors. Asset-heavy operators sustain density through integrated road-sea networks, while asset-light specialists capture margin pools in project-cargo and cold-chain verticals. Three archetypes dominate: integrated multimodal providers, domestic last-mile anchors, and renewable-energy logistics specialists. Competitive moves concentrate on fleet electrification partnerships and warehouse automation integration.
Among integrated providers, DSV A/S occupies a position exemplifying cross-border density maintenance, while PostNord Sverige AB represents the domestic infrastructure anchor archetype. NTG Nordic Transport Group sits within the specialized project-cargo tier, serving offshore wind construction corridors. These three patterns illustrate how capital-intensity divergence bifurcates competitive dynamics across the region.
| Leading Market Players |
|---|
| PostNord Sverige AB |
| NTG Nordic Transport Group |
| DSV A/S |
| CEVA Logistics |
| DB Schenker |
| A.P. Moller - Maersk |
| Kuehne+Nagel |
| Greencarrier |
| DHL Group |
| Others |
Value Network & Pricing Analysis
Battery-electric truck platforms replacing diesel fleets across Swedish procurement corridors simultaneously redraw terminal infrastructure geography and compress total-cost-of-ownership economics for heavy-haul operators. This substitution dynamic concentrates pricing power with integrated providers controlling electrified depot networks while fragmenting spot-market rate-setting authority among asset-light brokers.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value capture for fleet operators navigating electrification transitions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by carbon-accounting disclosure requirements and route complexity. Cost compression in the economy tier is intensifying because small Finnish and rural Swedish operators face 2.5-3x acquisition premiums for battery-electric platforms. Retailers with Scope 3 mandates exhibit lowest price sensitivity; spot-market shippers on Baltic corridors show highest elasticity.
Supply Chain Analysis
Sweden and Denmark anchor warehouse automation equipment manufacturing, while Norway concentrates specialized cold-chain infrastructure deployment. Battery cell production draws from South Korean and Chinese suppliers, hydrogen fuel-cell stacks rest on German and Japanese sources, and shore-power terminal components feed from Danish maritime technology providers. Single-source vulnerability sits with fuel-cell maintenance networks concentrated around Stockholm, Copenhagen, and Oslo. Distribution runs through multimodal transshipment hubs at Malmö, Trelleborg, and southern Finnish ports reconfigured for Baltic Sea routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nordic freight logistics fragments across carbon-accounting capability tiers, with E-commerce fulfillment networks and pharmaceutical cold-chain corridors creating defendable niches for specialized operators.
For Market Incumbents: Fortify density positions on electrified corridor segments through backward integration into charging depot infrastructure. Secure fleet electrification partnerships with Swedish and Norwegian regulators enforcing 2026 shore-power mandates. Prioritize middleware development connecting warehouse automation systems to incumbent ERP platforms, defending against robotics supplier disintermediation. For New Entrants and Emerging Players: Differentiate on autonomous platooning technology validation, targeting Swedish Transport Agency-permitted E4 motorway segments for pilot deployment. Capture white-space in Finnish multimodal transshipment hub development as eastern corridors pivot toward Baltic Sea shipping. Pursue green ammonia bunkering infrastructure partnerships with Norwegian port authorities at Stavanger and Haugesund. For Investors and Strategic Acquirers: Capital is best deployed toward integrated multimodal providers with electrified fleet density and carbon-accounting disclosure capabilities. Long-term viability favors operators controlling both road-sea network nodes and warehouse automation integration layers. Monitor Swedish carbon-border adjustment implementation as inflection indicator for cross-border haulage economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Swedish carbon-emission standards compress procurement timelines for battery-electric platforms. |
| Shore-Power Terminal Retrofit | Norwegian port mandates force vessel operator compliance investments by 2026. |
| Warehouse Automation Integration | Danish and Swedish robotics suppliers require middleware connecting legacy ERP systems. |
| Autonomous Platooning Pilot | Swedish Transport Agency permissions on E4 segments validate technology before Nordic rollout. |
| Multimodal Transshipment Hub Development | Finnish eastern corridor reconfiguration toward Baltic Sea shipping creates hub demand. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, terminal infrastructure managers, pharmaceutical logistics coordinators, and E-commerce fulfillment planners and refined through secondary validation against customs trade records, EU Green Deal implementation documents, Swedish Transport Agency regulatory filings, and Baltic Sea shipping manifests. Bottom-up volume modeling triangulated with top-down macroeconomic indicators across the Nordic region.
Variance decomposition across service type, customer segment, technology deployment, and delivery model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory synthesis. Mode substitution elasticities, electrification capex curves, and carbon-border adjustment implementation timelines served as freight-specific forecast inputs.
Material uncertainties — regulatory acceleration or delay in Swedish and Norwegian emission standards, battery-electric platform cost curves, and Baltic Sea route reconfiguration pace — sit outside the modeled envelope. Forecasts reflect assumptions about infrastructure buildout continuity and technology adoption S-curves. Recalibration cycles align with material shifts in fleet procurement patterns and terminal electrification investment flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Less-Than-Truckload Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
India Cold Chain Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market