
 Taiwan Discrete Semiconductor Market | 2026-2036
Taiwan Discrete Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Discrete Semiconductor Market Insights
Software-defined power management is decoupling hardware sales from long-term revenue streams in the Taiwan Discrete Semiconductor Market. Infineon Technologies AG leverages its SiC module portfolio to anchor premium positioning in automotive traction inverters. Taiwan Semiconductor Co., Ltd. sustains foundry-scale advantages across discrete device wafer fabrication. ASE Technology Holding Co., Ltd. dominates outsourced assembly and test capacity for power discretes serving Greater China.
Discrete semiconductors are non-integrated circuit electronic components—diodes, transistors, thyristors, and rectifiers—fabricated on silicon, silicon carbide, gallium nitride, or gallium arsenide substrates, typically handling voltage ratings from tens to thousands of volts and current levels from milliamps to hundreds of amperes. These components switch, regulate, or rectify electrical energy in power electronics and signal conditioning circuits. Transistors and silicon carbide technology command expanding margin pools as EV inverters and renewable energy inverters drive specification upgrades. Diodes and silicon-based devices retain volume leadership in consumer power adapters and industrial motor drives, though price compression limits profit expansion in those tiers.
Taiwan's Bureau of Standards, Metrology and Inspection and the Ministry of Economic Affairs enforce energy-efficiency labeling and industrial safety standards that mandate higher-performance discrete components in power supplies and motor systems. The International Electrotechnical Commission and ISO 9001 quality frameworks shape export qualification requirements for Taiwan-based manufacturers shipping into Europe and North America. Stakeholders must monitor gallium nitride qualification timelines against silicon carbide cost curves to determine technology commitment sequencing.
Market Dynamics
Silicon carbide substrate qualification timelines are compressing procurement cycles across Taiwan's power electronics supply chain, forcing discrete semiconductor vendors to accelerate device validation or surrender socket positions to earlier movers.
Growth Catalysts
- EV Powertrain Electrification:Automotive OEMs in Taiwan's manufacturing corridor are specifying 650V-1200V SiC MOSFETs for traction inverters, pulling discrete device demand from traditional silicon IGBT sockets.
- BSMI Energy-Labeling Enforcement:Taiwan's Bureau of Standards, Metrology and Inspection mandates higher-efficiency power supplies in consumer electronics, requiring upgraded rectifiers and switching transistors across adapter production lines.
- Hsinchu Science Park Cluster Density:Integrated device manufacturing concentration enables foundry-to-OSAT handoff efficiencies that shorten power discrete time-to-market by 15-20% versus dispersed supply chains.
Market Restraints
- Silicon Carbide Wafer Supply Concentration:Six-inch SiC substrate supply concentrates among three non-Taiwanese ingot growers, exposing local device fabricators to allocation rationing during demand surges.
- Copper and Epoxy Resin Input Volatility:Leadframe and molding compound materials experience 12-18% price swings that compress assembly margins at ASE Technology and smaller OSAT competitors.
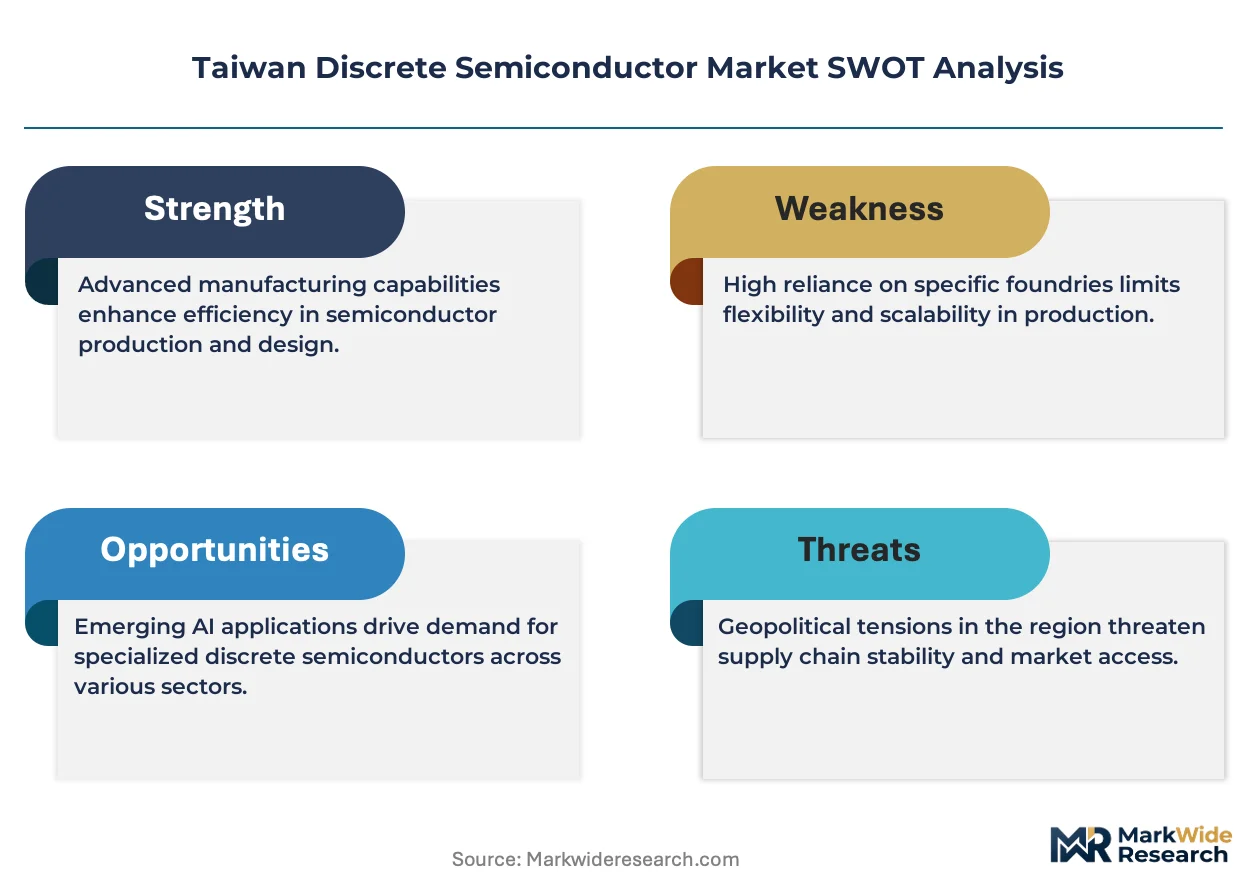
- Gallium Nitride Substitution Threat:GaN-on-silicon devices below 650V threaten silicon MOSFET and super-junction MOSFET sockets in sub-3kW power supplies, forcing silicon vendors into defensive pricing.
Strategic Opportunities
- Underpenetrated Industrial Motor Drives:Variable frequency drive retrofits across Taiwan's machine tool sector remain below 35% penetration, representing untapped demand for insulated-gate bipolar transistors and fast-recovery diodes.
- Renewable Energy Inverter Localization:Taiwan's offshore wind buildout requires domestic sourcing commitments for power conversion equipment, opening discrete semiconductor qualification pathways for local vendors.
- GaN-SiC Hybrid Module Convergence:Multi-chip modules combining GaN HEMTs for high-frequency switching with SiC diodes for rectification enable new performance tiers in data center power supplies.
Industry Challenges
- Compound Semiconductor Process Talent Scarcity:Taiwan's university pipeline produces fewer than 200 annual graduates with SiC/GaN epitaxy and device physics expertise, forcing foundries to poach from limited talent pools.
- AEC-Q101 Automotive Qualification Timelines:Discrete power devices require 12-18 month validation cycles for automotive grade certification, delaying revenue recognition from design wins.
- Legacy Silicon Capacity Stranding:8-inch silicon power MOSFET fabs face utilization pressure as customers migrate to 12-inch platforms or compound semiconductors, complicating depreciation recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Discrete Semiconductor Market |
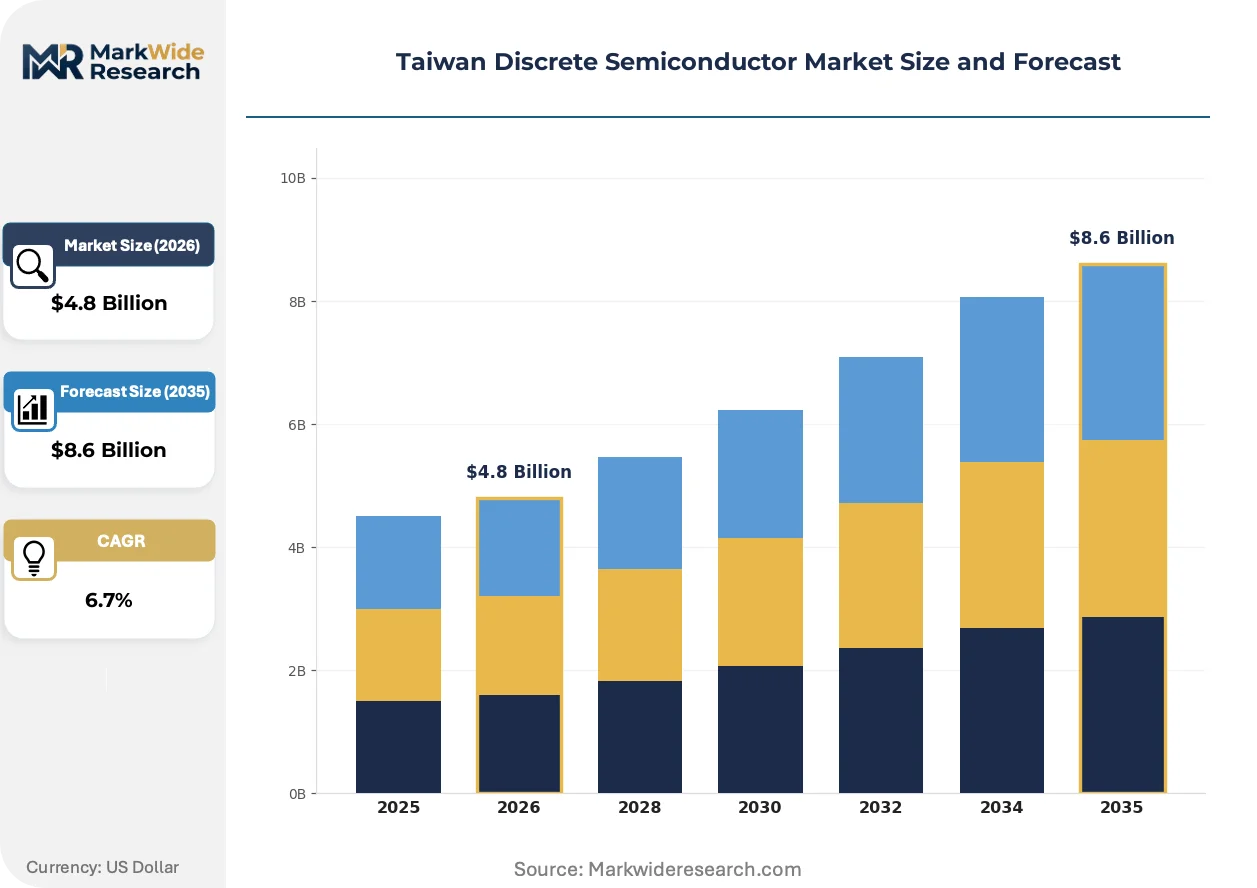
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Rectifiers End User: Consumer Electronics, Automotive Components, Industrial Equipment, Telecommunications Technology: Silicon, Gallium Nitride, Silicon Carbide, Gallium Arsenide Application: Power Management, Signal Processing, Motor Control, Lighting Solutions |
| Companies Covered | Taiwan Semiconductor Co., Ltd., Infineon Technologies AG, NXP Semiconductors NV, Eaton Corporation PLC, ABB Ltd, United Microelectronics Corporation, ASE Technology Holding Co., Ltd., LITE-ON Technology Corporation, STMicroelectronics NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Discrete Semiconductor Market Trends and Innovations
Device architecture evolution and regulatory pressure on energy efficiency are converging to redefine competitive positioning in Taiwan's discrete semiconductor landscape, with material transitions outpacing traditional silicon roadmap extensions.
Silicon carbide MOSFET technology handles voltage ratings from 650V to 1700V with switching losses 70% below comparable silicon IGBTs. Taiwan-based automotive tier-one suppliers are adopting SiC modules for 800V EV architectures at triple-digit annual growth rates. This performance advantage is integrating premium pricing into inverter bill-of-materials, compressing silicon device margins in traction applications above 400V.
Taiwan's Bureau of Standards, Metrology and Inspection revised energy-labeling rules for external power supplies effective 2024, mandating active-mode efficiency above 89% at 50% load. Industrial consequence forces adapter manufacturers to abandon legacy Schottky diodes for synchronous rectification MOSFETs. Consumer electronics OEMs sourcing from Taiwan are responding by qualifying super-junction MOSFETs and GaN-based solutions in 65W-140W adapter segments.
Power discrete procurement is consolidating toward direct foundry relationships as module assemblers bypass traditional distribution channels for high-volume automotive and renewable energy contracts. Digi-Key and local distributors are losing socket access in 10,000-unit-plus annual programs. This channel compression is most visible in Hsinchu and Tainan Science Park corridors where IDMs and OSATs operate adjacent facilities enabling just-in-time wafer bank management.
Taiwan Discrete Semiconductor Market Segmentation
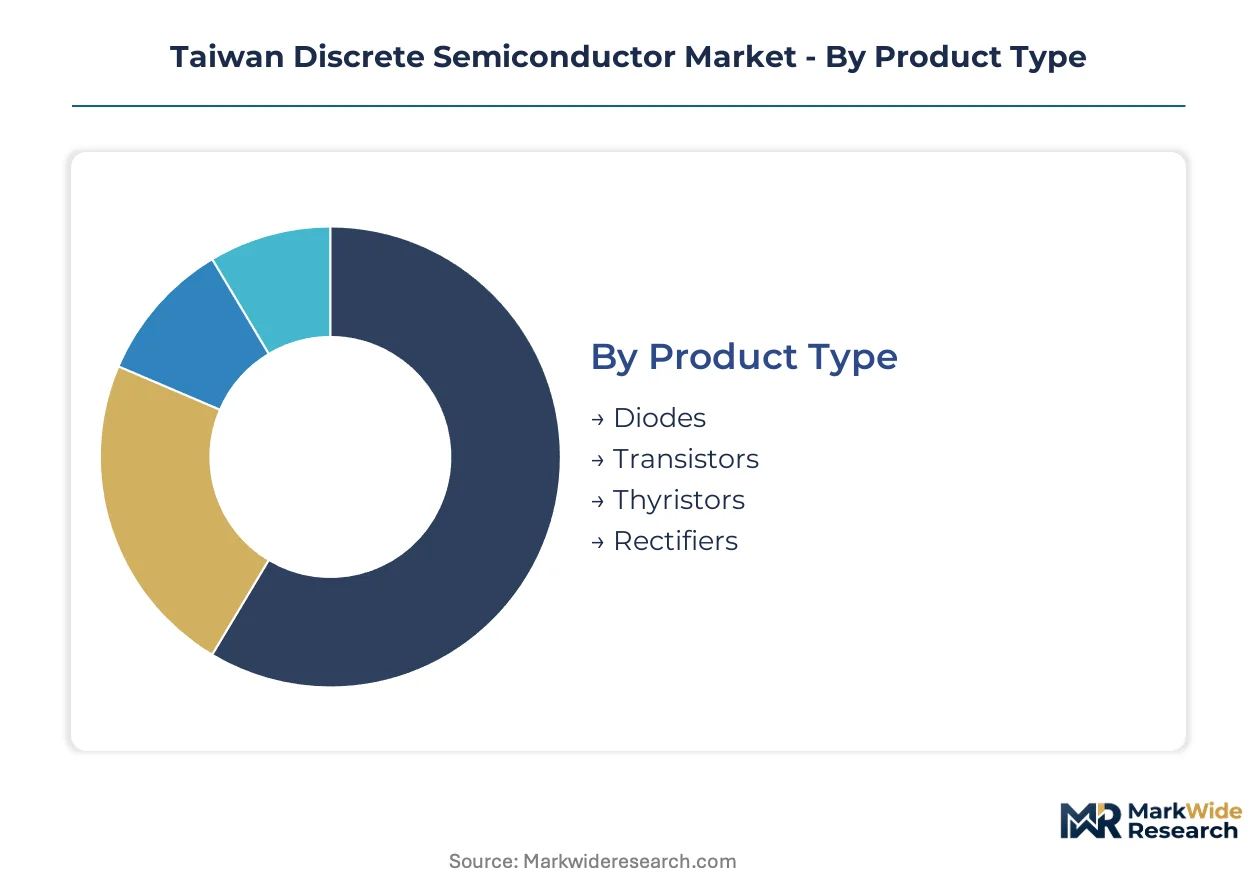
Discrete semiconductor segmentation in Taiwan tracks material transitions and end-use electrification with unusual precision. Foundry capacity allocation and OSAT scheduling decisions flow directly from how demand splits across these four dimensions.
Product Type:
Supply concentration in Hsinchu Science Park's integrated device manufacturing cluster shapes procurement patterns for each product family differently.
- Transistors:Silicon carbide MOSFETs and IGBTs handle switching frequencies above 50kHz with breakdown voltages spanning 600V to 1700V. Hsinchu-based automotive tier-one suppliers are absorbing the bulk of 1200V SiC MOSFET output for 800V EV traction inverters.
- Diodes:Fast-recovery and Schottky variants fabricated on silicon or silicon carbide substrates rectify AC-to-DC conversion with reverse recovery times below 50 nanoseconds. Taiwan's adapter manufacturers under BSMI energy-labeling mandates are shifting from legacy silicon to synchronous rectification MOSFETs in 65W-140W consumer power supplies.
- Thyristors:Phase-control devices for industrial motor drives and soft-start applications above 1kV, produced primarily at legacy 6-inch silicon fabs in Tainan.
- Rectifiers:Bridge and single-device configurations for power supply input stages, with automotive-grade variants requiring AEC-Q101 qualification cycles that extend lead times.
Transistors absorb the bulk of installed capacity; diodes are expanding most quickly as synchronous rectification displaces Schottky devices.
End User:
Margin tiering across end-use segments reflects certification burden and volume scale rather than technology complexity alone.
- Automotive Components:Traction inverters, onboard chargers, and DC-DC converters specify AEC-Q101 qualified devices with junction temperatures rated to 175°C. Taiwan-based EV powertrain assemblers are pulling 650V-1200V SiC devices from local foundries at annual growth rates exceeding triple digits.
- Industrial Equipment:Variable frequency drives and servo systems demand IGBTs and fast-recovery diodes with 1200V-1700V blocking capability. The machine tool sector around Taichung remains below 35% penetration for drive retrofits, leaving substantial socket opportunity.
- Consumer Electronics:External power adapters and chargers below 140W specify super-junction MOSFETs or GaN HEMTs to meet BSMI efficiency thresholds. Adapter OEMs in Taipei and Taoyuan are consolidating procurement toward direct foundry relationships.
- Telecommunications:Base station power supplies and server rack rectifiers require high-reliability devices with 100,000-hour MTBF ratings, sourced through qualified vendor lists managed by domestic network equipment manufacturers.
Automotive Components command premium pricing; Industrial Equipment offers the steepest expansion trajectory as motor drive retrofits accelerate.
Technology:
Wafer supply geography and epitaxy capability availability determine which substrate technologies can scale within Taiwan's manufacturing corridor.
- Silicon Carbide:4H-SiC epitaxy on 6-inch substrates enables MOSFETs with specific on-resistance below 3mΩ·cm². Device fabricators in Hsinchu face allocation pressure from non-Taiwanese ingot growers controlling substrate supply.
- Gallium Nitride:GaN-on-silicon HEMTs switch above 1MHz with figures-of-merit surpassing silicon super-junction devices below 650V. Adapter manufacturers are qualifying GaN solutions for sub-3kW power supplies.
- Silicon:Trench-gate and super-junction MOSFETs on 8-inch and 12-inch wafers retain cost advantage in consumer and industrial applications below 600V. Legacy 8-inch power MOSFET fabs face utilization pressure from customer migration.
- Gallium Arsenide:Schottky diodes and RF power transistors for specialized telecommunications and defense applications, produced at limited scale by specialized compound semiconductor foundries.
Silicon retains volume leadership; Silicon Carbide is climbing the fastest as EV powertrain electrification accelerates.
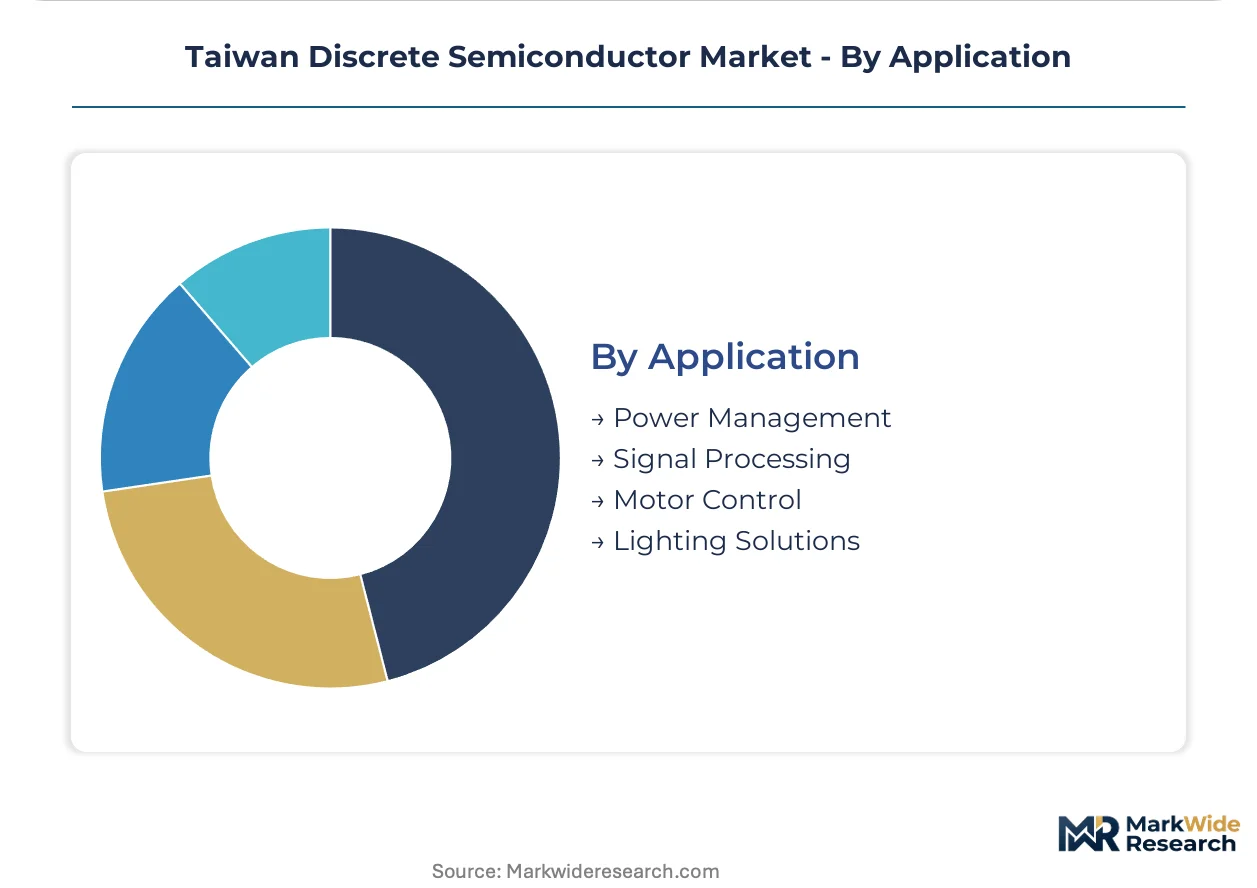
Application:
Customer type fragmentation—automotive tier-ones versus adapter OEMs versus industrial system houses—drives divergent specification and procurement behaviors.
- Power Management:AC-DC conversion, DC-DC regulation, and battery charging circuits across all end-use segments. BSMI energy-labeling enforcement is forcing synchronous rectification adoption in external adapters.
- Motor Control:Variable frequency drives, servo amplifiers, and EV traction inverters requiring high-current switching devices. Taiwan's machine tool sector and emerging EV supply chain represent dual demand anchors.
- Signal Processing:RF amplification and switching in telecommunications infrastructure, primarily served by GaAs and silicon LDMOS devices.
- Lighting Solutions:LED driver ICs and discrete ballast components for solid-state lighting, a mature segment with limited growth but stable replacement demand.
Power Management absorbs the bulk of unit volume; Motor Control is gaining share fastest as industrial electrification and EV adoption converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan manufactures discrete semiconductors at scale exceeding domestic absorption, with Hsinchu Science Park fabs supplying automotive and industrial demand across East Asia while local EV and renewable energy projects pull premium SiC devices from the same production base.
Hsinchu Science Park
Integrated device manufacturing concentration here anchors Taiwan's silicon carbide MOSFET output for 800V EV traction inverters. The National Science and Technology Council coordinates foundry-to-OSAT handoff efficiencies that shorten power discrete time-to-market. ASE Technology and Taiwan Semiconductor Co., Ltd. operate adjacent facilities enabling just-in-time wafer bank management for automotive tier-one suppliers.
Tainan Science Park
Legacy 6-inch silicon fabs here produce thyristors and rectifiers for industrial motor drives below 35% retrofit penetration. The Southern Taiwan Science Park Administration incentivizes compound semiconductor expansion through land and utility concessions. Local machine tool manufacturers around Taichung source IGBTs and fast-recovery diodes from this cluster for variable frequency drive retrofits.
Taoyuan Metro
Consumer electronics adapter OEMs here consolidate procurement toward direct foundry relationships under BSMI energy-labeling mandates. The Ministry of Economic Affairs enforces active-mode efficiency thresholds above 89% at 50% load for external power supplies. Super-junction MOSFET and GaN HEMT qualification activity concentrates among Taipei and Taoyuan manufacturers serving 65W-140W segments.
Kaohsiung Harbor Zone
Offshore wind power conversion equipment sourcing commitments here open discrete semiconductor qualification pathways for local vendors. The Bureau of Standards, Metrology and Inspection certifies power electronics for grid connection under renewable energy regulations. Domestic inverter manufacturers cluster near port logistics for turbine component import and power module export.
Taiwan Discrete Semiconductor Market Competitive Landscape
Top-tier vendors anchor premium SiC and GaN device tiers, while mid-scale fabricators compete on silicon super-junction and IGBT volumes. The vendor base stratifies across three archetypes: integrated device manufacturers with captive foundry capacity, fabless specialists relying on Taiwan-based wafer fabrication, and outsourced assembly and test providers capturing packaging value. Capacity expansion and direct foundry relationships constitute the dominant competitive moves as module assemblers bypass traditional distribution channels.
Among Germany-based semiconductor conglomerates, Infineon Technologies AG exemplifies the integrated device manufacturer archetype with SiC module portfolios anchoring automotive traction positioning. Taiwan Semiconductor Co., Ltd. and ASE Technology Holding Co., Ltd. represent the foundry-scale and OSAT-scale vectors respectively, with the former sustaining wafer fabrication advantages and the latter dominating outsourced assembly and test capacity for power discretes serving Greater China.
| Leading Market Players |
|---|
| Taiwan Semiconductor Co., Ltd. |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Eaton Corporation PLC |
| ABB Ltd |
| United Microelectronics Corporation |
| ASE Technology Holding Co., Ltd. |
| LITE-ON Technology Corporation |
| STMicroelectronics NV |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale IDMs with captive silicon carbide epitaxy capacity exercise asymmetric pricing power over fabless competitors, compressing margins at ASE Technology and smaller OSATs while insulating their own module assembly operations from raw material volatility. Taiwan's Bureau of Standards, Metrology and Inspection energy-labeling enforcement funnels adapter procurement toward direct foundry relationships, bypassing distribution markups and flattening tiered pricing structures across Hsinchu and Taoyuan manufacturing corridors.
Pricing Analysis
Margin tightening in silicon-based power MOSFETs traces to gallium nitride substitution below 650V and customer migration toward 12-inch platforms. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates AEC-Q101 qualified devices from commercial-temperature variants. Cost compression accelerates in legacy 8-inch silicon fabs as utilization pressure forces defensive pricing against compound semiconductor alternatives. Consumer electronics OEMs sourcing 65W-140W adapters exhibit highest price sensitivity; automotive tier-ones prioritize junction temperature ratings and qualification pedigree over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs force discrete semiconductor buyers to qualify second-source SiC substrate suppliers beyond the three dominant non-Taiwanese ingot growers. Geographic supply concentration centers on Taiwan for wafer fabrication and outsourced assembly, South Korea for silicon carbide epitaxy equipment, and Japan for high-purity copper leadframe materials. Raw material dependencies draw from copper and epoxy resin for packaging, 6-inch SiC substrates for power devices, and gallium nitride-on-silicon wafers for adapter applications. Single-source vulnerability in SiC ingot supply exposes local device fabricators to allocation rationing during demand surges. Distribution runs through direct foundry relationships for high-volume automotive and renewable energy contracts, with traditional distributors retaining socket access only in sub-10,000 unit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's discrete semiconductor market sits in a material-transition phase where silicon carbide MOSFETs displace silicon IGBTs in traction inverters above 400V, while gallium nitride encroaches on sub-3kW power supplies. Stakeholders must position against this technology substitution timeline rather than legacy roadmap extensions.
For Market Incumbents: Extend AEC-Q101 qualification pipelines to capture 800V EV architecture sockets before second-source competitors complete validation cycles. Deepen backward integration into SiC epitaxy capacity or secure long-term substrate offtake agreements to defend against allocation rationing from non-Taiwanese ingot growers. Prioritize foundry-to-OSAT co-location in Hsinchu Science Park to preserve the 15-20% time-to-market advantage over dispersed supply chains. For New Entrants and Emerging Players: Capture underpenetrated industrial motor drive retrofits across Taichung's machine tool sector, where variable frequency drive adoption remains below 35% and incumbent qualification cycles have stalled. Target synchronous rectification MOSFET sockets in 65W-140W consumer adapters under BSMI energy-labeling mandates, where super-junction and GaN alternatives create procurement flexibility for new suppliers. Pursue direct OEM qualification pathways rather than distribution channel penetration to bypass entrenched supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor legacy 6-inch silicon fab operators in Tainan with thyristor and rectifier specialization, where depreciation pressure and customer migration create acquisition multiples below replacement cost. Compound semiconductor process talent scarcity and AEC-Q101 validation timelines compress revenue recognition windows, favoring patient capital with 5-10 year holding periods. Monitor gallium nitride qualification velocity against silicon carbide cost curves as the inflection signal for technology commitment sequencing across the portfolio.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Epitaxy Capacity Expansion | Captures substrate allocation priority from non-Taiwanese ingot growers for automotive traction inverters. |
| AEC-Q101 Automotive Qualification Investment | Opens 800V EV powertrain sockets with 175°C junction temperature ratings and 12-18 month validation cycles. |
| GaN-on-Silicon Adapter Qualification | Addresses BSMI energy-labeling mandates above 89% active-mode efficiency at 50% load in 65W-140W segments. |
| Direct Foundry Relationship Consolidation | Bypasses distribution markups for 10,000-unit-plus automotive and renewable energy procurement programs. |
| Compound Semiconductor Talent Acquisition | Offsets university pipeline output below 200 annual SiC/GaN epitaxy and device physics graduates. |
Research Methodology
Document review covered Taiwan Bureau of Standards, Metrology and Inspection regulatory filings, IEC and ISO 9001 quality framework documentation, and customs trade data for power discrete imports, complemented by interviews with foundry operations executives, automotive tier-one procurement managers, OSAT technical directors, and adapter OEM supply chain leads. Secondary validation drew from Ministry of Economic Affairs energy-efficiency disclosures, National Science and Technology Council cluster development reports, and SEC filings from publicly traded semiconductor firms. Bottom-up unit demand modeling and top-down value chain triangulation converged on segment-level estimates.
Segmentation outputs reflect product type, end user, technology substrate, and application dimensions modeled across the projection horizon, with geographic splits tracking Hsinchu Science Park, Tainan Science Park, Taoyuan Metro, and Kaohsiung Harbor Zone production clusters. CAGRs were derived from installed base replacement cycles, EV powertrain electrification trajectories, and renewable energy inverter localization commitments. Industry-specific forecast inputs incorporated SiC substrate qualification timelines, BSMI energy-labeling phase-in schedules, and AEC-Q101 validation pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gallium nitride cost-parity achievement, silicon carbide wafer supply expansion, and automotive OEM platform standardization decisions. Deviation in compound semiconductor process talent availability or substrate allocation rationing severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market