
 Europe Printed Circuit Board (PCB) Market | 2026-2036
Europe Printed Circuit Board (PCB) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Printed Circuit Board (PCB) Market Insights
High-density interconnect specification tiers is collapsing into mainstream automotive and telecom procurement as OEMs mandate finer line widths and via-in-pad architectures. AT&S Austria Technologie und Systemtechnik AG leverages its Leoben and Nanjing facilities to sustain European supply security for advanced substrates. Wurth Elektronik Group anchors prototype-to-volume continuity through its Niedernhall campus, while Schweizer Electronic AG differentiates via embedded-chip competency in Schramberg.
Europe Printed Circuit Board refers to a laminated structure of conductive copper traces etched onto insulating substrate layers, typically FR-4 glass-reinforced epoxy or polyimide for flex circuits, mechanically supporting and electrically connecting electronic components through soldered joints and plated through-holes. Its primary purpose is to provide signal routing, power distribution, and thermal management in electronic assemblies ranging from engine control modules to base station transceivers. Multi-layer configurations now dominate value creation as stack counts exceed twelve layers in automotive radar and server applications, while rigid-flex hybrids capture expanding share in aerospace and medical instrumentation where three-dimensional packaging constraints apply. FR-4 remains the volume substrate but faces margin compression as CEM-1 and halogen-free alternatives gain specification share under environmental compliance mandates.
REACH substance restrictions and RoHS directives enforced by ECHA shape material selection across European fabrication facilities, eliminating legacy flame retardants and restricting cadmium-bearing surface finishes. CE marking requirements under the EU AI Act and MDR extend traceability obligations to PCB assemblies in medical devices and autonomous systems. Stakeholders must monitor ETS carbon border adjustments and evolving F-Gas Regulation scopes that threaten fluorinated chemistry used in high-frequency laminates, while calibrating capacity investments against the CSRD reporting burden now filtering through Tier-1 EMS procurement criteria.
Market Dynamics
Automotive electrification is collapsing specification tiers across European PCB procurement as OEMs mandate finer line widths and via-in-pad architectures for radar modules and battery management systems. Tier-1 EMS providers in Germany and Austria now enforce unified HDI standards that previously differentiated premium from mid-range supply.
Growth Catalysts
- EU Green Deal substrate mandates:Halogen-free laminate specifications under REACH substance restrictions are accelerating material transitions across Czech and Slovak fabrication corridors. FR-4 with legacy flame retardants faces systematic phase-out.
- Automotive radar proliferation:Multi-layer stack counts exceeding twelve layers are now standard for advanced driver-assistance systems. German OEM procurement volumes for 77GHz sensor modules have tripled specification complexity.
- CE marking under EU AI Act:Traceability obligations for autonomous system PCBs are creating certified supplier preference tiers. EMS providers with documented supply chain governance capture disproportionate medical and mobility contracts.
Market Restraints
- Copper and resin input volatility:CME copper price swings above fifteen percent annually compress laminate fabricator margins. Smaller Austrian and French substrate producers lack hedging infrastructure to buffer raw material shocks.
- High-frequency laminate supply concentration:Fluorinated chemistry dependency for 5G base station substrates concentrates in Asian resin suppliers. European fabricators face ETS carbon border adjustment exposure on imported specialty laminates.
- CEM-1 technical ceiling:Lower-grade substrates cannot achieve thermal cycling reliability for automotive underhood applications. Specification lock-in to FR-4 and halogen-free alternatives delays cost-down trajectories in price-sensitive industrial segments.
Strategic Opportunities
- Embedded-chip substrate white space:Chip-embedding competency in Schramberg and surrounding Baden-Württemberg clusters addresses aerospace and medical miniaturization demands. European captive production of embedded dies reduces dependency on Asian OSAT capacity.
- CSRD procurement criteria filtering:Tier-1 EMS sustainability reporting under the Corporate Sustainability Reporting Directive creates preferential sourcing for facilities with verified carbon accounting. Early-compliant fabricators in Austria and Germany secure long-term supply agreements.
- Rigid-flex hybrid convergence:Three-dimensional packaging constraints in surgical robotics and drone avionics are expanding addressable market for polyimide-glass composite substrates. French medical device OEMs represent underpenetrated demand relative to German automotive concentration.
Industry Challenges
- Plasma etch and laser drill skill scarcity:Microvia formation below seventy-five micron diameter requires operators with compound semiconductor processing backgrounds. Eastern European technical universities lack curriculum alignment with HDI fabrication requirements.
- MDR certification timeline compression:Medical device PCB assemblies face extended conformity assessment under the EU Medical Device Regulation. Small-batch prototype shops in Bavaria and Baden-Württemberg struggle to amortize notified body audit costs across limited production runs.
- Legacy ERP integration with traceability systems:Shop-floor data capture for REACH substance documentation conflicts with decades-old MRP architectures at mid-tier German fabricators. Real-time material genealogy remains operationally fragmented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Printed Circuit Board (PCB) Market |
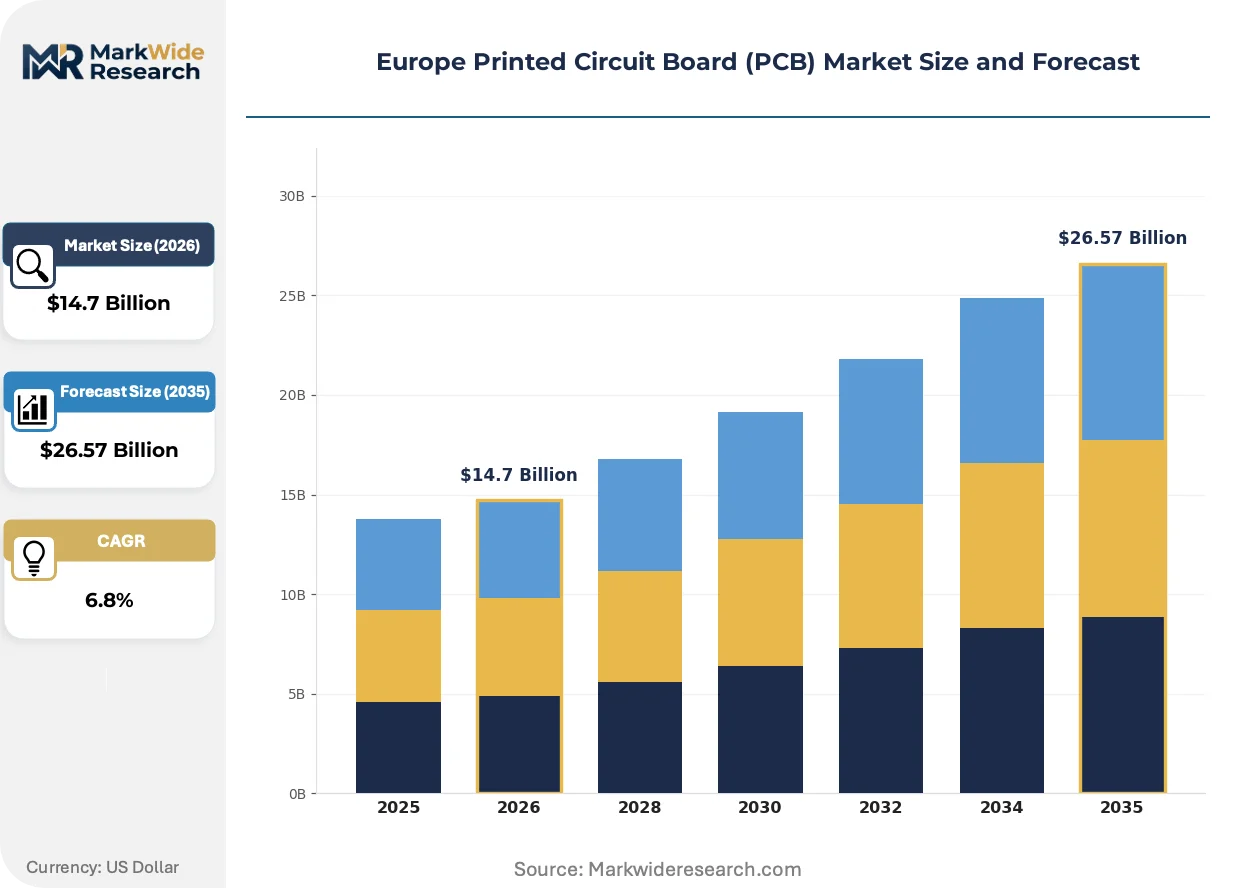
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Rigid Material: FR-4, CEM-1, Copper, Polyimide End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Manufacturing Stage: Design, Assembly, Testing, Fabrication |
| Companies Covered | AT&S Austria Technologie und Systemtechnik AG, Wurth Elektronik Group, KSG GmbH, NCAB Group, Schweizer Electronic AG, Aspocomp Group, ICAPE Group, Elvia PCB Group, Eurocircuits, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Printed Circuit Board (PCB) Market Trends and Innovations
Specification convergence across automotive and telecom procurement is compressing technology lifecycles and forcing substrate fabricators to serve dual qualification regimes simultaneously. Process innovation now centers on thermal management and signal integrity rather than pure density scaling.
Modified semi-additive process technology is displacing subtractive etch methods for line-and-space geometries below thirty microns. German automotive radar suppliers have adopted mSAP for 77GHz antenna-in-package modules within eighteen-month qualification windows. The displacement of conventional pattern plating is enabling finer pitch without laminate thickness penalties, though chemistry waste treatment costs rise proportionally.
REACH substance restrictions enforced by ECHA are eliminating legacy tetrabromobisphenol-A flame retardants from FR-4 formulations. Laminate fabricators in Austria and Germany have reformulated to phosphorus-nitrogen systems at fifteen to twenty percent material cost premiums. Medical device and aerospace segments absorb these premiums; industrial automation buyers delay transitions pending supply chain price stabilization.
Consolidated procurement through Tier-1 EMS providers is fragmenting direct OEM-fabricator relationships. German automotive OEMs now specify substrates exclusively through Continental, Bosch, and ZF sourcing umbrellas. Direct supplier access concentrates among Austrian and Bavarian fabricators with established EMS portal integration, while smaller French and Czech producers face channel marginalization.
Europe Printed Circuit Board (PCB) Market Segmentation
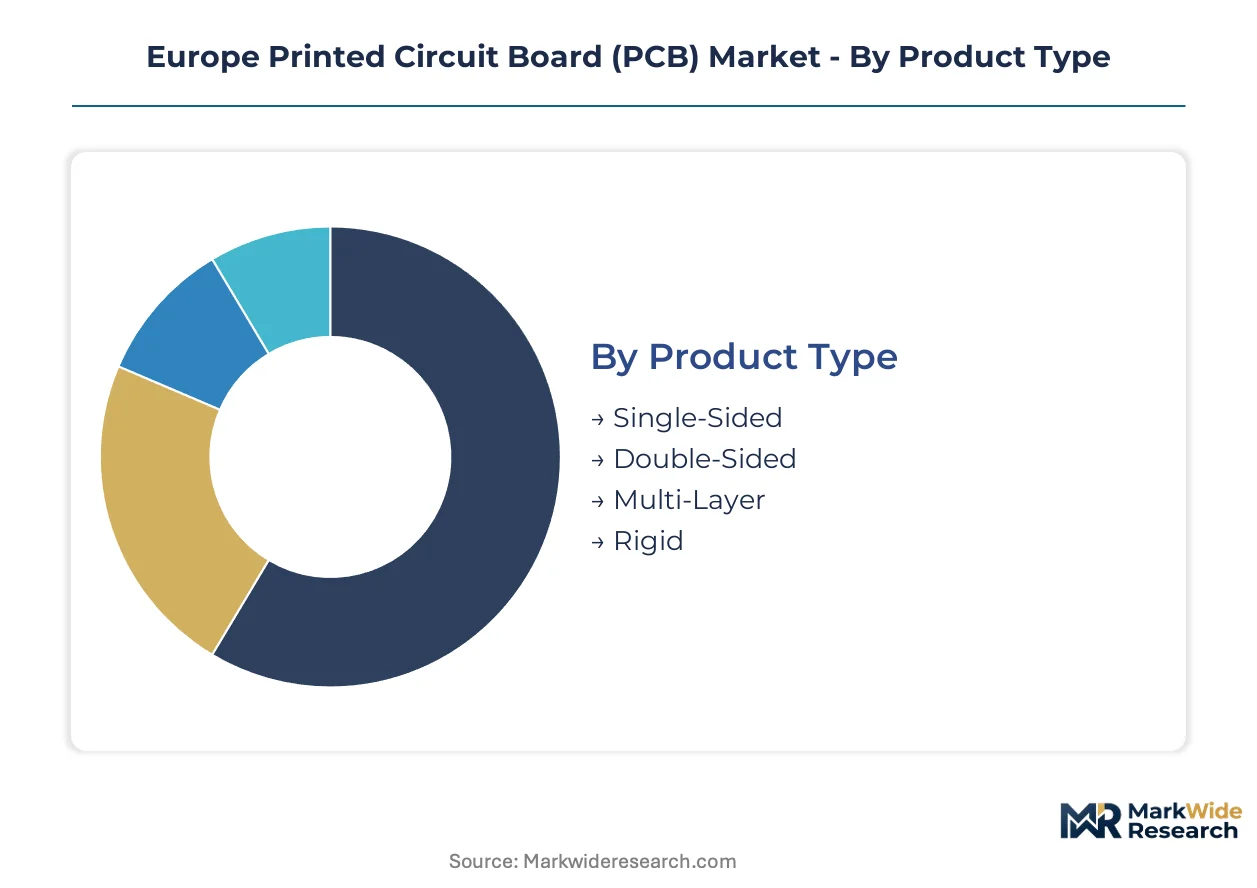
Segmentation in the European PCB market reveals how procurement patterns bifurcate between domestic automotive clusters and export-oriented industrial supply. Material specifications and layer counts vary sharply across German OEM captive demand versus broader European EMS distribution.
Product Type:
Domestic consumption concentrates in high-layer-count substrates for automotive radar and battery management, while single-sided and double-sided boards serve price-sensitive industrial export markets from Czech and Slovak fabrication corridors.
- Single-Sided:Basic copper-clad phenolic or CEM-1 substrates with traces on one surface only. Demand clusters in French and Italian industrial automation for motor controllers and power supplies; REACH compliance costs suppress margin recovery in this commoditized tier.
- Double-Sided:Through-hole plated substrates enabling moderate complexity with lower tooling investment than multi-layer alternatives. Bavarian and Baden-Württemberg fabricators supply double-sided boards to mid-tier automotive suppliers for body electronics modules; ECHA substance documentation requirements now filter procurement toward certified Austrian producers.
- Multi-Layer:Stack configurations with four to twelve-plus conductive layers separated by prepregs, enabling dense signal routing for ADAS processors and server backplanes. German OEM procurement for 77GHz radar modules has standardized on eight-layer minimum specifications.
- Rigid:Standard inflexible laminates dominating volume production across European facilities. Czech fabrication corridors export rigid boards to German EMS providers for telecom infrastructure.
Multi-layer configurations hold the largest share; momentum sits with rigid substrates as automotive electrification accelerates stack count requirements.
Material:
Cost tiers separate REACH-compliant halogen-free formulations from legacy FR-4, with premium laminates capturing medical and aerospace contracts while industrial buyers delay transitions.
- FR-4:Glass-reinforced epoxy laminate with brominated flame retardants, historically the volume standard. German automotive Tier-1s enforce systematic phase-out under EU Green Deal mandates; Austrian fabricators have reformulated to phosphorus-nitrogen systems at material cost premiums absorbed by radar module suppliers.
- CEM-1:Composite epoxy material with cellulose paper core and glass surface, offering cost reduction for single-sided applications. Technical ceiling in thermal cycling reliability prevents penetration into underhood automotive segments; Slovak producers serve industrial automation export demand.
- Copper:Foil and clad materials forming conductive traces and plane layers. CME price volatility above fifteen percent annually compresses laminate fabricator margins; smaller French substrate producers lack hedging infrastructure.
- Polyimide:High-temperature flexible substrate enabling rigid-flex hybrids for three-dimensional packaging. French medical device OEMs represent expanding demand for surgical robotics applications.
FR-4 retains volume dominance despite regulatory pressure; polyimide is climbing the fastest as rigid-flex hybrids penetrate aerospace and medical instrumentation.
End User:
Customer type stratification concentrates value in automotive and telecommunications, with consumer electronics procurement fragmented across price-competitive Asian supply.
- Consumer Electronics:Smartphones, wearables, and home devices requiring high-density interconnect at consumer price points. European fabrication has ceded this segment to Asian capacity; residual demand concentrates in Austrian specialty shops serving premium audio equipment.
- Automotive:Engine control modules, battery management systems, and radar sensors demanding thermal cycling reliability and traceability documentation. German OEM procurement volumes for electrified powertrains have tripled specification complexity; CSRD reporting requirements now filter Tier-1 EMS sourcing toward carbon-accounted suppliers.
- Telecommunications:5G base stations and optical networking equipment requiring low-loss high-frequency laminates. Fluorinated chemistry dependency concentrates resin supply in Asian suppliers; European fabricators face ETS carbon border adjustment exposure on imported specialty substrates.
- Industrial Equipment:PLCs, motor drives, and sensor networks with moderate reliability requirements and extended product lifecycles. Czech and Polish producers serve this segment through German distribution channels.
Automotive captures the largest value share; telecommunications is gaining share fastest as 5G infrastructure deployment accelerates laminate specification upgrades.
Manufacturing Stage:
Supply concentration in fabrication and assembly stages reflects European capacity investment patterns, with design and testing services fragmented across engineering consultancies.
- Design:PCB layout, signal integrity simulation, and stack-up optimization performed by OEM engineering teams or specialized consultancies. German automotive suppliers have consolidated design authority in-house; Bavarian prototype shops face channel marginalization.
- Assembly:Component mounting and solder reflow operations, increasingly concentrated in Tier-1 EMS providers. Continental, Bosch, and ZF sourcing umbrellas now mediate all German OEM substrate procurement; direct fabricator access requires EMS portal integration.
- Testing:Electrical verification, thermal cycling qualification, and ionic contamination analysis. MDR certification timeline compression under EU Medical Device Regulation extends conformity assessment for medical device PCB assemblies.
- Fabrication:Core laminate processing, etching, plating, and drilling operations. AT&S Leoben and Nanjing facilities sustain European supply security for advanced substrates; Wurth Elektronik Niedernhall campus anchors prototype-to-volume continuity.
Fabrication holds the largest share; momentum sits with assembly as EMS consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers in Eastern Europe exhibit acute price sensitivity to laminate premiums, while German automotive OEMs absorb fifteen to twenty percent material cost increases for halogen-free substrates without procurement volume reduction. This demand-elasticity divergence shapes capacity allocation across European fabrication corridors.
Germany
Battery management systems and 77GHz radar modules for electrified powertrains dominate substrate procurement from Continental, Bosch, and ZF sourcing umbrellas. KBA vehicle-type approval requirements enforce traceability documentation that filters Tier-1 EMS contracts toward CSRD-compliant suppliers. Bavarian and Baden-Württemberg fabrication clusters anchor prototype-to-volume continuity for automotive qualification regimes.
Austria
Advanced substrate production for medical device and aerospace miniaturization commands premium positioning under ECHA REACH substance documentation mandates. AT&S Leoben facility sustains European supply security for high-layer-count configurations. The country's technical universities feed specialized plasma etch and laser drill talent pools that Eastern European competitors cannot replicate.
Czech Republic
Single-sided and double-sided board production for industrial automation export markets concentrates in Slovak-border fabrication corridors. EU Green Deal halogen-free mandates compress margins on legacy FR-4 volumes that still dominate this price-sensitive tier. Czech producers serve German distribution channels without direct OEM access.
France
Surgical robotics and drone avionics applications drive rigid-flex hybrid demand from medical device OEMs in the Île-de-France cluster. ANSM medical device regulations extend MDR certification timelines that disadvantage small-batch prototype shops. The country's polyimide substrate consumption climbs fastest among European markets despite lower absolute volumes than German automotive demand.
Switzerland
Precision instrumentation and embedded-chip substrates for aerospace applications leverage Swissmedic certification alignment with EU MDR requirements. Geneva and Zurich metropolitan fabrication facilities specialize in low-volume, high-reliability boards that bypass price competition with Czech industrial exports. The country's carbon accounting infrastructure positions early CSRD-compliant suppliers for cross-border German procurement.
Europe Printed Circuit Board (PCB) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European PCB market. Consolidated procurement through Tier-1 EMS providers has fragmented direct OEM-fabricator relationships, creating a tiered structure where portal-integrated suppliers capture premium automotive contracts while channel-marginalized producers compete on industrial export pricing. Three archetypes dominate: Austrian-Bavarian advanced substrate specialists with EMS integration, Czech-Slovak volume fabricators serving price-sensitive industrial demand, and French-Swiss rigid-flex specialists targeting medical-aerospace niches. Competitive moves center on CSRD compliance certification for procurement preference and embedded-chip competency acquisition for aerospace-medical differentiation.
Among Austrian-based fabricators, AT&S Austria Technologie und Systemtechnik AG occupies the advanced substrate archetype with Leoben facility positioning, while Wurth Elektronik Group anchors the prototype-to-volume continuity tier through its Niedernhall campus. Schweizer Electronic AG exemplifies the embedded-chip specialization vector with Schramberg competency. These three represent distinct strategic positions without overlapping archetype claims.
| Leading Market Players |
|---|
| AT&S Austria Technologie und Systemtechnik AG |
| Wurth Elektronik Group |
| KSG GmbH |
| NCAB Group |
| Schweizer Electronic AG |
| Aspocomp Group |
| ICAPE Group |
| Elvia PCB Group |
| Eurocircuits |
| Others |
Pricing and Supply Chain Analysis
Ninety-day laminate lead times for halogen-free substrates concentrate pricing power with Austrian and German fabricators possessing ECHA REACH-certified material genealogy systems, while Czech producers serving industrial automation export markets absorb margin compression from copper price volatility without recourse to hedging infrastructure.
Pricing Analysis
After-sales service contracts for embedded-chip substrate qualification and MDR documentation support drive lifetime value capture among medical device OEMs. Three-tier pricing structure across premium, standard, and economy levels separates CSRD-compliant Austrian suppliers from certified-but-undifferentiated Bavarian mid-tiers and price-driven Czech industrial exporters. Cost compression in single-sided and double-sided tiers intensifies because REACH substance documentation requirements raise fixed compliance costs that smaller Slovak-border fabricators cannot amortize across limited volumes. Industrial automation buyers in Eastern Europe exhibit acute price sensitivity, while German automotive OEMs absorb material cost premiums without procurement volume reduction.
Supply Chain Analysis
Inventory cycles stretching to sixteen weeks for fluorinated high-frequency laminates expose European fabricators to ETS carbon border adjustment risks on Asian resin imports. Supply concentrates in China for specialty laminates, Germany for automotive-grade multi-layer substrates, and Austria for medical-aerospace miniaturization. Raw material dependencies rest on CME-traded copper cathodes, phosphorus-nitrogen flame retardant formulations, and polyimide films for rigid-flex hybrids. Single-source vulnerability in fluorinated chemistry for 5G base station substrates threatens telecommunications procurement continuity. Distribution runs through Tier-1 EMS provider portals at Continental, Bosch, and ZF, marginalizing direct OEM-fabricator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward Tier-1 EMS consolidation, with Continental, Bosch, and ZF sourcing umbrellas now mediating all German automotive OEM substrate procurement and fragmenting direct supplier access.
For Market Incumbents: Consolidate CSRD compliance certification and embedded-chip competency to defend against Austrian-Bavarian advanced substrate specialists. Acquire plasma etch and laser drill talent pools from technical universities before Eastern European competitors reform curricula. Channel control through EMS portal integration represents the critical lever; fabricators without Continental or Bosch system access face systematic marginalization.
For New Entrants and Emerging Players: Differentiate on rigid-flex hybrid substrates for French surgical robotics OEMs in the Île-de-France cluster, where polyimide demand climbs fastest among European markets. Target medical device miniaturization white space where MDR certification timelines disadvantage incumbent prototype shops. Pursue go-to-market partnerships with Swissmedic-aligned Swiss fabricators to bypass German automotive procurement concentration.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive PCB fabrication assets lacking EMS portal integration or CSRD carbon accounting infrastructure. Long-term viability hinges on qualification regime alignment with EU AI Act traceability obligations and REACH substance documentation mandates. Watch for inflection when ETS carbon border adjustments materially impact fluorinated laminate import economics.
| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Certification | Carbon-accounted facilities secure preferential sourcing from Tier-1 EMS providers under sustainability procurement criteria. |
| Embedded-Chip Competency Acquisition | Schramberg-cluster chip-embedding capability reduces dependency on Asian OSAT capacity for aerospace-medical applications. |
| Halogen-Free Laminate Transition | Phosphorus-nitrogen formulations satisfy EU Green Deal mandates while commanding fifteen to twenty percent material cost premiums. |
| EMS Portal Integration | Direct supplier access to Continental, Bosch, and ZF sourcing umbrellas filters procurement toward integrated fabricators. |
| Rigid-Flex Hybrid Capacity Buildout | Polyimide-glass composite substrates capture expanding surgical robotics demand from French medical device OEMs. |
Research Methodology
A spread of perspectives from Tier-1 EMS procurement directors, Austrian substrate fabricator operations heads, Czech industrial automation buyers, and ECHA regulatory affairs specialists converged on the working assumptions driving material transition timelines. Primary fieldwork combined structured interviews with secondary validation through REACH substance restriction filings, EU Green Deal implementation documents, and customs data on laminate trade flows. Bottom-up capacity assessments at Leoben, Niedernhall, and Schramberg facilities triangulated against top-down demand modeling from German OEM electrification roadmaps.
Segmentation dimensions modeled span product type, material formulation, end-user industry, and manufacturing stage across the analysis window. The analytical framework projects value expansion through layer-count escalation in automotive radar, halogen-free laminate penetration under regulatory mandate, and rigid-flex hybrid adoption in medical instrumentation. CAGRs derive from shipment volume trajectories by substrate tier, calibrated against copper price elasticity observations and EMS procurement consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated ETS carbon border adjustment implementation would require recalibration. Forecasts reflect assumptions on laminate lead-time stabilization and Tier-1 EMS portal access continuity. Supply disruption in fluorinated chemistry or curriculum reform in Eastern European technical universities could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Schottky Rectifiers Market