
 China Semiconductor Device Market | 2026-2036
China Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
China Semiconductor Device Market Insights
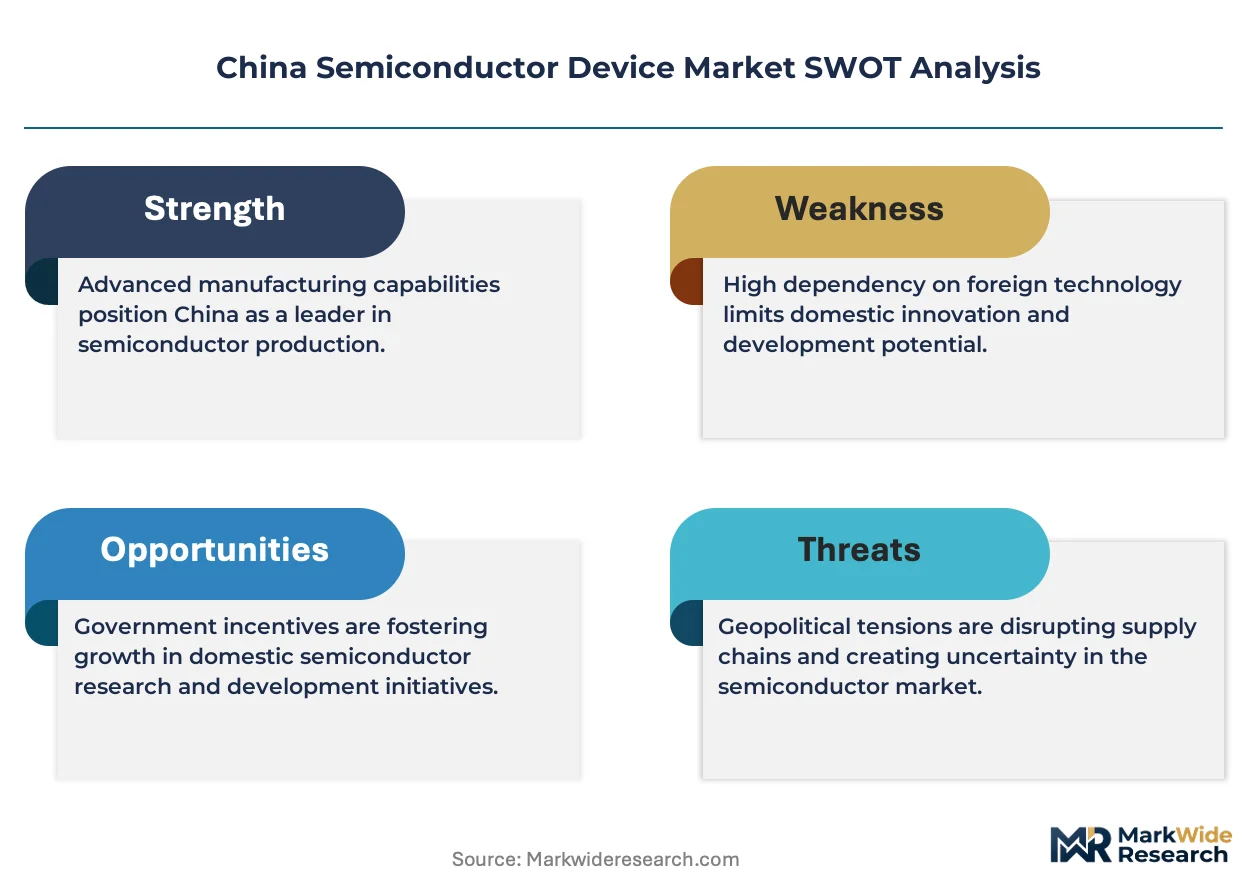
Software-defined feature licensing is restructuring how Chinese foundries monetize wafer output beyond physical die sales. SMIC leverages captive 28nm capacity to anchor supply contracts with state-linked equipment makers. YMTC competes in NAND flash through vertical integration into memory controller design. Hua Hong Semiconductor specializes in power discretes for automotive inverters, occupying a defensible niche against silicon carbide entrants.
China semiconductor devices are electronic components fabricated on crystalline silicon or compound semiconductor substrates, typically processed through photolithography, etching, and deposition steps to achieve feature sizes ranging from mature nodes to advanced geometries, serving functions from signal amplification to power conversion in industrial and consumer systems. Discrete and analog segments dominate current revenue as domestic fabs prioritize process technologies where equipment sanctions impose fewer constraints. Gallium nitride and silicon carbide technologies are capturing margin pools in power management applications as EV charging infrastructure and renewable energy inverters strain silicon thermal limits. Integrated circuits for data processing remain the largest addressable category but face the steepest equipment access barriers.
MIIT's domestic substitution directives, NMPA certification requirements for automotive-grade chips, and GB standards for electromagnetic compatibility collectively shape product roadmaps and foundry qualification timelines. The central bank's technology lending facilities and the PLI scheme for semiconductor manufacturing are redirecting capital toward mature-node expansion and advanced packaging capacity. Stakeholders must monitor equipment import license approvals and foundry utilization rates as signals of whether domestic supply can match design house demand.
Market Dynamics
MIIT's domestic substitution mandates are redirecting procurement flows toward local foundries, compressing foreign supplier access while accelerating capacity buildout at mature nodes where equipment sanctions impose fewer constraints.
Growth Catalysts
- Electric vehicle powertrains:Automakers are scaling orders for silicon carbide MOSFETs and IGBT modules as 800V architectures proliferate, pulling foundry capacity toward automotive-grade qualification.
- GB standards for electromagnetic compatibility:Mandatory certification timelines for industrial equipment are forcing design houses to pre-qualify domestic suppliers, accelerating foundry customer acquisition.
- Dual carbon goals:Central government energy efficiency mandates are prioritizing gallium nitride adoption in data center power supplies and renewable energy inverters.
Market Restraints
- Equipment import licensing:Lithography and deposition tool approvals face extended review cycles, constraining advanced node expansion and forcing reliance on depreciated foreign equipment.
- Silicon wafer price volatility:Polysilicon supply disruptions and energy cost spikes at ingot producers are transmitting margin pressure downstream to foundry cost structures.
- Compound semiconductor substrate scarcity:Silicon carbide boule production concentrates among a handful of non-Chinese suppliers, limiting domestic vertical integration into wide-bandgap devices.
Strategic Opportunities
- Central bank technology lending facilities:Preferential credit lines for semiconductor manufacturing equipment are lowering cost of capital for mature-node expansion and advanced packaging capacity.
- Chiplet-based system architectures:Advanced packaging integration of chiplets fabricated across heterogeneous nodes is expanding into AI accelerators and network processors, bypassing single-die scaling limits.
- State-linked equipment makers:Captive demand from defense and aerospace procurement channels is creating guaranteed offtake for domestically qualified mature-node production.
Industry Challenges
- Process engineer scarcity:Foundry expansion is outpacing supply of experienced 28nm and 40nm process integration talent, extending yield ramp timelines at new facilities.
- NMPA automotive certification:Functional safety qualification for AEC-Q100 Grade 0 devices requires 18-24 month validation cycles, delaying revenue recognition on EV chip contracts.
- Legacy equipment maintenance:Depreciated foreign tool fleets lack manufacturer support, forcing fabs to develop in-house spare part fabrication and repair capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Semiconductor Device Market |
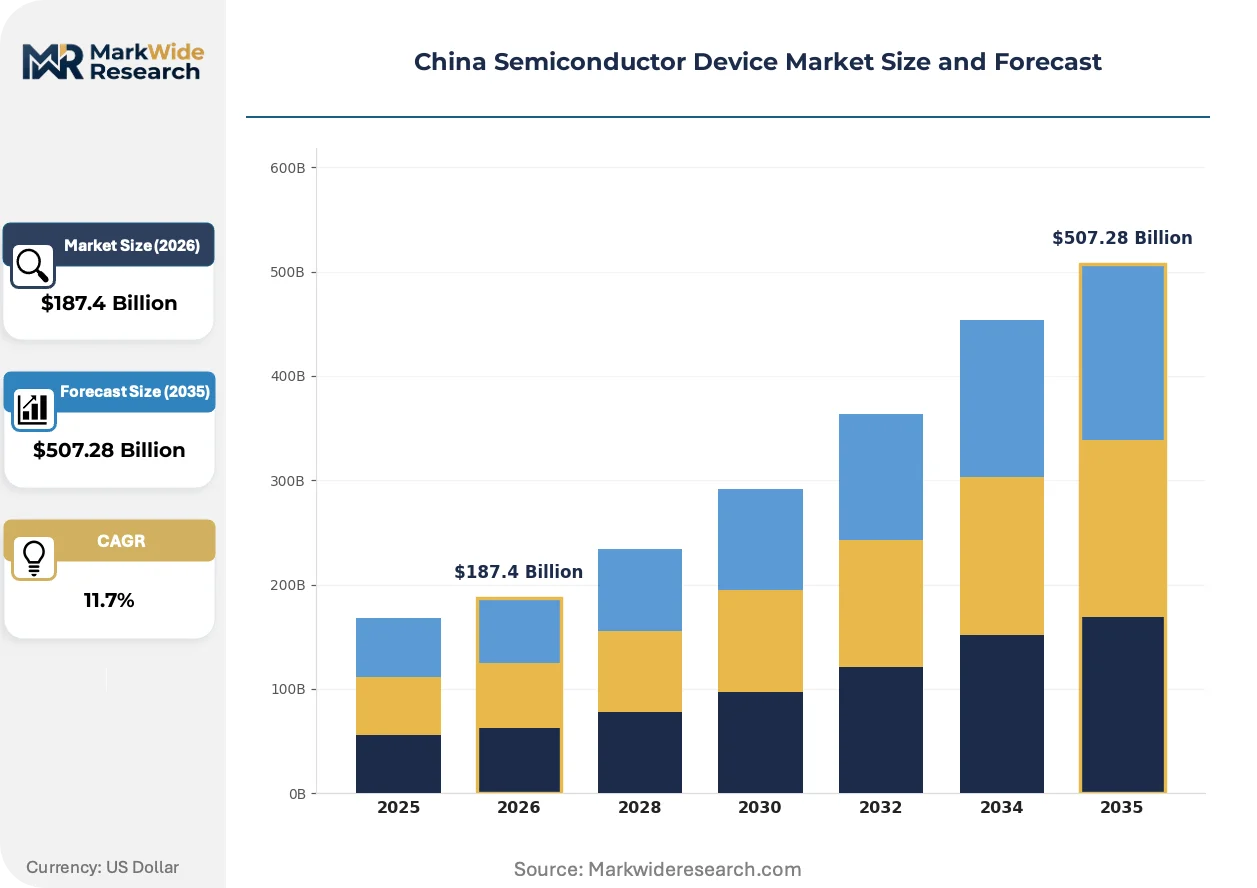
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete, Analog, Digital, Integrated Circuit End User: Telecommunications, Automotive, Consumer Electronics, Industrial Equipment Technology: Silicon, Gallium Nitride, Silicon Carbide, MEMS Application: Signal Processing, Power Management, Data Processing, Sensing |
| Companies Covered | Semiconductor Manufacturing International Corporation (SMIC), Hua Hong Semiconductor, Yangtze Memory Technologies Co. (YMTC), HiSilicon, UNISOC, GigaDevice Semiconductor, China Resources Microelectronics, Will Semiconductor Co. Ltd, JCET Group Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Semiconductor Device Market Trends and Innovations
Software-defined feature licensing is restructuring monetization models, while wide-bandgap materials and advanced packaging architectures are displacing conventional silicon approaches in power and compute applications.
Silicon carbide MOSFET technology is expanding into traction inverters and onboard chargers as EV manufacturers pursue 800V architectures for faster charging. BYD and NIO are qualifying domestic suppliers for 2025 model year platforms. This voltage transition is expanding into a $2 billion addressable pool for power module packaging and thermal management subsystems.
MIIT's domestic substitution directives are mandating minimum local content ratios for telecommunications infrastructure procurement. State-owned carriers must document semiconductor provenance for 5G base station deployments. Equipment vendors are responding by dual-sourcing critical ASICs from SMIC and Hua Hong to maintain contract eligibility.
Design houses are consolidating procurement around qualified domestic foundries, replacing dispersed global supplier relationships with concentrated local contracting. Tier-one fabless companies are embedding yield engineers at partner fabs to compress qualification cycles. This concentration is most visible in Guangdong and Jiangsu provinces where MIIT-linked industrial parks cluster design and manufacturing capabilities.
China Semiconductor Device Market Segmentation
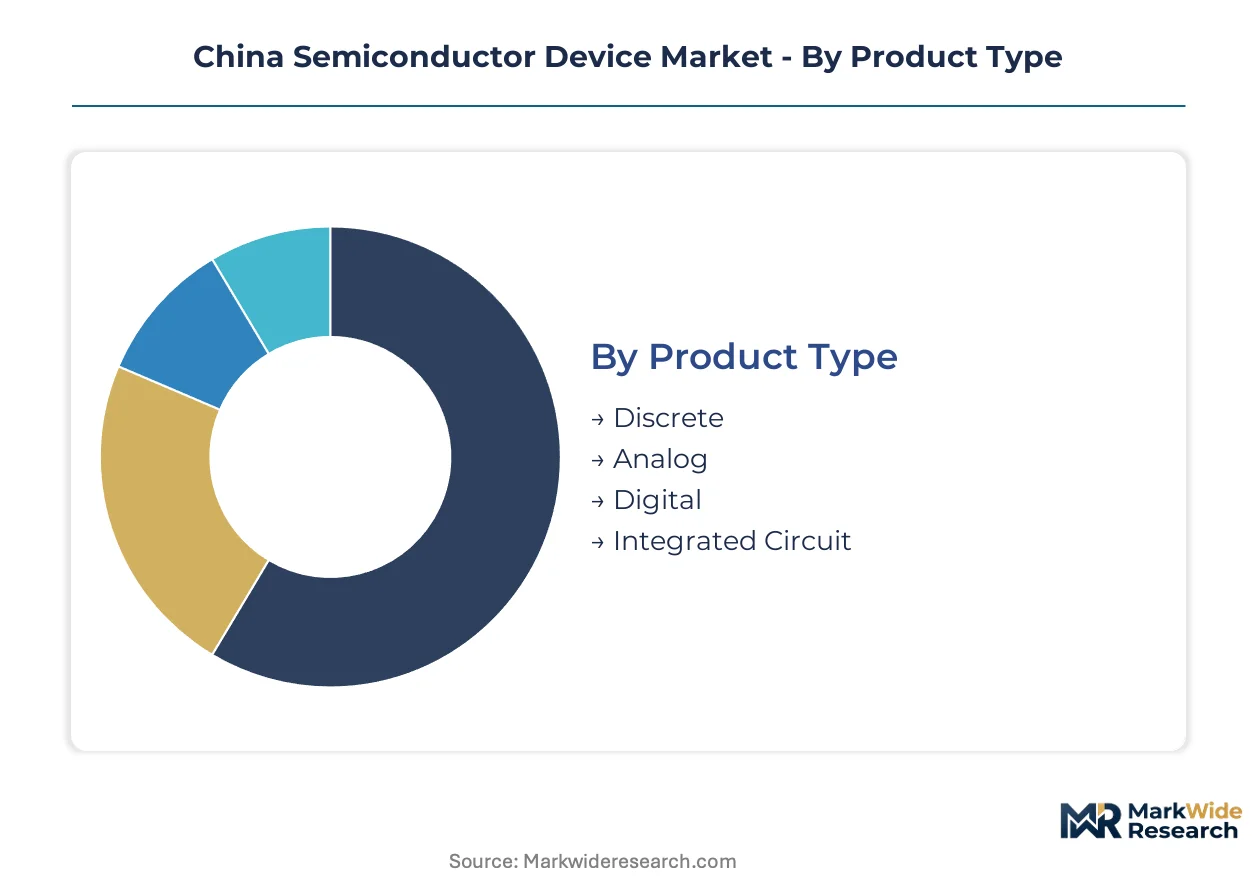
Segmentation of the China semiconductor device market reveals how procurement mandates, equipment constraints, and end-use specifications are fragmenting demand across incompatible process technologies. Foundry capacity allocation decisions now hinge on which segments offer qualified domestic supply versus import-dependent alternatives.
Product Type:
Silicon wafer processing capabilities and lithography tool access determine which product categories domestic fabs can serve profitably.
- Discrete:Individual transistors, diodes, and thyristors fabricated on mature nodes with minimal lithography demands. MIIT procurement directives for state-linked equipment manufacturers are concentrating orders for power discretes at Hua Hong and SMIC facilities in Shanghai and Wuxi.
- Analog:Signal conditioning and interface circuits requiring precise doping control rather than fine feature resolution. Automotive inverter suppliers are qualifying domestic analog foundries for voltage regulator and gate driver production to satisfy NMPA certification timelines.
- Digital:Logic gates and memory cells demanding advanced patterning capabilities. Equipment licensing constraints restrict domestic production to legacy node geometries, forcing design houses to rely on foreign foundries for high-performance digital.
- Integrated Circuit:Multi-function chips combining analog, digital, and memory blocks on single die. Telecommunications infrastructure procurement under MIIT domestic content mandates is accelerating qualification of locally fabricated integrated circuits for 5G base station deployment.
Mature deployment sits with Discrete and Analog segments where equipment sanctions impose minimal constraints. Newer deployment is concentrated in Integrated Circuit categories where advanced packaging techniques circumvent single-die scaling limitations.
End User:
Customer procurement concentration shapes foundry utilization and qualification priorities across China's industrial regions.
- Telecommunications:Base station and optical networking equipment demanding high-reliability semiconductors. State-owned carriers in Jiangsu and Guangdong provinces are documenting semiconductor provenance to satisfy MIIT local content verification requirements.
- Automotive:Powertrain, infotainment, and ADAS systems requiring AEC-Q100 Grade 0 qualification. BYD and NIO are scaling orders for silicon carbide MOSFETs as 800V architectures proliferate across 2025 model year platforms.
- Consumer Electronics:Smartphones, wearables, and home appliances driving volume demand for mature-node logic and memory. Design houses in Shenzhen are consolidating procurement around qualified domestic foundries to replace dispersed global supplier relationships.
- Industrial Equipment:Motor drives, programmable logic controllers, and power supplies subject to GB electromagnetic compatibility certification. Mandatory certification timelines are forcing design houses to pre-qualify domestic suppliers, accelerating foundry customer acquisition.
Volume concentration centers on Consumer Electronics procurement corridors in Guangdong province. Margin expansion is climbing the fastest in Automotive segments where power module packaging and thermal management subsystems command pricing premiums.
Technology:
Substrate material properties and fabrication process maturity determine which technology platforms domestic supply chains can support.
- Silicon:Crystalline substrate processed through established photolithography, etching, and deposition sequences. Foundry expansion at 28nm and 40nm nodes is outpacing supply of experienced process integration talent, extending yield ramp timelines.
- Gallium Nitride:Wide-bandgap compound semiconductor enabling higher switching frequencies and power densities. Central government dual carbon goals are prioritizing gallium nitride adoption in data center power supplies and renewable energy inverters.
- Silicon Carbide:Ultra-wide-bandgap material for high-temperature, high-voltage power applications. Boule production concentrates among non-Chinese suppliers, limiting domestic vertical integration into traction inverters and onboard chargers.
- MEMS:Microelectromechanical structures integrating mechanical and electrical functions on silicon substrates. Sensing applications in automotive and industrial segments are pulling foundry capacity toward specialized MEMS fabrication lines.
Process maturity and equipment availability favor Silicon technology for high-volume production. Capability gaps are most acute in Silicon Carbide substrate supply, constraining domestic capture of EV powertrain semiconductor value.
Application:
Functional requirements determine specification thresholds and qualification burdens for semiconductor procurement.
- Signal Processing:Amplification, filtering, and conversion of analog and digital signals. Telecommunications infrastructure deployment is concentrating demand for high-speed signal processing integrated circuits qualified under MIIT domestic substitution directives.
- Power Management:Voltage regulation, conversion, and distribution across electrical systems. EV charging infrastructure and renewable energy inverters are straining silicon thermal limits, accelerating wide-bandgap material adoption.
- Data Processing:Computation and storage operations in servers, edge devices, and AI accelerators. This segment faces the steepest equipment access barriers for advanced node logic fabrication within domestic supply chains.
- Sensing:Environmental, motion, and biometric detection through integrated transducer elements. Industrial automation and automotive safety systems are driving qualification of domestic MEMS foundries for pressure and inertial sensor production.
Established supply relationships dominate Signal Processing and Power Management applications. Emerging demand is concentrating in Sensing segments where MEMS process specialization creates defensible foundry niches against commodity logic competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabs concentrate in eastern coastal provinces while western regions absorb capacity expansion. Consumption clusters in manufacturing corridors where automotive and telecommunications OEMs anchor demand.
Guangdong Province
BYD and NIO scale silicon carbide orders for 800V EV platforms. MIIT local content mandates force telecom equipment vendors to document semiconductor provenance for 5G base stations. Shenzhen design houses consolidate procurement around qualified domestic foundries.
Jiangsu Province
State-owned carriers verify chip origin for infrastructure deployment under MIIT substitution directives. Nanjing and Suzhou industrial parks cluster fabless companies with SMIC and Hua Hong wafer supply. Yield engineers embed at partner fabs to compress qualification cycles.
Shanghai Municipality
SMIC anchors 28nm capacity contracts with state-linked equipment manufacturers. Central bank technology lending facilities lower capital costs for mature-node expansion. Zhangjiang Hi-Tech Park concentrates analog and power discrete design activity.
Beijing Municipality
HiSilicon and UNISOC headquarters drive demand for locally fabricated integrated circuits. Dual carbon goals accelerate gallium nitride adoption in data center power supplies. Zhongguancun software corridor pulls MEMS sensor qualification for industrial automation.
Shaanxi Province
Western China capacity expansion targets automotive-grade analog production for NMPA certification. Xi'an semiconductor industrial park attracts packaging and test investment. Process engineer scarcity extends yield ramp timelines at new 40nm facilities.
China Semiconductor Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for margin capture across the value chain. Foundry capacity allocation hinges on equipment access and qualification timelines rather than pure scale economics. Three archetypes dominate: state-linked integrated device manufacturers, fabless design houses with captive fab relationships, and specialized power discrete suppliers. Competitive moves center on backward integration into substrate supply and strategic partnerships for advanced packaging capacity.
Among state-affiliated producers, Semiconductor Manufacturing International Corporation exemplifies the capital-intensive foundry archetype, while Hua Hong Semiconductor occupies a defensible position in automotive power discretes. Yangtze Memory Technologies Co. anchors the memory specialist tier through in-house controller design capabilities. These three entities represent distinct strategic postures: scale-driven logic fabrication, niche power device qualification, and vertical memory integration.
| Leading Market Players |
|---|
| Semiconductor Manufacturing International Corporation (SMIC) |
| Hua Hong Semiconductor |
| Yangtze Memory Technologies Co. (YMTC) |
| HiSilicon |
| UNISOC |
| GigaDevice Semiconductor |
| China Resources Microelectronics |
| Will Semiconductor Co. Ltd |
| JCET Group Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade certification tiers bifurcate the China semiconductor device market into premium qualified supply and commodity spot markets, with NMPA AEC-Q100 validation timelines embedding 18-24 month cost premiums that concentrate procurement among pre-qualified domestic foundries while unqualified suppliers compete on wafer price alone.
Pricing Analysis
Margin tightening in mature-node production reflects depreciated foreign tool maintenance burdens and polysilicon energy cost spikes transmitting downstream. Contract-based long-term offtake dominates automotive power module procurement, while spot transactions govern consumer electronics logic. Price differentiation separates AEC-Q100 Grade 0 certified supply from industrial-grade alternatives, with volume scale and GB electromagnetic compatibility certification as secondary tiering factors. BYD and NIO procurement teams exhibit lowest price sensitivity for silicon carbide traction inverters, whereas Shenzhen consumer electronics design houses prioritize wafer cost minimization.
Supply Chain Analysis
Refurbishment flows for lithography and deposition tools are expanding as domestic fabs develop in-house spare part fabrication capabilities to sustain depreciated foreign equipment fleets. Taiwan, South Korea, and the USA anchor advanced node equipment supply, while Japan and Germany concentrate silicon carbide boule production. Raw material dependencies span high-purity polysilicon ingots, photoresist chemicals, and rare earth elements for compound semiconductor substrates. Single-source vulnerability in extreme ultraviolet lithography systems constrains domestic advanced node expansion. Distribution runs through state-linked equipment procurement channels and MIIT-verified telecommunications carrier supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment access barriers and MIIT domestic substitution mandates are consolidating procurement around qualified domestic foundries, forcing unqualified competitors toward commodity spot markets or exit.
For Market Incumbents: Hedge against silicon carbide substrate scarcity by securing long-term supply agreements with non-Chinese boule producers or accelerating gallium nitride process qualification for EV powertrain applications. Anchor 28nm capacity utilization through captive contracts with state-linked defense and aerospace equipment makers, leveraging central bank technology lending facilities to compress cost of capital versus emerging competitors.
For New Entrants and Emerging Players: MEMS sensor foundry partnerships offer the most penetrable entry vector, as industrial automation and automotive safety systems pull capacity toward specialized fabrication lines with fewer incumbent barriers. Target Shaanxi Province packaging and test investment corridors where process engineer scarcity extends yield ramp timelines and creates acquisition opportunities for technical talent. Qualify through NMPA certification pre-consultation to compress AEC-Q100 validation cycles versus standard submission pathways.
For Investors and Strategic Acquirers: Re-rating potential sits with advanced packaging specialists given chiplet-based AI accelerator demand and heterogeneous integration bypassing single-die lithography limits. Five-to-ten year viability favors foundries with demonstrated MIIT qualification track records and established yield engineering partnerships with tier-one fabless design houses. Monitor equipment import license approval velocity as the inflection indicator for domestic advanced node capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Substrate Supply | Reduces dependency on Japanese and German boule producers for EV powertrain qualification. |
| Advanced Packaging Capacity Expansion | Captures chiplet integration demand from AI accelerator and network processor design houses. |
| MIIT Domestic Content Certification Investment | Unlocks state-owned carrier procurement for 5G base station integrated circuit deployment. |
| Yield Engineering Partnership Embedding | Compresses NMPA automotive qualification timelines through fabless-foundry technical collaboration. |
| Gallium Nitride Process Technology Licensing | Addresses dual carbon goals in data center power supply and renewable energy inverter applications. |
Research Methodology
Independent corroboration across foundry operations executives, fabless design house procurement leads, automotive Tier 1 supplier quality engineers, and MIIT policy research fellows underwrites the qualitative findings. Secondary validation draws from MIIT equipment import license disclosures, NMPA automotive certification registries, central bank technology lending facility allocations, and SEC 10-K filings of foreign equipment suppliers with China exposure. Bottom-up wafer capacity buildout tracking triangulates against top-down procurement mandate implementation assessments.
Historical reference periods anchor the projection horizon through trailing utilization rate trends and qualification cycle duration benchmarks. Segmentation dimensions span product type, end user industry, substrate technology, and application function, with regional MIIT directive intensity as a China-specific overlay. CAGRs derive from capacity expansion announcements, equipment delivery schedules, and design house procurement consolidation patterns. Forecast inputs incorporate polysilicon price volatility transmission and compound semiconductor substrate supply constraints.
Caveats apply where equipment licensing review cycle extensions or polysilicon supply disruptions could materially shift the outlook. Practitioners should monitor foundry utilization rates and NMPA certification queue lengths for early signals of domestic supply-demand balance inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Thin Film Transistors (TFT) Market