
 DNA Chip Market | 2026-2036
DNA Chip Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Chip Market Intelligence
The direct-to-laboratory sales channel for high-throughput screening equipment is reshaping competitive positioning among microarray manufacturers. Illumina, Inc. leverages its market leadership in sequencing platforms to bundle chip sales and create integrated workflows. Thermo Fisher Scientific Inc. competes on the breadth of its life sciences portfolio and extensive global distribution network. Agilent Technologies specializes in customized array solutions, differentiating itself by serving niche research and diagnostic development needs with high-specificity products.
A DNA chip, or microarray, is a solid-state device, typically a glass slide or silicon chip, onto which thousands of microscopic spots of DNA oligonucleotides are attached. Its primary purpose is to simultaneously measure the expression levels of large numbers of genes or to genotype multiple regions of a genome. Oligonucleotide Arrays represent the dominant product type due to their high density and flexibility in design. Gene Expression Analysis and Drug Discovery applications drive significant volume, particularly from pharmaceutical companies and academic research institutions.
Regulatory frameworks from the US FDA, Europe's EMA, and China's NMPA govern the use of DNA chips in clinical diagnostics and drug development. These bodies impose stringent validation requirements for assays, influencing chip manufacturing quality control and data reproducibility standards. Future development depends on establishing universal standards for data analysis and inter-laboratory comparability to support broader clinical adoption and regulatory acceptance of microarray-based tests.
Market Dynamics
The primary structural force shaping the DNA chip market is the convergence of semiconductor manufacturing techniques with genomics. Advanced photolithography, originally developed for microprocessors, enables the production of increasingly dense microarrays, which drives down the cost per genetic marker analysis.
Growth Catalysts
- Precision Medicine Initiatives:Government-backed projects, such as the US All of Us Research Program, create large-scale demand for genotyping arrays to support population health studies and biomarker discovery for disease risk prediction.
- Pharmacogenomics in Drug Development:Pharmaceutical firms utilize DNA chips to stratify patient cohorts in clinical trials, enhancing the efficacy of trial design and accelerating the development of targeted therapies.
- Next-Generation Lithography:Continued improvements in photolithographic processes permit the fabrication of ultra-high-density arrays, increasing probe capacity and enabling more complex genetic investigations on a single chip.
Market Restraints
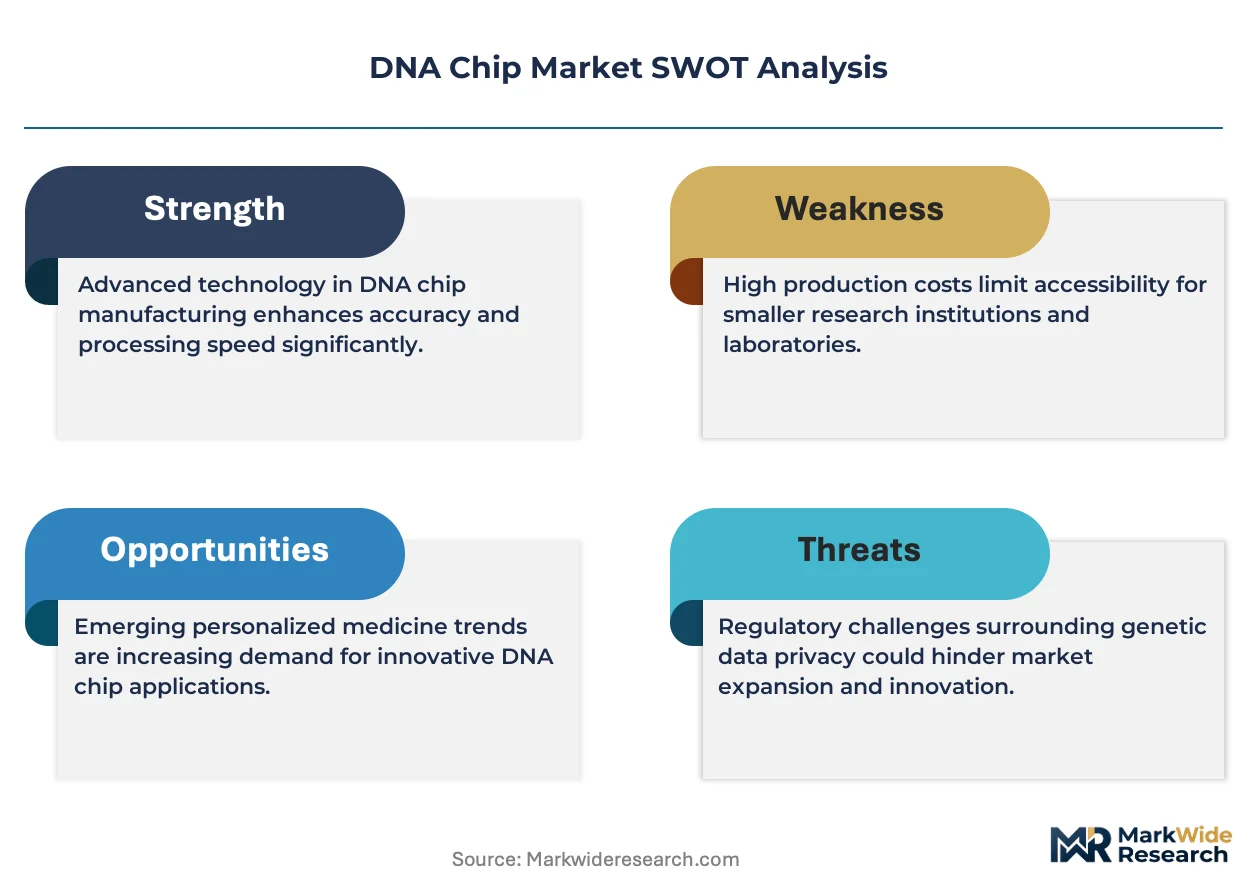
- High Capital Equipment Cost:The sophisticated scanners and automated fluidics stations needed for high-throughput microarray processing require significant upfront capital, limiting adoption by smaller research labs and clinical facilities.
- Competition from NGS:For whole-genome and exome analysis, Next-Generation Sequencing (NGS) provides more comprehensive data than targeted genotyping arrays, presenting a strong substitution threat in specific research and diagnostic applications.
- Bioinformatics Bottleneck:Analyzing the vast datasets from high-density arrays demands substantial computational power and specialized bioinformatics expertise, which remains a critical resource constraint for many end-users.
Strategic Opportunities
- Clinical Diagnostics in Asia:Regulatory reforms by China's NMPA are creating clearer pathways for in-vitro diagnostic (IVD) approvals, opening opportunities for microarray-based tests in oncology and non-invasive prenatal screening.
- Expansion into Agrigenomics:The use of DNA chips for marker-assisted selection in crop and livestock breeding represents a significant growth vector outside of human health, improving agricultural productivity.
- Integration with Microfluidics:Combining microarray technology with microfluidic systems enables the automation of sample preparation and analysis, creating a pathway toward developing integrated, point-of-care diagnostic platforms.
Industry Challenges
- Data Standardization Barriers:A lack of universal standards for data formats and analysis protocols across different microarray platforms complicates inter-laboratory comparisons and hinders regulatory acceptance of array data by bodies like the EMA.
- Complex Intellectual Property:The field is characterized by a dense patent landscape covering probe sequences, fabrication methods, and analysis algorithms, which can create licensing hurdles and legal risks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Chip Market |
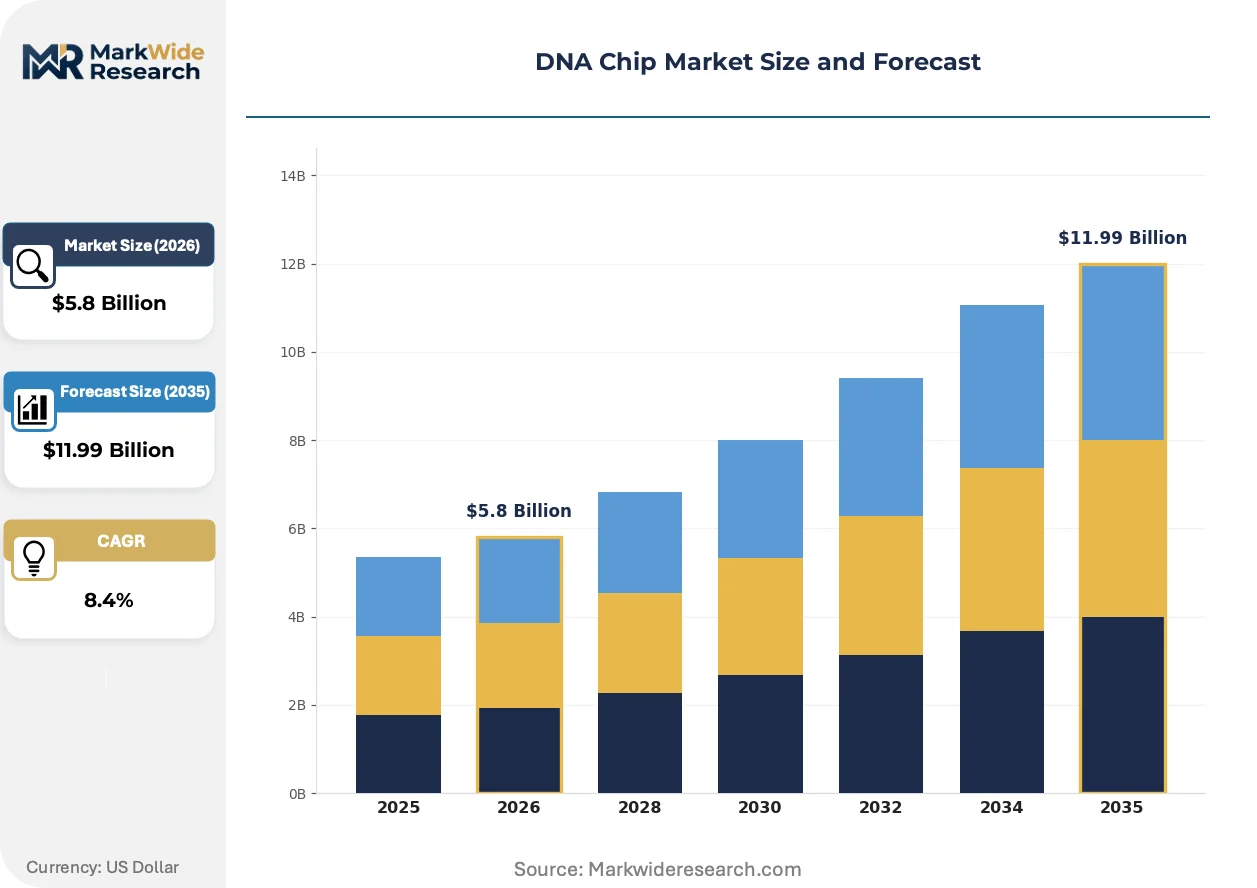
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligonucleotide Arrays, Coded Bead Arrays, Complementary DNA Arrays, Protein Arrays, Peptide Arrays Technology: Photolithography, Inkjet Synthesis, Spotting, Semiconductor, Electrochemical Detection Application: Genotyping, Gene Expression Analysis, Drug Discovery, Biomarker Identification, Forensic Analysis End User: Research Institutions, Biotechnology Firms, Pharmaceutical Companies, Diagnostic Laboratories |
| Companies Covered | Revvity, CapitalBio Technology Co., Ltd., Illumina, Inc., Oxford Gene Technology IP Limited, Asper Biotech, Thermo Fisher Scientific Inc., Macrogen, Inc., Greiner Bio-One International GmbH, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Chip Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from discovery research tools toward validated solutions for clinical and industrial applications. This shift prioritizes automation, data reproducibility, and integration into standardized workflows to meet stringent quality and regulatory demands.
Computer-aided design (CAD) of custom arrays combined with flexible inkjet synthesis technologies allows for rapid prototyping of specialized chips. Niche diagnostic developers and research consortia are the primary adopters of this approach for targeted assay development. This capability for on-demand design is rendering obsolete the exclusive reliance on fixed-content catalog products for initial research and development phases.
Europe's In Vitro Diagnostic Regulation (IVDR) is elevating the requirements for clinical evidence and post-market surveillance for all diagnostic tests. This directly impacts DNA chip-based diagnostics, forcing manufacturers to generate more extensive validation data. Consequently, diagnostic kit producers are increasing investment in rigorous clinical trials and quality management systems to comply with the heightened scrutiny.
A fundamental shift in consumption patterns shows end-users moving from direct instrument purchases toward using core facilities and contract research organizations (CROs) for microarray services. This model disrupts direct-to-lab sales channels, concentrating purchasing power within these specialized service providers. This trend is most advanced within academic and biotechnology clusters in the United States and Germany, where outsourcing capital-intensive operations is a prevalent strategy.
DNA Chip Market Segmentation
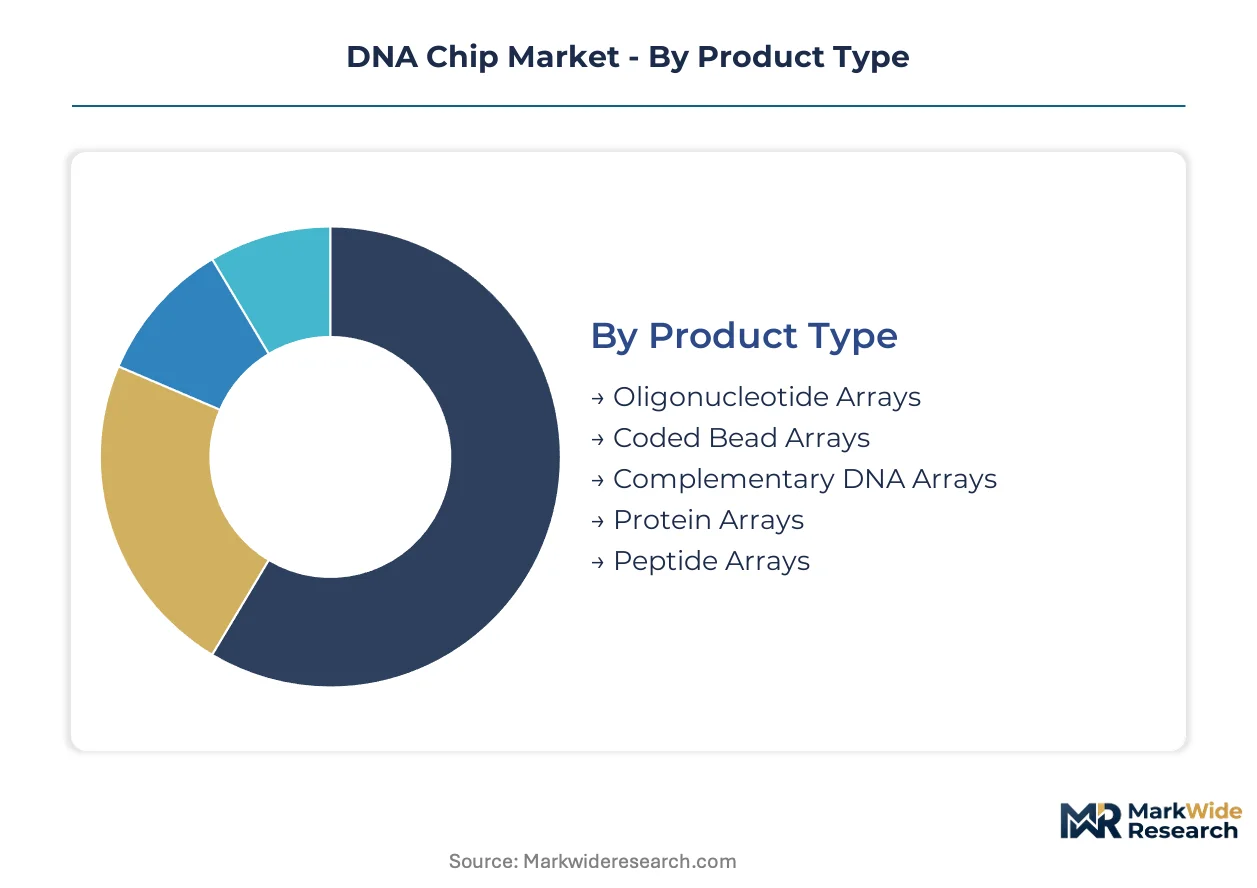
The DNA chip market exhibits diverse segmentation, reflecting varied technological approaches and end-user requirements. Understanding these distinct segments is essential for identifying specific growth pockets and competitive dynamics within the broader genomic analysis landscape. Each segment addresses unique research and clinical challenges, driving specialized product development.
Product Type:
The product type segment spans mature, established array formats alongside more specialized, emerging platforms designed for specific analytical needs.
- Oligonucleotide Arrays:These arrays feature short, synthetic DNA sequences attached to a solid surface, enabling high-density gene expression profiling and genotyping. Demand concentrates within pharmaceutical companies for drug discovery, leveraging their flexibility in design and high throughput capabilities.
- Coded Bead Arrays:This technology employs microscopic beads, each encoded with a unique identifier and linked to a specific probe, allowing for multiplexed detection of various analytes in a single reaction. Clinical diagnostic laboratories increasingly adopt these systems for high-throughput screening, driven by their ability to analyze multiple targets simultaneously.
- Complementary DNA Arrays:These arrays utilize longer cDNA sequences to monitor gene expression, particularly in early-stage academic research.
- Protein Arrays:Protein arrays are used for studying protein-protein interactions, biomarker discovery, and antibody profiling in proteomics research.
- Peptide Arrays:These arrays feature synthetic peptides for epitope mapping, enzyme activity studies, and drug target identification.
Oligonucleotide Arrays retain volume leadership; Coded Bead Arrays hold the steepest expansion curve.
Technology:
Technological approaches underpin the array fabrication process, with each method optimized for specific application requirements regarding density, cost, and customization.
- Photolithography:This semiconductor manufacturing technique patterns microscopic features on a substrate, enabling ultra-high-density DNA chips with precise probe placement. Research institutions and large biotechnology firms leverage photolithography for complex genetic studies, benefiting from the low cost per data point.
- Inkjet Synthesis:Inkjet-based methods deposit DNA oligonucleotides directly onto a surface, allowing for rapid prototyping and on-demand customization of array designs. Niche diagnostic developers and academic consortia adopt this technology for targeted assay development due to its flexibility and quick turnaround.
- Spotting:Mechanical spotting involves physically depositing pre-synthesized probes onto a substrate, a cost-effective method for lower-density arrays.
- Semiconductor:Semiconductor-based DNA chips integrate detection directly onto the chip, offering high sensitivity and rapid analysis for point-of-care applications.
- Electrochemical Detection:This technology uses electrical signals to detect hybridization events, providing label-free and real-time analysis for advanced research.
Photolithography remains foundational for high-volume production, while Inkjet Synthesis accelerates specialized assay development.
Application:
Application segments delineate the primary use cases for DNA chips, with certain areas driving substantial market volume due to their direct impact on research and healthcare outcomes.
- Gene Expression Analysis:This application measures the activity of thousands of genes simultaneously, providing insights into biological processes, disease mechanisms, and drug responses. Academic research institutions and biotechnology firms represent significant users, driven by the need for comprehensive transcriptional profiling.
- Drug Discovery:Pharmaceutical companies utilize DNA chips extensively in drug discovery to identify therapeutic targets, stratify patient cohorts for clinical trials, and assess drug toxicity. This application demands high-throughput screening capabilities and accurate genetic profiling to accelerate targeted therapy development.
- Genotyping:Genotyping involves identifying genetic variations, such as SNPs, for population studies, disease association, and personalized medicine.
- Biomarker Identification:This application focuses on discovering and validating molecular indicators of disease presence, progression, or therapeutic response.
- Forensic Analysis:DNA chips are employed in forensic science for human identification, paternity testing, and criminal investigations, requiring high specificity and reliability.
Gene Expression Analysis generates substantial research volume, and Drug Discovery applications are expanding rapidly within the pharmaceutical sector.
End User:
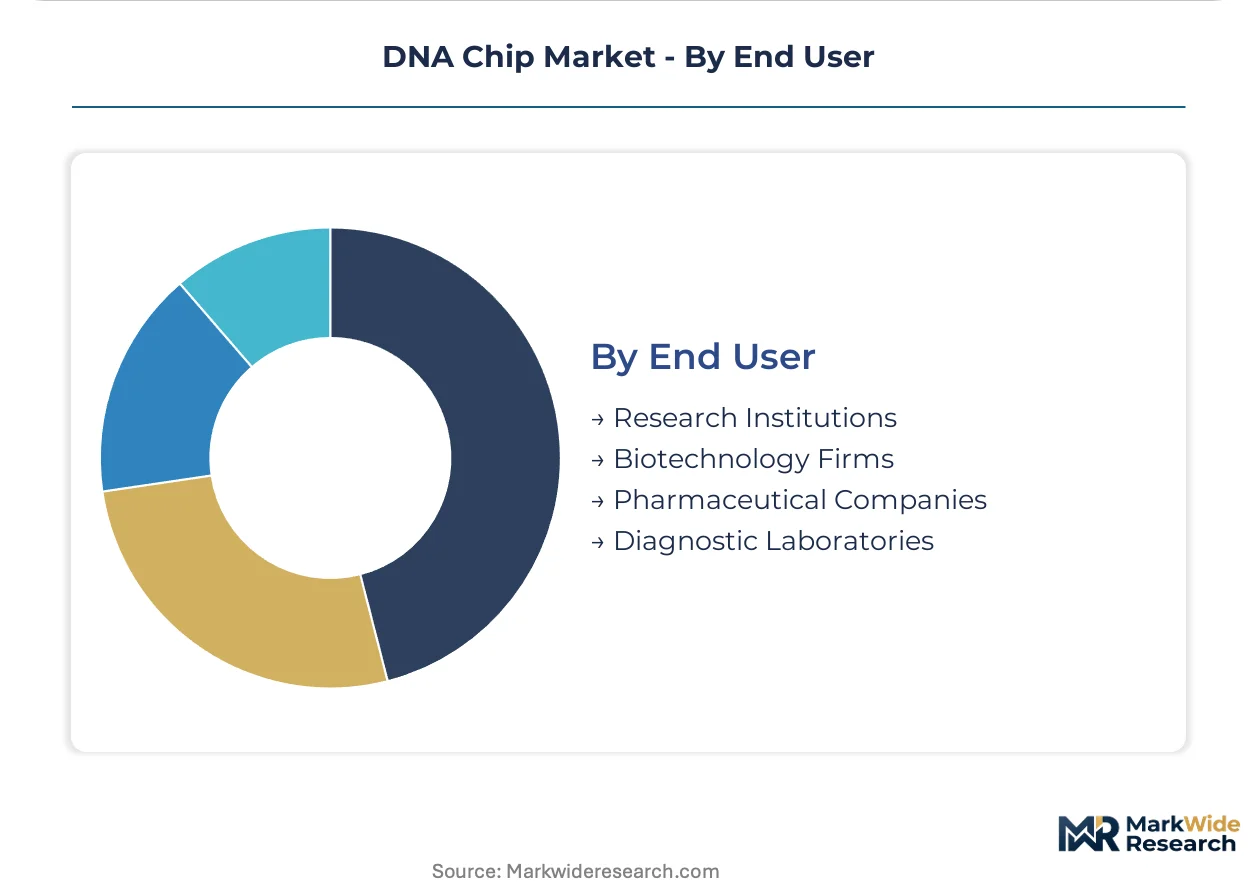
End-user segments reflect the diverse organizations leveraging DNA chip technology, each with distinct procurement patterns and application priorities.
- Pharmaceutical Companies:These firms are major consumers of DNA chips for pharmacogenomics, drug target validation, and patient stratification in clinical trials. Their demand is concentrated in the United States and Europe, driven by extensive R&D budgets and a focus on precision medicine.
- Diagnostic Laboratories:Clinical diagnostic laboratories use DNA chips for genetic testing, infectious disease screening, and oncology diagnostics, particularly for in-vitro diagnostic (IVD) applications. Regulatory reforms by China's NMPA create clearer pathways for IVD approvals, boosting adoption in Asia.
- Research Institutions:Academic and government research institutions utilize DNA chips for fundamental genomic studies, biomarker discovery, and population health initiatives.
- Biotechnology Firms:These companies employ DNA chips for product development, contract research services, and specialized genomic analysis solutions.
Pharmaceutical Companies represent a high-value customer base, while Diagnostic Laboratories demonstrate increasing demand for validated clinical assays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the DNA chip market exhibits asymmetry, with established markets like the United States dictating premium pricing while emerging regions such as China focus on volume-driven cost efficiencies. This dynamic influences investment flows and product development strategies across various global hubs. Manufacturers adapt their commercial models to these distinct regional economic realities.
United States
Demand for DNA chips in the United States is driven by its advanced biotechnology research infrastructure and significant public and private funding for genomic research. Government initiatives like the All of Us Research Program create large-scale demand for genotyping arrays. The Boston and San Francisco Bay Area biotechnology clusters lead innovation in array design and application development.
Germany
Germany's strong pharmaceutical industry and academic research institutions generate substantial demand for DNA chips in drug discovery and gene expression analysis. The European Medicines Agency (EMA) validation requirements influence chip manufacturing quality control and data reproducibility standards. Research hubs in Munich and Heidelberg are pioneering new applications for microarray technology.
China
China's market for DNA chips is expanding rapidly, particularly in clinical diagnostics and drug development applications. Regulatory reforms by China's NMPA are creating clearer pathways for in-vitro diagnostic approvals for microarray-based tests. The Yangtze River Delta and Beijing regions are central to manufacturing and research advancements in genomic analysis.
Japan
Academic research institutions and pharmaceutical firms in Japan utilize DNA chips extensively for fundamental genomic studies and drug discovery efforts. The Pharmaceuticals and Medical Devices Agency (PMDA) governs the use of DNA chips in clinical diagnostics, ensuring stringent validation requirements. Tokyo and Osaka remain key centers for biotechnology research and development in the country.
India
India's demand for DNA chips stems from a growing contract research organization sector and an increasing number of diagnostic laboratories. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, including DNA chips, for clinical use within the country. Major biotechnology clusters in Bangalore and Hyderabad are driving adoption for research and diagnostic services.
DNA Chip Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical reagents and fabrication services for DNA chips. The market structure is tiered, featuring a few dominant players offering comprehensive genomic solutions alongside numerous specialized array manufacturers. Strategic archetypes include integrated platform providers, niche diagnostic developers, and service-oriented contract research organizations. Competitive moves focus on strategic partnerships for broader application development and portfolio diversification into adjacent life science technologies.
Specialists in integrated genomic workflows like US-based Illumina, Inc. and Thermo Fisher Scientific Inc. represent leading market positions through extensive product portfolios and global distribution networks. These corporations exemplify the trend towards bundled solutions that combine hardware, consumables, and software platforms for comprehensive genetic analysis. US-based Agilent Technologies occupies a distinct position focused on customized array solutions, differentiating itself by serving niche research and diagnostic development needs with high-specificity products. These companies collectively anchor the market's innovation and commercialization efforts.
| Leading Market Players |
|---|
| Revvity |
| CapitalBio Technology Co., Ltd. |
| Illumina, Inc. |
| Oxford Gene Technology IP Limited |
| Asper Biotech |
| Thermo Fisher Scientific Inc. |
| Macrogen, Inc. |
| Greiner Bio-One International GmbH |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Photolithography, a core upstream manufacturing technique, dictates the cost structure for high-density DNA chips, channeling significant margin pools to integrated platform providers. This semiconductor-driven concentration influences pricing power across the entire value chain.
Pricing Analysis
Configured-to-order DNA chips command a premium over standard catalog products, reflecting specialized assay development and project-based pricing. Per-unit transactional sales characterize high-volume oligonucleotide arrays. Price differentiation stems from customization level, brand reputation, and regulatory validation status. Pricing softness runs through high-volume, standardized products due to competition from Next-Generation Sequencing, making smaller research labs highly price sensitive.
Supply Chain Analysis
Contract manufacturing capacity for DNA chips largely resides with specialized foundries leveraging semiconductor techniques in the United States and China. The supply chain relies on high-purity glass substrates, silicon wafers, and custom DNA oligonucleotides. Complex intellectual property covering probe sequences presents a structural risk, creating licensing hurdles. Distribution runs through direct-to-lab channels and increasingly via specialized core facilities and Contract Research Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DNA chip market represents a high-growth disruption, driven by the convergence of semiconductor manufacturing techniques with advanced genomics. Next-generation lithography continually refines array density, enabling more complex genetic investigations.
For Market Incumbents:
Insulate core market share by deepening integrated workflows, bundling chip sales with sequencing platforms to counter Next-Generation Sequencing competition. Incumbents should invest in advanced photolithography R&D to maintain density leadership and reduce cost per data point. Expanding global distribution networks and investing in clinical validation for IVD compliance reinforces market position against emerging specialized players.
For New Entrants and Emerging Players:
Build out specialized assay development capabilities using inkjet synthesis for rapid prototyping and customization, targeting unmet needs in niche diagnostics. Asia's clinical diagnostics market, particularly with China's NMPA reforms, offers a significant white space for microarray-based tests. Focusing on integrated microfluidic systems for point-of-care applications provides a distinct go-to-market angle, reducing reliance on high-capital equipment.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with specialized diagnostic developers and bioinformatics solution providers, offering attractive acquisition targets for long-term growth. The market's trajectory towards clinical and industrial applications supports sustained viability over the next decade. Acquirers should prioritize firms with established regulatory pathways for IVD approvals or strong intellectual property in next-generation lithography. A critical signal to watch is the establishment of universal data analysis standards for broader clinical adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Integrated Workflow Solutions | Illumina's strategy of bundling chip sales with sequencing platforms enhances customer stickiness. |
| Invest in Next-Generation Photolithography | Continued advancement in array density supports complex genetic studies and reduces cost per analysis. |
| Pursue IVD Regulatory Approvals in Asia | China's NMPA reforms open significant opportunities for microarray-based clinical diagnostics. |
| Expand into Agrigenomics Applications | DNA chips for marker-assisted selection improve agricultural productivity and diversify revenue streams. |
| Develop Microfluidics-Integrated Platforms | Automation of sample preparation enables point-of-care diagnostic platforms, expanding market access. |
Research Approach
A spread of perspectives from pharmaceutical R&D heads, diagnostic lab directors, academic genomic researchers, and biotechnology firm executives converged on the working assumptions. This primary research was validated against secondary sources including US FDA filings, EMA submissions, and academic journals. Bottom-up data aggregation and top-down market sizing provided robust triangulation of market dynamics.
Demand-supply balance modeling informed the quantitative framework across the analysis window. The market was segmented by product type, technology, application, end-user, and regional regulatory clusters for granular analysis. Compound annual growth rates were derived from historical adoption trends and projected technological advancements. Key forecast inputs included next-generation lithography improvements and anticipated IVD approval timelines.
Stress conditions across NGS technological advancements and evolving regulatory validation standards were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained R&D investment and stable public health initiatives. Quarterly review of sequencing technology advancements and regulatory guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Dual Voltage Comparator Market