
 Japan Semiconductor Device in Consumer Industry Market | 2026-2036
Japan Semiconductor Device in Consumer Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Semiconductor Device in Consumer Industry Market Insights
The gap between premium custom silicon and commodity off-the-shelf chips is expanding as Japanese consumer OEMs dual-source for cost control while reserving top-tier slots for proprietary designs. Toshiba Corporation leverages captive fabs to sustain supply security for high-reliability microcontrollers in home appliances. Renesas Electronics Corporation anchors the automotive-to-consumer crossover, competing on mixed-signal integration that bridges infotainment and power management. Sony Semiconductor Solutions Corporation dominates image sensor architectures, differentiating through stacked CMOS processes that command design wins in premium smartphones and cameras.
Japan semiconductor devices in the consumer industry comprise integrated circuits, discrete components, and sensor modules fabricated on silicon wafers ranging from 200mm to 300mm, employing nodes from mature 40nm to advanced 7nm for applications demanding low power consumption, high thermal efficiency, and precise analog performance in televisions, gaming consoles, and connected home systems. Memory chips face structural pressure from Korean price competition, yet logic devices capture expanding margin pools as OEMs prioritize application-specific integrated circuits for AI-enabled edge processing in consumer electronics. MEMS technology leads growth in wearable devices, where miniaturized accelerometers and pressure sensors enable health monitoring functions that analog-only architectures cannot deliver.
METI enforces domestic production targets through subsidy frameworks that condition funding on local 300mm fab commitments, while JIS standards mandate electromagnetic compatibility and thermal cycling thresholds that foreign suppliers must certify before accessing Japanese OEM procurement lists. PMDA oversight intersects where semiconductor-enabled medical wearables blur consumer and healthcare classifications, adding compliance layers to mixed-signal designs. Stakeholders must monitor whether METI's next subsidy tranche prioritizes equipment over materials, as that choice will reshape which technology tiers—digital, analog, or MEMS—receive capital allocation priority.
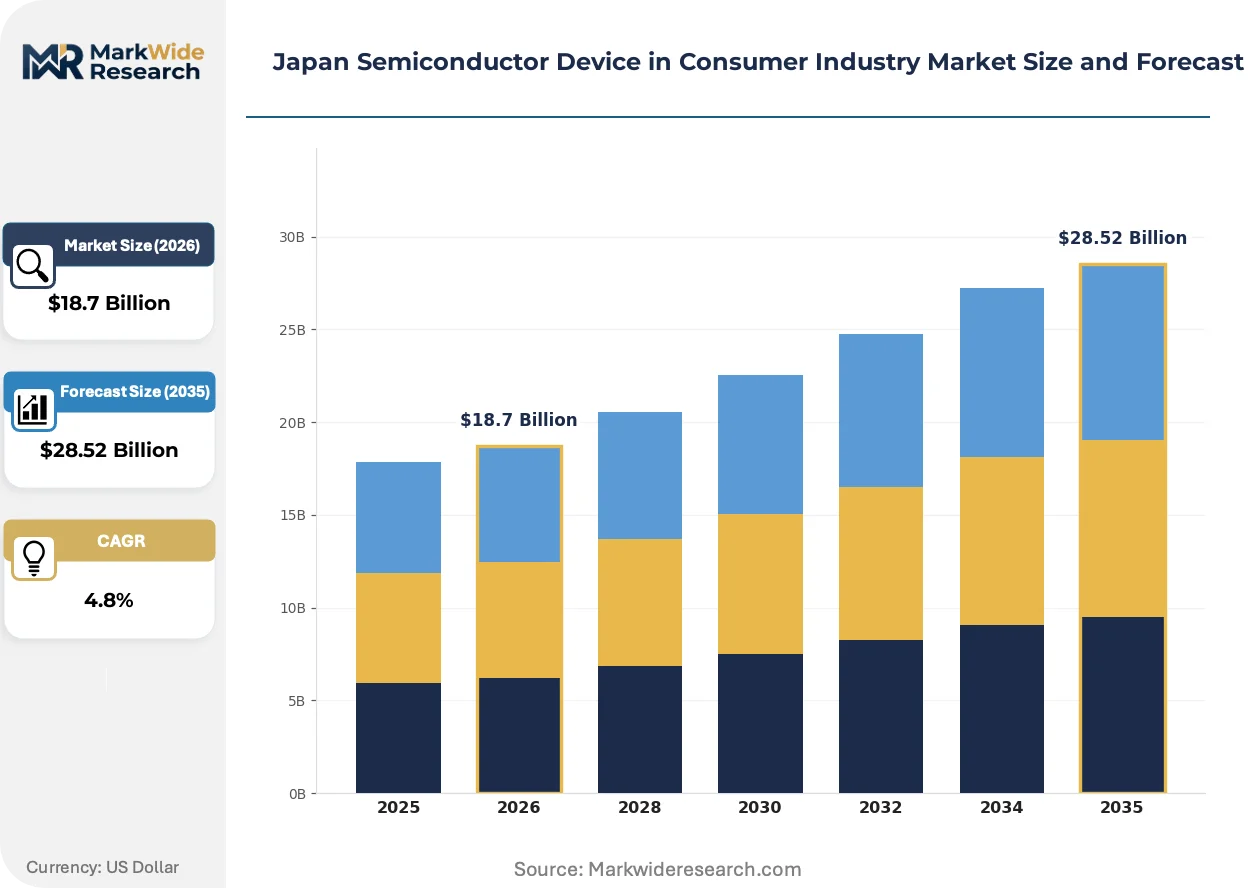
Market Dynamics
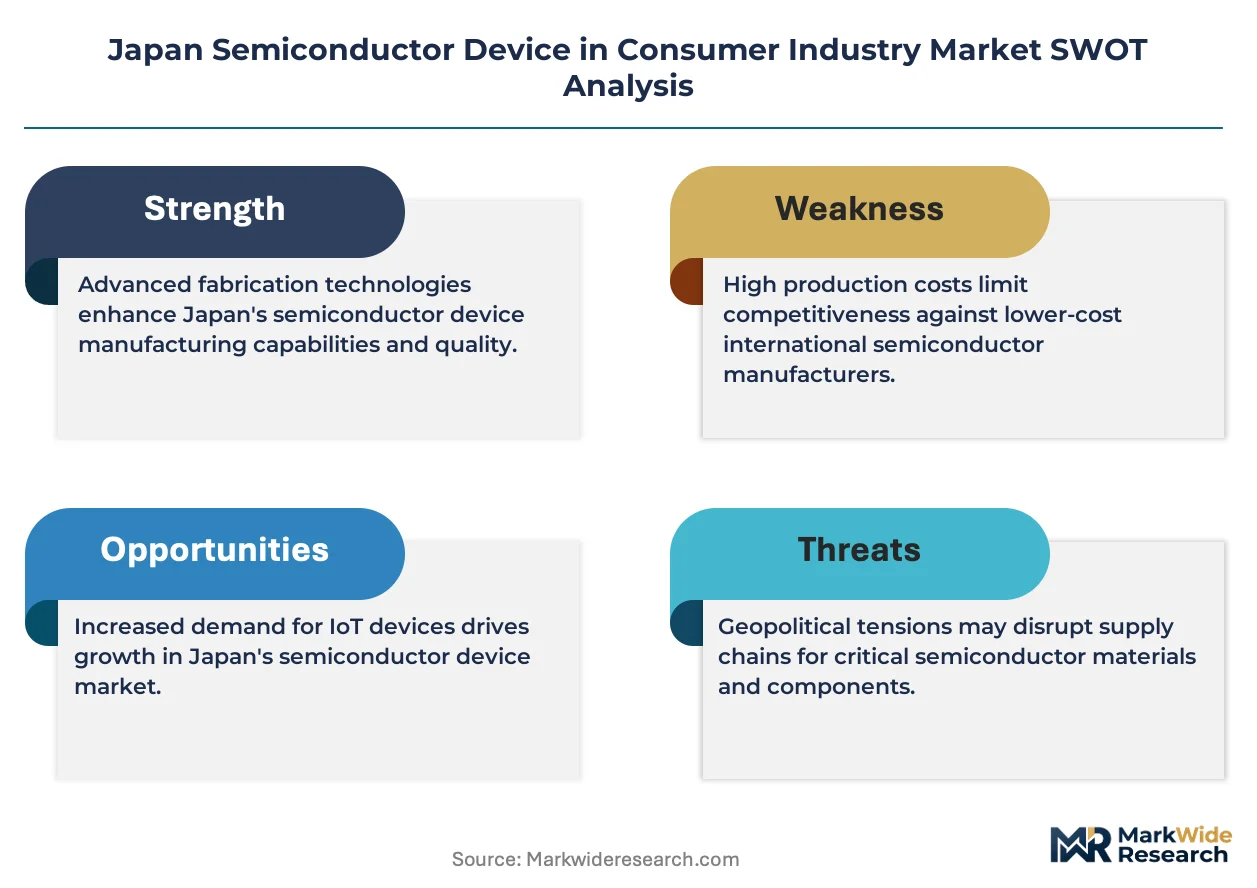
METI's semiconductor resilience subsidies are redirecting fabrication investments toward domestic 300mm wafer capacity, compressing lead times for Japanese consumer OEMs while raising capital barriers for foreign competitors seeking procurement access.
Growth Catalysts
- Domestic Fab Expansion:METI subsidy frameworks condition funding on local 300mm wafer commitments, pulling equipment investments toward Kanto and Kansu manufacturing corridors.
- AI-Enabled Edge Processing:Application-specific integrated circuits for machine learning inference in televisions and gaming consoles command expanding margin pools as OEMs dual-source logic devices.
- Health Monitoring Convergence:PMDA oversight of semiconductor-enabled medical wearables creates hybrid demand for mixed-signal controllers that bridge consumer and healthcare classifications.
Market Restraints
- Memory Price Compression:Korean DRAM and NAND flash suppliers undercut Japanese memory chip pricing, eroding margin pools for commodity storage components in consumer devices.
- Equipment Import Dependency:Lithography and deposition tools concentrate among Dutch and American suppliers, exposing Japanese fabs to export control volatility and delivery uncertainty.
- Analog Node Stagnation:Mature 40nm and 28nm processes for mixed-signal controllers face limited foundry competition, constraining cost reduction for home appliance microcontrollers.
Strategic Opportunities
- Osaka-Nagoya Manufacturing Belt:Smart home appliance manufacturers in these industrial clusters are expanding orders for mixed-signal controllers, creating captive demand for domestic fab output.
- Stacked CMOS Process Leadership:Advanced packaging architectures for image sensors enable premium smartphone and camera design wins through differentiated pixel density and power efficiency.
- JIS Certification Arbitrage:Electromagnetic compatibility and thermal cycling thresholds mandated by Japanese standards create procurement friction that domestic suppliers exploit against uncertified foreign competitors.
Industry Challenges
- Specialized Analog Design Talent:Mixed-signal circuit architects with precision analog performance expertise concentrate among aging engineer cohorts at legacy integrated device manufacturers, constraining workforce expansion.
- Legacy System Integration:Consumer OEMs in Kanto maintain decades-old microcontroller architectures in appliance lines, forcing backward-compatible chip designs that delay node migration.
- Dual-Use Export Scrutiny:Advanced node fabrication equipment faces multilateral coordination on licensing timelines, stretching procurement cycles for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Semiconductor Device in Consumer Industry Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Memory Chips, Logic Devices, Amplifiers Application: Consumer Electronics, Automotive Systems, Home Appliances, Wearable Devices Technology: Digital, Analog, Mixed-Signal, MEMS End User: Manufacturers, OEMs, Distributors, Retailers |
| Companies Covered | Toshiba Corporation, Renesas Electronics Corporation, Sony Semiconductor Solutions Corporation, ROHM Semiconductor, Kyocera Corporation, Mitsubishi Electric Corporation, Panasonic Holdings Corporation, NXP Semiconductors NV, Sharp Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Semiconductor Device in Consumer Industry Market Trends and Innovations
Stacked CMOS architectures and MEMS miniaturization are compressing form factors while expanding functional density in Japanese consumer electronics, with regulatory subsidies accelerating domestic fabrication commitments.
Advanced packaging for image sensors is absorbing wafer-level integration complexity that previously required discrete component assemblies. Tokyo-based smartphone OEMs and camera manufacturers are adopting these architectures at accelerated design cycles. The technology is absorbing margin pressure from commoditized sensor markets by enabling proprietary pixel configurations that command premium positioning.
METI's subsidy frameworks are conditioning capital allocation on verified domestic 300mm fab commitments, reshaping investment flows toward Kanto manufacturing corridors. Equipment vendors and materials suppliers are relocating technical support resources to satisfy local content verification requirements. Consumer logic and MEMS segments receive disproportionate funding priority under current tranche structures, diverting resources from memory expansion projects.
Component sourcing for wearable devices is rotating toward health-monitoring-optimized specifications as PMDA oversight extends to consumer-grade medical adjacent products. Osaka and Nagoya OEMs are unbundling traditional semiconductor procurement into separate analog, digital, and sensor module contracts. This pattern concentrates most visibly in Kanto design centers, where Tokyo-based engineering teams specify mixed-signal controllers with explicit health data security compliance pathways.
Japan Semiconductor Device in Consumer Industry Market Segmentation
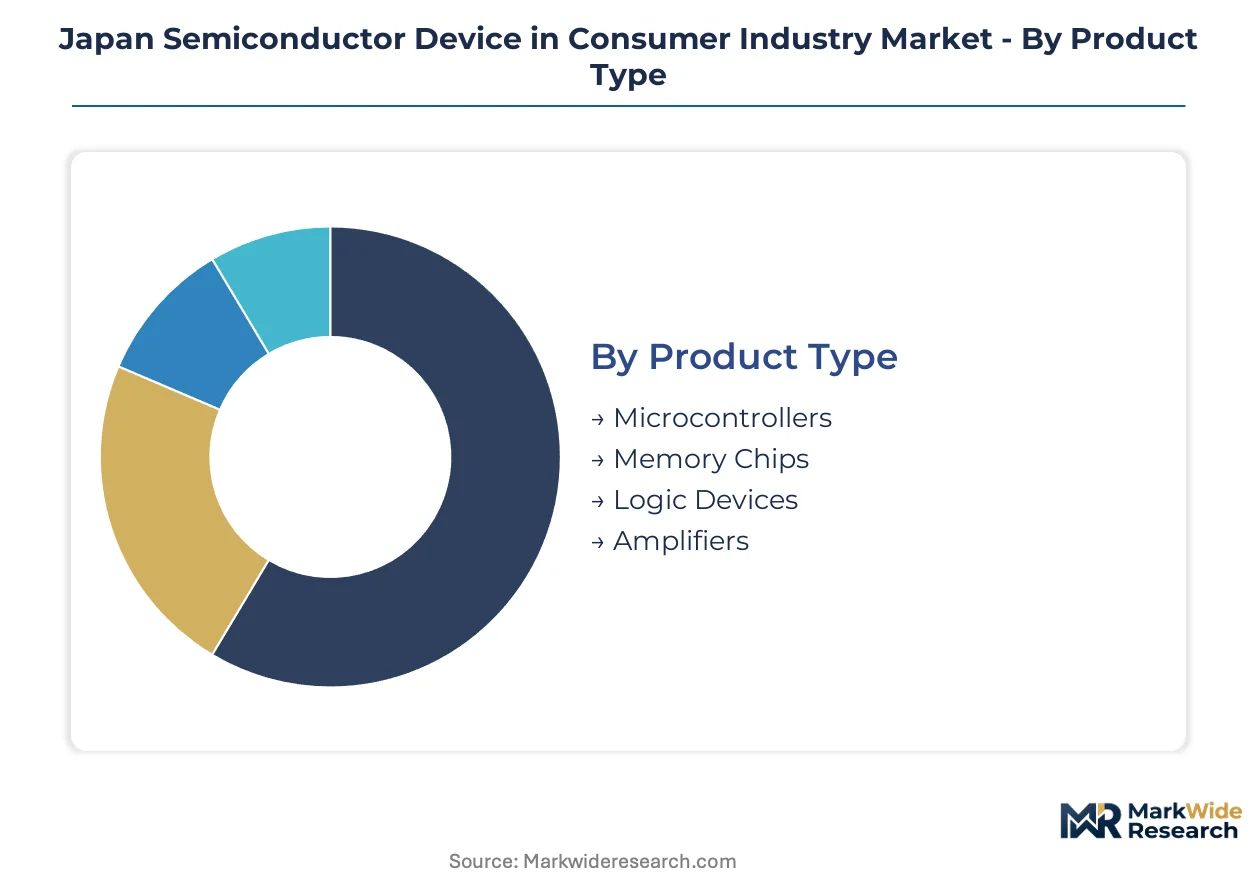
Segmentation in Japan's consumer semiconductor market reveals how METI subsidies and JIS certification requirements reshape procurement patterns across product tiers. Understanding these divides exposes where domestic fabrication investments concentrate versus where foreign suppliers retain access.
Product Type:
JIS electromagnetic compatibility certification applies differentially across product types, with mixed-signal controllers facing the most stringent thermal cycling thresholds while commodity memory operates under relaxed standards.
- Microcontrollers:These integrated circuits combine processor cores with embedded memory and peripheral interfaces on single dies. Osaka and Nagoya smart home appliance manufacturers are expanding orders for 40nm-28nm mixed-signal variants that integrate power management with sensor interfaces. METI subsidies condition funding on local 300mm fab commitments for these devices.
- Memory Chips:DRAM and NAND flash storage components fabricated on mature nodes. Korean suppliers undercut Japanese pricing in this category, eroding margin pools for commodity storage in televisions and gaming consoles while pushing domestic producers toward specialty configurations.
- Logic Devices:Application-specific integrated circuits and programmable logic enabling AI-enabled edge processing.
- Amplifiers:Audio and signal conditioning circuits requiring precise analog performance in home entertainment systems.
Leading the category by volume: Microcontrollers. Growing fastest: Logic devices for AI inference.
Application:
End-use applications sort by PMDA oversight intensity, with medical-adjacent wearables triggering hybrid compliance pathways absent from pure consumer electronics.
- Consumer Electronics:Televisions, gaming consoles, and imaging equipment demanding high thermal efficiency and low power consumption. Tokyo-based OEMs cluster design centers in Kanto for wearable and imaging chips, specifying stacked CMOS processes for premium smartphones and cameras.
- Wearable Devices:Health-monitoring-optimized specifications now dominate procurement as PMDA oversight extends to consumer-grade medical adjacent products. MEMS miniaturization enables accelerometers and pressure sensors that analog-only architectures cannot deliver for fitness tracking and vital sign monitoring.
- Home Appliances:Connected refrigerators, washing machines, and climate systems requiring mixed-signal controllers.
- Automotive Systems:Infotainment and power management bridging consumer and transportation classifications.
Volume concentrates in Consumer Electronics. Steepest expansion trajectory: Wearable Devices.
Technology:
Process technology segments align with capital allocation priority under METI's current subsidy tranche, which disproportionately funds logic and MEMS over memory expansion.
- Mixed-Signal:Controllers integrating analog sensing with digital processing on unified dies. These devices bridge infotainment and power management applications where Renesas Electronics anchors the automotive-to-consumer crossover, competing on integration density that reduces component count.
- MEMS:Micro-electromechanical systems fabricating mechanical structures on silicon substrates. Miniaturized accelerometers and pressure sensors in Osaka-Nagoya manufacturing belts enable health monitoring functions driving wearable device procurement.
- Digital:Pure logic circuits for computation and data processing.
- Analog:Continuous signal processing circuits for sensor interfaces and audio paths.
Mixed-Signal dominates procurement value. MEMS climbs the fastest on health monitoring convergence.
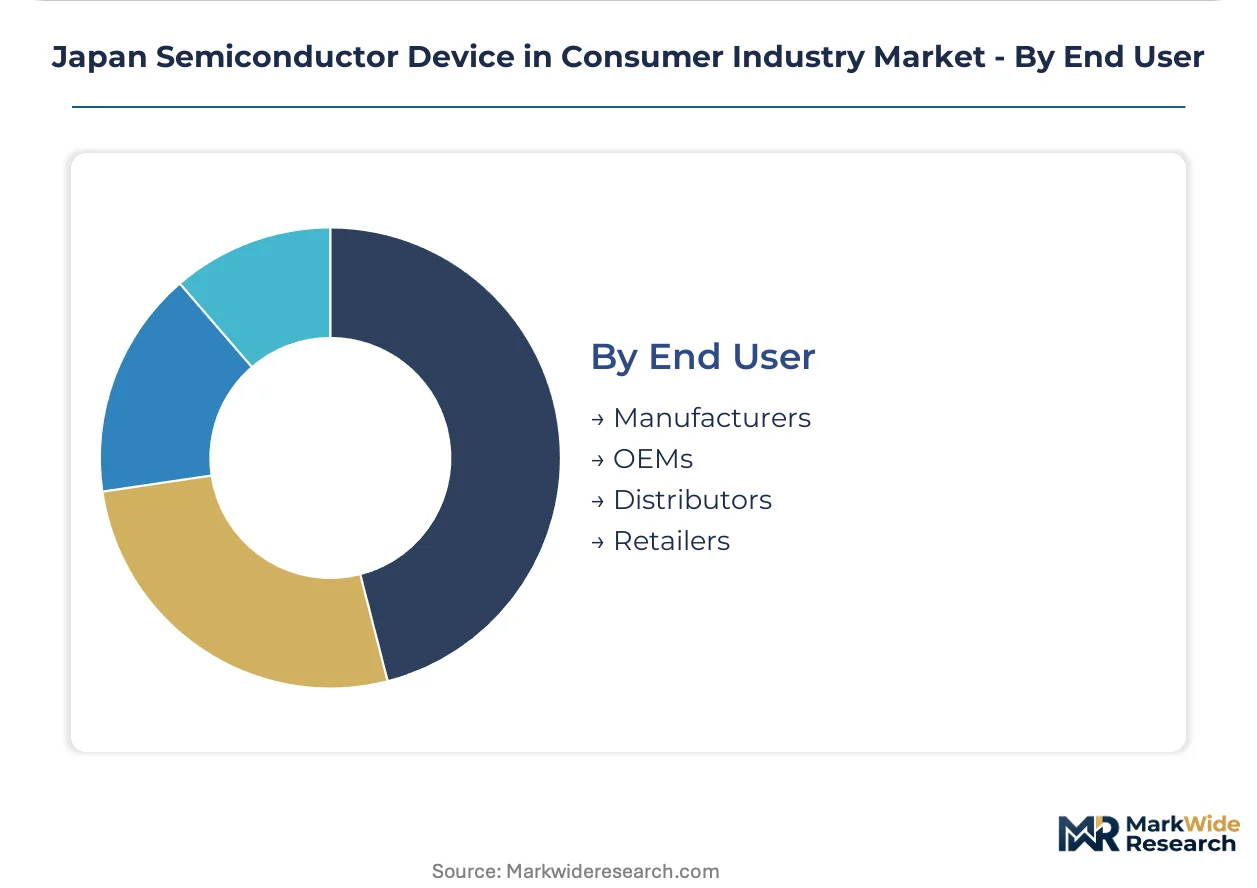
End User:
Channel position determines JIS certification burden, with direct OEM relationships requiring full electromagnetic compatibility documentation while distributor intermediaries absorb compliance verification.
- OEMs:Original equipment manufacturers in Kanto and Kansai corridors specifying chip designs for captive production lines. These buyers dual-source for cost control while reserving top-tier slots for proprietary designs, unbundling traditional semiconductor procurement into separate analog, digital, and sensor module contracts.
- Manufacturers:Domestic fab operators and assembly houses consuming wafer-level output.
- Distributors:Intermediaries managing inventory and technical support for mid-tier procurement.
- Retailers:End-market channels for replacement components and aftermarket modules.
OEMs lead procurement volume. Distributors gain share fastest on unbundled contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors semiconductor demand through Kanto-based OEM design centers specifying mixed-signal controllers for wearable and imaging applications. Osaka and Nagoya manufacturing belts concentrate smart home appliance production, driving captive demand for domestic 300mm wafer output. METI subsidy frameworks redirect fabrication investments toward verified local commitments, compressing procurement lead times for Japanese consumer electronics manufacturers.
Kanto
Tokyo-based OEMs cluster design centers for wearable and imaging chips, specifying stacked CMOS processes for premium smartphones and cameras. METI enforces domestic production targets through subsidy frameworks conditioning funding on local 300mm fab commitments. Yokohama and surrounding Kanto manufacturing corridors absorb disproportionate capital allocation under current tranche structures.
Kansai
Osaka smart home appliance manufacturers expand orders for mixed-signal controllers integrating power management with sensor interfaces. JIS standards mandate electromagnetic compatibility and thermal cycling thresholds that foreign suppliers must certify before accessing procurement lists. Kyoto and Osaka fabrication facilities capture equipment investments pulled toward domestic content verification requirements.
Chubu
Nagoya industrial clusters drive demand for 40nm-28nm mixed-signal variants in connected home systems. PMDA oversight intersects where semiconductor-enabled medical wearables blur consumer and healthcare classifications, adding compliance layers to mixed-signal designs. Toyota-adjacent suppliers in Aichi Prefecture specify backward-compatible chip architectures that delay node migration.
Kyushu
Legacy semiconductor fabrication facilities in Kumamoto and Miyazaki Prefectures maintain mature node capacity for analog-intensive consumer applications. Regional suppliers face equipment import dependency on Dutch lithography and American deposition tools, exposing operations to export control volatility. Local governments coordinate with METI to secure subsidy tranches prioritizing logic and MEMS segments.
Tohoku
Sendai and surrounding prefectures host materials suppliers relocating technical support resources to satisfy local content verification requirements. Earthquake resilience protocols shape fab construction standards distinct from other Japanese regions. Regional industrial policy targets semiconductor equipment manufacturing rather than wafer fabrication, diverging from Kanto and Kansai investment patterns.
Japan Semiconductor Device in Consumer Industry Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the mixed-signal integration and stacked CMOS process tiers. The vendor base concentrates among integrated device manufacturers with captive fabrication capacity and fabless specialists leveraging domestic foundry partnerships. Three archetypes dominate: legacy conglomerates with diversified electronics portfolios, pure-play semiconductor specialists, and automotive-to-consumer crossover suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with subsidy-conditioned local 300mm commitments determining procurement access.
Among Japan-based integrated device manufacturers, Toshiba Corporation, Renesas Electronics Corporation, and Sony Semiconductor Solutions Corporation occupy distinct archetype positions. Toshiba exemplifies the legacy conglomerate model with diversified electronics exposure. Renesas anchors the automotive-to-consumer crossover tier. Sony Semiconductor Solutions represents the imaging-specialist vector commanding premium positioning through differentiated pixel architectures.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Renesas Electronics Corporation |
| Sony Semiconductor Solutions Corporation |
| ROHM Semiconductor |
| Kyocera Corporation |
| Mitsubishi Electric Corporation |
| Panasonic Holdings Corporation |
| NXP Semiconductors NV |
| Sharp Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive fab ownership by integrated device manufacturers anchors both supply security and pricing power in Japan's consumer semiconductor market, with METI subsidy-conditioned local 300mm commitments creating procurement access tiers that foreign competitors cannot match.
Pricing Analysis
Value-based pricing anchored to thermal cycling reliability and JIS electromagnetic compatibility certification separates premium mixed-signal controllers from commodity memory components. Price differentiation hinges on certification grade and volume scale, with Osaka-Nagoya appliance OEMs commanding standard-tier rates while Tokyo-based imaging specialists absorb premium positioning for stacked CMOS architectures. Cost compression in DRAM and NAND flash is intensifying because Korean suppliers undercut domestic pricing, eroding margin pools for commodity storage. Memory chip buyers exhibit highest price sensitivity, whereas health-monitoring wearable OEMs prioritize compliance-grade mixed-signal controllers over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Tokyo design centers specifying proprietary chip architectures for premium smartphones and cameras. Wafer fabrication draws from Taiwan, South Korea, and domestic Japanese facilities, with lithography and deposition equipment sourcing tethered to Dutch and American suppliers. Silicon wafers, photoresist materials, and specialty gases constitute critical input dependencies. Single-source vulnerability in extreme ultraviolet lithography systems exposes capacity expansion timelines to multilateral export control coordination. Distribution runs through certified domestic fab operators and technical support networks relocated to satisfy METI local content verification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's consumer semiconductor market operates as a vertical-integration race where captive 300mm fab capacity and JIS certification control determine procurement access, with upstream equipment and materials localization representing the decisive lever players are pursuing.
For Market Incumbents: Cement supply security through METI subsidy-conditioned domestic fab expansion in Kanto and Kansai corridors, while locking in long-term equipment service agreements with Dutch and American suppliers to mitigate export control volatility. Korean memory price erosion threatens commodity tier margins; respond by concentrating R&D resources on mixed-signal integration density that foreign competitors cannot replicate without JIS thermal cycling certification. For New Entrants and Emerging Players: Cloud-based design collaboration platforms offer the lowest-friction entry path into Tokyo-based OEM specification workflows, bypassing capital-intensive fab ownership requirements. White-space concentrates in health-monitoring sensor modules where PMDA oversight creates hybrid compliance barriers that established memory suppliers hesitate to cross. Target unbundled procurement contracts in Osaka-Nagoya manufacturing belts where appliance OEMs separate analog, digital, and sensor module sourcing. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-to-consumer crossover specialists with proven mixed-signal integration capabilities and verified domestic fab partnerships. Long-term viability over the projection horizon rests on securing positions in MEMS and logic segments that METI's current subsidy tranche prioritizes over memory expansion. Monitor whether METI's next capital allocation shifts equipment over materials funding, as that inflection would reshape which technology tiers receive procurement priority.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic 300mm Fab Commitment | METI subsidies condition funding on verified local capacity, compressing procurement lead times for Japanese OEMs. |
| JIS Certification Investment | Electromagnetic compatibility and thermal cycling thresholds create procurement friction against uncertified foreign competitors. |
| Mixed-Signal Integration Partnership | Renesas anchors automotive-to-consumer crossover through power management and infotainment bridge architectures. |
| Stacked CMOS Process Advancement | Sony Semiconductor Solutions commands premium smartphone and camera design wins through differentiated pixel density. |
| Equipment Localization Agreement | Dutch and American lithography suppliers relocate technical support to satisfy METI local content verification requirements. |
Research Methodology
Independent corroboration across semiconductor equipment vendor disclosures, METI subsidy framework documentation, and JIS certification registry records underwrites the qualitative findings in this analysis. Primary interviews with fab operations executives, mixed-signal design architects, and OEM procurement managers in Kanto and Kansai corridors combined with secondary validation from SEC filings, customs trade data, and industry association production statistics. Bottom-up wafer capacity estimates and top-down consumer electronics shipment projections were cross-referenced to anchor segmentation splits.
Comparable-period anchoring to historical 200mm-to-300mm migration patterns and subsidy-conditioned investment cycles established the forecast window baseline. The analytical framework modeled product type, application, technology node, and end-user channel dimensions across the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis incorporating AI-enabled edge processing demand curves, health-monitoring wearable penetration assumptions, and domestic fab capacity commissioning schedules.
The model holds under sustained METI subsidy commitment and stable multilateral export control frameworks; deviation in equipment licensing timelines or memory price volatility would shift capacity expansion trajectories. Forecasts reflect documented assumptions regarding JIS certification adoption rates and OEM dual-sourcing behavior. Periodic stress-testing of base assumptions against equipment import dependency and Korean supplier pricing actions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
T-Con Board Market