
 Nosql Market | 2026-2036
Nosql Market Size, Share, and Industry Trends Forecast 2026-2036
Nosql Market Intelligence
Database licensing revenue is fragmenting between perpetual on-premise contracts and consumption-based cloud services. MongoDB leverages its document-oriented architecture to anchor enterprise developer ecosystems. Redis Labs competes through in-memory performance specialization for low-latency workloads. Couchbase sustains edge-to-cloud synchronization capabilities that differentiate its hybrid deployment positioning.
NoSQL databases employ non-relational data models that distribute storage across commodity server clusters using flexible schemas, JSON documents, wide-column stores, or graph relationships to handle unstructured and semi-structured data at scale. Their primary purpose centers on horizontal scalability for real-time web applications, IoT data ingestion, and personalized content delivery where relational table structures impose throughput constraints. Document databases lead adoption among developers building mobile and web applications requiring schema evolution without migration downtime. Cloud deployment models represent the fastest-expanding segment as enterprises shift operational overhead to managed services. Column-family stores occupy mature positions in telemetry and time-series analytics where write throughput dominates query patterns.
FCC guidelines on telecommunications data retention intersect with SEC recordkeeping rules to shape audit and compliance architectures for financial sector NoSQL implementations. GDPR and EU AI Act provisions on data minimization and automated decision-making are forcing European deployments toward region-specific instance isolation and encryption standards. Stakeholders must monitor evolving cross-border data transfer restrictions and their compounding effects on multi-cloud replication strategies.
Market Dynamics
Cloud migration mandates from EU data sovereignty rules are accelerating database modernization cycles across enterprises, forcing infrastructure teams to re-architect data platforms around region-specific instance isolation and encryption standards that fragment traditional centralized deployments.
Growth Catalysts
- EU AI Act data minimization requirements:Automated decision-making provisions in European deployments are driving demand for flexible schema databases that enable rapid data purging and audit trails without structural downtime.
- Real-time fraud detection workloads:Financial services firms are expanding NoSQL deployments to process transaction streams at millisecond latency, replacing batch-oriented relational architectures that impose throughput constraints on anomaly detection pipelines.
- Hyperscaler infrastructure investments:United States-based cloud providers are building dedicated database-as-a-service regions that reduce operational overhead for enterprises migrating from self-managed on-premise clusters.
Market Restraints
- Specialized talent scarcity:Distributed systems engineering expertise required for sharding, replication tuning, and cluster orchestration commands salary premiums that inflate total cost of ownership beyond licensing fees.
- Input cost volatility in memory components:DRAM price fluctuations directly impact in-memory database operational economics, compressing margins for providers offering fixed-rate managed service contracts.
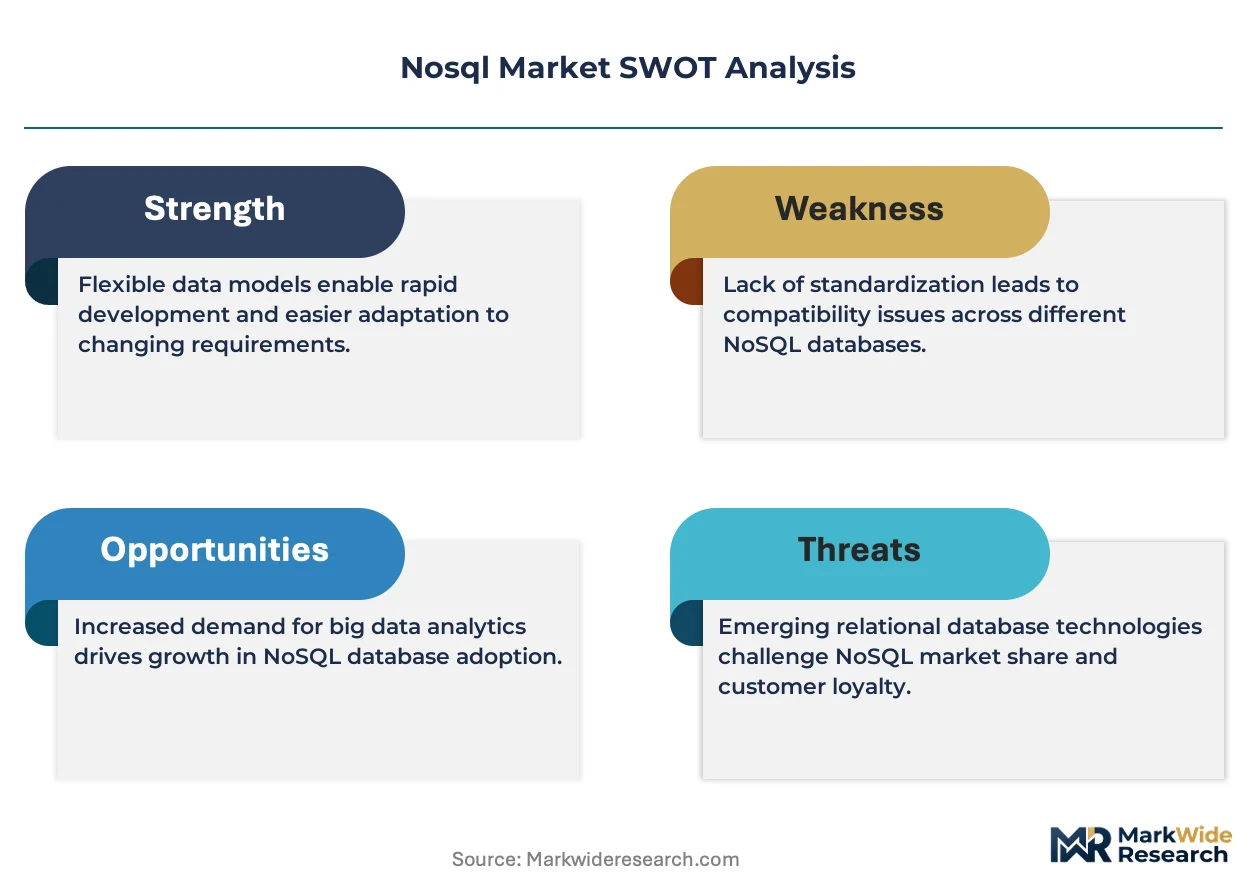
- Relational database substitution threat:PostgreSQL JSONB extensions and cloud-native relational services are recapturing workloads previously considered NoSQL-exclusive, particularly in applications with moderate scale requirements.
Strategic Opportunities
- Edge-to-cloud synchronization architectures:Manufacturing and logistics operators in Germany require database platforms that maintain consistency across factory floor deployments and central cloud analytics without continuous connectivity.
- India PLI scheme digital infrastructure:Production-linked incentive programs for electronics and semiconductor manufacturing are creating demand for localized database clusters that satisfy data residency requirements for multinational contract manufacturers.
- Convergence of vector search and document storage:Generative AI retrieval-augmented generation pipelines are driving integration of embedding indexes with JSON document databases, opening new workload categories beyond traditional operational data.
Industry Challenges
- Cross-functional skill gaps in platform engineering:Organizations struggle to hire teams that combine distributed database administration expertise with DevOps automation and security compliance knowledge.
- Multi-cloud replication complexity:Enterprises operating across AWS, Azure, and GCP regions face operational friction maintaining consistent replication topologies, backup policies, and failover procedures across incompatible managed service implementations.
- GDPR Article 17 erasure implementation:Right-to-be-forgotten compliance requires architectural modifications to distributed databases that were not originally designed for record-level deletion across eventually consistent replica sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nosql Market |
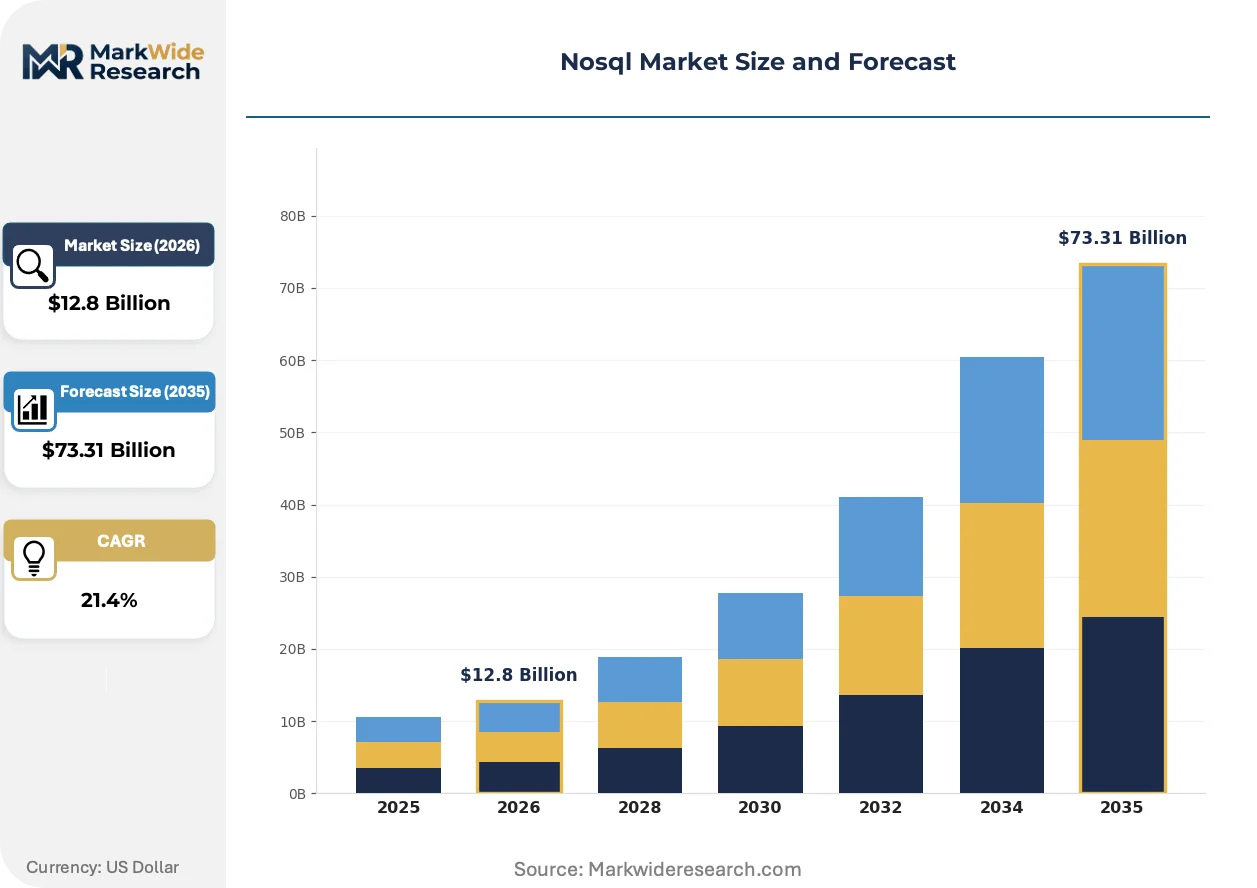
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $73.31 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Database Type: Document, Column-family, Key-value, Graph Deployment Model: On-premise, Cloud, Hybrid, Multi-cloud End User: IT, BFSI, Retail, Telecom Application: Data Analytics, Content Management, Real-time Data Processing, E-commerce |
| Companies Covered | MongoDB, Couchbase, DataStax, Amazon DynamoDB, Microsoft Azure Cosmos DB, Google Cloud Firestore, Redis Labs, Aerospike, ScyllaDB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nosql Market Strategic Shifts & Innovations
Database architectures are fragmenting around workload-specific optimization, with vendors racing to embed vector search, time-series compression, and graph traversal capabilities into unified platforms that reduce the need for specialized secondary systems.
Serverless database provisioning is collapsing the traditional capacity planning cycle for application teams. Developers at fintech startups and e-commerce operators are adopting pay-per-request pricing models that eliminate provisioned instance management. This shift is collapsing the barrier between prototype and production deployment, compressing time-to-market for data-intensive applications from quarters to weeks.
GDPR and the EU AI Act are mandating algorithmic accountability documentation that affects how training data pipelines interface with operational databases. European financial services regulators now require explainability traces for credit decisions sourced from customer profile databases. French and German banking consortia are responding by funding open-source query audit logging extensions that standardize compliance instrumentation across document and graph database engines.
Consumption-based pricing is displacing perpetual licensing in enterprise procurement cycles. Database buyers in United States healthcare and retail sectors are negotiating annual committed use contracts with burst allowance mechanisms rather than purchasing depreciating software assets. This behavioral shift is most visible among mid-market SaaS vendors who previously maintained dedicated database infrastructure teams and now prefer fully managed operational overhead transfer.
Nosql Market Segmentation
NoSQL segmentation reveals distinct procurement cycles across database architectures. Deployment models and end-user industries exhibit dramatically different technology refresh timelines. Understanding these velocity differences shapes vendor go-to-market and platform investment priorities.
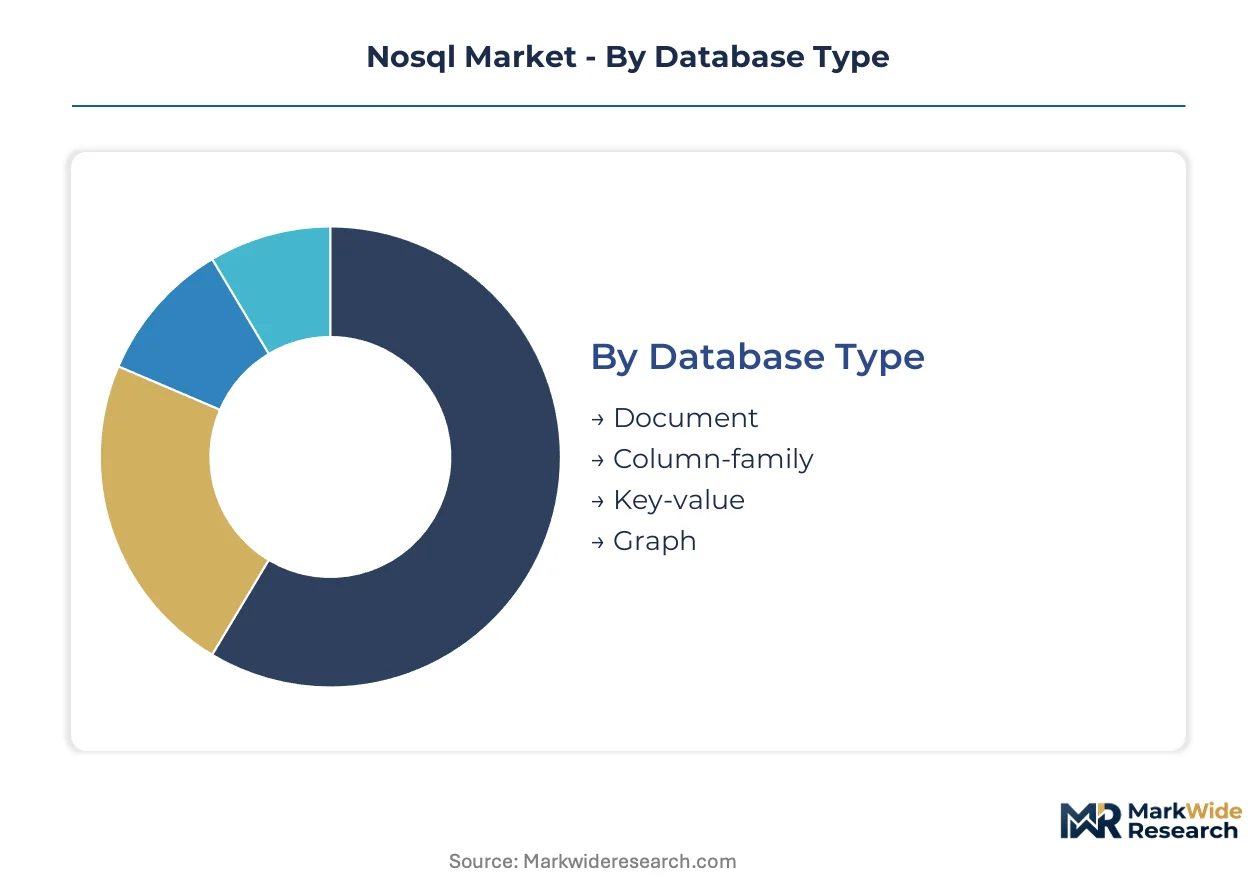
Database Type:
Document databases turn over fastest as mobile and web application teams iterate schemas weekly. Column-family stores refresh slowest, anchored in multi-year telemetry infrastructure contracts.
- Document:JSON-native storage with flexible schemas eliminates migration downtime for evolving application data models. Demand concentrates among United States fintech startups building real-time payment interfaces where developer velocity determines competitive position.
- Column-family:Wide-column structures optimize write throughput for time-series and telemetry workloads. German automotive manufacturers deploy these for connected vehicle data lakes where petabyte-scale ingestion dominates query patterns.
- Key-value:In-memory and persistent key-value stores deliver sub-millisecond latency for session management and caching tiers.
- Graph:Relationship-first storage traverses interconnected data for recommendation engines and fraud network detection.
Document databases dominate installed base. Column-family is where expansion concentrates.
Deployment Model:
Cloud deployments command premium pricing through operational overhead transfer. On-premise clusters retain cost tier positioning for regulated data sovereignty requirements.
- Cloud:Managed database-as-a-service provisions capacity on demand without infrastructure teams. United States healthcare SaaS vendors are migrating here to eliminate dedicated DBA headcount and redirect engineering toward application features.
- Hybrid:Edge-to-cloud synchronization maintains operational continuity across intermittent connectivity. French logistics operators require this for warehouse floor systems that sync with central analytics when network conditions permit.
- On-premise:Self-managed clusters persist where data residency mandates prohibit third-party infrastructure control.
- Multi-cloud:Replication across AWS, Azure, and GCP regions reduces vendor lock-in for enterprises with geographic diversification requirements.
Cloud deployments dominate installed base. Hybrid architectures are climbing the fastest as manufacturing digitalization accelerates.
End User:
BFSI procurement cycles run longest due to compliance validation stages. Retail refreshes fastest as seasonal demand drives infrastructure elasticity requirements.
- BFSI:Banking and financial services deploy NoSQL for real-time fraud detection and customer 360 profiles. United States regional banks are replacing batch-oriented relational systems with stream-processing document databases to meet SEC recordkeeping rules for audit trails.
- Retail:E-commerce platforms require elastic scaling for flash sales and personalized recommendation engines. Indian online marketplaces are driving demand for auto-sharding key-value stores that handle Diwali traffic spikes without provisioned capacity waste.
- IT:Technology vendors embed NoSQL in SaaS products and internal platform engineering.
- Telecom:Carriers store call detail records and network telemetry at massive scale under FCC data retention guidelines.
BFSI dominates installed base. Retail is gaining share fastest as omnichannel personalization investments intensify.
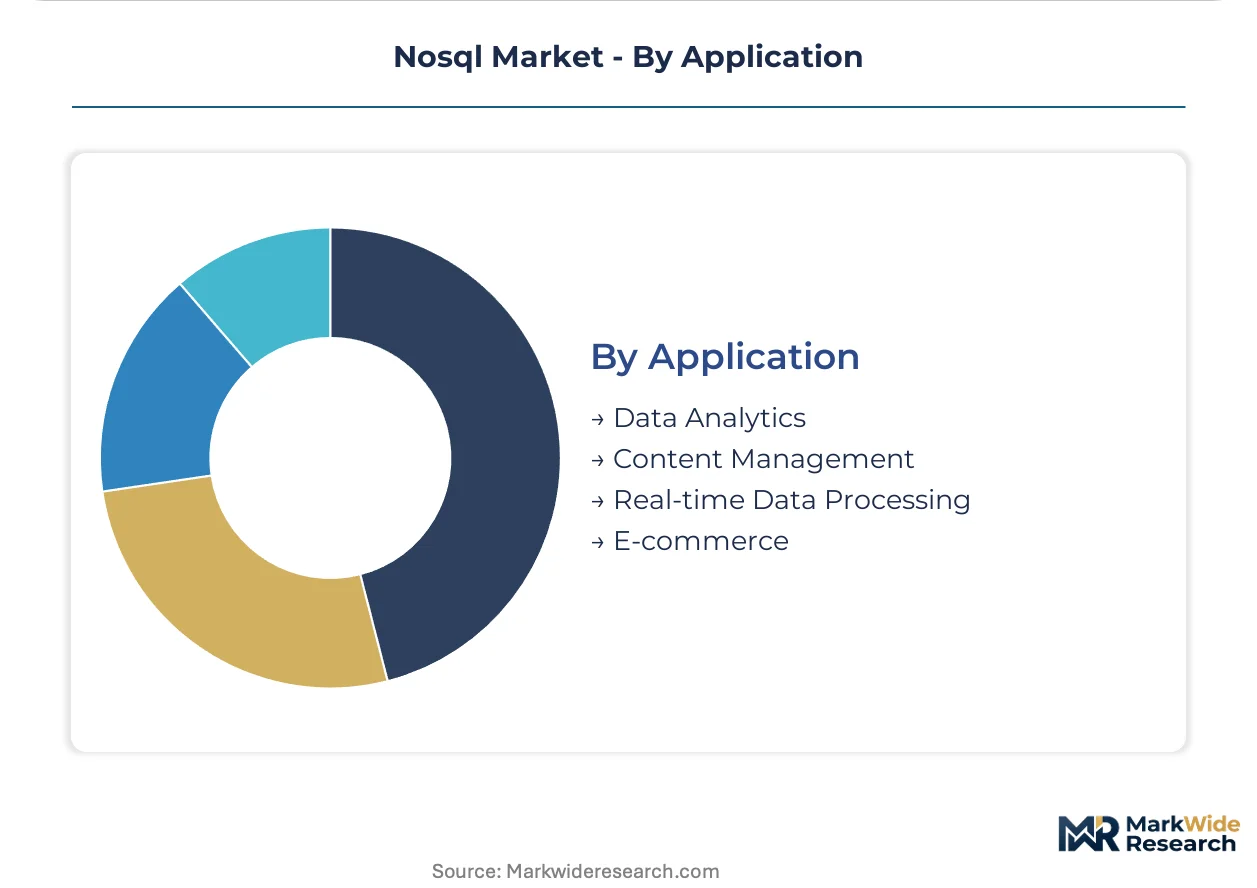
Application:
Real-time data processing commands highest performance premiums. Content management operates at lowest infrastructure intensity with longest replacement cycles.
- Real-time Data Processing:Stream ingestion and millisecond-latency query execution power fraud detection and IoT monitoring pipelines. German industrial operators pair this with edge computing for predictive maintenance on factory equipment.
- Data Analytics:Aggregation and exploration of unstructured datasets drives column-family and document store adoption. United States pharmaceutical researchers use these for genomic sequence analysis where schema flexibility accommodates evolving scientific ontologies.
- Content Management:Digital asset storage and delivery systems leverage document databases for metadata flexibility.
- E-commerce:Product catalogs, inventory, and shopping cart state management require consistent low-latency access patterns.
Data analytics dominates installed base. Real-time data processing shows the steepest expansion trajectory as operational intelligence investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises deploy NoSQL predominantly for real-time operational workloads, whereas German industrial operators prioritize edge-to-cloud synchronization for manufacturing continuity. Indian digital marketplaces drive demand for elastic auto-sharding architectures that handle seasonal traffic spikes.
United States
Hyperscaler infrastructure investments and fintech fraud detection pipelines dominate procurement. SEC recordkeeping rules for audit trails compel regional banks to migrate from batch relational systems to stream-processing document databases. Silicon Valley SaaS vendors anchor demand for serverless database-as-a-service provisions that eliminate dedicated DBA headcount.
Germany
Automotive telemetry data lakes and factory floor predictive maintenance systems require petabyte-scale column-family ingestion. GDPR Article 17 erasure mandates force architectural modifications to distributed replica sets for right-to-be-forgotten compliance. Bavarian manufacturing clusters drive edge-to-cloud hybrid deployments that maintain operational continuity across intermittent connectivity.
India
E-commerce flash sales and omnichannel personalization engines demand key-value stores with automatic sharding. PLI scheme digital infrastructure incentives for electronics manufacturing create localized database cluster requirements for multinational contract manufacturers. Bangalore and Hyderabad technology corridors concentrate developer talent for document database implementations.
United Kingdom
Financial services regulatory technology and open banking APIs accelerate document database adoption for customer 360 profiles. FCA operational resilience requirements intersect with GDPR data minimization provisions to shape compliance architectures. London fintech clusters prioritize managed service deployments that transfer operational overhead to cloud providers.
Japan
IoT data ingestion for connected vehicle platforms and retail personalization engines drives column-family and document store demand. METI data sovereignty guidelines influence multi-cloud replication strategies for enterprises with geographic diversification requirements. Tokyo-Osaka industrial corridors anchor manufacturing digitalization investments requiring hybrid database architectures.
Nosql Market Key Industry Players
Capability concentration sits with specialized document and in-memory database vendors; scale advantage sits with hyperscaler cloud platforms offering integrated managed services. The market structures around three tiers: pure-play database vendors, cloud-native platform extensions, and enterprise legacy modernization specialists. Dominant competitive moves include strategic partnerships embedding database engines into vertical SaaS stacks and geographic expansion of managed service regions to satisfy data residency mandates.
Within the pure-play tier, MongoDB and Redis Labs represent developer-centric positioning anchored in document flexibility and in-memory performance specialization respectively. Couchbase occupies a hybrid-deployment archetype emphasizing edge-to-cloud synchronization capabilities. Among hyperscaler offerings, Amazon DynamoDB and Microsoft Azure Cosmos DB exemplify scale-driven consolidation of operational database demand into cloud-native service catalogs.
| Leading Market Players |
|---|
| MongoDB |
| Couchbase |
| DataStax |
| Amazon DynamoDB |
| Microsoft Azure Cosmos DB |
| Google Cloud Firestore |
| Redis Labs |
| Aerospike |
| ScyllaDB |
| Others |
Cost & Logistics Intelligence
Undercapacity in DRAM fabrication facilities across South Korea and Taiwan is compressing margins for in-memory database providers while simultaneously elevating pricing power for cloud-managed service tiers that buffer end-users from component volatility.
Pricing Analysis
Consumption-based SaaS contracts with committed use allowances dominate enterprise procurement, displacing perpetual licensing arrangements. Pricing stratifies across premium managed services, standard self-hosted deployments, and economy-tier open-source support subscriptions. Cost compression in self-managed tiers is intensifying because hyperscaler infrastructure investments reduce operational overhead transfer premiums. Mid-market SaaS vendors exhibit highest price sensitivity, while financial services institutions prioritize compliance-grade SLAs over unit economics.
Supply Chain Analysis
Upstream feedstock in semiconductor memory components draws from concentrated fabrication capacity in South Korea, Taiwan, and the United States. DRAM wafer supply, NAND flash production, and advanced packaging services constitute critical input dependencies. Single-source vulnerability in EUV lithography equipment creates bottleneck exposure for cutting-edge node production. Distribution runs through hyperscaler cloud marketplaces and direct enterprise licensing channels with regional systems integrators providing deployment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workload-specific optimization is fragmenting database procurement, creating specialized niches for vector search, time-series compression, and edge synchronization capabilities that resist consolidation by generalist platforms.
For Market Incumbents: Harden multi-cloud replication orchestration to defend against hyperscaler lock-in strategies. Invest in region-specific managed service regions to satisfy EU data sovereignty mandates under GDPR and the EU AI Act. Deepen backward integration into vector indexing hardware to capture generative AI retrieval-augmented generation workloads.
For New Entrants and Emerging Players: Edge-to-cloud synchronization for German automotive manufacturing clusters represents the most penetrable entry point given intermittent connectivity requirements and incumbent gaps in factory floor deployment expertise. Target Indian PLI scheme electronics manufacturers with localized database clusters that satisfy data residency requirements for multinational contract manufacturers. Lead with consumption-based pricing to bypass entrenched procurement relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid-deployment specialists with proven edge synchronization capabilities and established manufacturing sector relationships. Long-term viability hinges on differentiation from hyperscaler commodity services through workload-specific optimization. Monitor hyperscaler capex disclosures for database-as-a-service region expansion signals indicating competitive intensity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Vector Search Integration | Embedding indexes in document databases capture generative AI retrieval-augmented generation pipelines. |
| Edge-to-Cloud Synchronization | Factory floor continuity capabilities differentiate platforms for German automotive telemetry workloads. |
| EU Region Expansion | GDPR Article 17 erasure compliance requires localized instance isolation and encryption standards. |
| Serverless Provisioning | Pay-per-request pricing eliminates capacity planning barriers for United States fintech startups. |
| Strategic Partnership Embedding | Vertical SaaS stack integration anchors developer ecosystems against hyperscaler consolidation. |
Research Approach
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. Platform engineering directors, distributed systems architects, cloud procurement officers, and compliance officers at financial services institutions provided operational perspective. SEC 10-K disclosures, hyperscaler capex reports, EU regulatory impact assessments, and customs trade data supplied external validation. Bottom-up deployment estimates triangulate against top-down market sizing from infrastructure spending trends.
Calibration against historical adoption curves and technology refresh cycles shapes the projection framework. Segmentation by database type, deployment model, end-user industry, and regional regulatory cluster drives granularity. CAGRs derive from fitted technology diffusion curves applied to infrastructure investment trajectories. Forecast inputs incorporate cloud migration velocity under EU data sovereignty rules and DRAM price elasticity for in-memory database economics.
Practitioners should monitor hyperscaler region expansion announcements and EU AI Act implementation guidance for early signals of competitive repositioning. Cross-checking against hyperscaler reported database revenue growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Data Center Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market