
 India Data Center Networking Market | 2026-2036
India Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Networking Market Insights
MeitY's Data Centre Policy is decoupling certification requirements from pure scale thresholds, allowing smaller facilities to qualify for infrastructure status. Cisco Systems Inc. leverages its installed base of enterprise routing to defend incumbency in tier-one cities. NVIDIA Corporation anchors high-performance interconnect demand through GPU-cluster networking designs. Dell Technologies Inc. competes across the full stack of server-switch integration for private cloud deployments.
Data center networking encompasses the switching, routing, and interconnect fabric that enables compute and storage resource communication within and between facilities, operating at speeds from 10 Gbps to 800 Gbps with latency budgets under microseconds for AI training clusters. The primary purpose is to maintain deterministic throughput for distributed workloads while minimizing packet loss during east-west traffic surges. Ethernet dominates the technology layer due to cost interoperability, though InfiniBand captures premium positions in GPU-centric AI factories where bandwidth density justifies protocol specialization. The deployment model dimension tilts toward colocation and hybrid architectures as enterprises defer capital intensity while retaining workload control. Load balancers and advanced firewalls concentrate margin pools at the edge where security and traffic engineering converge.
BIS certification requirements for telecom equipment, CDSCO-aligned data sovereignty expectations for health data hosting, and state-level single-window clearances under the Digital India framework collectively shape vendor qualification timelines and procurement specifications. CEA electrical safety standards further constrain power distribution design choices for facility operators. Stakeholders must monitor how state data localization rulings interact with central MeitY guidelines to anticipate compliance-driven refresh cycles.
Market Dynamics
Hyperscale cloud providers are consolidating rack deployment decisions around GPU-cluster density requirements, forcing switching fabric vendors to prioritize 800 Gbps backplane compatibility over incremental 400 Gbps refreshes in Mumbai and Hyderabad buildouts.
Growth Catalysts
- MeitY Data Centre Policy:Certification thresholds now accommodate smaller facilities, expanding the addressable base of infrastructure-status seekers beyond hyperscale operators.
- AI training clusters:GPU-intensive workloads in Maharashtra and Telangana are mandating sub-microsecond latency budgets that only advanced interconnect fabrics can satisfy.
- Submarine cable landings:Mumbai's concentration of international bandwidth entry points is anchoring domestic data gravity and cross-border peering demand.
Market Restraints
- Copper and optical component costs:Raw material volatility in transceiver manufacturing is compressing gross margins for switch vendors serving price-sensitive colocation operators.
- BIS certification timelines:Telecom equipment approval cycles are extending vendor qualification periods by six to nine months for new product introductions.
- Power infrastructure bottlenecks:CEA electrical safety standards are constraining rapid deployment of high-density racks in legacy facilities across tier-two cities.
Strategic Opportunities
- Edge computing nodes:Underpenetrated tier-three cities in Karnataka and Tamil Nadu present whitespace for micro-data center networking deployments.
- Convergence of silicon photonics with co-packaged optics:This pairing enables 51.2 Tbps switch capacity in thermally constrained environments.
- State-level single-window clearances:Digital India framework incentives in Gujarat and Uttar Pradesh are accelerating greenfield facility approvals.
Industry Challenges
- Optical networking specialization:Shortage of engineers proficient in 800 Gbps signal integrity and forward error correction implementation is throttling deployment velocity.
- Legacy Ethernet migration:Enterprises operating 10 Gbps/40 Gbps infrastructure face forklift upgrade costs and application revalidation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Networking Market |
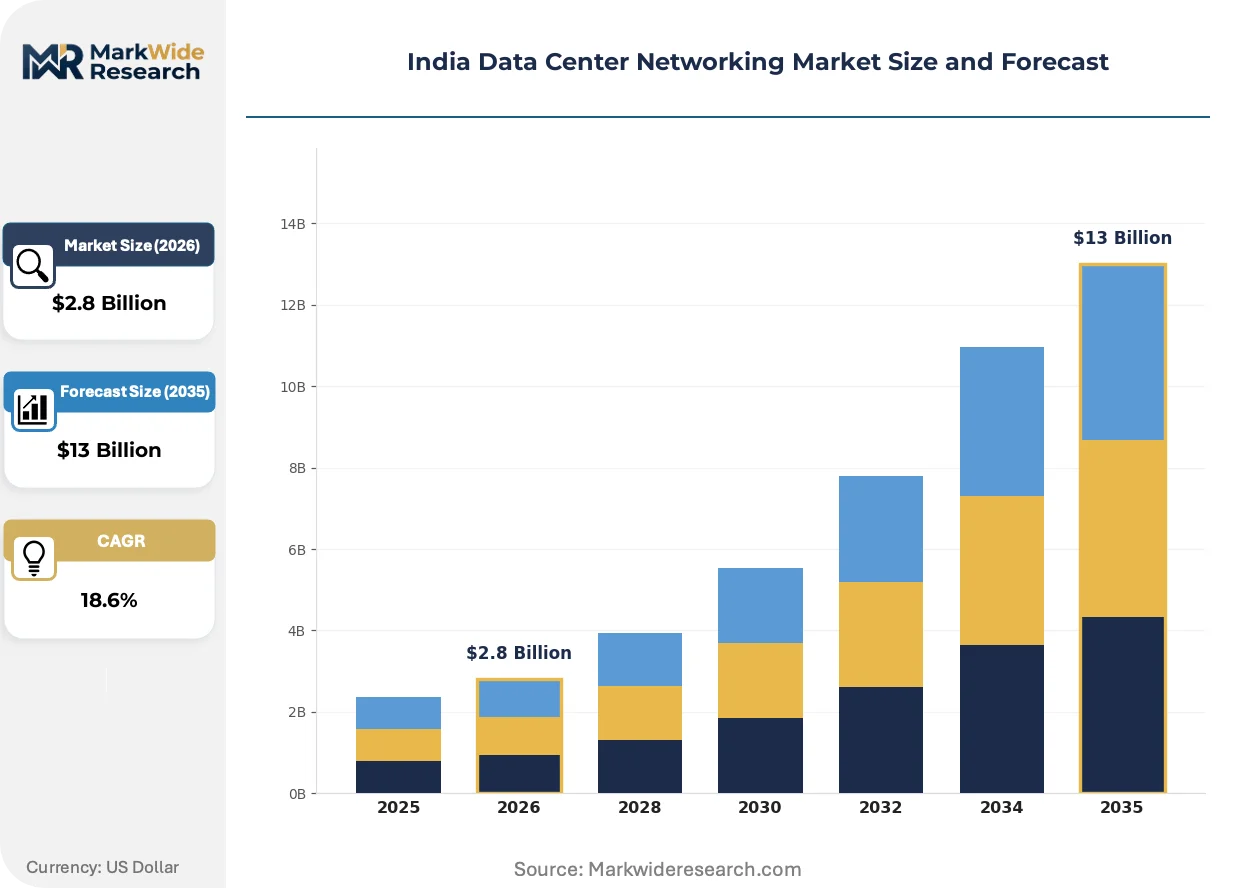
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Firewall, Load Balancer Technology: Ethernet, Fibre Channel, InfiniBand, SD-WAN Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Telecommunications, BFSI, Government, E-commerce |
| Companies Covered | Dell Technologies Inc., NVIDIA Corporation, Cisco Systems Inc., Adani ConneX, Sterlite Technologies, Juniper Networks Inc., Hewlett Packard Enterprise Company LP, Tejas Networks, Arista Networks Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Networking Market Trends and Innovations
Software-defined networking architectures are displacing hardware-centric control planes, while regulatory pressure on data sovereignty is forcing architectural decisions that prioritize domestic traffic routing over latency-optimized international paths.
SmartNICs and DPUs are decentralizing network function processing from centralized switches to server-attached accelerators. Hyperscale operators in Hyderabad are deploying these at rack scale to free CPU cycles for revenue-generating workloads. This shift is compressing traditional top-of-rack switching margins while expanding the addressable market for programmable silicon.
CDSCO-aligned data sovereignty expectations for health data hosting are mandating air-gapped network segmentation with dedicated encryption key management. Healthcare-focused colocation providers in Maharashtra are retrofitting facilities with hardware security module integration. This regulatory layer adds twelve to eighteen months to facility commissioning timelines.
Consumption-based networking procurement is replacing perpetual licensing for enterprise edge deployments. Mid-market manufacturers in Pune and Chennai are adopting subscription models for switch management and support. This behavioral shift is most visible in automotive and precision engineering verticals where capital allocation prioritizes operational expenditure treatment.
India Data Center Networking Market Segmentation
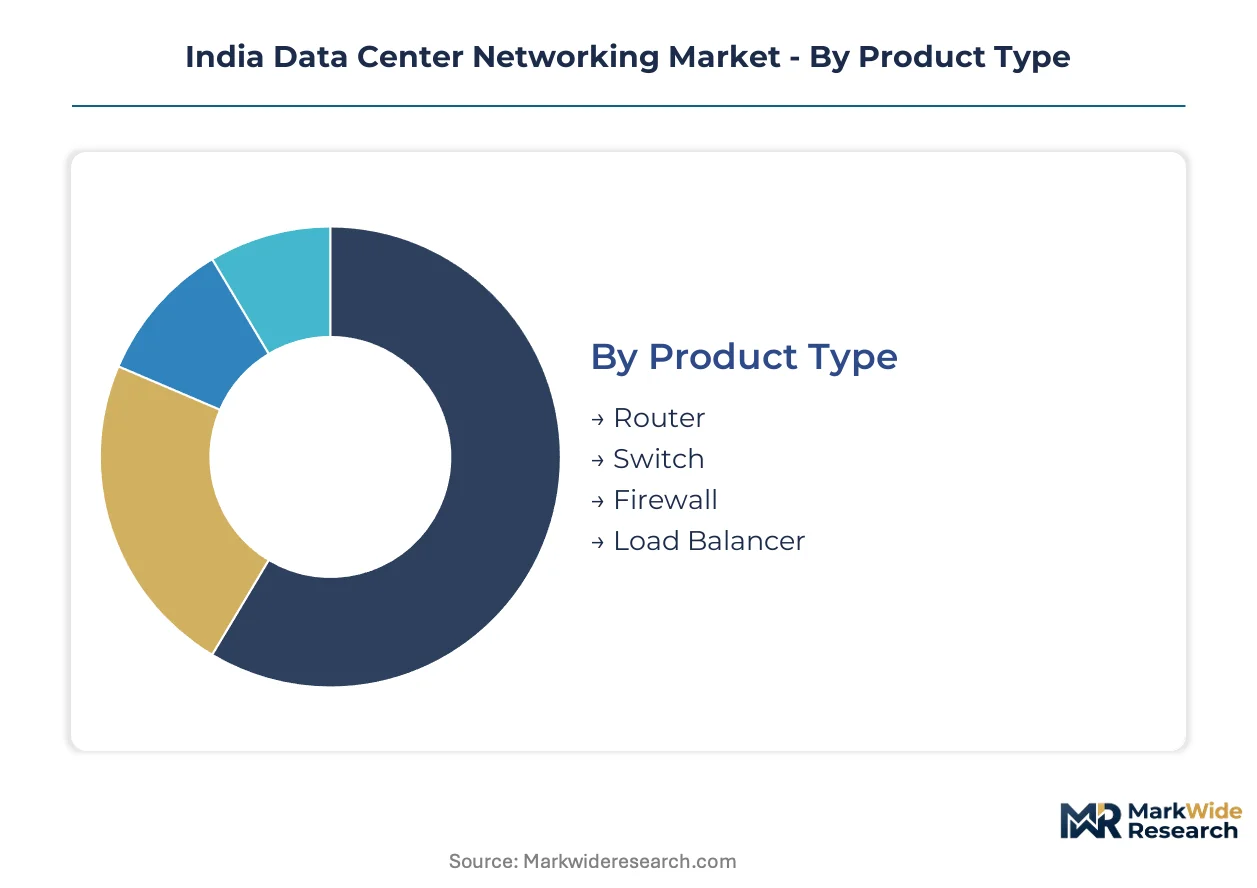
Segmentation in India's data center networking market reveals how capital allocation, workload density, and regulatory compliance intersect to shape procurement patterns across Maharashtra and Telangana's hyperscale corridors.
Product Type:
Switches command the highest upfront capital outlay per rack due to backplane density requirements and transceiver costs, while firewalls and load balancers concentrate margin pools at the edge.
- Router:Core routing infrastructure handles inter-facility traffic between Mumbai's submarine cable landings and Hyderabad's AI clusters. Telangana's GPU-intensive workloads are mandating 800 Gbps port densities that only next-generation chassis can satisfy.
- Switch:Top-of-rack and spine-leaf architectures dominate intra-facility east-west traffic. Maharashtra's colocation operators are standardizing on 400 Gbps access ports with 800 Gbps uplink readiness to accommodate hyperscale tenant demands.
- Firewall:Next-generation firewalls with hardware security module integration address CDSCO-aligned data sovereignty mandates for healthcare workloads.
- Load Balancer:Application delivery controllers optimize traffic distribution across distributed compute nodes in e-commerce and BFSI deployments.
Switching hardware absorbs the bulk of installed capacity; routers are expanding most quickly as inter-facility bandwidth requirements escalate.
Technology:
Protocol selection directly determines interoperability costs and thermal design constraints across India's tropical climate zones.
- Ethernet:Dominates cost-sensitive enterprise and colocation deployments through interoperable 25 Gbps to 400 Gbps standards. BFSI operators in Mumbai prefer Ethernet for its vendor diversity and replacement part availability.
- InfiniBand:Captures premium positioning in GPU-centric AI training clusters where sub-microsecond latency justifies protocol specialization. Hyderabad's hyperscale buildouts are mandating InfiniBand for inter-GPU communication fabrics.
- Fibre Channel:Persists in legacy storage area networks for government and telecommunications workloads with established FC investments.
- SD-WAN:Software-defined overlays enable hybrid connectivity for enterprises deferring on-premises capital intensity.
Ethernet commands the largest installed base; InfiniBand is climbing the fastest as AI cluster investments accelerate.
Deployment Model:
Capital deployment patterns reveal enterprise risk preferences between ownership control and operational flexibility.
- Colocation:Interconnection-heavy facilities in Mumbai's cable landing zones allow enterprises to access hyperscale peerings without facility ownership. Telangana's state incentives are attracting colocation operators to Hyderabad's greenfield corridors.
- Hybrid:Combines on-premises control for latency-sensitive workloads with cloud burst capacity for variable demand. E-commerce platforms in Maharashtra leverage hybrid architectures to manage festival-season traffic spikes.
- On-Premises:Government and defense installations mandate air-gapped infrastructure with BIS-certified equipment.
- Cloud-Based:Consumption models appeal to mid-market manufacturers in Pune and Chennai seeking operational expenditure treatment.
Colocation claims the dominant share of new capacity additions; hybrid deployments are gaining share fastest among regulated BFSI operators.
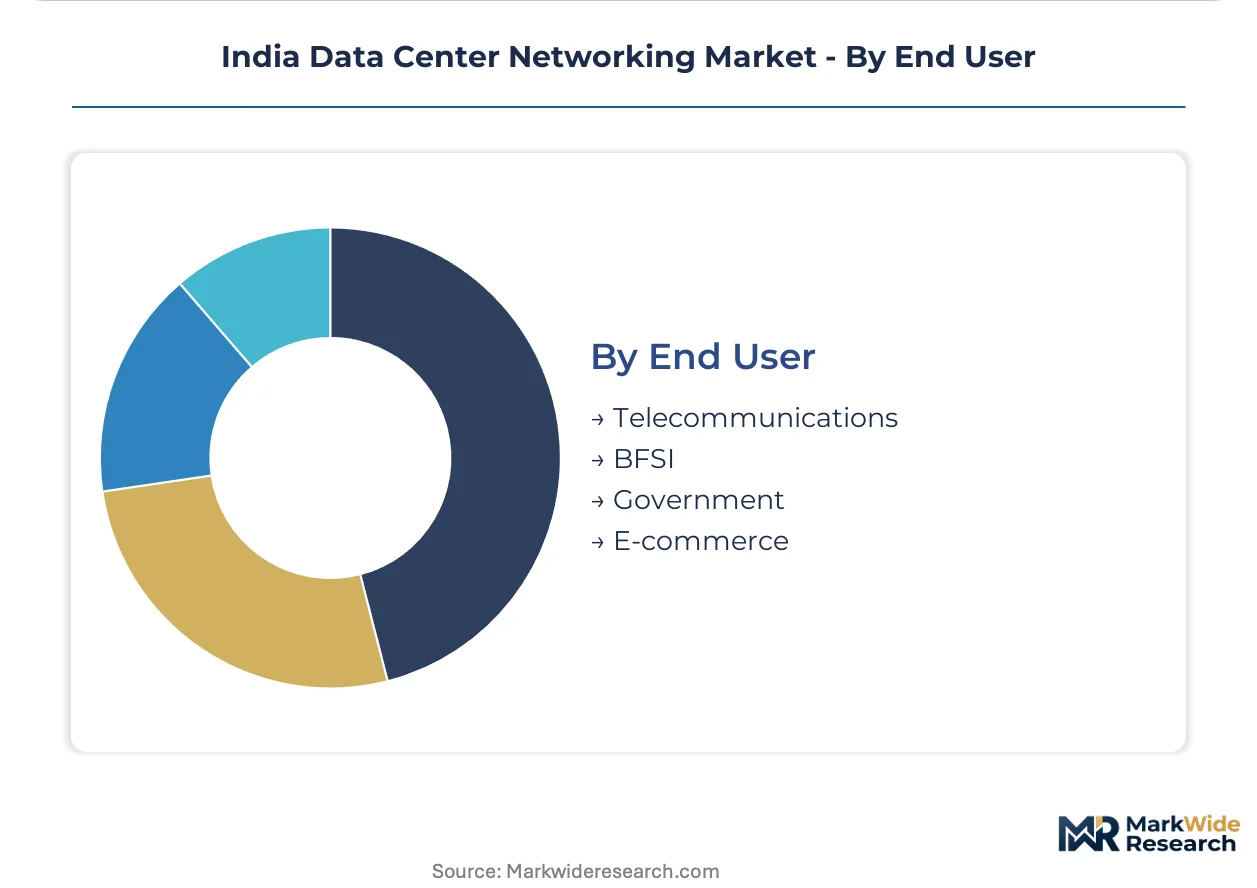
End User:
Vertical-specific compliance requirements and workload density profiles shape networking procurement specifications.
- Telecommunications:5G core deployments and edge computing nodes demand ultra-reliable low-latency switching. TRAI's infrastructure sharing mandates are concentrating networking investments in Maharashtra and Gujarat.
- BFSI:RBI's data localization directives require domestic transaction processing with dedicated encryption fabrics. Mumbai's financial district anchors high-frequency trading interconnect demand.
- Government:MeitY's certification requirements and CEA electrical standards constrain vendor qualification timelines for public sector tenders.
- E-commerce:Seasonal demand volatility favors elastic bandwidth provisioning through hybrid and colocation models.
Telecommunications holds the largest committed capacity; BFSI is expanding most quickly as digital payment volumes surge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Data Centre Policy incentives and Telangana's AI City designation are concentrating rack deployments in western and southern corridors. State-level single-window clearances under the Digital India framework are accelerating facility approvals in Gujarat and Tamil Nadu. Submarine cable landings in Mumbai anchor international bandwidth entry points that drive domestic data gravity.
Maharashtra
Mumbai's submarine cable landing stations attract hyperscale cloud providers seeking low-latency international connectivity. The state's Data Centre Policy offers power tariff subsidies and stamp duty exemptions for certified facilities. Navi Mumbai and Pune industrial corridors host the densest concentrations of colocation infrastructure serving BFSI and e-commerce workloads.
Telangana
Hyderabad's AI City initiative mandates GPU-cluster density requirements that force 800 Gbps switching fabric upgrades. The state electronics policy provides capital subsidies for data center equipment procurement. HITEC City and the upcoming Pharma City corridor are anchoring dedicated health data hosting facilities with CDSCO-aligned compliance architectures.
Gujarat
GIFT City's international financial services zone demands ultra-low latency connectivity for trading infrastructure. The state's single-window clearance mechanism compresses facility commissioning timelines by four to six months. Gandhinagar and Surat are emerging as secondary nodes for disaster recovery and backup capacity.
Karnataka
Bengaluru's concentration of SaaS enterprises drives hybrid cloud networking procurement with consumption-based licensing models. The state's startup policy extends data center infrastructure subsidies to registered technology parks. Whitefield and Electronic City corridors are retrofitting legacy facilities for AI training cluster compatibility.
Tamil Nadu
Chennai's undersea cable diversity and lower land costs attract hyperscale operators seeking Mumbai alternatives. The state's electronics manufacturing policy incentivizes domestic switch and router assembly. Sriperumbudur and Oragadam industrial zones are hosting greenfield facilities with CEA-compliant electrical safety architectures.
India Data Center Networking Market Competitive Landscape
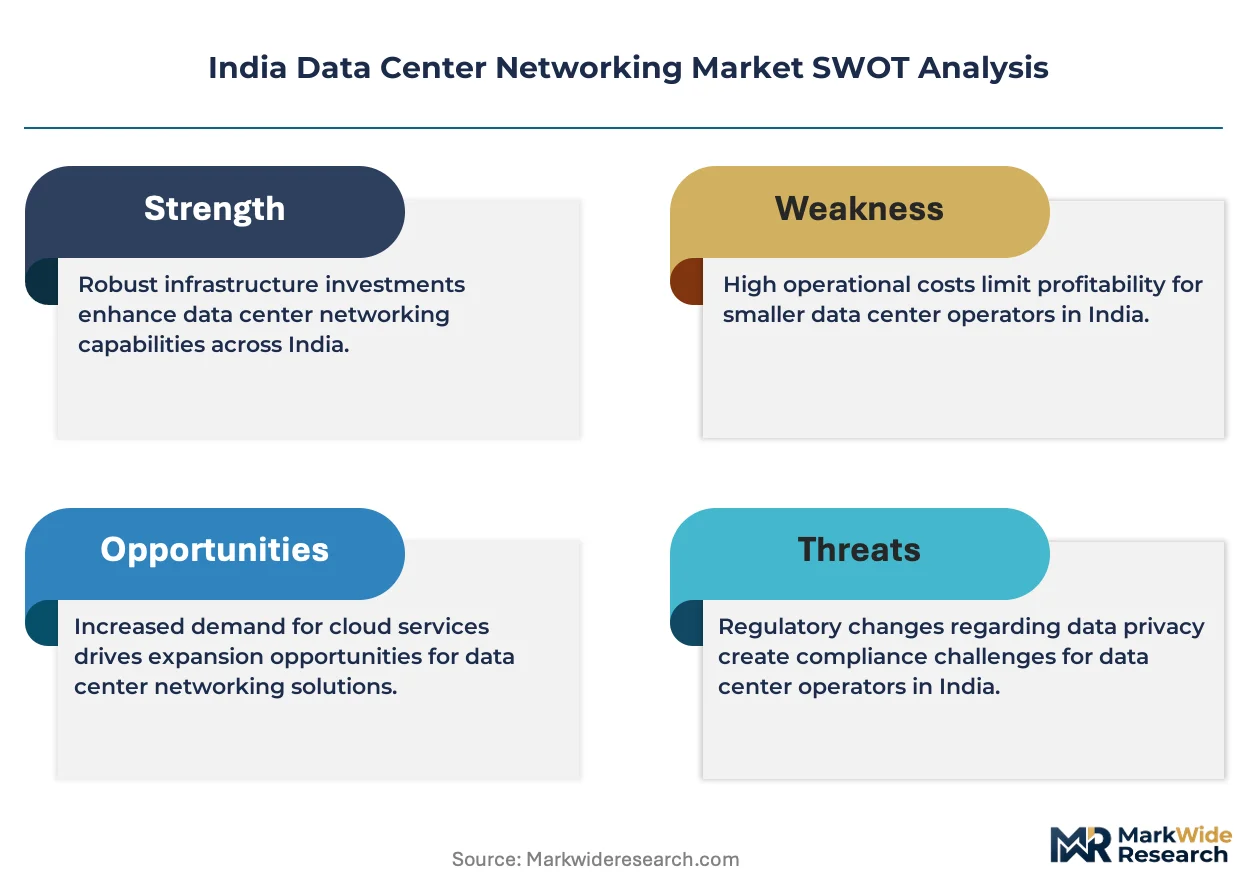
Diversified conglomerates compete with focused pure-play specialists across switching, routing, and interconnect fabric segments. The vendor base stratifies into three tiers: global networking incumbents with enterprise installed bases, domestic system integrators leveraging state policy incentives, and silicon-level specialists targeting GPU-cluster densities. Consolidation pressures intensify as hyperscale procurement centralizes around 800 Gbps compatibility requirements. Strategic partnerships between facility operators and equipment vendors are displacing transactional procurement relationships.
Within the diversified technology conglomerate tier, Dell Technologies Inc. and Cisco Systems Inc. exemplify full-stack integration strategies spanning server-switch-firewall portfolios. NVIDIA Corporation occupies a distinct position anchoring high-performance interconnect demand through GPU-centric fabric designs. These three entities represent contrasting archetypes: Dell Technologies Inc. competes across private cloud integration, Cisco Systems Inc. defends enterprise routing incumbency, and NVIDIA Corporation captures premium positioning in AI training clusters where InfiniBand specialization commands protocol-level differentiation.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| NVIDIA Corporation |
| Cisco Systems Inc. |
| Adani ConneX |
| Sterlite Technologies |
| Juniper Networks Inc. |
| Hewlett Packard Enterprise Company LP |
| Tejas Networks |
| Arista Networks Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive integration into optical transceiver manufacturing anchors both supply security and pricing power for Indian data center networking vendors, as BIS certification requirements and MeitY localization mandates force domestic assembly investments that compress margins for non-integrated players.
Pricing Analysis
Lead-time-driven pricing stratification separates hyperscale operators securing 800 Gbps switch allocations through twelve-month contracts from colocation providers purchasing spot-market 400 Gbps inventory at elevated premiums. Three-tier pricing structure across premium InfiniBand fabrics, standard Ethernet switching, and economy-grade legacy equipment reflects certification grade and volume scale differentials. Cost compression in the Ethernet tier is intensifying because optical component volatility feeds through to transceiver pricing. Colocation operators in Maharashtra exhibit the highest price sensitivity, while AI training cluster operators in Telangana prioritize latency performance over unit cost.
Supply Chain Analysis
BIS certification and CEA electrical safety qualification gating extends vendor onboarding timelines by six to nine months, concentrating supply relationships among incumbents with established testing protocols. Manufacturing draws from Taiwan for switch ASICs, China for optical transceivers, and Malaysia for passive components. Raw material dependencies span copper for signal integrity, gallium arsenide for laser diodes, and silicon substrates for co-packaged optics. Single-source vulnerability in 800 Gbps DSP chip supply threatens deployment velocity for Hyderabad AI clusters. Distribution runs through authorized distributors in Mumbai and direct procurement relationships with hyperscale facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's data center networking market sits in a technology-transition phase where 800 Gbps Ethernet and InfiniBand fabrics displace legacy 10 Gbps/40 Gbps infrastructure, compressing refresh cycles and redistributing vendor market share.
For Market Incumbents: Acquire programmable silicon IP to defend against SmartNIC and DPU disintermediation threatening traditional top-of-rack switching margins. Cisco Systems Inc. and Juniper Networks Inc. must deepen backward integration into co-packaged optics manufacturing to offset transceiver cost volatility, while accelerating BIS pre-certification for 51.2 Tbps switch platforms to maintain qualification advantages over emerging entrants.
For New Entrants and Emerging Players: Tier-three manufacturing clusters in Tamil Nadu and Karnataka present whitespace for micro-data center networking deployments underserved by hyperscale-focused incumbents. Tejas Networks and domestic system integrators should target state-level single-window clearance incentives in Gujarat and Uttar Pradesh for greenfield edge computing nodes, leveraging consumption-based procurement models to bypass capital-intensive perpetual licensing barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified technology conglomerates seeking full-stack data center integration. Long-term viability hinges on GPU-cluster density alignment and silicon photonics capability depth. The signal to monitor is InfiniBand penetration rates in Maharashtra and Telangana hyperscale buildouts as an inflection indicator for protocol-specialization premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Co-packaged optics enable 51.2 Tbps capacity in thermally constrained Mumbai facilities. |
| Backward Integration into Transceivers | Domestic optical assembly reduces BIS certification exposure and raw material volatility. |
| SmartNIC Platform Development | Server-attached accelerators displace centralized switching in Hyderabad GPU clusters. |
| State Incentive Leverage | Digital India single-window clearances in Gujarat compress facility commissioning timelines. |
| InfiniBand Specialization | Sub-microsecond latency fabrics capture premium positioning in Telangana AI training deployments. |
Research Methodology
Document review covered TRAI infrastructure reports, MeitY policy circulars, and hyperscaler capex disclosures, complemented by interviews with data center facility operators, network equipment procurement managers, and optical component distributors. Primary fieldwork engaged switching hardware engineers, colocation sales directors, and state electronics policy officers across Maharashtra, Telangana, Gujarat, and Tamil Nadu. Secondary validation drew from BIS certification databases, CEA electrical safety filings, and submarine cable landing records. Bottom-up rack deployment estimates triangulated against top-down infrastructure investment flows.
Segmentation outputs across product type, protocol technology, deployment model, and end-use vertical informed the analytical framework throughout the projection horizon. CAGRs were derived from facility commissioning timelines, equipment refresh cycles, and workload density trajectories. Model inputs incorporated GPU cluster expansion rates in Hyderabad, BFSI data localization compliance spend in Mumbai, and state incentive uptake velocities across the Digital India framework.
Revisions become necessary when BIS certification timelines extend materially, state data localization rulings diverge from central MeitY guidelines, or optical component supply disruptions exceed baseline volatility assumptions. A model refresh is warranted upon material change in hyperscale GPU cluster deployment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Data Center Networks Market