
 Denmark Data Center Networking Market | 2026-2036
Denmark Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Networking Market Insights
Shortage of fiber-optic technicians and network automation engineers is redrawing hiring patterns across Danish data center operations. Cisco Systems Inc. leverages its established Nordic training partnerships to sustain talent pipelines for switch deployment programs. Juniper Networks, Inc. anchors its Copenhagen presence through specialized routing expertise serving financial services clients. Arista Networks, Inc. differentiates by dominating high-frequency trading connectivity in Denmark's fintech hub.
Data center networking encompasses the interconnected hardware, protocols, and management systems enabling server-to-server, server-to-storage, and external connectivity within distributed computing facilities, typically operating at speeds from 10 Gbps to 800 Gbps with latency requirements below 10 microseconds for high-performance workloads. Its primary purpose is ensuring reliable, scalable data flow supporting cloud computing, artificial intelligence training clusters, and enterprise application hosting. Ethernet technology leads Danish deployments due to cost efficiency and interoperability, while InfiniBand captures premium segments serving AI and high-performance computing workloads where bandwidth density matters most. Cloud service providers represent the fastest-growing end user category as hyperscalers expand Nordic facilities to exploit Denmark's renewable energy profile and submarine cable connectivity.
The Danish Energy Agency enforces strict efficiency standards for data center power usage, directly shaping networking equipment procurement toward lower-consumption switch architectures and liquid-cooled rack designs. BIS certification requirements for imported telecommunications equipment create compliance checkpoints for non-EU vendors entering the Danish market. The EU AI Act and Denmark's national cybersecurity strategy impose escalating data governance obligations on network infrastructure operators. Stakeholders must monitor how forthcoming EU chip sovereignty initiatives and submarine cable security frameworks reshape supplier qualification criteria and capital allocation timelines.
Market Dynamics
Denmark's data center networking sector confronts a structural talent squeeze as fiber-optic technician shortages collide with hyperscale expansion timelines, forcing equipment vendors to reconfigure deployment support models around remote automation and compressed training cycles.
Growth Catalysts
- EU AI Act compliance deadlines:Danish financial services and pharmaceutical operators are accelerating network segmentation investments to meet algorithmic transparency mandates, directly lifting demand for programmable switch fabrics.
- Submarine cable landing concentration:Copenhagen's position as a Nordic interconnection hub draws colocation investment from cloud service providers seeking low-latency paths to continental Europe.
- Liquid cooling adoption:Heat density from AI training clusters is pushing rack-level thermal redesign, creating pull-through demand for networking hardware compatible with immersive cooling architectures.
Market Restraints
- Copper and silicon carbide input volatility:Switch ASIC foundry capacity constraints and raw material price swings compress gross margins for networking equipment vendors serving Danish deployments.
- BIS certification friction:Non-EU hardware manufacturers face extended approval timelines for telecommunications equipment imports, delaying procurement cycles for Odense corridor expansions.
- InfiniBand-Ethernet substitution pressure:Ultra-low-latency trading applications in Copenhagen's fintech cluster retain preference for InfiniBand, limiting Ethernet's addressable share in premium performance tiers.
Strategic Opportunities
- Greater Copenhagen edge nodes:Underpenetrated municipal and industrial edge locations outside the capital ring offer first-mover positioning for distributed networking infrastructure.
- EU Green Deal alignment:Denmark's national efficiency mandates for power usage effectiveness create regulatory tailwinds for vendors with verified low-consumption switch portfolios.
- Intent-based networking convergence:Integration of AI-driven network automation with existing SDN controllers opens white space for hybrid management platform deployment.
Industry Challenges
- Network automation engineer scarcity:Danish operations teams lack sufficient personnel fluent in Python-based orchestration and API-driven provisioning, extending deployment timelines.
- Legacy three-tier architecture integration:Spine-leaf fabric upgrades require complex migration planning for enterprises with entrenched core-aggregation-access designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Networking Market |
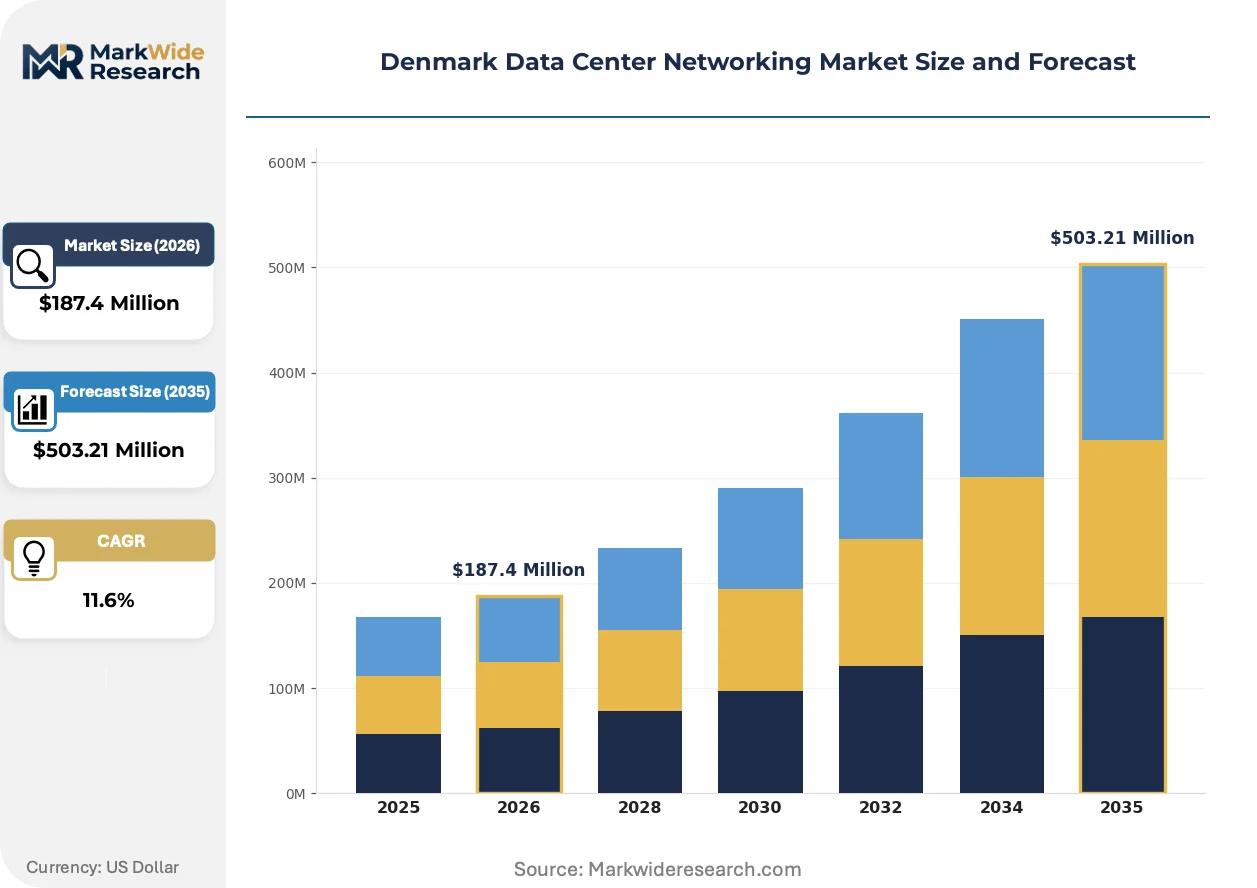
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Cables, Firewalls Technology: Ethernet, Fiber Channel, InfiniBand, MPLS End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Agencies Deployment Model: On-Premises, Hybrid, Cloud-Based, Virtualized |
| Companies Covered | Cisco Systems Inc., Juniper Networks, Inc., Arista Networks, Inc., Dell Inc., Huawei Technologies, Hewlett Packard Enterprise, Broadcom, VMware, Inc., Ericsson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Networking Market Trends and Innovations
Automation and sustainability mandates are restructuring how Danish data center operators specify, procure, and operate networking infrastructure. Three developments dominate current investment planning.
800G Ethernet optics are displacing 400G as the default spine-layer standard for new hyperscale builds. Cloud service providers in the Copenhagen area are standardizing on 800G DR8 and 2xFR4 transceivers for intra-facility links. This transition is compressing depreciation schedules for recently deployed 400G inventory and forcing colocation providers to accelerate refresh cycles to remain competitive.
The Danish Energy Agency's efficiency benchmarking requirements are tightening allowable power consumption thresholds for networking equipment. Operators must now document switch-level energy metrics under standardized load conditions. Financial services clients with ESG disclosure obligations are most affected, prioritizing vendors with third-party validated efficiency certifications.
Buying patterns among Danish enterprise data center operators are consolidating around integrated hardware-software bundles. Discrete procurement of switches and separate management licenses is giving way to subscription-based network-as-a-service arrangements. This shift is most visible among mid-market pharmaceutical and logistics firms in the Odense corridor seeking to reduce operational complexity.
Denmark Data Center Networking Market Segmentation
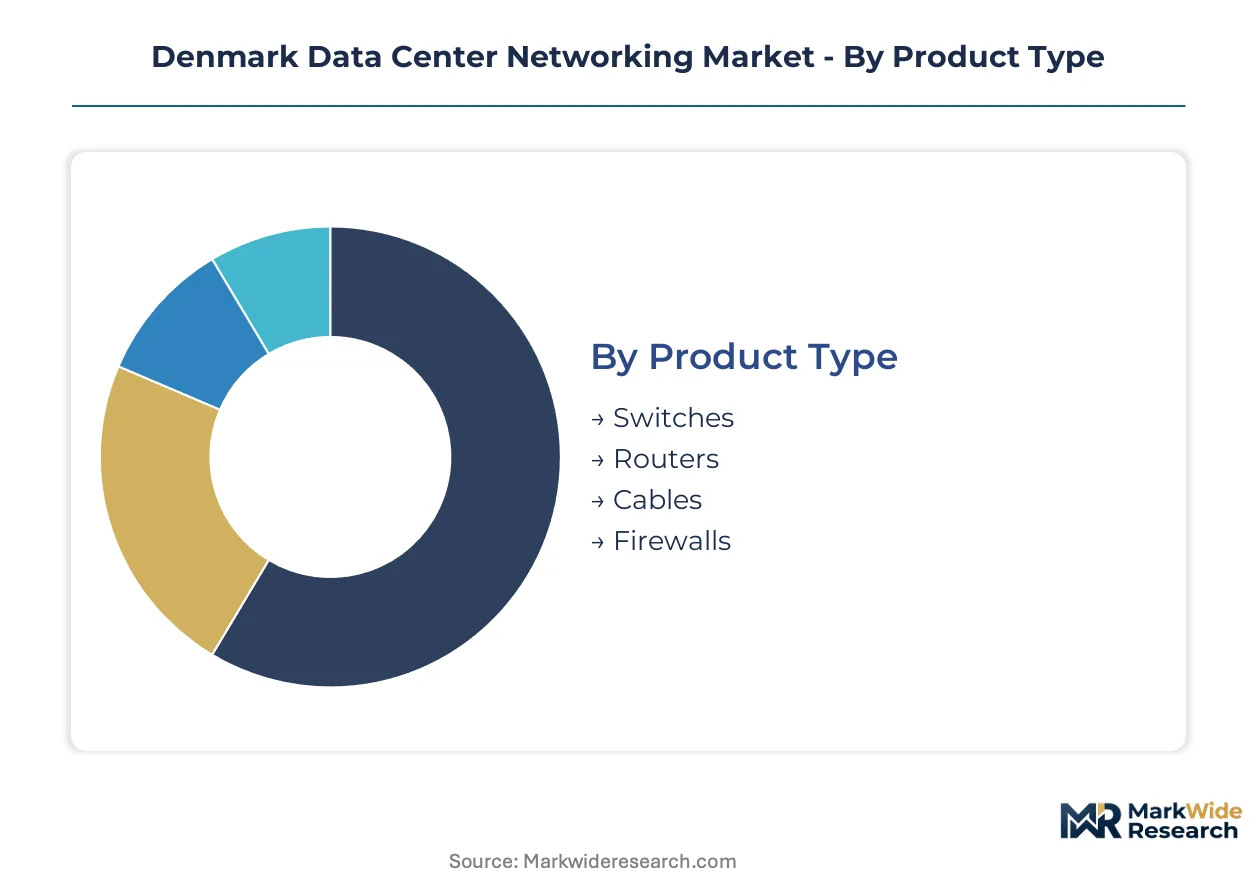
Segmentation reveals how Denmark's data center networking market fragments across competing connectivity paradigms. Each dimension carries distinct substitution risks and procurement logic that reshape vendor positioning.
Product Type:
InfiniBand-to-Ethernet substitution pressure weighs heaviest on router and switch categories as AI training clusters reconsider protocol choices for cost efficiency.
- Switches:Spine-leaf fabric switches dominate hyperscale builds in Copenhagen's colocation corridor. Danish cloud service providers prioritize 800G-capable models with liquid-cooling compatibility for AI cluster density.
- Routers:Border gateway and core aggregation platforms anchor submarine cable landing facilities. Financial services clients in the capital demand programmable routing silicon supporting EU AI Act compliance workflows.
- Cables:Active optical assemblies face pricing pressure from copper alternatives in short-reach applications.
- Firewalls:Next-generation platforms integrate zero-trust segmentation for Denmark's national cybersecurity strategy mandates.
Switches retain volume leadership; routers hold the steepest expansion curve as submarine cable investment accelerates.
Technology:
Cost tier differentiation separates commodity Ethernet from premium InfiniBand deployments across Danish facilities.
- Ethernet:Dominates Danish deployments through cost efficiency and interoperability advantages. Cloud service providers in Greater Copenhagen standardize on 800G Ethernet for spine-layer connectivity to exploit Denmark's renewable energy profile.
- InfiniBand:Captures premium segments serving AI and high-performance computing workloads where bandwidth density matters most. Copenhagen's fintech cluster retains preference for ultra-low-latency InfiniBand in high-frequency trading connectivity.
- Fiber Channel:Serves legacy enterprise storage networks in Odense corridor pharmaceutical operations.
- MPLS:Persists in government agency networks requiring deterministic traffic engineering.
Ethernet commands volume leadership; InfiniBand maintains the steepest expansion trajectory as AI training clusters multiply.
End User:
Customer type determines procurement sophistication and contract structure across Danish networking infrastructure.
- Cloud Service Providers:Hyperscalers expanding Nordic facilities drive fastest demand growth. Copenhagen-area builds prioritize submarine cable proximity and renewable energy access for sustainability commitments.
- Colocation Providers:Greater Copenhagen and Odense corridor operators invest in spine-leaf upgrades to attract international tenants. BIS certification requirements for imported equipment complicate procurement timelines for facility expansions.
- Enterprises:Pharmaceutical and logistics firms in the Odense corridor consolidate around subscription-based network-as-a-service arrangements.
- Government Agencies:National cybersecurity strategy compliance shapes classified network segmentation investments.
Cloud service providers retain volume leadership; colocation providers hold the steepest expansion curve as international connectivity demand intensifies.
Deployment Model:
Application criticality and data sovereignty requirements segment Danish operators across infrastructure ownership models.
- On-Premises:Financial services and pharmaceutical operators maintain captive facilities for algorithmic transparency mandates under EU AI Act deadlines. Copenhagen banks prioritize programmable switch fabrics supporting audit-ready network segmentation.
- Hybrid:Mid-market enterprises balance latency-sensitive workloads on-premises with burst capacity in cloud. Odense corridor logistics firms favor this model for seasonal demand variation.
- Cloud-Based:Startups and digital-native firms consume networking as operational expenditure without capital deployment.
- Virtualized:Software-defined overlays enable rapid reconfiguration for DevOps teams in Danish fintech clusters.
Hybrid deployments retain volume leadership; on-premises holds the steepest expansion curve as compliance deadlines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish Energy Agency anchors Nordic data center policy through efficiency mandates that cascade across neighboring jurisdictions. Submarine cable landing concentration in Copenhagen creates interconnection demand that ripples through Scandinavian markets. Regulatory alignment around EU AI Act deadlines synchronizes infrastructure investment cycles across the region.
Sweden
Hyperscale cloud expansion in Stockholm and Luleå drives spine-leaf switch demand for AI training clusters. The Swedish Post and Telecom Authority enforces national cybersecurity frameworks that shape network segmentation procurement. Luleå's subarctic cooling advantage attracts international colocation investment requiring high-density networking hardware.
Norway
Renewable hydroelectric capacity powers data center growth around Oslo and Stavanger, lifting demand for energy-efficient switch architectures. The Norwegian Communications Authority implements telecommunications equipment certification parallel to BIS requirements. Bergen's emerging cable landing position draws submarine connectivity investment with associated routing infrastructure.
Germany
Frankfurt's status as continental Europe's interconnection hub creates backhaul demand that Danish facilities increasingly serve. The Federal Network Agency enforces critical infrastructure protection standards that influence cross-border network design. Hamburg's northern corridor hosts submarine cable terminations linking Danish and German digital infrastructure.
Netherlands
Amsterdam's AMS-IX peering ecosystem generates traffic volumes that Danish colocation providers capture through low-latency alternatives. The Netherlands Authority for Consumers and Markets oversees data center energy reporting requirements that inform Nordic efficiency benchmarking. Rotterdam's port zone hosts emerging edge computing nodes competing with Copenhagen-area deployments.
Finland
Helsinki's submarine cable connectivity to Asia creates complementary routing paths that Danish landing stations reinforce. The Finnish Transport and Communications Agency coordinates Nordic cybersecurity exercises that standardize network resilience expectations. Espoo's hyperscale concentration drives comparable liquid-cooling adoption patterns to Greater Copenhagen facilities.
Denmark Data Center Networking Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Denmark's data center networking structure. The upper tier commands procurement relationships with hyperscale cloud operators and submarine cable landing facilities. Specialist vendors occupy niches in high-frequency trading connectivity and AI cluster InfiniBand deployments. Competitive moves center on talent acquisition for network automation engineering and strategic partnerships with Danish colocation operators seeking bundled hardware-software solutions.
Within the integrated infrastructure tier, Cisco Systems Inc. and Juniper Networks, Inc. exemplify established Nordic presences leveraging training partnerships and routing expertise respectively. Arista Networks, Inc. occupies a distinct position serving latency-sensitive financial services applications in Copenhagen's fintech cluster. These three companies represent contrasting archetypes: broad portfolio incumbents, specialized routing specialists, and performance-optimized challengers. Their collective positioning illustrates how vendor selection in Denmark fragments across compliance requirements, performance tiers, and operational support capabilities.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks, Inc. |
| Arista Networks, Inc. |
| Dell Inc. |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Broadcom |
| VMware, Inc. |
| Ericsson |
| Others |
Pricing and Supply Chain Analysis
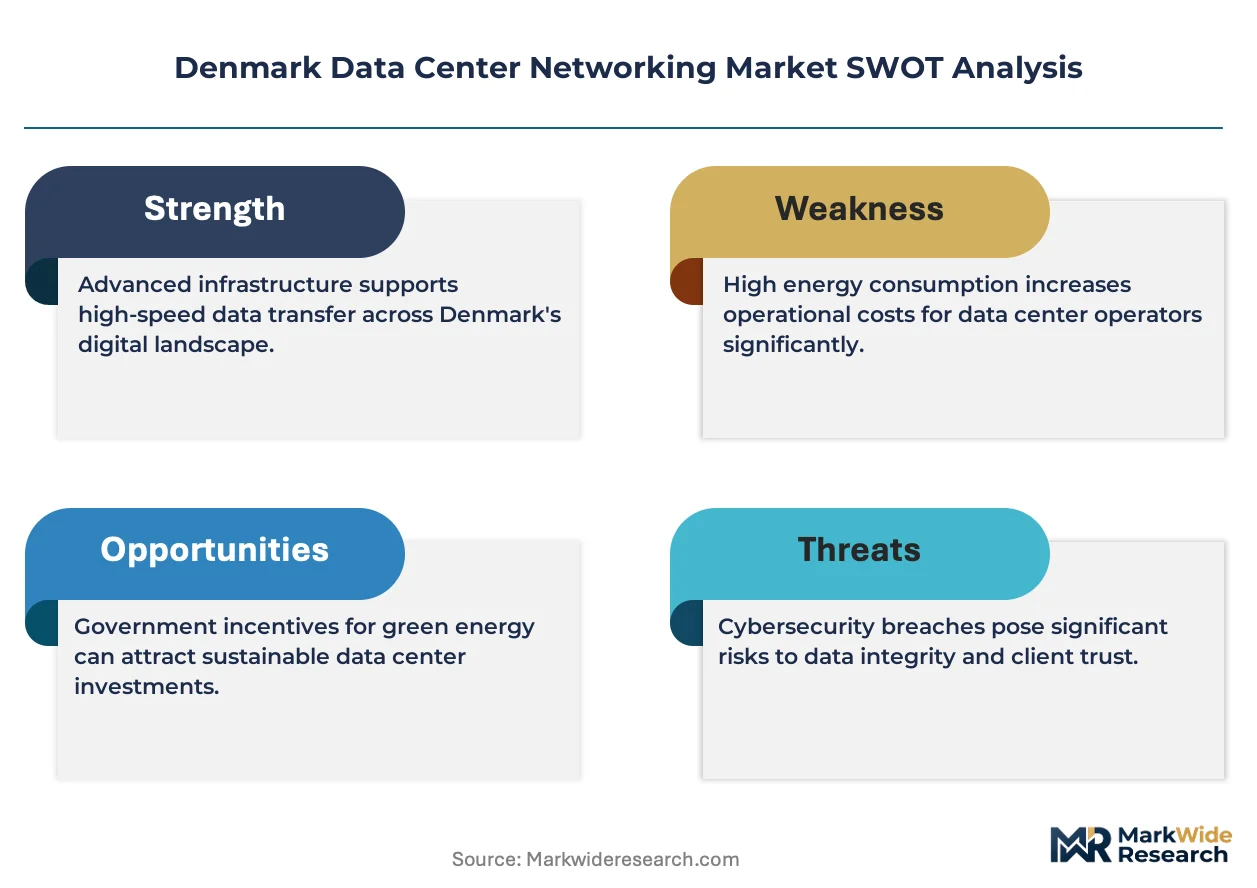
Hyperscale switch foundry utilization rates above 90 percent in Taiwan and South Korea compress procurement timelines for Danish cloud service providers while anchoring price floors for 800G Ethernet modules. This capacity concentration forces colocation operators in Greater Copenhagen to accept longer lead times or pay expedite premiums, reshaping total cost of ownership calculations for spine-leaf fabric upgrades.
Pricing Analysis
Copenhagen-area pricing for 800G optical transceivers runs 15-20 percent above Frankfurt equivalents due to BIS certification add-ons and lower shipment volumes into the Danish market. Three-tier pricing structure across premium InfiniBand, standard enterprise Ethernet, and economy-grade copper interconnects reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because Chinese vendors are bypassing traditional distribution channels to serve Odense corridor logistics firms directly. Cloud service providers exhibit the lowest price sensitivity due to sustainability-linked procurement mandates, while mid-market pharmaceutical enterprises in the hybrid deployment segment negotiate hardest on per-port licensing costs.
Supply Chain Analysis
Strategic stockpiling of switch ASICs and optical components dominates procurement behavior among Danish colocation providers confronting 26-week foundry lead times, displacing the just-in-time inventory models prevalent in software-defined networking procurement. Supply concentrates in Taiwan for merchant silicon, Malaysia for optical transceiver assembly, and China for copper cable harnesses. Raw material dependencies span silicon carbide substrates, rare-earth doped fiber, and high-purity copper. Single-source vulnerability around TSMC's 5nm switch chip production creates concentration risk for 800G spine-layer deployments. Distribution runs through Nordic value-added distributors with Copenhagen warehousing, supplemented by direct fulfillment from Juniper and Arista for hyperscale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's data center networking market sits in early-cycle expansion as 800G Ethernet refresh cycles and EU AI Act compliance deadlines drive replacement demand faster than historical norms. Penetration of intent-based networking platforms remains below 15 percent among mid-market enterprises, creating runway for automation-led value capture.
For Market Incumbents: Shield installed base relationships by embedding network automation engineers within Copenhagen-area colocation facilities, countering Arista's fintech specialization with localized support density. Accelerate backward integration into optical transceiver design to offset silicon carbide cost volatility and compress gross margin exposure. Prioritize BIS pre-certification for next-generation switch platforms to eliminate procurement friction in Odense corridor expansions.
For New Entrants and Emerging Players: Managed network-as-a-service offerings for pharmaceutical and logistics mid-market firms represent the most penetrable white space, as incumbents optimize for hyperscale account coverage. Target municipal edge nodes in Greater Copenhagen's outer ring where fiber density lags capital core demand. Lead with subscription-based pricing that bundles hardware, automation software, and compliance documentation to reduce operational complexity for ESG-constrained buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with proven liquid-cooling compatibility and AI cluster deployment experience over broad-portfolio generalists. Long-term viability hinges on 5-10 year runway for InfiniBand-to-Ethernet substitution capture in high-performance computing segments. The signal to watch is Danish Energy Agency efficiency threshold tightening, which would accelerate replacement demand for pre-2023 switch inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| 800G Spine-Leaf Deployment | Copenhagen hyperscalers standardize on 800G DR8 to support AI training cluster density requirements. |
| Liquid Cooling Compatibility Certification | Danish Energy Agency efficiency mandates pull through demand for immersion-ready switch hardware. |
| Intent-Based Networking Platform Launch | Python-based orchestration addresses automation engineer scarcity compressing deployment timelines. |
| BIS Pre-Certification Investment | Accelerated approval timelines unlock Odense corridor colocation expansion procurement cycles. |
| Network-as-a-Service Subscription Model | Mid-market pharmaceutical firms consolidate procurement to reduce operational complexity. |
Research Methodology
Desk research of submarine cable landing databases, Danish Energy Agency efficiency filings, and hyperscaler capex disclosures preceded structured interviews with data center operations directors, network automation engineers, colocation procurement managers, and optical component distributors. Primary fieldwork captured deployment timelines, certification friction points, and vendor selection criteria across Copenhagen and Odense corridor facilities. Secondary validation drew from EU AI Act implementation guidance, BIS telecommunications equipment standards, and Nordic trade flow data. Bottom-up equipment unit forecasts triangulated against top-down infrastructure investment projections.
Variance decomposition across technology substitution curves, regulatory compliance deadlines, and hyperscale expansion schedules shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, connectivity protocol, end-user category, and deployment model complexity. CAGRs derived from equipment replacement cycle analysis, capacity utilization trends, and energy efficiency mandate acceleration. Forecast inputs incorporated switch ASIC foundry capacity constraints and submarine cable landing investment pipelines.
Underlying assumptions cover sustained hyperscale Nordic expansion, stable BIS certification timelines, and copper-silicon carbide input price corridors, with deviation risk concentrated in foundry capacity allocation shifts and EU chip sovereignty initiative implementation. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when Danish Energy Agency efficiency thresholds tighten beyond modeled parameters or submarine cable landing investments stall.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Data Center Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Europe Data Center Networking Market