
 Taiwan Data Center Market | 2026-2036
Taiwan Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Market Insights
Hyperscale buyers is bifurcating Taiwan's data center demand away from traditional enterprise colocation. Chunghwa Telecom leverages its submarine cable landing stations and domestic fiber backbone to anchor wholesale capacity in northern Taiwan. Google competes through direct power purchase agreements and custom-built facilities optimized for AI tensor processing workloads. Chief Telecom differentiates by operating carrier-neutral interconnection hubs that bridge submarine networks with mainland China transit routes.
A data center constitutes a dedicated facility housing compute, storage, and networking infrastructure with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and power usage effectiveness ratios below 1.5 for new builds—designed to deliver continuous digital services for enterprises and cloud operators. Colocation services command the largest revenue share as multinational cloud providers seek certified facilities with dual-grid power and liquid cooling readiness. Edge computing deployments represent the fastest-growing deployment segment, driven by latency requirements for autonomous systems and smart manufacturing in Taichung and Tainan industrial zones.
Taiwan's National Communications Commission mandates cybersecurity compliance for critical information infrastructure, while the Bureau of Standards, Metrology and Inspection enforces energy efficiency codes under the Greenhouse Gas Reduction and Management Act. These frameworks compel operators to invest in redundant power architectures and low-carbon cooling systems as a condition of market access. Stakeholders must monitor evolving carbon intensity benchmarks and submarine cable routing decisions that reshape interconnection value across the Taiwan Strait corridor.
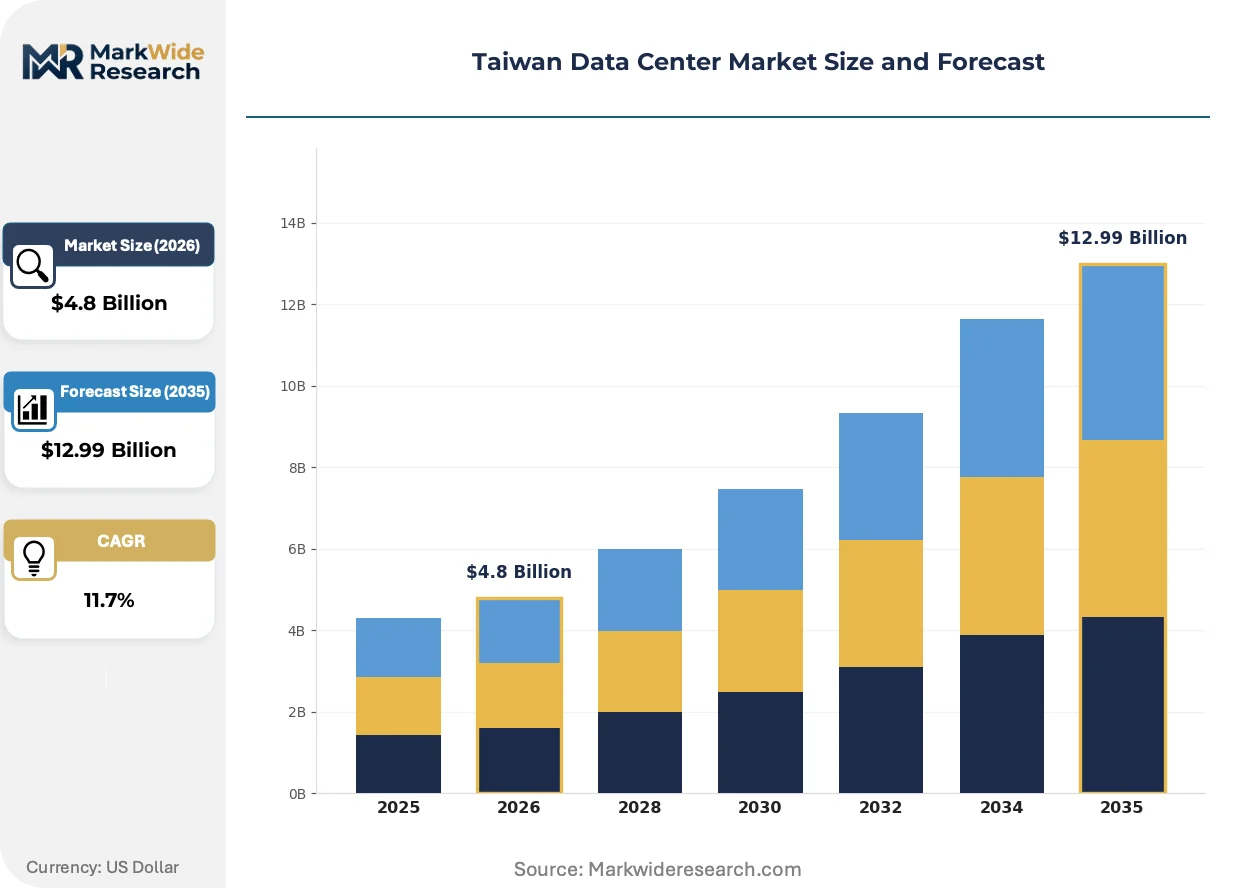
Market Dynamics
AI training workloads are concentrating demand in Taiwan's northern corridor, where submarine cable landings and semiconductor clusters create unique latency advantages for tensor processing infrastructure.
Growth Catalysts
- Greenhouse Gas Reduction and Management Act:Taiwan's Bureau of Standards, Metrology and Inspection mandates energy efficiency codes that accelerate adoption of liquid cooling and low-carbon power architectures in new facilities.
- Submarine cable convergence:Landing stations at Tamsui and Fangshan anchor interconnection density, drawing hyperscale operators seeking direct access to transpacific and intra-Asia fiber routes.
- Smart manufacturing latency requirements:Autonomous systems and industrial IoT deployments in Taichung and Tainan zones pull edge computing capacity into secondary metropolitan markets.
Market Restraints
- Land scarcity in Taipei corridor:Industrial zone availability constraints limit greenfield expansion for facilities exceeding 50MW capacity, compressing development timelines.
- Taiwan Strait geopolitical exposure:Submarine cable routing decisions and cross-strait transit dependencies create operational contingency risks for mainland China connectivity.
- Power grid density limitations:Taoyuan and New Taipei City substation capacity constraints require operators to secure dedicated high-voltage feeds years ahead of commissioning.
Strategic Opportunities
- Central Taiwan industrial zones:Taichung's precision machinery cluster remains underserved by tier-III facilities, opening whitespace for latency-sensitive manufacturing workloads.
- AI inference at the edge:Convergence of 5G radio access networks with micro data centers enables real-time model serving for autonomous vehicle testing in Tainan.
- Renewable energy certificates:Taiwan's offshore wind buildout allows operators to structure 24/7 carbon-free energy matching for sustainability-mandated enterprise buyers.
Industry Challenges
- Liquid cooling engineering talent:Specialized thermal design expertise for direct-to-chip and immersion systems remains concentrated among semiconductor equipment vendors, not facility operators.
- Dual-grid certification timelines:National Communications Commission cybersecurity compliance for critical infrastructure extends commissioning schedules by 8-14 months for first-time entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Interconnection End User: BFSI, Government, IT & Telecom, Healthcare Deployment: On-Premises, Off-Premises, Hybrid, Edge Computing Technology: Hyperconverged Infrastructure, Modular Data Centers, Cooling Solutions, Security Solutions |
| Companies Covered | Chunghwa Telecom, Chief Telecom, Vantage Data Centers, Amazon Web Services, Taiwan Mobile, Google, Equinix, NTT, Acer eDC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Market Trends and Innovations
Workload specialization is fragmenting facility design standards as AI training demands diverge from traditional enterprise colocation requirements across Taiwan's northern corridor.
Direct liquid cooling is decomposing conventional air-handling architectures in hyperscale deployments. Operators serving NVIDIA GPU clusters are adopting cold plate and immersion systems to manage 100kW+ rack densities. This thermal approach is decomposing the historical 1.5 PUE ceiling for new builds, enabling sustained power densities that air-cooled designs cannot support.
Taiwan's National Communications Commission cybersecurity mandates for critical information infrastructure are tightening facility certification requirements. Operators must demonstrate redundant power architectures and physical access controls to serve government and financial workloads. Northern Taiwan facilities are responding by segregating compliant zones within multi-tenant buildings.
Buyers are consolidating procurement around vertically integrated campus developments rather than incremental colocation leases. Cloud providers now prioritize single-operator control over power, cooling, and fiber interconnection. This preference shift concentrates contract value with developers holding contiguous land positions in Taoyuan and New Taipei City.
Taiwan Data Center Market Segmentation
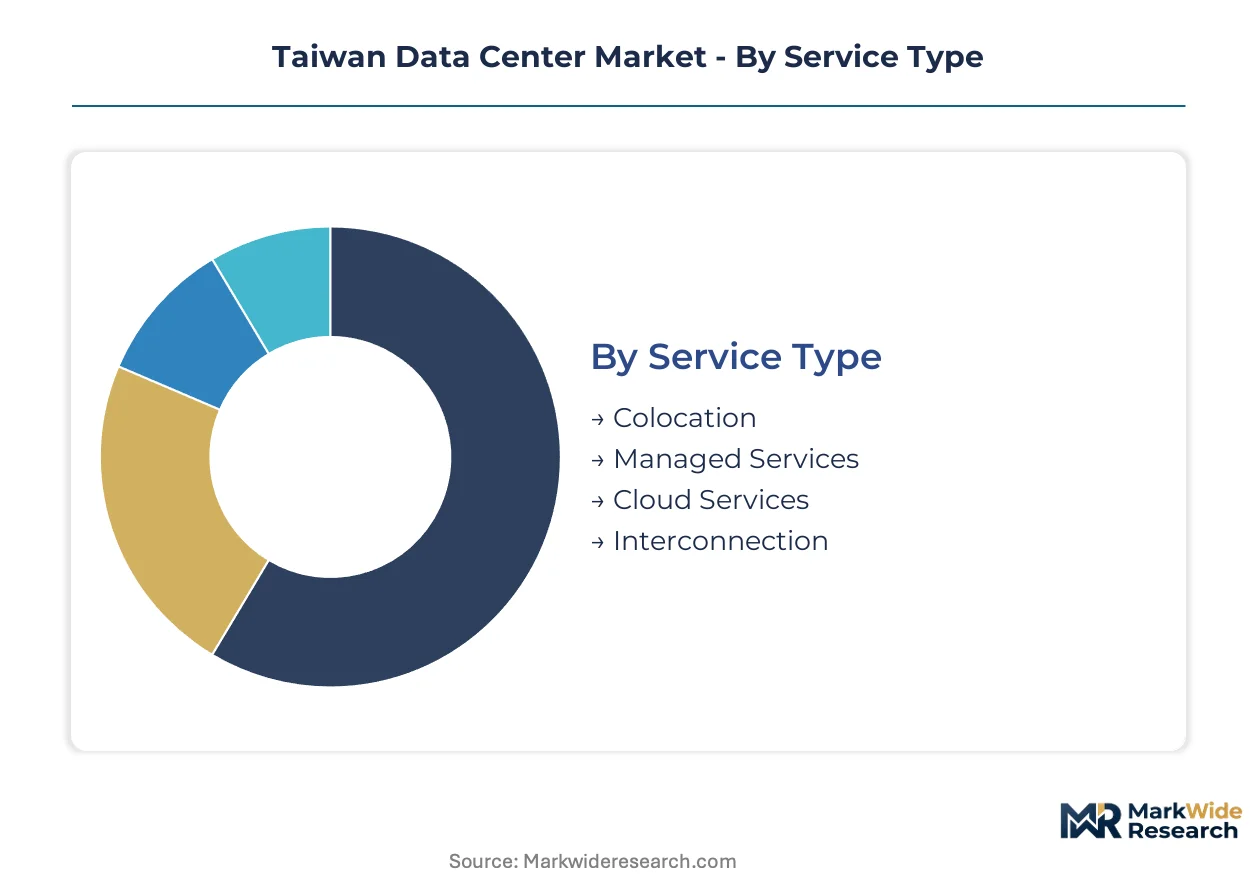
Segmentation in Taiwan's data center market reflects divergent compliance burdens and infrastructure requirements across buyer categories. National Communications Commission cybersecurity mandates and Bureau of Standards energy efficiency codes create tiered certification pathways that reshape procurement patterns.
Service Type:
National Communications Commission cybersecurity certification requirements for critical infrastructure create distinct service tiers based on compliance depth and redundancy architecture.
- Colocation:Wholesale and retail rack space provision with dual-grid power and liquid cooling readiness. Demand concentrates among multinational cloud providers seeking certified facilities in Taipei's metropolitan corridor, where submarine cable landings reduce latency for transpacific workloads.
- Managed Services:Remote hands, monitoring, and infrastructure management delivered by facility operators. Taichung's precision machinery cluster drives uptake as manufacturers outsource operational complexity to meet tight commissioning timelines.
- Cloud Services:Public and private cloud resource provisioning including compute, storage, and networking virtualization. Hyperscale operators are expanding capacity to serve artificial intelligence training workloads with direct power purchase agreements.
- Interconnection:Cross-connect and peering services bridging submarine networks with domestic fiber backbones. Chunghwa Telecom leverages its landing station assets to anchor wholesale capacity in northern Taiwan.
Colocation handles the majority of throughput; Interconnection is expanding most quickly as cross-strait transit routes reshape connectivity value.
End User:
Customer archetypes diverge sharply in their tolerance for commissioning delays and mandatory redundancy investments.
- BFSI:Banking, financial services, and insurance institutions requiring physical access controls and redundant power architectures. Taipei-based financial institutions drive demand for segregated compliant zones within multi-tenant buildings.
- Government:Central and municipal agencies subject to National Communications Commission critical information infrastructure designation. Extended certification timelines of 8-14 months compress vendor selection windows for first-time entrants.
- IT & Telecom:Technology vendors and telecommunications carriers operating their own infrastructure or reselling capacity. Chief Telecom's carrier-neutral hubs attract this segment seeking mainland China transit route access.
- Healthcare:Medical institutions and health information exchanges with data sovereignty requirements. Tainan's biomedical corridor generates emerging demand for edge computing deployments.
BFSI commands the highest compliance premiums; Healthcare is gaining share fastest as telemedicine infrastructure expands.
Deployment:
Physical location strategy reflects latency requirements against land scarcity constraints in the northern corridor.
- On-Premises:Enterprise-owned facilities constructed and operated by end users on their own real estate. Semiconductor fabrication clusters in Hsinchu maintain captive capacity for intellectual property protection.
- Off-Premises:Third-party data center space leased from colocation or wholesale providers. Land scarcity in Taipei corridor limits greenfield expansion for facilities exceeding 50MW capacity.
- Hybrid:Workload distribution across owned and leased infrastructure with orchestration layers. Smart manufacturing deployments in Taichung and Tainan industrial zones favor this model for flexibility.
- Edge Computing:Distributed micro data centers positioned for sub-10 millisecond latency requirements. Autonomous vehicle testing in Tainan and industrial IoT in Taichung pull capacity into secondary metropolitan markets.
Off-Premises absorbs the bulk of new capacity; Edge Computing shows the steepest expansion trajectory as 5G radio access networks converge with micro data centers.
Technology:
Infrastructure technology selection tracks power density trajectories and thermal management requirements.
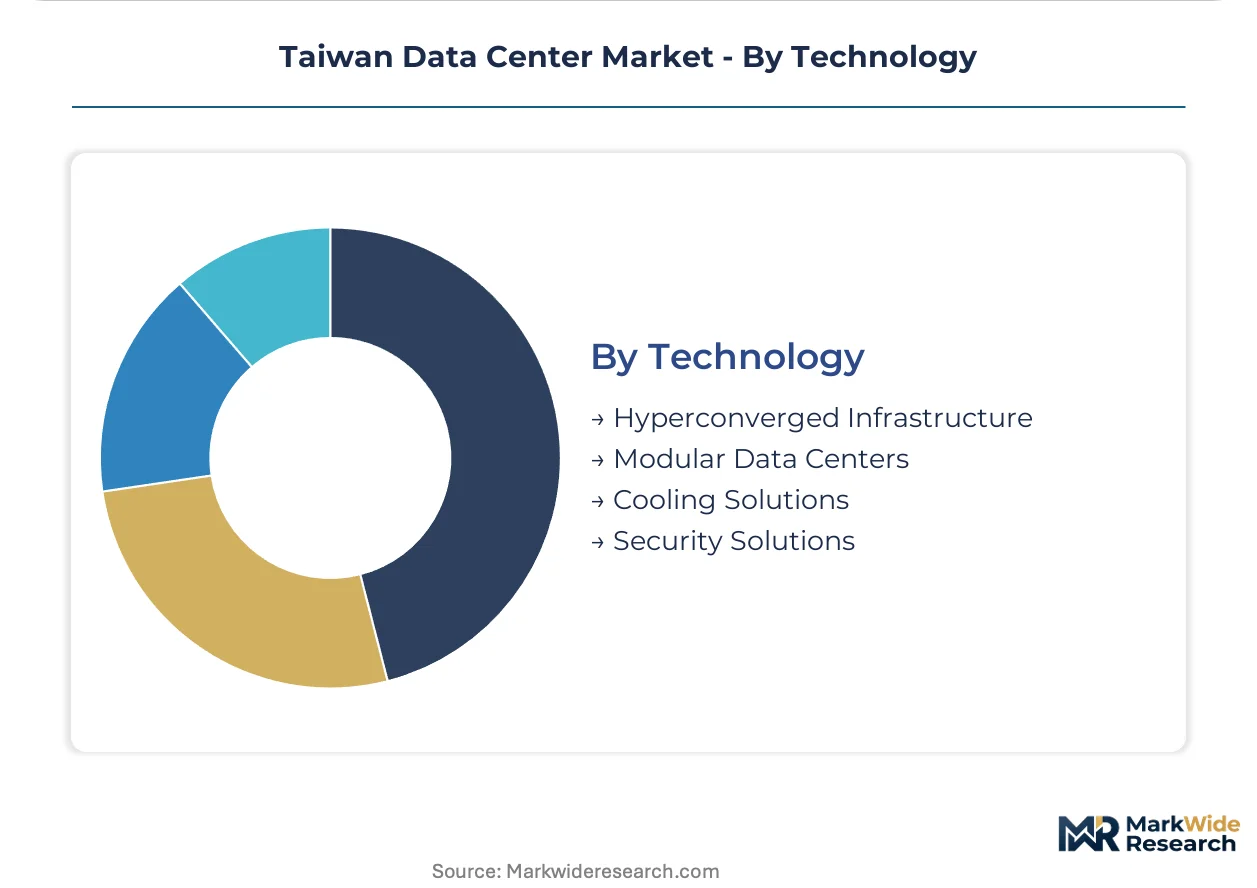
- Hyperconverged Infrastructure:Integrated compute, storage, and networking virtualization on commodity hardware. Enterprise buyers consolidate procurement around vertically integrated campus developments rather than incremental leases.
- Modular Data Centers:Prefabricated, containerized, or skid-mounted facility components enabling rapid deployment. Taoyuan and New Taipei City developers leverage contiguous land positions to offer single-operator control over power and cooling.
- Cooling Solutions:Direct liquid cooling, immersion systems, and advanced air-handling architectures. NVIDIA GPU clusters drive adoption of cold plate and immersion systems to manage 100kW+ rack densities, decomposing historical PUE ceilings.
- Security Solutions:Physical access control, biometric authentication, and network segmentation systems. National Communications Commission mandates compel operators to demonstrate redundant architectures for government and financial workloads.
Cooling Solutions attracts the most capital intensity; Modular Data Centers is climbing the fastest as compressed development timelines favor prefabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud providers and AI training workloads concentrate demand in Taiwan's northern corridor, where submarine cable landings and semiconductor fabrication clusters create latency advantages. The National Communications Commission enforces cybersecurity standards that reshape facility certification requirements across metropolitan zones. Bureau of Standards energy efficiency codes under the Greenhouse Gas Reduction and Management Act accelerate adoption of liquid cooling architectures.
Taipei Metropolitan Corridor
Hyperscale operators seek certified facilities with dual-grid power and liquid cooling readiness in this primary demand zone. The National Communications Commission mandates cybersecurity compliance for critical information infrastructure operators seeking market access. Tamsui and Fangshan submarine cable landing stations anchor interconnection density, drawing cloud providers requiring direct transpacific fiber access.
Taoyuan and New Taipei City
Land scarcity compresses development timelines for facilities exceeding 50MW capacity in this northern expansion zone. Bureau of Standards, Metrology and Inspection enforcement of energy efficiency codes compels investment in low-carbon cooling systems. Substation capacity constraints require operators to secure dedicated high-voltage feeds years ahead of commissioning, favoring developers with contiguous land positions.
Taichung Industrial Zone
Precision machinery clusters generate emerging demand for latency-sensitive manufacturing workloads in this central region. Smart manufacturing deployments favor hybrid infrastructure models combining owned and leased capacity for operational flexibility. The precision machinery cluster remains underserved by tier-III facilities, opening whitespace for edge computing deployments serving autonomous systems.
Tainan Biomedical Corridor
Telemedicine infrastructure expansion and autonomous vehicle testing pull edge computing capacity into this southern metropolitan market. 5G radio access network convergence with micro data centers enables real-time model serving for latency-critical applications. Biomedical data sovereignty requirements generate specialized demand for segregated compliant zones within multi-tenant facilities.
Hsinchu Science Park
Semiconductor fabrication clusters maintain captive data center capacity for intellectual property protection in this technology hub. Enterprise-owned facilities constructed on captive real estate serve proprietary workloads requiring physical security controls. The concentration of semiconductor equipment vendors creates localized expertise in direct-to-chip thermal management systems.
Taiwan Data Center Market Competitive Landscape
Player mix skews toward integrated telecommunications carriers with submarine cable assets and hyperscale cloud operators with direct power purchase capabilities. Market structure bifurcates between wholesale capacity providers anchoring northern Taiwan interconnection points and carrier-neutral specialists bridging cross-strait transit routes. Strategic archetypes include cable-anchored incumbents, AI-optimized hyperscalers, and mainland China connectivity specialists. Dominant competitive moves encompass direct renewable energy contracting and custom-built facility development for tensor processing workloads.
Within the telecommunications incumbent tier, Chunghwa Telecom leverages its submarine cable landing station assets and domestic fiber backbone to anchor wholesale capacity. Chief Telecom occupies a position bridging submarine networks with mainland China transit routes through carrier-neutral interconnection hubs. Google exemplifies the hyperscale operator archetype through direct power purchase agreements and custom-built facilities optimized for AI processing workloads.
| Leading Market Players |
|---|
| Chunghwa Telecom |
| Chief Telecom |
| Vantage Data Centers |
| Amazon Web Services |
| Taiwan Mobile |
| Equinix |
| NTT |
| Acer eDC |
| Others |
Pricing and Supply Chain Analysis
Megawatt-scale facility utilization rates above 85 percent compress unit economics for hyperscale operators while elevating price floors for smaller colocation providers lacking contiguous land banks in Taoyuan and New Taipei City. Taiwan's Bureau of Standards energy efficiency enforcement and National Communications Commission cybersecurity certification create tiered cost structures that propagate through contract pricing to enterprise buyers.
Pricing Analysis
Cost-plus contracts indexed to Taiwan Power Company industrial tariffs dominate wholesale agreements, with hyperscale operators securing 10-15 year terms against dedicated substation investments. Price differentiation separates Tier III certified facilities with dual-grid power from uncertified secondary sites, while liquid cooling readiness commands premiums for AI training workloads. Pricing pressure stems from land scarcity compressing development timelines and forcing accelerated depreciation schedules. Cloud providers exhibit lowest price sensitivity given direct power purchase capabilities; mid-market manufacturers in Taichung show highest sensitivity due to thin operational margins.
Supply Chain Analysis
Equipment lead times for 500kV transformers and immersion cooling systems now stretch 18-24 months, constraining facility commissioning schedules across northern Taiwan. Supply chains draw from China for electrical switchgear, Japan for precision cooling components, and the United States for hyperscale networking equipment. Single-source vulnerability concentrates in liquid cooling engineering talent pooled among Hsinchu semiconductor equipment vendors. Distribution runs through vertically integrated campus developers holding contiguous Taoyuan land positions rather than fragmented colocation leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
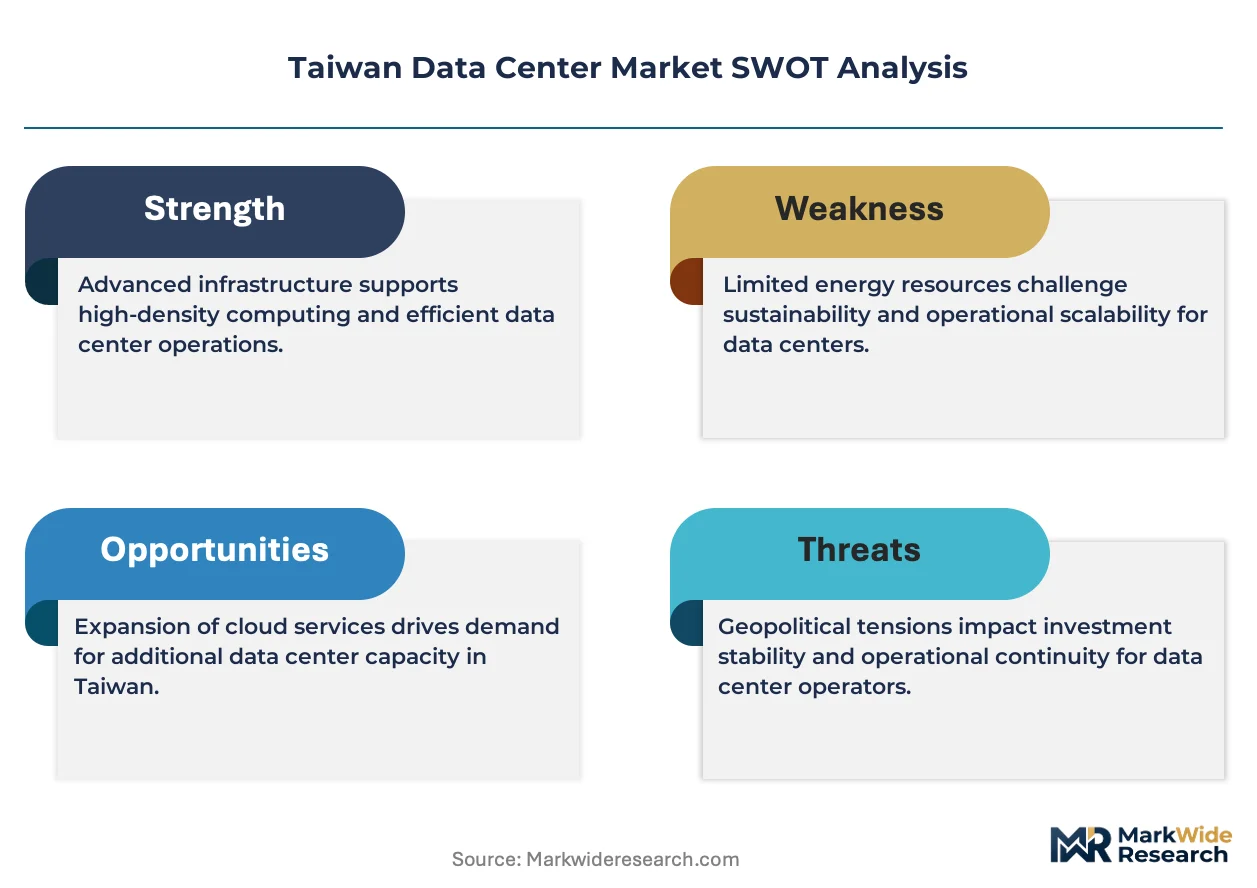
Taiwan's data center market sits at a platform-economics inflection where submarine cable landing access and renewable energy matching are becoming interoperable currencies for workload placement. The convergence of 5G edge requirements with AI inference demand is fragmenting procurement patterns away from centralized northern corridors.
For Market Incumbents: Consolidate carrier-neutral interconnection assets at Tamsui and Fangshan landing stations to defend against hyperscale bypass threats. Secure contiguous land banks in Taoyuan ahead of substation capacity releases to maintain pricing power. Invest in liquid cooling certification partnerships with Hsinchu semiconductor equipment vendors to address talent scarcity.
For New Entrants and Emerging Players: Lead with edge computing deployments in Taichung precision machinery clusters and Tainan biomedical corridors where tier-III facility whitespace remains. Target latency-sensitive manufacturing workloads unserved by northern hyperscale concentration. Structure go-to-market around hybrid infrastructure orchestration combining owned and leased capacity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carrier-neutral interconnection specialists bridging cross-strait transit routes. Long-term viability hinges on renewable energy certificate stacking capabilities aligned with Taiwan's offshore wind buildout. Monitor submarine cable routing decisions as inflection signals for interconnection value migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables 100kW+ rack densities for NVIDIA GPU clusters while decomposing historical PUE ceilings. |
| Submarine Cable Landing Station Expansion | Anchors interconnection density at Tamsui and Fangshan for transpacific fiber access. |
| Renewable Energy Certificate Stacking | Structures 24/7 carbon-free energy matching for sustainability-mandated enterprise buyers. |
| Edge Computing Micro Data Center Buildout | Serves sub-10 millisecond latency requirements for autonomous vehicle testing in Tainan. |
| Cybersecurity Certification Zone Segregation | Demonstrates redundant architectures for National Communications Commission compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across facility developers, hyperscale cloud procurement teams, and telecommunications infrastructure planners. Secondary validation drew from Bureau of Standards energy efficiency filings, National Communications Commission critical infrastructure designations, submarine cable development databases, and Taiwan Power Company grid interconnection records. Bottom-up capacity installation tracking and top-down cloud capex allocation analysis were triangulated to establish market sizing boundaries.
Across the analysis window, forecasts model service type segmentation alongside deployment model, end-user industry vertical, and regional metropolitan cluster dimensions. CAGRs were derived from capacity pipeline tracking against commissioning probability weightings. Industry-specific inputs include liquid cooling adoption curves tied to GPU cluster deployment schedules and renewable energy certificate market liquidity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Taiwan Strait cable routing stability or accelerated Bureau of Standards carbon intensity benchmarks would require recalibration. Forecasts reflect documented assumptions regarding hyperscale commitment timelines and edge computing latency requirement evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Philippines Data Center Rack Market