
 Data Center Services Market | 2026-2036
Data Center Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Services Market Analysis
Hyperscale-grade facility specifications are unwinding legacy Tier II and Tier III buildouts across major markets. Microsoft Azure leverages its global fiber backbone to sustain low-latency connectivity between cloud regions. Equinix anchors interconnection density in strategic metros, while Digital Realty dominates wholesale campus developments with scaled power allocations.
Data center services encompass the design, construction, leasing, operation, and maintenance of facilities that house compute, storage, and networking infrastructure, typically requiring redundant power systems, precision cooling, and sub-15 millisecond latency to edge nodes for real-time workloads. Cloud Services within the Service Type dimension leads revenue contribution as enterprises migrate transactional workloads away from owned infrastructure. Hybrid Cloud deployments across the Deployment Model dimension represent the fastest-expanding structural segment, reflecting buyer preference for workload portability between on-premises control and public elasticity. Security Management within the Management Level dimension commands premium pricing due to escalating ransomware exposure and compliance audit frequency.
EPA carbon reporting rules and OSHA electrical safety standards shape facility design and operational protocols for US-based providers, while the EU Energy Efficiency Directive and CE marking requirements govern European buildout specifications and equipment sourcing. NIST cybersecurity frameworks further constrain access architecture for operators serving federal workloads. Stakeholders must weigh sovereign data localization mandates against the capital efficiency of centralized mega-campuses when committing to multi-year capacity expansion plans.
Market Dynamics
Hyperscaler power density requirements are compressing legacy facility economics as liquid cooling infrastructure displaces traditional air-handling architectures across primary markets. Tier III specifications now face obsolescence pressure from 100kW-plus rack configurations demanded by GPU-intensive workloads.
Growth Catalysts
- Algorithmic Trading Latency Mandates:Financial services firms in Chicago and London are expanding colocation footprints to achieve sub-5 millisecond proximity to exchange matching engines. This demand concentrates in Northern Virginia and Frankfurt.
- EU Energy Efficiency Directive:Mandatory power usage effectiveness reporting for facilities above 500kW capacity is accelerating retrofit investments across European operators. Compliance deadlines compress upgrade timelines.
- Edge Computing Proliferation:Manufacturing automation and autonomous vehicle telemetry are forcing distributed micro-data center deployment within 50 kilometers of industrial clusters. Latency sensitivity now governs site selection.
Market Restraints
- Copper and Silicon Carbide Supply Concentration:Power distribution equipment depends on Chilean copper concentrate and Chinese silicon carbide substrates. Geopolitical friction threatens delivery reliability.
- Permitting Duration:Local zoning boards in Loudoun County and Amsterdam impose 18-24 month approval cycles for substation upgrades. Grid interconnection queues extend commissioning timelines.
- Skilled Electrical Technician Scarcity:Medium-voltage switchgear certification programs produce insufficient graduates to match construction velocity. Labor bottlenecks inflate installation costs.
Strategic Opportunities
- Saudi Arabia Giga-Project Pipeline:NEOM and Red Sea tourism developments require captive data infrastructure with renewable energy pairing. Sovereign wealth capital de-risks greenfield investment.
- Heat Reuse Integration:District heating networks in Copenhagen and Helsinki are contracting for waste heat offtake from hyperscale facilities. Revenue stacking improves project returns.
- NIST Cybersecurity Framework Compliance:Federal cloud procurement mandates are creating captive demand for FedRAMP-authorized facilities. Specialized security architecture commands rate premiums.
Industry Challenges
- Medium-Voltage Engineering Talent Pipeline:Retirement waves among 480V-34.5kV design specialists constrain quality assurance capacity. Training programs require 24-month certification cycles.
- Legacy DCIM Integration Complexity:Brownfield facilities operate fragmented building management systems that resist API standardization. Retrofit costs absorb 12-15% of modernization budgets.
- Water Scarcity in Arid Climates:Evaporative cooling dependence conflicts with drought conditions in Phoenix and Johannesburg. Alternative cooling architectures require re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Services Market |
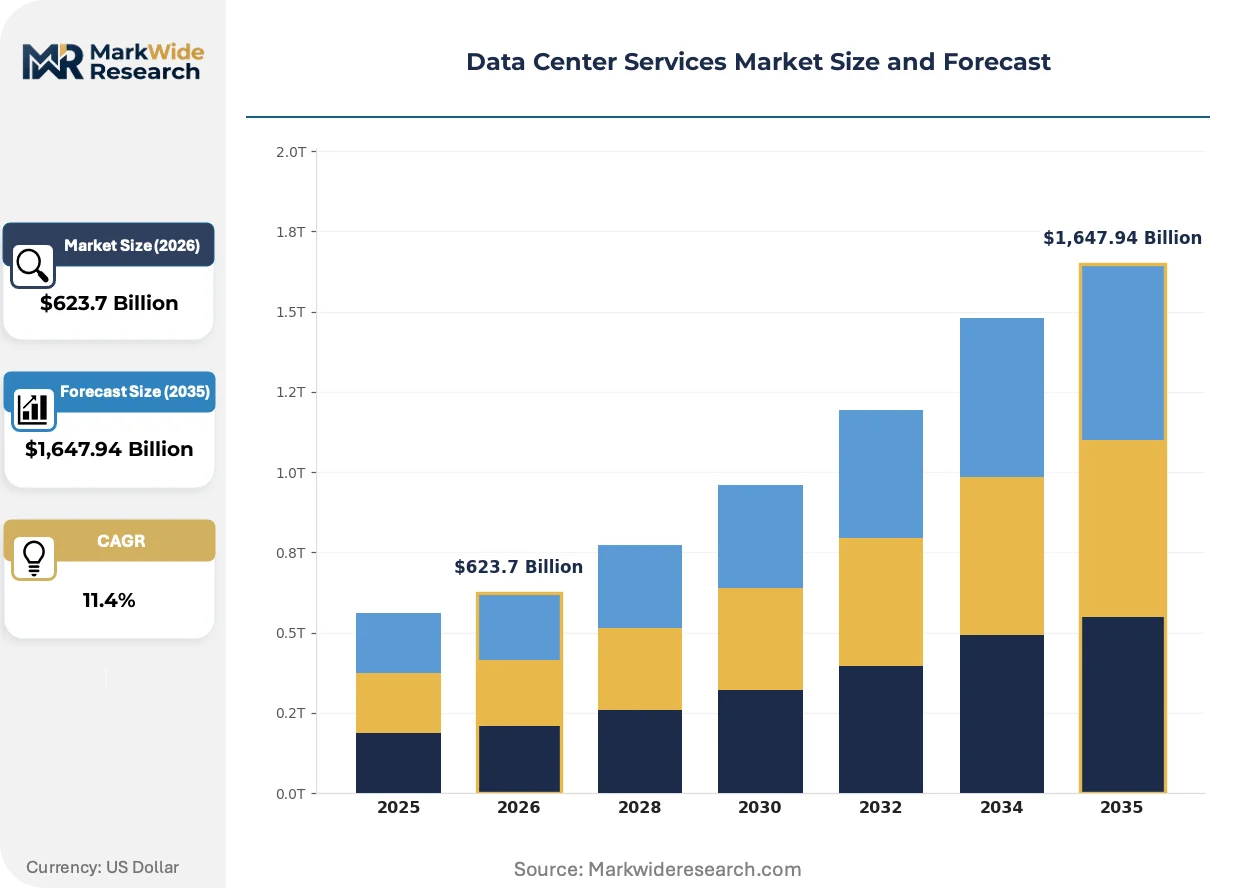
| Market Size in 2026 | $623.7 Billion |
| Market Size in 2035 | $1,647.94 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Disaster Recovery Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: SMEs, Large Enterprises, Government, Telecom Management Level: Facility Management, IT Management, Network Management, Security Management |
| Companies Covered | Microsoft Azure, NTT Global Data Centers, Equinix, CyrusOne, Vantage Data Centers, Digital Realty, Google Cloud, Oracle Cloud Infrastructure, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Services Market Emerging Trajectories
Direct liquid cooling is compressing facility footprints while EPA carbon reporting rules and hyperscaler procurement standards are rewriting equipment specifications and vendor qualification criteria.
Immersion cooling systems using dielectric fluids are supplanting conventional raised-floor air distribution in high-performance computing deployments. Research institutions and AI training clusters are specifying tank-based architectures for 500kW-plus rack densities. This technology is supplanting traditional chiller plant investments and enabling heat capture for district energy integration.
The EPA's mandatory carbon reporting rules for facilities exceeding 25,000 metric tons CO2 equivalent annually are forcing Scope 2 emission disclosure. Operators are procuring renewable energy credits and on-site solar to manage disclosure thresholds. Wholesale colocation providers in Texas and Iowa are responding with 24/7 carbon-free energy matching contracts.
Buyers are consolidating vendor relationships around integrated design-build-operate contracts rather than fragmented procurement of real estate, power, and IT infrastructure. Enterprise IT departments are transferring capex responsibility to specialized operators with balance sheet capacity. This concentration is most visible among Fortune 500 manufacturers outsourcing North American and European footprint expansion.
Data Center Services Market Segmentation
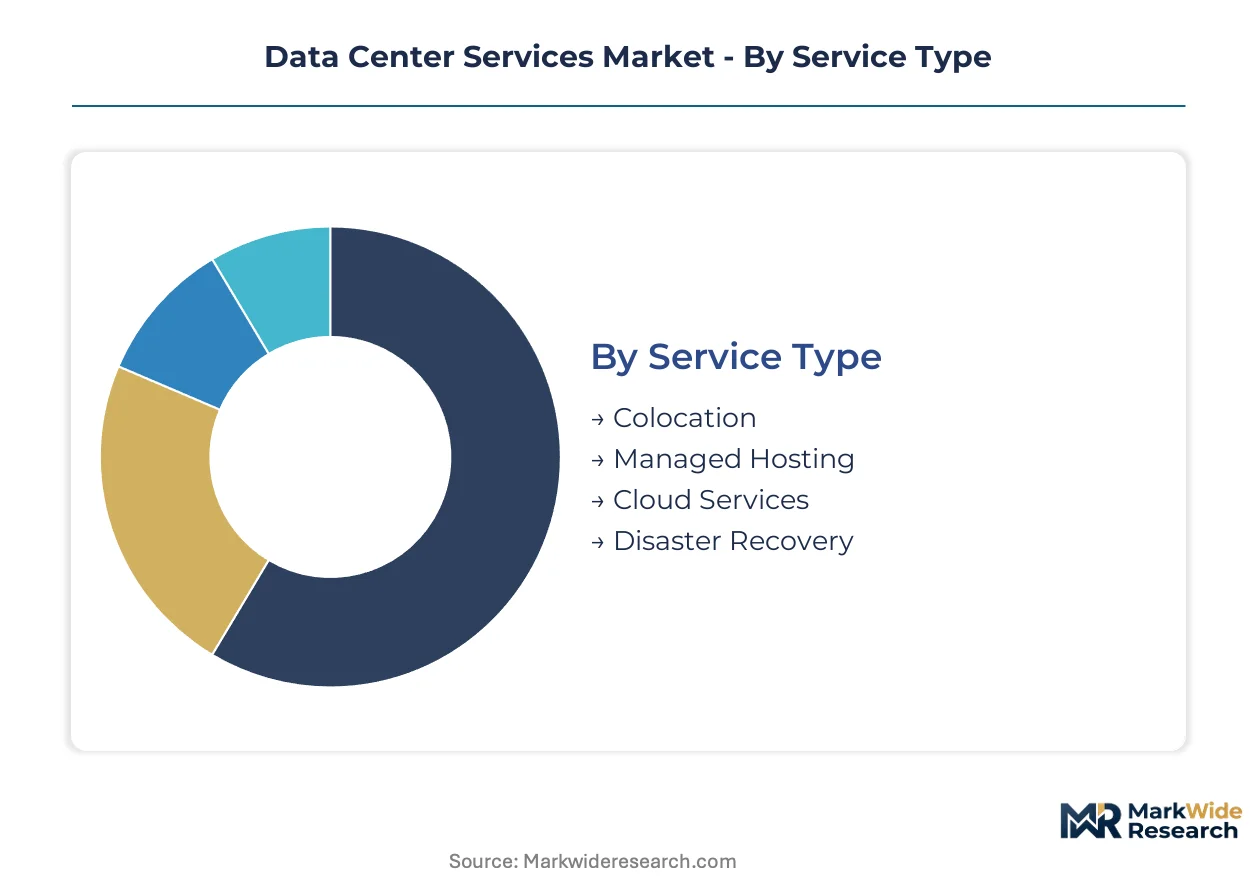
Data center services segmentation reveals how workload requirements, compliance mandates, and capital constraints fragment buyer behavior across four critical dimensions. Each category captures distinct substitution pressures as enterprises weigh owned infrastructure against outsourced alternatives.
Service Type:
Substitution pressure from hyperscale cloud platforms is compressing margins for traditional colocation and managed hosting, while specialized compliance-driven services defend pricing power.
- Cloud Services:Public and private cloud platforms deliver compute, storage, and networking via subscription models with elastic scaling. Financial services firms in Chicago and London are migrating transactional workloads to meet algorithmic trading latency mandates. Hyperscaler procurement standards are rewriting equipment specifications and vendor qualification criteria.
- Colocation:Wholesale and retail leasing of powered shell space with cross-connect access to carrier-neutral ecosystems. Northern Virginia and Dallas-Fort Worth absorb substantial capacity from enterprises exiting owned facilities. EPA carbon reporting rules now govern facility design for US-based providers above emission thresholds.
- Managed Hosting:Dedicated server provisioning with operational support but without full infrastructure abstraction. Manufacturing automation buyers favor this model for legacy application containment.
- Disaster Recovery:Secondary site replication and failover orchestration governed by recovery time objective contracts. Healthcare and banking compliance audits drive specification intensity.
Cloud Services anchors the volume base while Disaster Recovery gains share at the steepest rate as ransomware exposure escalates.
Deployment Model:
Cost tier stratification separates capex-intensive on-premises builds from opex-light public cloud consumption, with hybrid architectures commanding premium positioning.
- Hybrid Cloud:Workload portability between on-premises control and public elasticity via orchestration platforms. Fortune 500 manufacturers are outsourcing North American and European footprint expansion to specialized operators. This segment climbs the fastest as sovereignty requirements clash with scale economics.
- Public Cloud:Shared multi-tenant infrastructure with metered consumption and global region availability. SaaS providers and digital-native enterprises concentrate demand here.
- Private Cloud:Single-tenant dedicated infrastructure with customization latitude for regulated workloads. Federal cloud procurement mandates are creating captive demand for FedRAMP-authorized configurations.
- On-Premises:Wholly owned facilities with direct capital deployment and operational control. Defense and intelligence agencies maintain this model for air-gapped security.
Public Cloud carries the largest installed base while Hybrid Cloud expands most quickly among enterprises navigating data residency mandates.
End User:
Volume concentration among capital-rich hyperscalers contrasts with margin compression serving price-sensitive smaller entities.
- Large Enterprises:Multi-megawatt deployments with custom mechanical and electrical specifications. Sovereign wealth capital in Saudi Arabia is de-risking greenfield investment for NEOM and Red Sea tourism developments. Integrated design-build-operate contracts are consolidating vendor relationships.
- SMEs:Sub-megawatt requirements with standardized colocation packages and limited customization. Retail colocation providers in secondary metros target this segment with pre-engineered solutions.
- Government:Classified and unclassified workloads bound by NIST cybersecurity frameworks and data localization statutes. Specialized security architecture commands rate premiums.
- Telecom:Edge node deployment for 5G core infrastructure and content delivery networks. Latency sensitivity now governs site selection within 50 kilometers of subscriber clusters.
Large Enterprises dominate committed capacity while Telecom shows the steepest expansion trajectory as 5G rollouts accelerate.
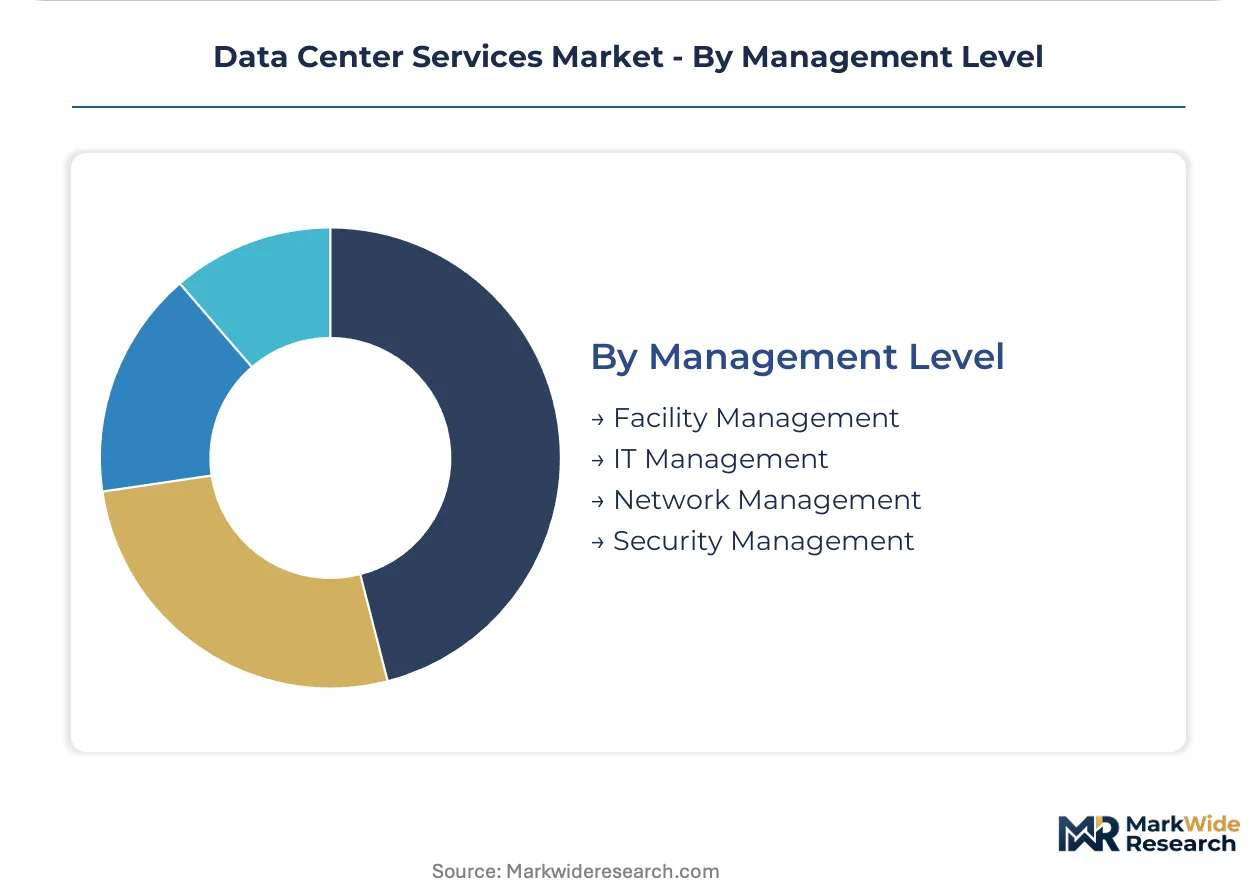
Management Level:
Margin stratification favors security-intensive offerings over commoditized facility operations as threat surfaces expand.
- Security Management:Zero-trust architecture implementation, intrusion detection, and compliance audit preparation. Ransomware exposure and audit frequency escalation sustain premium pricing. District heating networks in Copenhagen and Helsinki are contracting for waste heat offtake from facilities with integrated security stacks.
- Network Management:Cross-connect provisioning, traffic engineering, and peering coordination. Interconnection density in strategic metros anchors competitive positioning.
- IT Management:Server provisioning, patch management, and application monitoring. Standardized service catalogs compete on response time guarantees.
- Facility Management:Mechanical and electrical maintenance, capacity planning, and energy procurement. EU Energy Efficiency Directive mandates now compress upgrade timelines for European operators.
Facility Management anchors the revenue base while Security Management gains share at the steepest rate as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in data center services remain minimal as infrastructure is immovable, though capital flows concentrate in countries offering tax incentives and renewable energy access. The United States maintains a capital surplus position through hyperscaler investment dominance. European operators import specialized cooling equipment from Asian manufacturing clusters.
United States
Hyperscaler construction in Northern Virginia and Dallas-Fort Worth absorbs substantial capacity from enterprises exiting owned facilities. EPA carbon reporting rules mandate Scope 2 emission disclosure for facilities exceeding 25,000 metric tons CO2 equivalent annually. Chicago financial services firms expand colocation footprints to achieve sub-5 millisecond proximity to exchange matching engines.
Germany
Frankfurt anchors interconnection density for algorithmic trading latency mandates serving London and continental exchanges. The EU Energy Efficiency Directive mandates power usage effectiveness reporting for facilities above 500kW capacity. Berlin-Brandenburg experiences permitting bottlenecks as local zoning boards impose 18-24 month approval cycles for substation upgrades.
Saudi Arabia
NEOM and Red Sea tourism developments require captive data infrastructure with renewable energy pairing. Sovereign wealth capital de-risks greenfield investment through long-term offtake commitments. Riyadh-based operators negotiate heat reuse integration contracts with district heating networks.
United Kingdom
London financial services firms drive colocation demand for sub-5 millisecond exchange proximity. CE marking requirements govern European buildout specifications and equipment sourcing for cross-border operations. Slough and Docklands clusters face skilled electrical technician scarcity as medium-voltage switchgear certification programs produce insufficient graduates.
India
Mumbai and Chennai absorb cloud services migration from domestic enterprises and multinational back-office operations. The country's central bank mandates data localization for payment systems and financial transaction records. Telangana and Karnataka state governments offer land and power subsidies to attract hyperscale campus developments.
Data Center Services Market Vendor Landscape
Concentration sits with hyperscale cloud providers and wholesale colocation specialists who command balance sheet capacity for multi-megawatt deployments. Tier II and Tier III operators face margin compression as liquid cooling infrastructure requirements displace legacy air-handling economics. Three archetypes dominate: integrated cloud platforms with global fiber backbones, carrier-neutral interconnection specialists, and wholesale campus developers with scaled power allocations. Competitive moves center on M&A for fiber asset consolidation and strategic partnerships for renewable energy procurement.
Within the integrated cloud platform tier, Microsoft Azure and Amazon Web Services exemplify hyperscale operators leveraging proprietary global networks to sustain low-latency connectivity between regions. Equinix occupies a position as the dominant interconnection density anchor in strategic metros, while Digital Realty represents wholesale campus development at scale. NTT Global Data Centers, CyrusOne, Vantage Data Centers, Google Cloud, and Oracle Cloud Infrastructure sit within specialized segments serving sovereign cloud requirements and GPU-intensive workloads.
| Leading Market Players |
|---|
| Microsoft Azure |
| NTT Global Data Centers |
| Equinix |
| CyrusOne |
| Vantage Data Centers |
| Digital Realty |
| Google Cloud |
| Oracle Cloud Infrastructure |
| Amazon Web Services |
| Others |
Supply Flow & Price Mechanics
Liquid cooling infrastructure replacing conventional air-handling architectures is simultaneously redrawing procurement geography around Asian manufacturing clusters and compressing legacy facility pricing premiums as hyperscalers force equipment specification upgrades.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in data center services. Price differentiation hinges on certification tier (FedRAMP authorization versus SOC 2) and power density specification (sub-100kW versus 500kW-plus rack configurations). Cost compression in standard colocation tiers is intensifying because hyperscale cloud platforms absorb volume at scale. SMEs exhibit highest price sensitivity while financial services firms in Chicago and London demonstrate lowest sensitivity due to latency mandate compliance requirements.
Supply Chain Analysis
Port congestion along Shanghai-to-Los Angeles trade lanes and container availability constraints on Asia-Europe routes are elevating inbound logistics costs for precision cooling equipment and medium-voltage switchgear. Manufacturing concentrates in China, South Korea, and Taiwan for silicon carbide substrates and advanced cooling components. Raw material dependencies center on Chilean copper concentrate, Chinese rare earth processing, and German precision engineering for electrical switchgear. Single-source vulnerability in silicon carbide substrate supply threatens delivery reliability. Distribution runs through direct OEM relationships with hyperscalers and tiered distributor networks serving regional colocation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center services function as a service-attach opportunity where security management and compliance audit preparation layers expand faster than underlying facility leasing revenue as ransomware exposure escalates.
For Market Incumbents: Compound interconnection density advantages in Northern Virginia and Frankfurt by securing fiber backbone assets and renewable energy offtake contracts before permitting queues extend further. Liquid cooling infrastructure requirements threaten Tier II and Tier III operators with margin compression; vertical integration into electrical switchgear design capabilities defends quality assurance capacity against technician scarcity. For New Entrants and Emerging Players: Lead with district heating integration partnerships in Copenhagen, Helsinki, and Riyadh where waste heat offtake contracts improve project returns and differentiate against commodity colocation providers. Saudi Arabia's NEOM and Red Sea developments represent the most penetrable geography given sovereign wealth capital de-risking greenfield investment. A design-build-operate contract model bypasses capital intensity barriers while capturing recurring facility management revenue. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors wholesale campus developers with scaled power allocations and FedRAMP authorization capabilities. Long-term viability over a multi-year window favors operators with 24/7 carbon-free energy matching contracts and liquid cooling deployment experience. Watch NIST cybersecurity framework compliance mandates as the signal indicating accelerated federal procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Procurement | EPA carbon reporting rules force Scope 2 disclosure management through 24/7 clean energy matching. |
| Liquid Cooling Infrastructure Deployment | GPU-intensive AI workloads demand 500kW-plus rack densities that displace legacy air-handling economics. |
| FedRAMP Authorization Investment | Federal cloud procurement mandates create captive demand for specialized security architecture at rate premiums. |
| Fiber Asset Consolidation | Low-latency connectivity between cloud regions requires proprietary backbone control for competitive positioning. |
| Heat Reuse Integration | District heating contracts in Nordic and Middle Eastern markets stack revenue streams beyond core leasing. |
Methodological Framework
A spread of perspectives from hyperscaler procurement officers, colocation facility operators, electrical engineering contractors, and district heating network managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, EPA emission databases, and EU Energy Efficiency Directive compliance registers. Bottom-up triangulation across service type, deployment model, and management level dimensions anchored volume estimates against top-down macroeconomic indicators.
Segmentation dimensions modeled span service type (cloud services, colocation, managed hosting, disaster recovery), deployment model (hybrid cloud, public cloud, private cloud, on-premises), end user (large enterprises, SMEs, government, telecom), and management level (security management, network management, IT management, facility management) across the analysis window. CAGRs derived from historical trajectory analysis and elasticity modeling against cloud migration rates and AI workload proliferation. Industry-specific forecast inputs incorporated liquid cooling adoption curves and FedRAMP authorization pipeline data.
Forecasts assume regulatory continuity in EPA carbon reporting rules and EU Energy Efficiency Directive mandates; material policy shifts would require re-modeling. Scope 2 emission disclosure thresholds, data localization statutes, and medium-voltage engineering certification requirements represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Graph Database Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market