
 Synthetic Textile Fiber Market | 2026-2036
Synthetic Textile Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Textile Fiber Market Analytics
Buyer concentration in apparel procurement is restructuring supply dynamics across the synthetic textile fiber value chain. Reliance Industries Limited leverages its integrated petrochemical-to-fiber infrastructure to capture bulk contracts from consolidating Western retailers. Toray Industries anchors technical textile supply for automotive and industrial buyers through high-tenacity polyester specialization. Indorama Ventures Public Company Limited dominates bottle-to-fiber recycling scale, competing on circular feedstock availability.
Synthetic textile fibers comprise man-made polymeric filaments or staple fibers engineered from petrochemical-derived polymers such as polyethylene terephthalate or polyamide, extruded through melt-spinning or solution-spinning processes to achieve controlled denier, tenacity, and thermal stability for woven, knitted, or nonwoven constructions. Polyester filaments sustain the largest volume share across clothing and upholstery applications due to cost-performance ratios and dye-sub compatibility. Technical textiles represent the fastest-expanding application segment as geotextile and filtration specifications tighten. Nylon staple fiber occupies premium margin pools in automotive airbag and industrial cordage specifications where fatigue resistance commands price premiums.
REACH registration requirements and the EU Green Deal carbon-border adjustments constrain virgin polymer import pathways into European textile manufacturing. EPA industrial emissions standards and state-level extended producer responsibility frameworks in California and New York reshape domestic fiber sourcing compliance burdens. China's GB standards and dual carbon goals from MEE enforce energy-intensity caps on polyester melt-spinning facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certify feedstock provenance.
Market Dynamics
Apparel procurement consolidation is compressing supplier margins while circular feedstock mandates from Brussels and Beijing simultaneously reroute polymer sourcing pathways. Western retailers now bundle synthetic fiber contracts under single-source agreements exceeding prior volume thresholds by multiples.
Growth Catalysts
- EU Green Deal carbon-border adjustments:The CBAM mechanism imposes embodied-carbon tariffs on virgin polyester imports, accelerating regional recycling infrastructure buildout and certified circular fiber uptake.
- Technical textile specifications:Automotive airbag and filtration applications demand high-tenacity filaments with fatigue resistance beyond commodity grades, opening premium pricing tiers.
- China domestic mill integration:Vertical absorption of melt-spinning capacity by downstream textile manufacturers concentrates demand within integrated coastal clusters.
Market Restraints
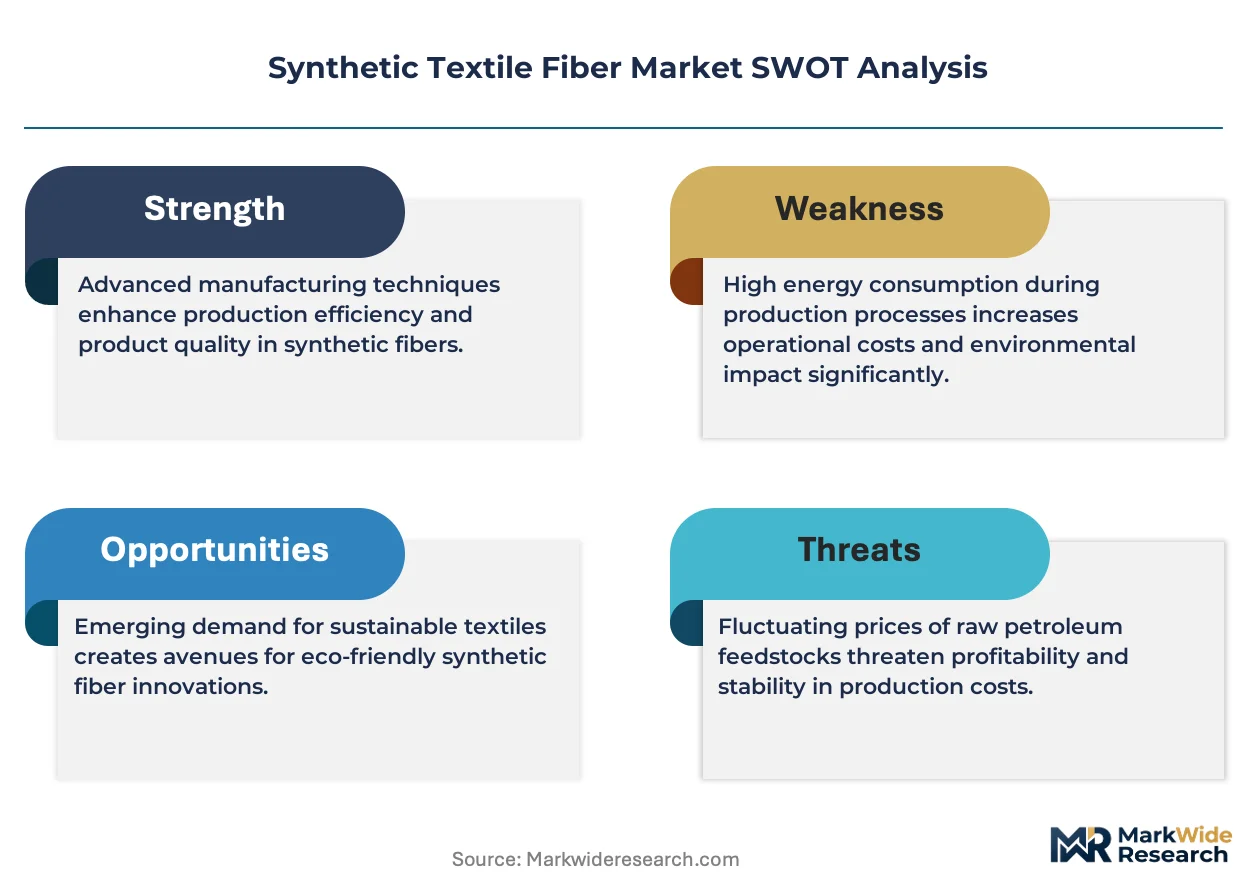
- Petrochemical feedstock volatility:Paraxylene and MEG pricing swings transmit directly to filament cost structures, eroding margin predictability for non-integrated spinners.
- MEE energy-intensity caps:China's Ministry of Ecology and Environment enforces dual carbon ceilings on polyester production, constraining capacity expansion at legacy facilities.
- Cellulosic fiber substitution:Lyocell and viscose alternatives capture share in premium apparel segments where moisture management and biodegradability command buyer preference.
Strategic Opportunities
- India PLI scheme for man-made fibers:Production-linked incentives for technical textile and MMF segments attract greenfield capacity outside China-dominated supply chains.
- Digital textile printing compatibility:Disperse-dye-ready recycled polyester filaments align with on-demand manufacturing models shortening fashion cycles.
- California EPR frameworks:Extended producer responsibility mandates for textile waste create closed-loop feedstock demand for bottle-to-fiber recyclers serving West Coast brands.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for bio-based and recycled feedstock processing lags capacity expansion timelines, inflating compensation for qualified technologists.
- REACH certification timelines:ECHA registration requirements for novel recycled-content additives extend product qualification cycles by 18-24 months, delaying commercialization.
- Legacy dyeing equipment incompatibility:Existing jet and beam infrastructure requires retrofitting for low-temperature dyeing of modified polyester, stranding capital in traditional wet-processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Textile Fiber Market |
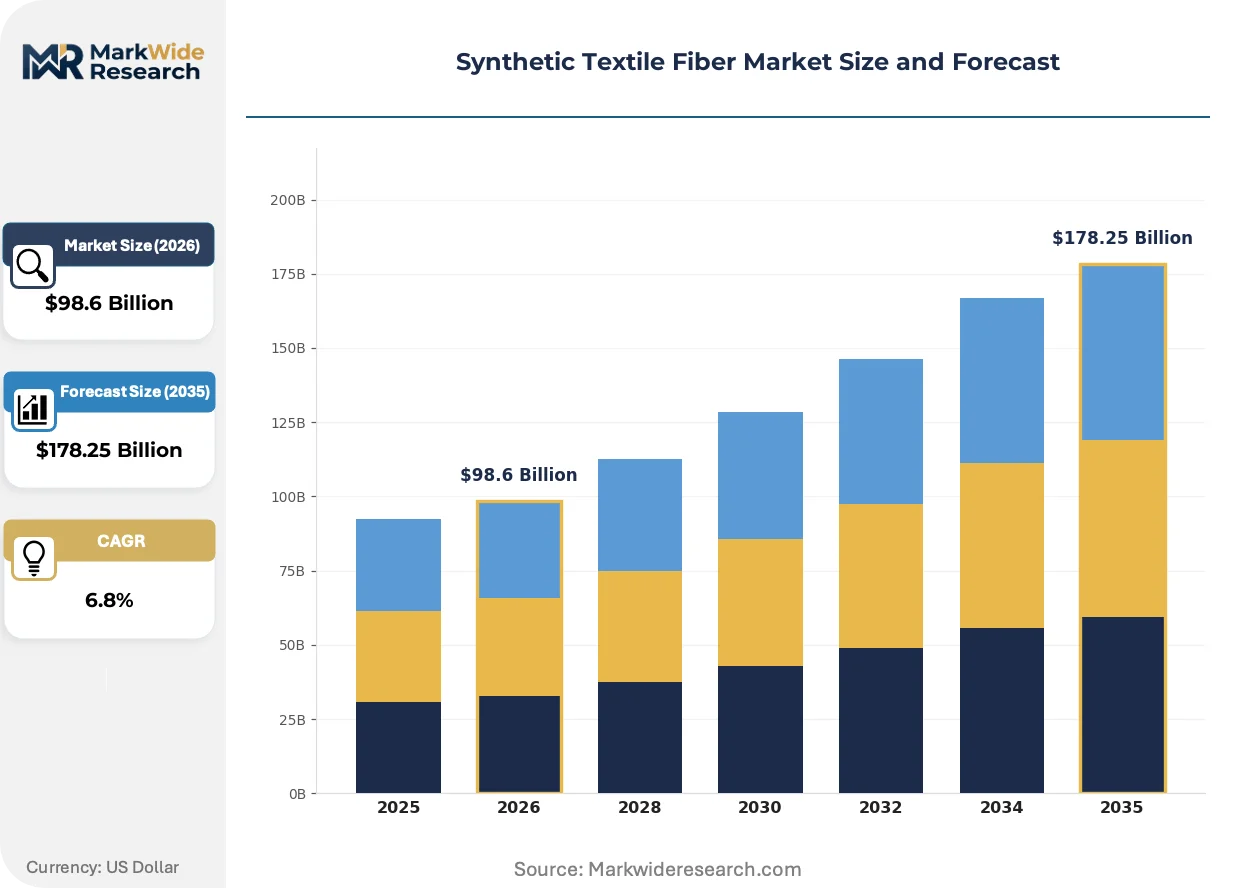
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Acrylic, Spandex End User: Apparel, Home Furnishings, Automotive, Industrial Applications Form: Filaments, Staple Fiber, Yarns, Fabrics Application: Clothing, Upholstery, Geotextiles, Technical Textiles |
| Companies Covered | Teijin Limited, Bombay Dyeing, Reliance Industries Limited, Mitsui Chemicals, Toyobo, Indorama Ventures Public Company Limited, DuPont de Nemours, Lenzing AG, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Textile Fiber Market Evolving Landscape
Digital process control and molecular recycling technologies are compressing the cost gap between virgin and circular feedstocks while regulatory frameworks harden around embodied carbon accounting.
AI-driven extrusion control systems is automating denier consistency in melt-spinning lines, reducing off-spec filament generation below 2% at Tier-1 facilities. Technical textile manufacturers in Germany and Japan deploy these systems for automotive safety component supply where lot-to-lot variance carries liability exposure. The technology is automating quality assurance labor out of high-tenacity production, shifting competitive advantage toward capital-intensive operators.
REACH chemical restrictions now mandate Substance of Very High Concern screening across full polymer supply chains, compelling fiber producers to document feedstock provenance through blockchain-anchored certificates. ECHA enforcement actions against non-compliant importers have accelerated substitution of legacy flame retardants in upholstery applications. European automotive seating suppliers now require OEKO-TEX and bluesign dual certification as table-stake qualification.
Direct-to-mill contracting is eliminating traditional fiber trader intermediaries as consolidated apparel groups establish captive procurement offices in Zhejiang and Fujian provinces. This disintermediation compresses working capital cycles for integrated petrochemical-to-fiber conglomerates while stranding independent traders without volume commitments. The pattern is most advanced among US and EU-based athleisure brands with China-dominant sourcing footprints.
Synthetic Textile Fiber Market Segmentation
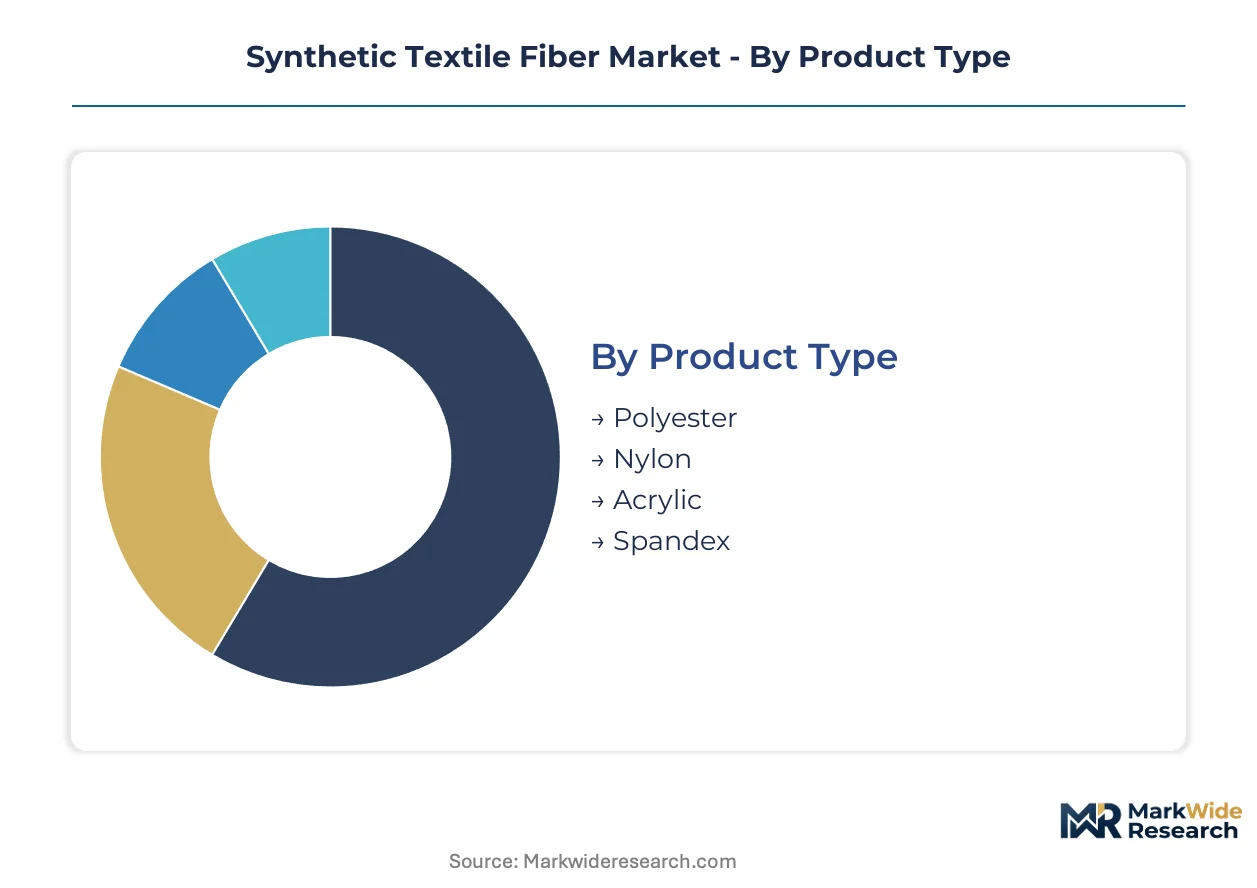
Synthetic textile fiber procurement patterns diverge sharply across product chemistry, end-use specifications, and physical form. Buyers segment contracts by performance tier rather than commodity grade alone, with technical specifications now driving supplier qualification ahead of unit cost.
Product Type:
Replacement cycles in apparel manufacturing are shortening as fast-fashion brands compress design-to-shelf timelines, forcing fiber producers to align inventory with seasonal specification shifts rather than annual contracting.
- Polyester:Melt-spun polyethylene terephthalate filaments and staple fibers dominate volume throughput across woven and knitted constructions. Demand concentrates in Zhejiang Province textile mills serving athleisure brands, where disperse-dye compatibility and tenacity-to-cost ratios lock in supplier relationships despite feedstock volatility.
- Nylon:Polyamide 6 and 6,6 polymers deliver fatigue resistance and abrasion tolerance that commodity polyesters cannot replicate. Automotive airbag weavers in Germany and industrial cordage manufacturers in Japan absorb premium pricing for high-tenacity grades, with specification tightening around lot-to-lot variance thresholds.
- Acrylic:Acrylonitrile-based staple fiber mimics wool handle and bulk for outerwear and blanket applications at lower moisture absorption.
- Spandex:Segmented polyurethane elastane provides stretch recovery in compression garments and activewear where 300-600% elongation specifications are mandatory.
Volume placements concentrate in Polyester; the faster expansion belongs to Nylon.
End User:
Cost tier stratification separates commodity apparel contracts from premium technical textile agreements, with the latter commanding 3-4x unit pricing for certified traceability and performance guarantees.
- Apparel:Woven shirting, knitted activewear, and outerwear constructions absorb the majority of staple fiber and filament offtake. Western retailer consolidation in the US and EU is compressing supplier counts per category, with mega-contracts now exceeding prior volume thresholds by multiples.
- Home Furnishings:Upholstery, carpet face yarn, and drapery applications demand solution-dyed filaments for lightfastness and stain resistance. REACH Substance of Very High Concern screening has eliminated legacy flame retardant chemistries, forcing reformulation cycles at European furniture manufacturers.
- Automotive:Seating fabric, airbag webbing, and tire cord specifications enforce zero-defect quality protocols with full batch traceability.
- Industrial Applications:Filtration media, rope and cordage, and geotextile reinforcements require UV-stabilized and chemically resistant fiber constructions.
Apparel commands the largest contract values; Industrial Applications are climbing the fastest as infrastructure spending accelerates specification-grade uptake.
Form:
Physical configuration determines downstream processing compatibility and working capital intensity, with filament producers capturing margin premiums for ready-to-weave supply.
- Filaments:Continuous extruded fibers ranging from 20-300 denier feed directly into warp knitting and weaving looms without spinning preparation. POY, FDY, and DTY variants align with fabric hand and strength requirements across apparel and technical textile end-uses.
- Staple Fiber:Cut-length discontinuous fibers from 0.8-15 denier require carding and spinning into yarn before fabric formation. Blending with cotton or cellulosic fibers in rotor and ring spinning systems sustains demand for polyester staple in shirting and suiting.
- Yarns:Twisted or air-jet interlaced assemblies of filaments or spun staple fibers deliver specified linear density and strength for downstream knitting or weaving.
- Fabrics:Woven, knitted, or nonwoven constructions represent the terminal form before garment or product cut-and-sew operations.
Filament shipments dominate tonnage; staple fiber is gaining share fastest as cotton-polyester blending resurges in mid-market apparel.
Application:
Geographic clustering of demand shapes application-level procurement, with Chinese mill integration absorbing growing shares of upstream fiber production.
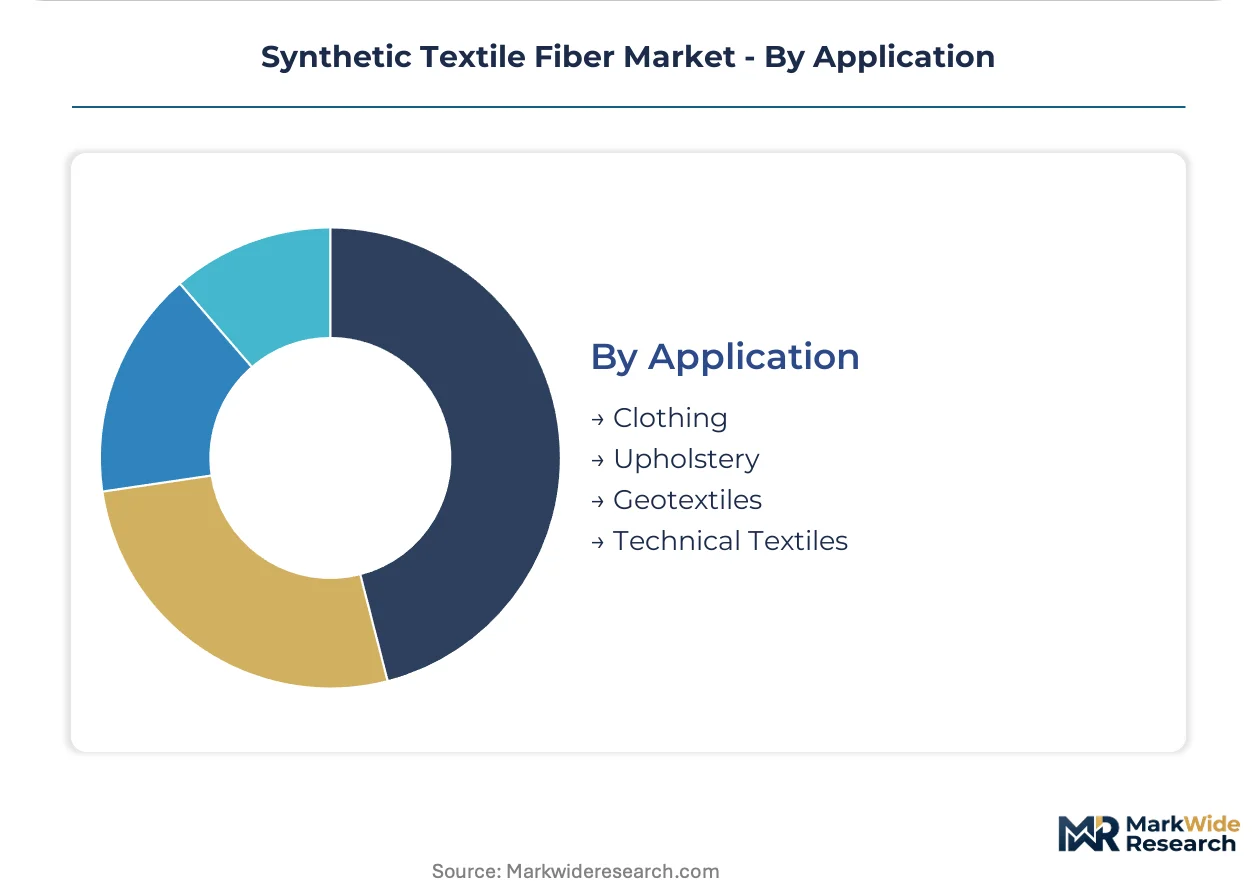
- Clothing:Shirts, trousers, dresses, and outerwear constitute the foundational apparel application where cost-performance optimization prevails. Digital textile printing compatibility now filters supplier selection, with disperse-dye-ready recycled polyester filaments qualifying for on-demand manufacturing models.
- Upholstery:Residential and contract furniture fabrics demand abrasion resistance, pilling resistance, and lightfastness certification. California's extended producer responsibility frameworks are redirecting procurement toward bottle-to-fiber recycled feedstocks for West Coast brand compliance.
- Geotextiles:Civil engineering applications including road stabilization, erosion control, and landfill liners specify high-tenacity polyester or polypropylene with UV stabilization.
- Technical Textiles:Filtration, medical, protective, and composite reinforcement applications impose performance specifications beyond commodity grades.
Clothing absorbs the greatest volume; Technical Textiles follow the steepest expansion trajectory as automotive and industrial specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of synthetic textile fiber demand as domestic textile mills expand captive melt-spinning capacity. Western procurement consolidation redirects contract flows toward integrated coastal clusters. Regulatory divergence across major manufacturing jurisdictions reshapes feedstock certification requirements.
China
Zhejiang and Fujian province textile mills drive polyester filament absorption for athleisure export contracts. MEE dual carbon goals enforce energy-intensity caps on legacy melt-spinning facilities. Shaoxing's Keqiao district concentrates digital textile printing-ready recycled polyester supply for on-demand manufacturing models.
United States
California and New York-based brands mandate bottle-to-fiber recycled content for West Coast compliance. EPA industrial emissions standards and state-level extended producer responsibility frameworks elevate sourcing documentation burdens. Southeast textile corridors attract technical yarn investment serving automotive airbag specifications.
Germany
Automotive seating and industrial filtration manufacturers specify high-tenacity filament with full batch traceability. REACH Substance of Very High Concern screening eliminates legacy flame retardant chemistries from upholstery supply chains. Baden-Württemberg technical textile clusters enforce OEKO-TEX and bluesign dual certification as baseline qualification.
India
Domestic apparel brands expand synthetic fiber integration under PLI scheme incentives for man-made fiber technical textile segments. BIS quality standards and DGFT trade policies shape import substitution trajectories. Gujarat and Maharashtra chemical corridors anchor greenfield polyester staple capacity outside China-dominated supply chains.
Japan
Automotive safety component and industrial cordage weavers absorb premium-priced high-tenacity nylon with fatigue resistance specifications. METI carbon neutrality roadmaps accelerate molecular recycling technology deployment. Aichi and Osaka prefecture manufacturing belts deploy AI-driven extrusion control for lot-to-lot variance reduction.
Synthetic Textile Fiber Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certified circular feedstock specialization. The supplier base compresses around integrated petrochemical-to-fiber conglomerates and recycled-content specialists. Three archetypes dominate: backward-integrated petrochemical giants, bottle-to-fiber recycling scale operators, and high-tenacity technical filament specialists. Competitive moves center on captive procurement office establishment in Chinese coastal provinces and molecular recycling capacity buildout for regulatory compliance.
Among Asia-Pacific headquartered conglomerates, Reliance Industries Limited and Indorama Ventures Public Company Limited exemplify scale-driven backward integration archetypes, while Toray Industries occupies a position within the premium technical filament tier. These entities anchor contrasting competitive vectors across commodity volume and performance-specification segments.
| Leading Market Players |
|---|
| Teijin Limited |
| Bombay Dyeing |
| Reliance Industries Limited |
| Mitsui Chemicals |
| Toyobo |
| Indorama Ventures Public Company Limited |
| DuPont de Nemours |
| Lenzing AG |
| Toray Industries |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon-border adjustment mechanisms gate qualified supply access and premium-tier pricing power, as certified circular fiber producers capture margin premiums while virgin polyester importers absorb embodied-carbon tariff penalties. Apparel procurement consolidation concentrates volume leverage among mega-suppliers, compressing margins for non-integrated spinners unable to document feedstock provenance through blockchain-anchored certificates.
Pricing Analysis
Volume placements concentrate in commodity polyester grades where tenacity-to-cost ratios dominate supplier selection, while premium margins accrue to high-tenacity nylon and certified recycled filaments with fatigue resistance specifications. Price differentiation rests on OEKO-TEX certification tier and disperse-dye compatibility for digital textile printing readiness. Cost compression in standard-grade polyester intensifies as Zhejiang Province mills integrate captive melt-spinning capacity and squeeze third-party fiber suppliers. Fast-fashion retailers exhibit acute price sensitivity, whereas automotive airbag weavers in Germany absorb 3-4x unit premiums for lot-to-lot variance guarantees.
Supply Chain Analysis
REACH Substance of Very High Concern screening and bluesign certification now gate supplier qualification for European automotive seating and upholstery contracts, eliminating legacy flame retardant chemistries from qualified supply bases. Production concentrates in China, India, and Vietnam as coastal textile clusters absorb upstream fiber capacity through vertical mill integration. Paraxylene and MEG feedstock costs hinge on petrochemical pricing volatility, while bottle-to-fiber recycling draws from post-consumer PET collection infrastructure concentrated in North America and Europe. Single-source vulnerability escalates as direct-to-mill contracting eliminates fiber trader intermediaries. Distribution runs through captive procurement offices established by consolidated Western retailers in Zhejiang and Fujian provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular recycling technologies are displacing conventional mechanical recycling in premium fiber segments, as regulatory mandates for certified circular content render legacy processing methods commercially obsolete. Incumbents and entrants must position around this technology transition to capture compliance-driven procurement shifts.
For Market Incumbents: Acquire molecular recycling technology assets to secure qualified circular feedstock capacity ahead of REACH registration deadline acceleration. Integrate backward into post-consumer PET collection infrastructure in California and New York to serve West Coast brand EPR compliance requirements. Defensive consolidation around high-tenacity technical filament capabilities protects against Asian specialty chemical entrants targeting automotive safety component supply.
For New Entrants and Emerging Players: California's extended producer responsibility framework opens a window for bottle-to-fiber recyclers to establish closed-loop feedstock contracts with athleisure brands seeking West Coast regulatory compliance. White-space targets include disperse-dye-ready recycled polyester for on-demand digital textile printing and geotextile-grade UV-stabilized filament for infrastructure spending acceleration. Go-to-market positioning should emphasize blockchain-anchored provenance documentation as a table-stake qualifier.
For Investors and Strategic Acquirers: Indorama Ventures' capacity announcements in India are the leading indicator that PLI scheme incentives are successfully diverting technical textile investment outside China-dominated supply chains. Long-term viability favors integrated petrochemical-to-fiber conglomerates with captive recycling technology and coastal China procurement office networks. Acquisition target archetypes include high-tenacity nylon specialists serving German automotive airbag specifications and molecular recycling technology developers with ECHA pre-registration status.
| Strategic Initiative | Industry Significance |
|---|---|
| Molecular Recycling Capacity Buildout | ECHA registration timelines for novel recycled-content additives compress competitive windows for early movers. |
| Backward Integration into PET Collection | California EPR mandates create captive feedstock demand for West Coast brand compliance. |
| AI-Driven Extrusion Control Deployment | Automotive safety component suppliers in Germany and Japan demand lot-to-lot variance below 2%. |
| Captive Procurement Office Establishment | Direct-to-mill contracting in Zhejiang eliminates trader intermediaries and compresses working capital cycles. |
| Dual Certification Investment (OEKO-TEX/bluesign) | European automotive seating suppliers now require both certifications as baseline qualification. |
Research Methodology
Document review covered customs and trade flow databases, SEC filings from petrochemical conglomerates, and ECHA registration databases, complemented by interviews with polyester plant managers, technical textile procurement leads at automotive Tier 1 suppliers, sustainability officers at apparel brands, and distribution channel partners in Asian fiber trading hubs. Primary fieldwork validated secondary data through structured conversations regarding melt-spinning capacity utilization, circular feedstock availability, and certification timeline experiences. Bottom-up fiber shipment analysis triangulated against top-down petrochemical derivative demand models.
Output projections span volume and value across the analysis window, with segmentation dimensions including polymer chemistry, physical form, end-use specification tier, and regional production cluster. CAGRs derive from trend extrapolation of melt-spinning capacity expansion, regulatory compliance cost absorption, and substitution elasticity between virgin and circular feedstocks. Key forecast inputs incorporate MEE energy-intensity cap enforcement trajectories and EU CBAM tariff phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for molecular recycling scale-up would alter the outlook for mechanical recyclers and virgin polyester producers. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock collection infrastructure development. A model refresh is warranted upon material change in ECHA registration timeline acceleration or MEE dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Carbon Fiber Strands Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Nanofibers Market