
 Polybenzoxazole Fibers Market | 2026-2036
Polybenzoxazole Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Polybenzoxazole Fibers Market Intelligence
Japanese polymer producers is consolidating output of high-modulus fibers for aerospace and defense applications. Toyobo Co., Ltd. leverages its proprietary spinning technology to dominate specialty fiber supply chains. DuPont sustains broad patent coverage across aramid and polybenzoxazole chemistries. Yantai Tayho Advanced Materials Co., Ltd. anchors expanding Asian production capacity for industrial-grade fibers.
Polybenzoxazole fibers are rigid-rod aromatic heterocyclic polymers with exceptional thermal stability above 650°C decomposition temperature and tensile strength exceeding 5.8 GPa, manufactured through dry-jet wet spinning of polyphosphoric acid dopes for ballistic armor, fire-resistant textiles, and structural composites. The aerospace application segment leads value capture due to stringent flame-retardant specifications in cabin interiors and engine compartments. The defense end-user category occupies the fastest-expanding margin pool as military procurement shifts toward lighter, multi-threat protective systems. Spinning technology controls cost structure, with advanced composite processing commanding premium pricing for integrated structural solutions.
REACH chemical registration requirements in Europe, the EU Green Deal sustainability mandates, and U.S. Department of Defense MIL-STD performance specifications collectively shape fiber purity benchmarks and market access conditions. China's GB standards and dual carbon goals are tightening energy intensity rules for polymer production facilities. Stakeholders must monitor regulatory divergence between jurisdictions and align certification strategies before capacity commitments lock in non-compliant process designs.
Market Dynamics
Dry-jet wet spinning technology is concentrating production capability among a handful of polymer specialists capable of handling polyphosphoric acid dopes at industrial scale. Defense procurement cycles for multi-threat ballistic systems are compressing lead times and favoring suppliers with certified in-house fiber production.
Growth Catalysts
- MIL-STD performance specifications:U.S. Department of Defense procurement mandates for lighter protective systems are pulling fiber volumes into qualified supply chains.
- Ballistic protection systems:Military end-users in NATO-aligned nations are specifying polybenzoxazole fibers for next-generation body armor and vehicle armor panels.
- EU Green Deal sustainability mandates:REACH chemical registration protocols are filtering out non-compliant polymer producers and consolidating market access for certified manufacturers.
Market Restraints
- Polyphosphoric acid feedstock volatility:Phosphorus supply concentration in China and Morocco creates input cost instability for spinning operations.
- Specialized reactor infrastructure:Multi-million dollar capital requirements for high-temperature polymerization limit new entrant participation.
- Aramid fiber substitution:DuPont Kevlar and Teijin Twaron maintain cost-performance advantages in lower-threat protection tiers.
Strategic Opportunities
- Commercial aerospace interiors:FAA flammability regulations for cabin materials are opening specification windows for thermally stable fibers in seat fabrics and insulation.
- India defense modernization:Ministry of Defence indigenization mandates under Make in India are creating localized demand for domestic fiber qualification.
- Composite processing integration:Convergence of automated fiber placement and thermoplastic matrix technologies is enabling structural component manufacturing.
Industry Challenges
- Polymer chemist scarcity:Expertise in rigid-rod aromatic heterocyclic synthesis resides at a handful of academic and corporate laboratories.
- REACH registration timelines:ECHA substance evaluation periods extend 18-36 months, locking capital in pre-revenue compliance phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polybenzoxazole Fibers Market |
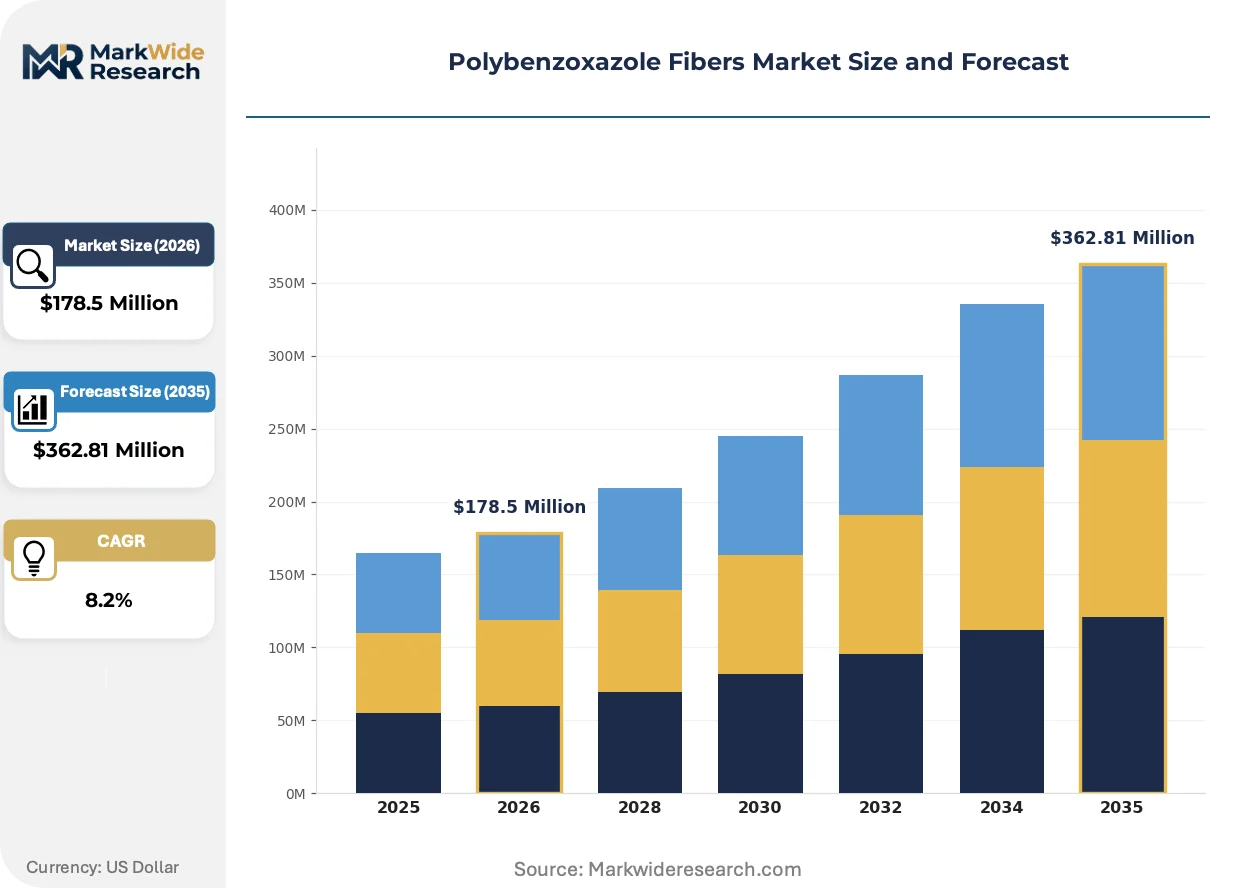
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $362.81 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
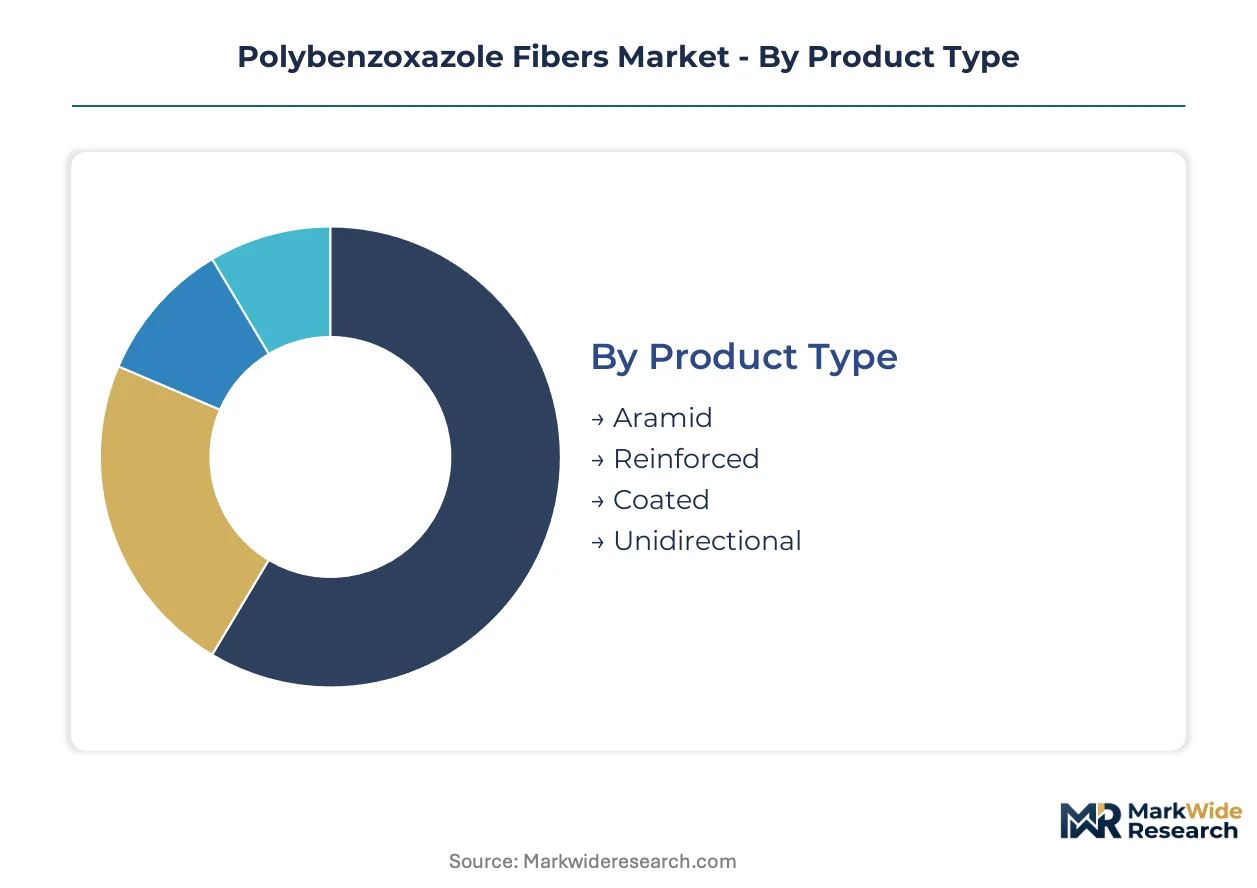
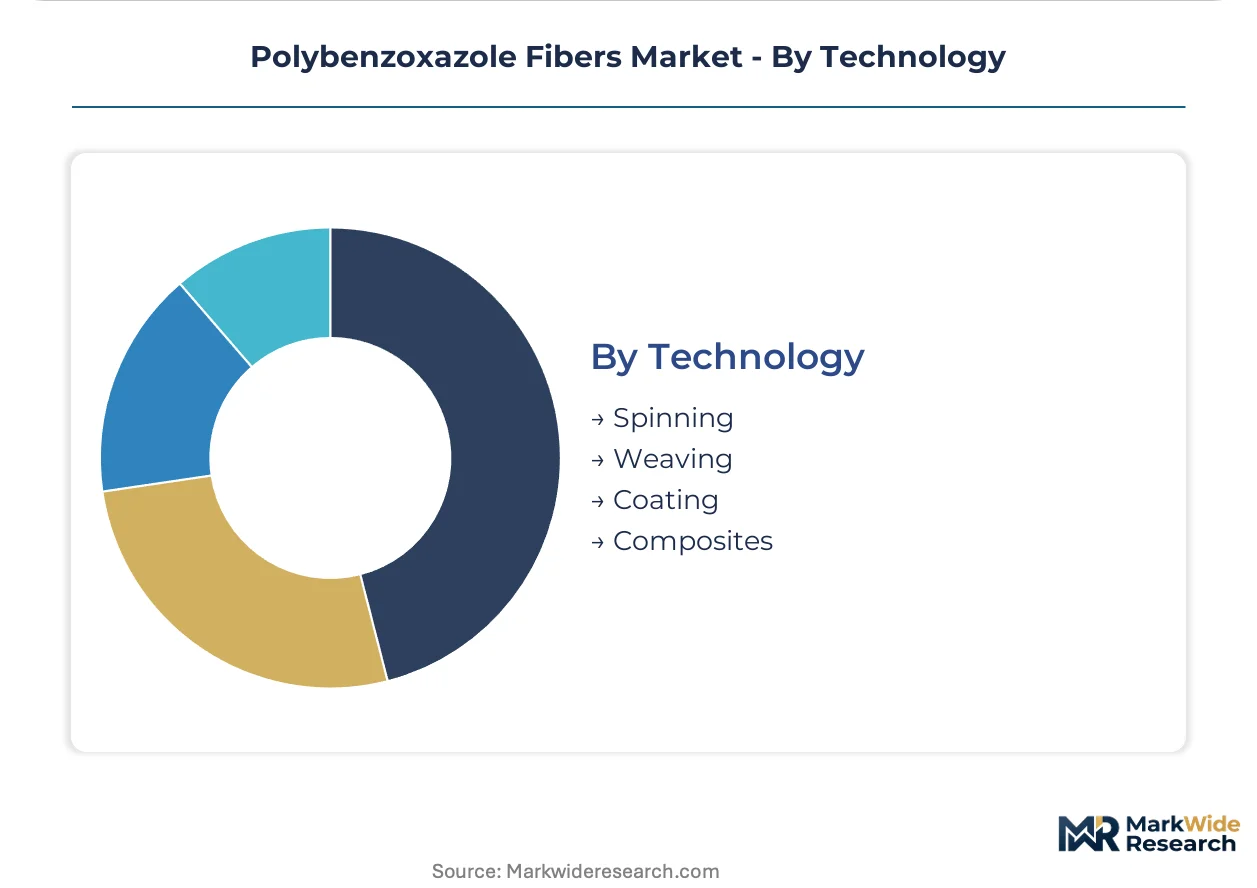
| Segmentation | Product Type: Aramid, Reinforced, Coated, Unidirectional Application: Aerospace, Electronics, Textiles, Transportation End User: Defense, Automotive, Construction, Healthcare Technology: Spinning, Weaving, Coating, Composites |
| Companies Covered | Evonik Industries AG, Fiber-Line, Toyobo Co., Ltd., Kermel, BIEGLO GmbH, DuPont, EuroFibers, SABIC, Yantai Tayho Advanced Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polybenzoxazole Fibers Market Strategic Shifts & Innovations
Process intensification and regulatory harmonization are reconfiguring how polybenzoxazole fibers move from specialty defense applications into broader industrial markets. Three developments merit particular attention.
Advanced composite processing is decentralizing supply chain control from fiber producers to tier-one aerospace and defense contractors. Automated fiber placement systems at BAE Systems and Lockheed Martin facilities are absorbing raw fiber directly into component manufacturing. This technology shift is compressing intermediate converter margins and forcing fiber producers to certify direct-supply relationships with end-users.
REACH chemical safety protocols in Europe are tightening purity benchmarks for polymer production facilities. ECHA substance evaluation requirements now mandate full toxicological profiles for processing aids used in polyphosphoric acid dopes. German and French aerospace manufacturers are demanding batch-level certification documentation, extending qualification cycles but locking in premium supplier relationships.
Defense procurement offices are consolidating vendor pools around vertically integrated fiber-to-fabric suppliers. Multi-year framework agreements with guaranteed volume minimums are displacing spot-market purchasing for ballistic protection programs. This behavioral shift is most visible in U.S. Army PEO Soldier programs and U.K. Ministry of Defence personal equipment directorates.
Polybenzoxazole Fibers Market Segmentation
Polybenzoxazole fiber buyers exhibit sharply divergent technical requirements across end-use categories. Defense contractors prioritize ballistic performance certification while aerospace OEMs demand flame-retardant compliance documentation.
Product Type:
Cost tier differentiation separates commodity-grade fibers from qualification-intensive specialty grades.
- Aramid:Blended polybenzoxazole-aramid hybrid constructions balance cost against thermal performance. U.S. Army PEO Soldier programs specify these blends for next-generation body armor to reduce unit weight while maintaining NIJ threat-level ratings.
- Reinforced:Multi-axial fiber architectures incorporate glass or carbon reinforcement layers for structural load-bearing applications. Airbus and Boeing cabin interior programs in Toulouse and Charleston drive specification development for seat frame composites.
- Coated:Surface-treated variants receive proprietary sizing chemistries for matrix adhesion in thermoset prepregs.
- Unidirectional:Aligned-fiber tapes optimize strength-to-weight ratios for helmet shell molding.
Aramid leads volumes today; reinforced is gaining share fastest.
Application:
Application selection correlates directly with regulatory exposure and certification cycle length.
- Aerospace:Cabin interior components must satisfy FAA FAR 25.853 flammability standards and EASA CS-25 smoke toxicity protocols. German aerospace manufacturers at Hamburg and Munich facilities now require batch-level REACH documentation from fiber suppliers.
- Electronics:Printed circuit board substrates and cable insulation exploit dielectric stability above 400°C. Japanese electronics assemblers in Osaka prefecture specify these fibers for 5G infrastructure thermal management layers.
- Textiles:Firefighter turnout gear and industrial protective clothing represent established demand channels.
- Transportation:High-speed rail interior panels in China follow GB/T 32379 flame-spread standards.
Aerospace commands premium pricing; electronics shows steepest expansion trajectory.
End User:
Customer procurement maturity determines contract structure and supplier qualification burden.
- Defense:Multi-year framework agreements with guaranteed volume minimums dominate NATO-aligned procurement. U.K. Ministry of Defence personal equipment directorates now mandate in-country fiber qualification testing at QinetiQ facilities.
- Automotive:Motorsport brake shrouds and EV battery thermal barriers create specification openings. Ferrari and McLaren racing divisions in Maranello and Woking specify polybenzoxazole composites for peak temperature zones.
- Construction:Structural reinforcement of concrete and seismic bracing systems utilize fiber mesh.
- Healthcare:Surgical robot armatures and imaging equipment housings exploit dimensional stability.
Defense absorbs the highest unit volumes; automotive is climbing the fastest.
Technology:
Process capability separates integrated fiber producers from downstream converters.
- Spinning:Dry-jet wet spinning of polyphosphoric acid dopes demands specialized reactor infrastructure and polymer chemistry expertise. Toyobo's Tsuruga facility maintains proprietary process control for aerospace-grade fiber production.
- Weaving:Multi-layer fabric architectures for ballistic panels require loom modifications for high-modulus yarn handling. Yantai Tayho's Shandong operations have commissioned dedicated weaving lines for military textile output.
- Coating:Matrix-compatible sizing application occurs at fiber finishing stages.
- Composites:Automated fiber placement and resin transfer molding integrate raw fiber directly into structural components.
Spinning captures value upstream; composites is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting polybenzoxazole fiber production toward jurisdictions with lower compliance costs. Manufacturers face divergent chemical safety regimes that reshape investment location decisions.
United States
Defense procurement through U.S. Army PEO Soldier programs absorbs substantial fiber volumes for next-generation body armor. FAA FAR 25.853 flammability standards govern aerospace applications, with Boeing Charleston and Airbus Mobile facilities driving specification development. Huntsville and Dallas-Fort Worth clusters concentrate ballistic panel fabrication.
China
Domestic capacity for advanced polymer fibers is expanding rapidly under GB standards and dual carbon goals. MIIT energy intensity rules tighten production facility compliance requirements. Yantai Tayho's Shandong operations anchor military textile output with dedicated weaving lines.
Germany
ECHA REACH substance evaluation mandates full toxicological profiles for polyphosphoric acid processing aids. Hamburg and Munich aerospace manufacturers now require batch-level certification documentation. Bavarian industrial clusters specialize in high-temperature polymerization reactor infrastructure.
Japan
Japanese polymer producers consolidate output of high-modulus fibers for aerospace and defense applications. METI industrial policy supports rigid-rod aromatic heterocyclic synthesis capabilities. Toyobo's Tsuruga facility maintains proprietary dry-jet wet spinning process control.
India
Ministry of Defence indigenization mandates under Make in India create localized demand for domestic fiber qualification. BIS standards govern industrial protective clothing specifications. QinetiQ facilities conduct in-country fiber qualification testing for U.K. Ministry of Defence personal equipment programs.
Polybenzoxazole Fibers Market Key Industry Players
Japanese producers anchor the premium fiber tier; Chinese specialists hold expanding industrial-grade capacity. The vendor base concentrates around vertically integrated polymer chemists with captive spinning technology. Three archetypes dominate: aerospace-grade specialists, defense-qualified fabricators, and industrial-volume suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure qualified supply chain positions.
Within the aerospace-grade tier, Toyobo Co., Ltd. and DuPont exemplify technology-intensive positioning through proprietary process control and broad patent coverage. Yantai Tayho Advanced Materials Co., Ltd. anchors the industrial-volume archetype with expanding Asian production footprint. These three firms represent distinct strategic postures: Japanese precision manufacturing, American chemical conglomerate breadth, and Chinese scale-driven expansion.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Fiber-Line |
| Toyobo Co., Ltd. |
| Kermel |
| BIEGLO GmbH |
| DuPont |
| EuroFibers |
| SABIC |
| Yantai Tayho Advanced Materials Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EU Green Deal sustainability mandates gate qualified supply and premium-tier pricing access for polybenzoxazole fiber producers. REACH chemical registration requirements filter out non-compliant manufacturers, consolidating market access for certified European suppliers who command pricing premiums. Defense procurement offices in NATO-aligned nations absorb higher unit costs for qualified fiber-to-fabric supply chains.
Pricing Analysis
Distributor margins compress as defense contractors consolidate procurement around direct-to-OEM supply relationships. Contract-based long-term offtake agreements dominate defense end-use, with pricing stratifying across aerospace-grade, defense-qualified, and industrial-grade tiers. Cost compression in industrial-grade segments intensifies due to Chinese capacity expansion. Defense contractors exhibit lowest price sensitivity; commercial textile converters face highest pressure.
Supply Chain Analysis
Refurbishment flows for ballistic panel recycling remain underdeveloped, creating end-of-life liability for defense contractors. Production concentrates in Japan, China, and the United States. Polyphosphoric acid dopes and high-temperature polymerization reactors anchor raw material dependencies. Single-source vulnerability in phosphorus feedstock from China and Morocco threatens input stability. Distribution runs through qualified fiber-to-fabric suppliers with certified weaving and composite processing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polybenzoxazole fibers function as a stable compounder anchored by defense procurement cycles for multi-threat ballistic systems. Military modernization programs across NATO-aligned nations sustain predictable volume growth.
For Market Incumbents: Extend patent coverage across rigid-rod aromatic heterocyclic chemistries to block substitute fiber encroachment. Deepen upstream control over polyphosphoric acid supply through captive phosphorus sourcing or long-term offtake agreements with Moroccan suppliers. Aramid fiber substitution in lower-threat protection tiers represents the primary margin pressure point. For New Entrants and Emerging Players: Enter via commercial aerospace interiors certification, where FAA flammability regulations create specification windows for thermally stable fibers. Target seat fabric and insulation applications at Boeing Charleston and Airbus Mobile facilities. Pursue direct qualification with tier-one aerospace OEMs rather than converter channels. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated fiber-to-fabric specialists because defense procurement offices are consolidating vendor pools around qualified suppliers with in-house spinning and weaving capabilities. Five-to-ten year viability hinges on sustained defense modernization budgets and aerospace fleet renewal cycles. Monitor U.S. Army PEO Soldier program budget allocations as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polyphosphoric acid production insulates Toyobo and DuPont from phosphorus price volatility. |
| Capacity Expansion | Yantai Tayho's Shandong weaving lines capture Make in India defense indigenization demand. |
| Long-term Supply Agreement | Multi-year framework contracts with U.K. Ministry of Defence lock in volume minimums for qualified suppliers. |
| Green Manufacturing Transition | REACH-compliant process redesign opens premium pricing access for German and French aerospace manufacturers. |
| Joint Venture | Automated fiber placement partnerships with BAE Systems and Lockheed Martin compress intermediate converter margins. |
Research Approach
Bottom-up defense and aerospace modeling reconciled against top-down polymer capacity tracking forms the analytical core of this study. Primary interviews with fiber plant managers, defense procurement officers at PEO Soldier and U.K. Ministry of Defence, aerospace technical directors at Boeing and Airbus, and distribution channel partners informed demand-side assumptions. Secondary validation drew from ECHA substance registration databases, U.S. Department of Defense budget justification documents, FAA certification filings, and customs trade data for polybenzoxazole fiber imports.
Historical trendline analysis across defense procurement cycles and aerospace build rates established baseline growth patterns. Segmentation modeling captured product type tiers, application-specific regulatory exposure, end-user procurement maturity, and technology integration levels. CAGRs were derived from volume trajectory fitting against qualified supplier capacity expansion timelines. Forecast inputs incorporated MIL-STD specification adoption curves and REACH registration completion schedules.
Inputs from defense procurement databases and aerospace OEM qualification records were available through the study window; gaps in commercial textile converter shipment data introduce uncertainty bands around industrial-grade segment estimates. Forecasts reflect documented assumptions regarding sustained NATO defense spending and stable phosphorus feedstock availability. Practitioners should monitor U.S. Congressional defense appropriations and ECHA substance evaluation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Spandex Fiber Market