
 Asia-Pacific Lyocell Fibers Market | 2026-2036
Asia-Pacific Lyocell Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lyocell Fibers Market Insights
Project finance tied to green bond issuance is narrowing the pool of lyocell producers capable of funding NMMO solvent-recovery expansions. Lenzing AG leverages its integrated pulp-to-fiber Austrian-Asian supply corridors to sustain cost advantages across multiple plant locations. Sateri anchors regional viscose-to-lyocell transition capacity through its Fujian and Jiangxi manufacturing bases. Aditya Birla Group competes via its Grasim Industries subsidiary, which controls dissolving wood pulp sourcing that feeds lyocell co-production lines.
Asia-Pacific lyocell fibers are regenerated cellulosic filaments produced through direct dissolution of wood pulp in N-methylmorpholine-N-oxide (NMMO), a non-derivatizing solvent that enables closed-loop recovery rates exceeding 99% in optimized systems. The resulting fibers exhibit high tenacity, moisture management, and biodegradability, making them suitable for textile applications requiring performance alongside environmental credentials. Apparel dominates current offtake volumes, while medical textiles represent the fastest-growing application segment as hospitals specify lyocell for surgical gowns and wound-care substrates that balance barrier properties with compostability. Activewear commands premium positioning among distribution channels, with specialty stores capturing margin pools through sustainability certification storytelling that wholesale transactions cannot replicate.
China's SAMR enforces GB/T standards for regenerated cellulose fiber labeling, while REACH-aligned substance restrictions in South Korea and Japan's JIS L 1902 antibacterial testing protocols shape product specifications for cross-border shipments. India's BIS certification requirements for imported textile raw materials create additional compliance layers that favor producers with established testing partnerships. Stakeholders must monitor how evolving extended producer responsibility frameworks across ASEAN jurisdictions will reshape post-consumer collection obligations and fiber-to-fiber recycling economics.
Market Dynamics
China's GB standards for textile sustainability and solvent recovery mandates are compressing the producer base, forcing facility upgrades that only capitalized operators can fund while regional fashion brands accelerate lyocell procurement for certified apparel lines.
Growth Catalysts
- Activewear specification:Sustainable fashion brands across East Asia are embedding lyocell into performance apparel lines, creating pull-through demand from Shanghai and Zhejiang textile clusters.
- SAMR labeling enforcement:China's GB/T standards for regenerated cellulose fiber labeling are mandating traceability infrastructure that favors compliant producers with existing testing partnerships.
- NMMO solvent recovery:Closed-loop recovery systems exceeding 99% efficiency are reducing environmental compliance costs and enabling premium positioning in medical textile applications.
Market Restraints
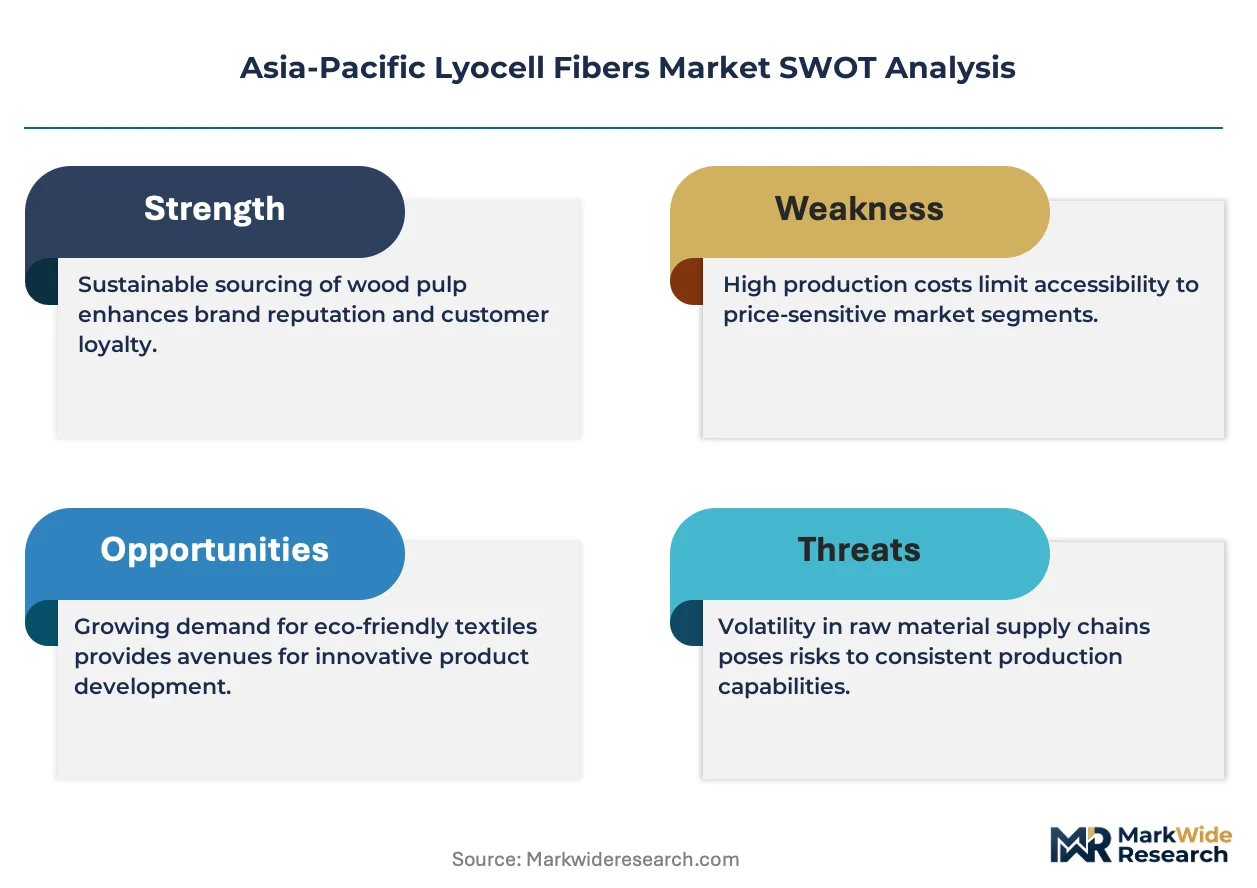
- Dissolving pulp concentration:Sourcing of dissolving wood pulp concentrates among integrated pulp-to-fiber operators, creating input cost volatility for non-integrated lyocell producers.
- Green bond financing scarcity:Project finance tied to sustainability-linked issuance is narrowing the pool of producers capable of funding NMMO solvent-recovery expansions.
- Viscose substitution pressure:Lower-cost viscose fibers continue to capture price-sensitive apparel volumes, compressing lyocell penetration in undifferentiated textile segments.
Strategic Opportunities
- Medical textile specification:Hospitals across South Korea and Japan are specifying lyocell for surgical gowns and wound-care substrates that balance barrier properties with compostability.
- Extended producer responsibility:Evolving EPR frameworks across ASEAN jurisdictions will reshape post-consumer collection obligations and create first-mover advantages in fiber-to-fiber recycling infrastructure.
- Specialty store channel expansion:Sustainability certification storytelling through specialty retail captures margin pools that wholesale transactions cannot replicate.
Industry Challenges
- NMMO process engineering talent:Scarcity of chemical engineers with direct dissolution expertise constrains capacity expansion timelines for new market entrants.
- Cross-border certification complexity:India's BIS requirements for imported textile raw materials create testing timeline friction that favors producers with established laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lyocell Fibers Market |
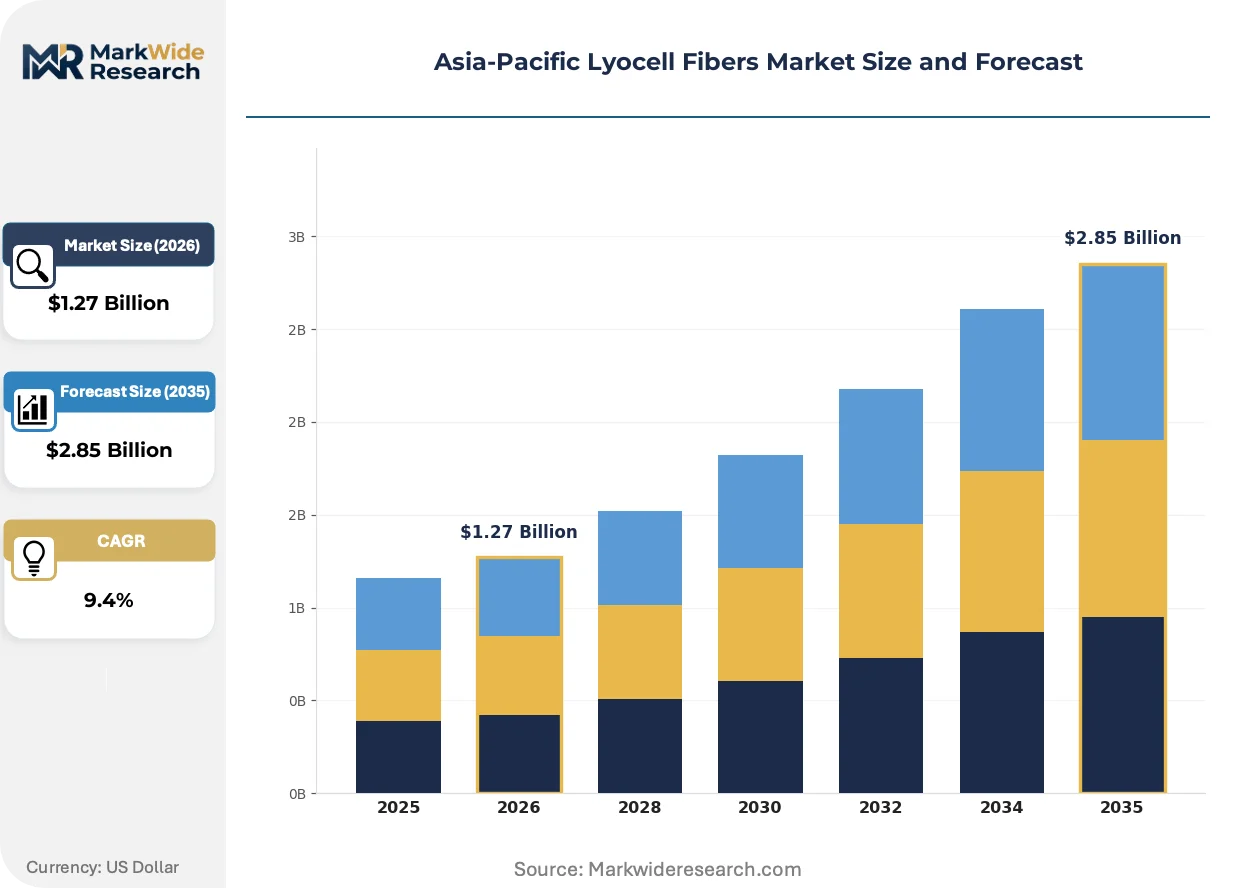
| Market Size in 2026 | $1.27 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Textiles, Industrial Fabric, Non-Woven End User: Fashion Brands, Textile Manufacturers, Retailers, Wholesalers Application: Activewear, Casual Wear, Upholstery, Medical Textiles Distribution Channel: Online Retail, Specialty Stores, Wholesale, Department Stores |
| Companies Covered | AceGreen Eco-Material Technology Co., Ltd., Tangshan Sanyou Xingda Chemical Fibre Co. Ltd., Sateri, Chonbang Co. Ltd., Qingdao Textiles Group Fiber Technology Co. Ltd., Aditya Birla Group, Baoding Swan Fiber Co. Ltd., Shanghai Lyocell Fibers, Lenzing AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lyocell Fibers Market Trends and Innovations
Direct dissolution technologies and closed-loop solvent systems are reconfiguring competitive economics in regenerated cellulosic fibers, while regulatory pressure on textile waste accelerates substitution away from petroleum-based synthetics.
Single-step lyocell production with integrated NMMO recovery is rendering obsolete conventional multi-stage viscose processes that rely on carbon disulfide chemistry. Activewear manufacturers in South Korea and Japan are adopting these fibers at accelerated specification rates. The technology is compressing capital requirements for sustainable fiber production while raising barriers for legacy viscose operators.
China's MEE enforcement of dual carbon goals is tightening emissions thresholds for chemical fiber manufacturing. Industrial consequence includes mandatory energy audits and carbon intensity disclosures for facilities above designated capacity thresholds. Producers in Fujian and Jiangxi provinces are responding with on-site renewable power purchase agreements and process heat recovery retrofits.
Hospital procurement committees are embedding compostability metrics into surgical textile specifications alongside barrier performance criteria. Wholesale distributors serving institutional healthcare channels are losing share to direct manufacturer relationships that provide batch-level biodegradability certification. This specification shift is most visible in Japan's metropolitan hospital systems and South Korea's national health service purchasing consortia.
Asia-Pacific Lyocell Fibers Market Segmentation
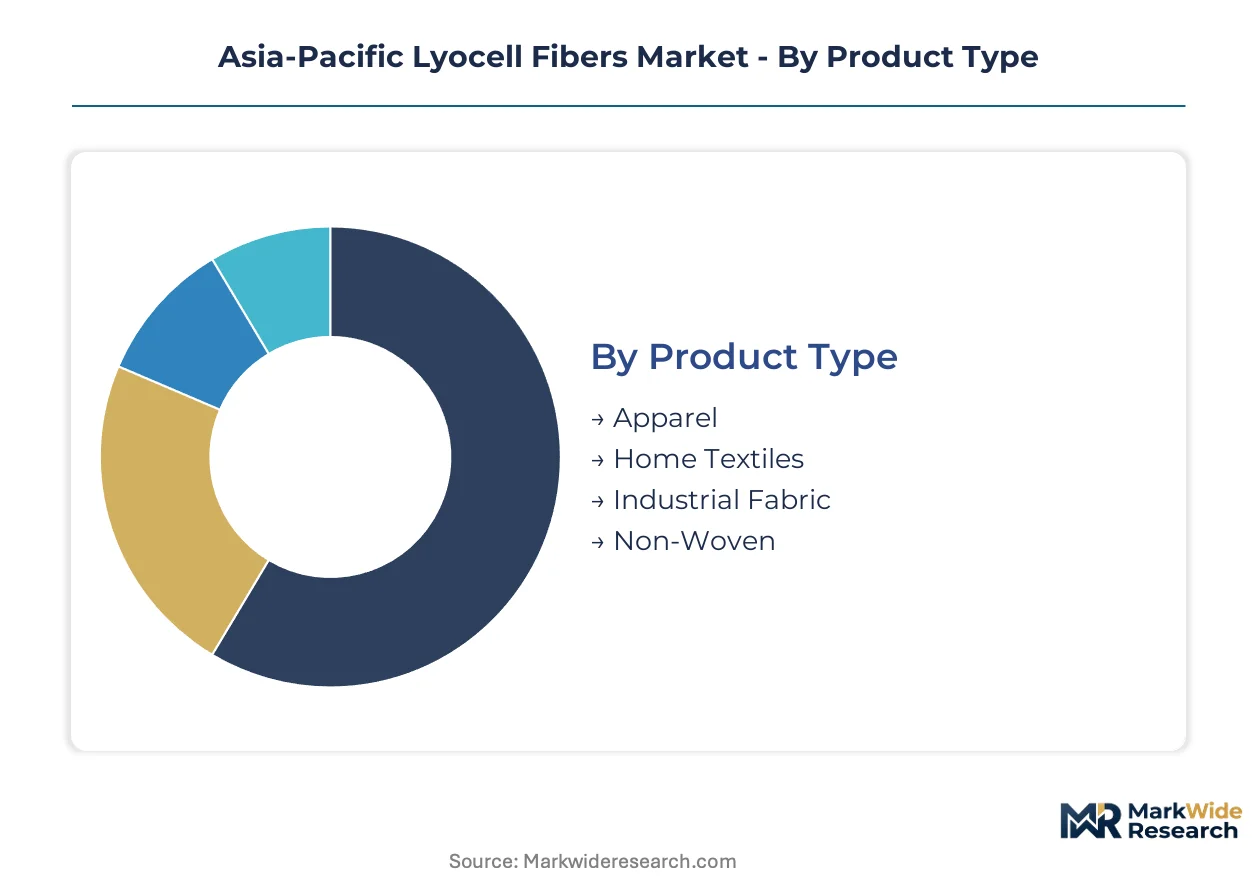
Segmentation reveals how lyocell fiber specifications diverge across procurement cycles, with fashion brand orders turning over fastest while medical textile contracts lock in multi-year supply agreements. Understanding these velocity patterns enables producers to align inventory positioning with demand cadence.
Product Type:
Cycle times compress from weeks for apparel replenishment to years for industrial fabric specifications, creating divergent working capital requirements across product categories.
- Apparel:Fine-denier staple fibers engineered for softness and drape dominate this segment. Shanghai and Zhejiang textile clusters absorb the majority of regional volume as sustainable fashion brands accelerate certified line launches. SAMR labeling enforcement under GB/T standards is mandating traceability infrastructure that favors compliant suppliers.
- Home Textiles:Higher-denier variants with enhanced durability specifications serve bedding and towel applications. Procurement concentrates through direct manufacturer relationships with institutional hospitality buyers seeking batch-level biodegradability certification.
- Industrial Fabric:Technical-grade filaments with elevated tenacity for filtration and reinforcement applications.
- Non-Woven:Short-cut fibers optimized for hydroentanglement processes in wipes and hygiene products.
Apparel anchors the volume base while medical textile applications gain share at the steepest rate.
End User:
Margin structures diverge sharply between direct brand relationships and intermediary channels, with ownership of sustainability certification storytelling determining pricing power.
- Fashion Brands:Direct specification of lyocell blends for activewear and casual lines drives premium positioning. East Asian sustainable fashion houses embed fiber provenance into consumer-facing marketing, capturing margin pools unavailable to wholesale transactions.
- Textile Manufacturers:Intermediate processors converting staple fiber into yarn and fabric for downstream apparel producers. Fujian and Jiangjiang manufacturing bases anchor regional viscose-to-lyocell transition capacity.
- Retailers:Private label programs at specialty stores and department stores create pull-through demand for certified lyocell assortments.
- Wholesalers:Volume distributors serving price-sensitive undifferentiated textile segments where viscose substitution pressure compresses lyocell penetration.
Fashion brands command the steepest expansion trajectory while wholesalers defend legacy volume through price-competitive positioning.
Application:
Performance requirements stratify from moisture-management activewear through barrier-property medical specifications, each demanding distinct fiber engineering and certification protocols.
- Activewear:High-tenacity fibers with engineered moisture wicking and breathability specifications. South Korean and Japanese manufacturers specify these materials at accelerated rates for performance apparel lines.
- Casual Wear:Standard-denier staple fibers prioritizing softness and drape for everyday apparel. China's GB standards for textile sustainability are accelerating procurement from compliant domestic producers.
- Upholstery:Durable filament grades with abrasion resistance for furniture and automotive applications.
- Medical Textiles:Surgical gowns and wound-care substrates balancing barrier properties with compostability. Japan's metropolitan hospital systems and South Korea's national health service purchasing consortia are embedding biodegradability metrics alongside performance criteria.
Casual wear retains the largest volume position while medical textiles climb the fastest on institutional specification shifts.
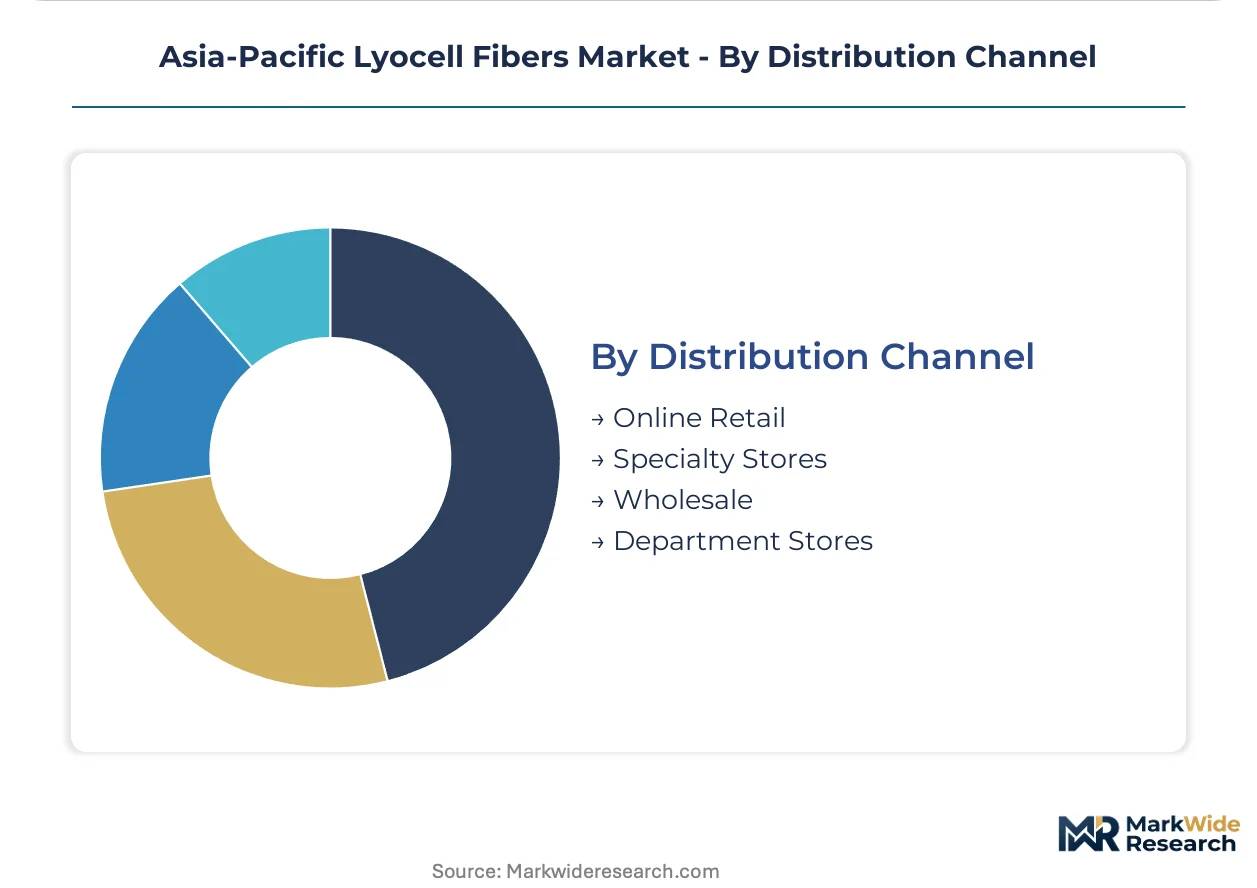
Distribution Channel:
Channel economics separate sustainability-premium capture at specialty retail from volume-driven wholesale transactions, with online retail emerging as a hybrid pathway.
- Online Retail:Direct-to-consumer platforms enabling fiber provenance transparency and certification storytelling. Digital channels bypass wholesale margin extraction for vertically integrated brands.
- Specialty Stores:Curated sustainability assortments with batch-level certification documentation. These outlets capture margin pools through exclusive supplier relationships that mass channels cannot replicate.
- Wholesale:Volume distributors serving undifferentiated textile segments where price competition favors lower-cost viscose alternatives.
- Department Stores:Mid-tier retail positioning with private label lyocell programs targeting mass-market sustainability consciousness.
Wholesale channels retain the broadest volume base while specialty stores expand most quickly on premium sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium capture concentrates in Japan and South Korea, while Chinese producers compete on scale and compliance velocity. Price differentiation between these markets exceeds standard freight differentials, reflecting certification premiums and solvent-recovery infrastructure gaps.
China
Shanghai and Zhejiang textile clusters absorb the majority of regional lyocell volume as sustainable fashion brands accelerate certified line launches. SAMR enforces GB/T standards for regenerated cellulose fiber labeling, mandating traceability infrastructure that favors compliant domestic producers. Fujian and Jiangxi manufacturing bases anchor the regional viscose-to-lyocell transition capacity.
Japan
Metropolitan hospital systems specify lyocell for surgical gowns and wound-care substrates that balance barrier properties with compostability. METI oversees JIS L 1902 antibacterial testing protocols that shape product specifications for cross-border shipments. Tokyo and Osaka-based specialty stores capture margin pools through sustainability certification storytelling that wholesale channels cannot replicate.
South Korea
Activewear manufacturers specify high-tenacity lyocell fibers at accelerated rates for performance apparel lines. MFDS-aligned substance restrictions govern medical textile imports, creating compliance layers that favor producers with established testing partnerships. Seoul Capital Area procurement committees embed compostability metrics alongside barrier performance criteria.
India
Grasim Industries controls dissolving wood pulp sourcing that feeds lyocell co-production lines through backward integration into fiber manufacturing. BIS certification requirements for imported textile raw materials create testing timeline friction that favors producers with established laboratory partnerships. Maharashtra and Gujarat textile hubs concentrate domestic conversion capacity.
Vietnam
Garment export manufacturers source lyocell staple for EU-bound activewear and casual apparel lines seeking REACH-aligned fiber credentials. The country's national textile regulator enforces traceability documentation for EU Green Deal compliance. Ho Chi Minh City and Hanoi industrial zones host expanding cut-make-trim operations specifying certified sustainable inputs.
Asia-Pacific Lyocell Fibers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pulp supply and solvent recovery. The producer base concentrates around capitalized operators capable of funding NMMO solvent-recovery expansions through green bond issuance. Three archetypes dominate: integrated pulp-to-fiber operators, viscose transition specialists, and regional chemical conglomerates with captive dissolving pulp. Competitive moves center on backward integration into dissolving wood pulp and geographic expansion through ASEAN manufacturing partnerships.
Among Austrian-Asian supply corridor operators, Lenzing AG exemplifies the integrated archetype with multiple plant locations. Sateri occupies a position within the viscose-to-lyocell transition specialist tier through its Fujian and Jiangxi manufacturing bases. Aditya Birla Group anchors the regional chemical conglomerate segment via Grasim Industries, which controls upstream dissolving wood pulp sourcing.
| Leading Market Players |
|---|
| AceGreen Eco-Material Technology Co., Ltd. |
| Tangshan Sanyou Xingda Chemical Fibre Co. Ltd. |
| Sateri |
| Chonbang Co. Ltd. |
| Qingdao Textiles Group Fiber Technology Co. Ltd. |
| Aditya Birla Group |
| Baoding Swan Fiber Co. Ltd. |
| Shanghai Lyocell Fibers |
| Lenzing AG |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Austrian-Asian pulp-to-fiber supply corridors determines both pricing tier spreads and supply chain shape across the Asia-Pacific lyocell market. NMMO solvent recovery infrastructure gaps between integrated operators and transition specialists compress margins for non-capitalized producers while amplifying premium capture at compliant facilities.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure with three-tier differentiation across premium certified, standard compliant, and economy viscose-substitute grades. Price differentiation stems from GB/T traceability certification level and volume scale commitments to Shanghai textile clusters. Cost compression in the economy tier is intensifying because lower-cost viscose fibers capture price-sensitive apparel volumes. Wholesale distributors serving undifferentiated segments exhibit highest price sensitivity while specialty stores capturing sustainability premiums show lowest.
Supply Chain Analysis
Tariff exposure between China and ASEAN garment export destinations dominates supply chain risk calculations for lyocell staple procurement. Manufacturing concentrates in China, Austria, and Indonesia with dissolving wood pulp sourcing anchored in South American and Southeast Asian plantation forestry. Raw material dependencies center on NMMO solvent chemistry, specialized wood pulp grades, and carbon-neutral energy inputs. Distribution runs through direct manufacturer relationships with East Asian fashion brands and institutional healthcare procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific lyocell market sits in a cyclical recovery phase driven by post-pandemic sustainable fashion brand restocking and medical textile specification upgrades across East Asian hospital systems.
For Market Incumbents: Entrench NMMO solvent-recovery capacity advantages through Fujian and Jiangxi facility upgrades before GB standards tighten further. Lock in multi-year dissolving pulp offtake agreements with South American suppliers to defend against input cost volatility from Grasim Industries' captive sourcing. Prioritize JIS L 1902 antibacterial certification investment to capture Japanese medical textile premiums. For New Entrants and Emerging Players: Vietnam's garment export manufacturing zones represent the most penetrable geography for EU-bound lyocell staple supply seeking REACH-aligned fiber credentials. Target Ho Chi Minh City cut-make-trim operations with batch-level biodegradability documentation as the go-to-market wedge. Avoid direct confrontation with Lenzing AG's integrated Austrian-Asian supply corridors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors viscose-to-lyocell transition specialists with existing NMMO process engineering talent. Long-term viability across the next decade hinges on fiber-to-fiber recycling infrastructure positioning under evolving ASEAN extended producer responsibility frameworks. Watch for SAMR enforcement actions against non-compliant domestic producers as the inflection signal for competitive share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| NMMO Solvent-Recovery Capacity Expansion | GB standards compliance under SAMR enforcement mandates facility upgrades exceeding 99% closed-loop efficiency thresholds. |
| Backward Integration into Dissolving Wood Pulp | Captive pulp sourcing from South American plantations insulates Grasim Industries and Lenzing AG from input cost volatility. |
| Medical Textile Certification Investment | JIS L 1902 antibacterial protocols and MFDS-aligned substance restrictions unlock Japanese and South Korean hospital procurement. |
| Fiber-to-Fiber Recycling Infrastructure | ASEAN extended producer responsibility frameworks will reshape post-consumer collection economics for first-movers. |
| Direct Manufacturer Relationship Development | Bypassing wholesale distributors enables batch-level biodegradability certification storytelling at specialty retail. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Fujian and Jiangxi manufacturing bases, procurement leads at Shanghai textile clusters, and regulatory affairs specialists navigating SAMR GB/T standards; alongside secondary validation through customs/trade data, SEC 10-K filings from listed fiber producers, and MEE carbon intensity disclosure records. Bottom-up fiber production estimates triangulated against top-down apparel demand projections from East Asian sustainable fashion brands.
Forecast inputs considered grade tier segmentation across fine-denier staple and technical-grade filaments, end-use industry splits between apparel and medical textiles, and regional production hub differentiation across China, Japan, and South Korea. CAGRs were derived from demand elasticity modeling against solvent-recovery capacity buildout timelines. Industry-specific inputs included NMMO process engineering talent availability and green bond issuance velocity for sustainability-linked project finance.
The forecast holds incumbent behavior within observed patterns; aggressive moves by regional chemical conglomerates with captive dissolving pulp would shift outcomes through accelerated price competition. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Fiberglass Roving Market