
 Global High Performance Fibers Market | 2026-2036
Global High Performance Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Fibers Market Foresight
Japanese carbon fiber producers is shifting capacity toward aerospace-grade precursors as commercial aviation recovers. Toray Industries leverages vertical integration from PAN precursor to carbon fiber to control quality and cost across the value chain. Teijin Ltd. anchors its position in aramid fibers through sustained investment in ballistic protection and industrial rope applications. DuPont competes in the para-aramid segment with Kevlar, specializing in protective apparel and automotive reinforcement markets.
High performance fibers are engineered synthetic filaments with tensile strength exceeding 3 GPa and modulus above 50 GPa, manufactured through controlled pyrolysis of polyacrylonitrile, aromatic polyamides, or ultra-high molecular weight polyethylene to deliver thermal stability, chemical resistance, and specific strength superior to steel. Carbon fiber dominates value generation due to its irreplaceable stiffness-to-weight ratio in primary aircraft structures and wind turbine blades, while aramid retains margin strength in military and first-responder protective equipment where cut and ballistic resistance are non-negotiable. Glass fiber occupies the volume base in construction and marine composites, though pricing pressure from Chinese supply limits profitability for non-differentiated grades.
The FAA certifies carbon fiber composite airframes under Part 25 standards, extending design approval timelines that lock in supplier relationships for decades. REACH and the EU Green Deal impose lifecycle carbon accounting on fiber imports, reshaping procurement criteria for European automotive OEMs and energy producers. OSHA mandates for flame-resistant protective clothing sustain aramid demand in North American industrial workplaces. Stakeholders must monitor regulatory divergence between EPA emissions rules and EU carbon border adjustments, as compliance fragmentation threatens to bifurcate supply chains into region-specific qualification tracks.
Market Dynamics
Carbon fiber precursor supply concentration in Japan and China is compressing margin capture for downstream composite fabricators, forcing aerospace and wind energy buyers to secure long-term offtake agreements or backward-integrate into PAN production.
Growth Catalysts
- EU Green Deal carbon accounting:Lifecycle emissions mandates for imported materials are redirecting European automotive procurement toward certified low-carbon fiber sources, accelerating qualification of alternative precursors.
- Wind turbine blade scaling:Offshore installations exceeding 15 MW require longer carbon fiber spar caps, pulling additional aerospace-grade tow capacity into energy applications.
- China:Domestic carbon fiber capacity expansion for electric vehicle battery enclosures and hydrogen pressure vessels is reducing import dependency and reshaping Asia-Pacific supply flows.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs track propylene-ammonia spreads, exposing fiber producers to petrochemical feedstock swings without pass-through mechanisms in long-term aerospace contracts.
- Japanese precursor concentration:Three producers control majority aerospace-grade PAN supply, creating single-source vulnerability for qualified carbon fiber manufacturers outside East Asia.
- Recycling technical limits:Pyrolysis recovery degrades fiber modulus, preventing closed-loop reuse in primary structural applications and forcing landfill or downcycling outcomes.
Strategic Opportunities
- India industrial protection:PLI scheme incentives for domestic advanced materials manufacturing offer first-mover positioning for aramid and carbon fiber production serving defense and infrastructure markets.
- Thermoplastic composite welding:Induction and ultrasonic joining technologies are eliminating adhesive bonding steps, enabling out-of-autoclave processing for automotive structural components at cycle times compatible with mass production.
- FAA streamlined certification:Updated policy for composite damage tolerance analysis reduces airframe amendment timelines, lowering barriers for new material suppliers to enter qualified vendor lists.
Industry Challenges
- Composite repair technician scarcity:FAA-approved NDT and scarf repair certification programs produce fewer qualified technicians than airline fleet expansion requires, extending aircraft downtime for carbon fiber damage events.
- Multi-tier qualification synchronization:Airframe OEMs, Tier 1 fabricators, and material suppliers maintain misaligned certification schedules, delaying new fiber grade adoption across the value chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Fibers Market |
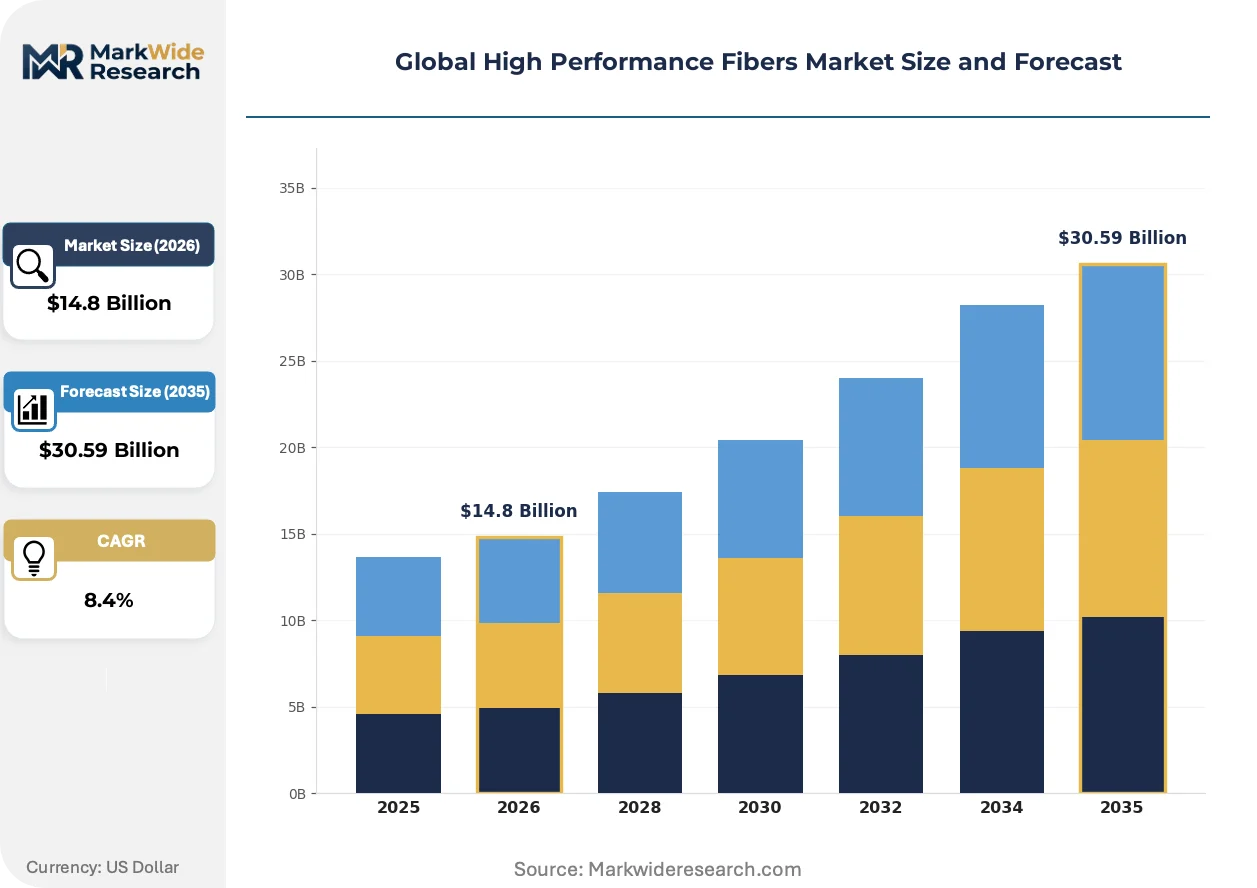
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aramid, Carbon Fiber, Glass Fiber, Basalt Fiber, Polyethylene, Inorganic Fiber Application: Aerospace, Sporting Goods, Military Equipment, Industrial Textiles, Protective Clothing, Composites End User Industry: Automotive OEMs, Apparel Manufacturers, Construction Firms, Marine Assemblers, Electronics Producers, Energy Producers Form: Continuous Fiber, Staple Fiber, Tow, Fabric, Yarn, Roving |
| Companies Covered | Toray Industries, Inc., Teijin Ltd., DuPont, Honeywell International Inc., Hexcel Corporation, Mitsubishi Chemical Corporation, SGL Carbon, Solvay, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Fibers Market Shifts & Advancements
Process intensification and regulatory carbon accounting are converging to redefine competitive advantage in fiber manufacturing, favoring producers with integrated energy recovery and captive renewable power.
Recycled carbon fiber from aerospace manufacturing scrap is absorbing growing volumes in automotive non-structural applications. BMW and Mercedes-Benz chassis component programs now specify reclaimed fiber for underbody shields and battery trays. This absorption is compressing virgin fiber demand in price-sensitive automotive segments while creating parallel supply chains with distinct qualification requirements.
REACH substance restrictions on solvent-based sizing chemistries are forcing fiber producers to reformulate surface treatments. ECHA hazard classifications for traditional epoxy-compatible finishes are accelerating water-based and plasma-activated alternatives. European wind blade manufacturers are most affected, rescheduling lamination process validations to maintain CE marking compliance.
Buyers in defense and aerospace are consolidating supplier panels around dual-source requirements with unified qualification standards. Long-term sole-source contracts are giving way to parallel development agreements with two qualified fiber producers per specification grade. This pattern is most visible in US Department of Defense airframe programs, where congressional sourcing mandates now override traditional vendor loyalty.
Global High Performance Fibers Market Segmentation
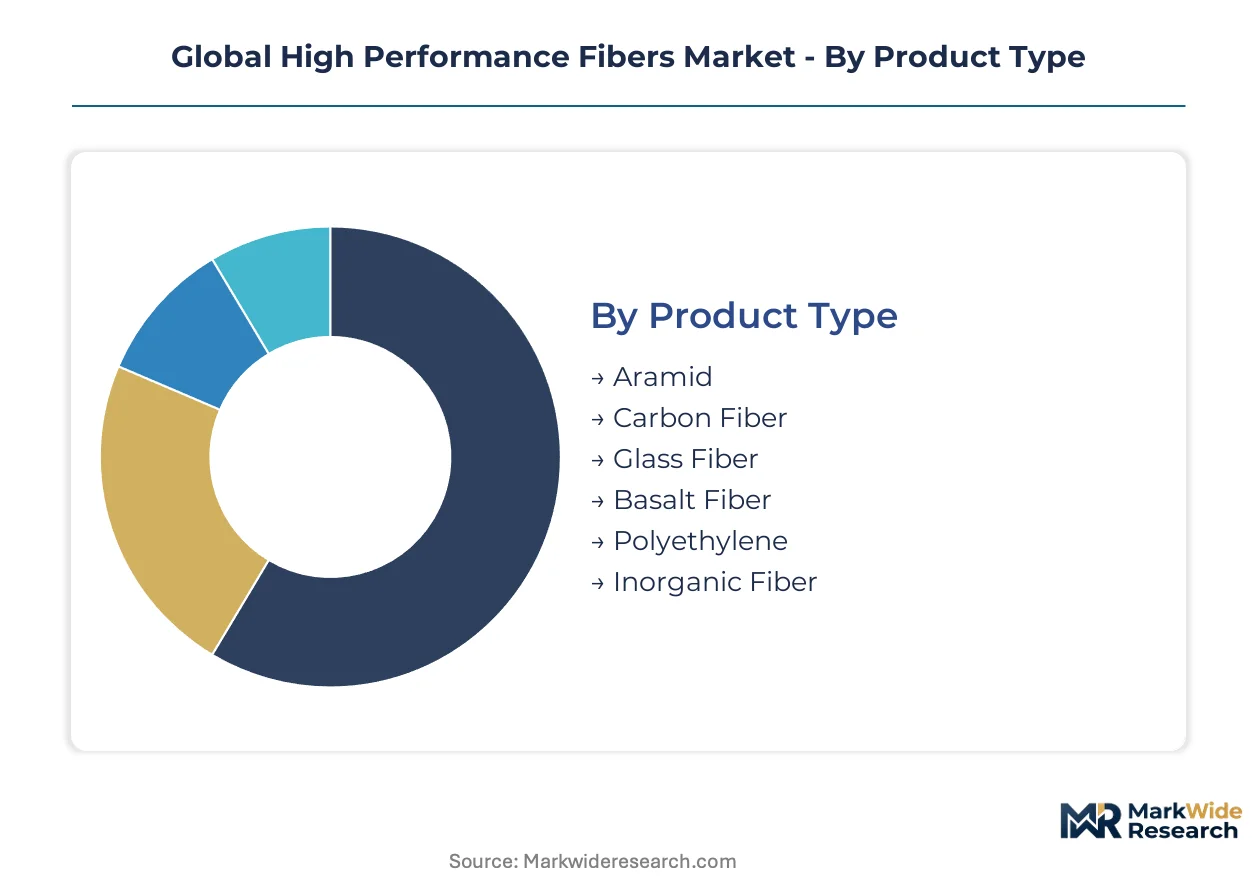
High performance fibers segment across multiple technical and commercial dimensions that determine manufacturing investment, qualification timelines, and margin capture. Understanding these divisions reveals where capital deployment concentrates and which specifications command pricing premiums.
Product Type:
Capital intensity varies dramatically by chemistry, with carbon fiber requiring the largest upfront commitment for precursor oxidation and carbonization lines.
- Carbon Fiber:Manufactured through controlled pyrolysis of polyacrylonitrile precursor to achieve tensile strength above 3.5 GPa. Demand concentrates in aerospace primary structures and wind turbine spar caps, where stiffness-to-weight ratios justify qualification costs and long-term offtake contracts.
- Aramid:Aromatic polyamide chains spun into fibers with exceptional cut and ballistic resistance. Military procurement in the US and EU sustains volume for body armor and vehicle protection, while industrial rope applications in offshore energy provide steady secondary demand.
- Glass Fiber:Silica-based filaments offering cost-effective reinforcement for construction and marine composites. Pricing pressure from Chinese supply limits margin expansion for commodity grades.
- Basalt Fiber:Melt-drawn volcanic rock fibers with thermal stability between glass and carbon. Niche adoption in fire-resistant construction panels and automotive exhaust shields drives modest volume.
- Polyethylene:Ultra-high molecular weight filaments delivering the highest specific strength among commercial fibers. Maritime mooring lines and cut-resistant gloves in Japanese and South Korean manufacturing anchor demand.
- Inorganic Fiber:Ceramic and metal oxide fibers for extreme temperature applications above 1000°C. Aerospace thermal protection systems and industrial furnace linings in Germany and the US represent primary end-uses.
Most installed capacity flows through Carbon Fiber. Expansion is steepest in Polyethylene for maritime and medical applications.
Application:
Application selection determines qualification burden, with aerospace imposing the most stringent certification requirements and longest development cycles.
- Aerospace:Primary and secondary structural components for commercial and defense airframes. FAA Part 25 certification locks in supplier relationships for decades, creating high barriers for new fiber entrants.
- Composites:Reinforced matrices for automotive, construction, and industrial equipment. Automotive OEMs in Germany and Japan are accelerating thermoplastic composite adoption for battery enclosures and structural members.
- Military Equipment:Ballistic protection, vehicle armor, and tactical gear. US Department of Defense dual-source mandates are reshaping supplier consolidation patterns.
- Protective Clothing:Flame-resistant and cut-resistant apparel for industrial and first-responder use. OSHA mandates in North American workplaces sustain baseline aramid consumption.
- Industrial Textiles:Conveyor belts, hoses, and filtration media. Mining and chemical processing operations in Australia and Canada drive replacement demand.
- Sporting Goods:Bicycles, golf clubs, and recreational equipment. Premium consumer brands in Italy and Taiwan specify high-modulus carbon for performance positioning.
Aerospace commands the highest fiber specification grades. Composites are climbing the fastest as automotive scale manufacturing matures.
End User Industry:
End user selection reveals procurement sophistication, with automotive OEMs and energy producers driving the most demanding technical specifications.
- Automotive OEMs:Structural composites for electric vehicle battery enclosures, body-in-white components, and hydrogen pressure vessels. EU Green Deal carbon accounting is redirecting procurement toward certified low-carbon fiber sources.
- Energy Producers:Wind turbine blade spar caps and offshore mooring systems. Offshore installations exceeding 15 MW in the North Sea and Baltic Sea are pulling aerospace-grade tow capacity into energy applications.
- Construction Firms:Reinforcement for concrete, facades, and infrastructure rehabilitation. Glass fiber dominates volume for rebar and mesh applications.
- Apparel Manufacturers:Technical textiles for protective and performance clothing. Cut-resistant gloves and flame-resistant workwear specifications vary by regional regulatory requirements.
- Marine Assemblers:Hull construction, rigging, and deck components. Recreational yacht builders in Italy and the Netherlands specify carbon fiber for racing vessel performance.
- Electronics Producers:Thermal management substrates and structural housings. 5G infrastructure and satellite components in South Korea and Taiwan utilize low-CTE carbon fiber.
Automotive OEMs absorb the most qualified fiber volume. Energy producers are gaining share fastest as offshore wind scales.
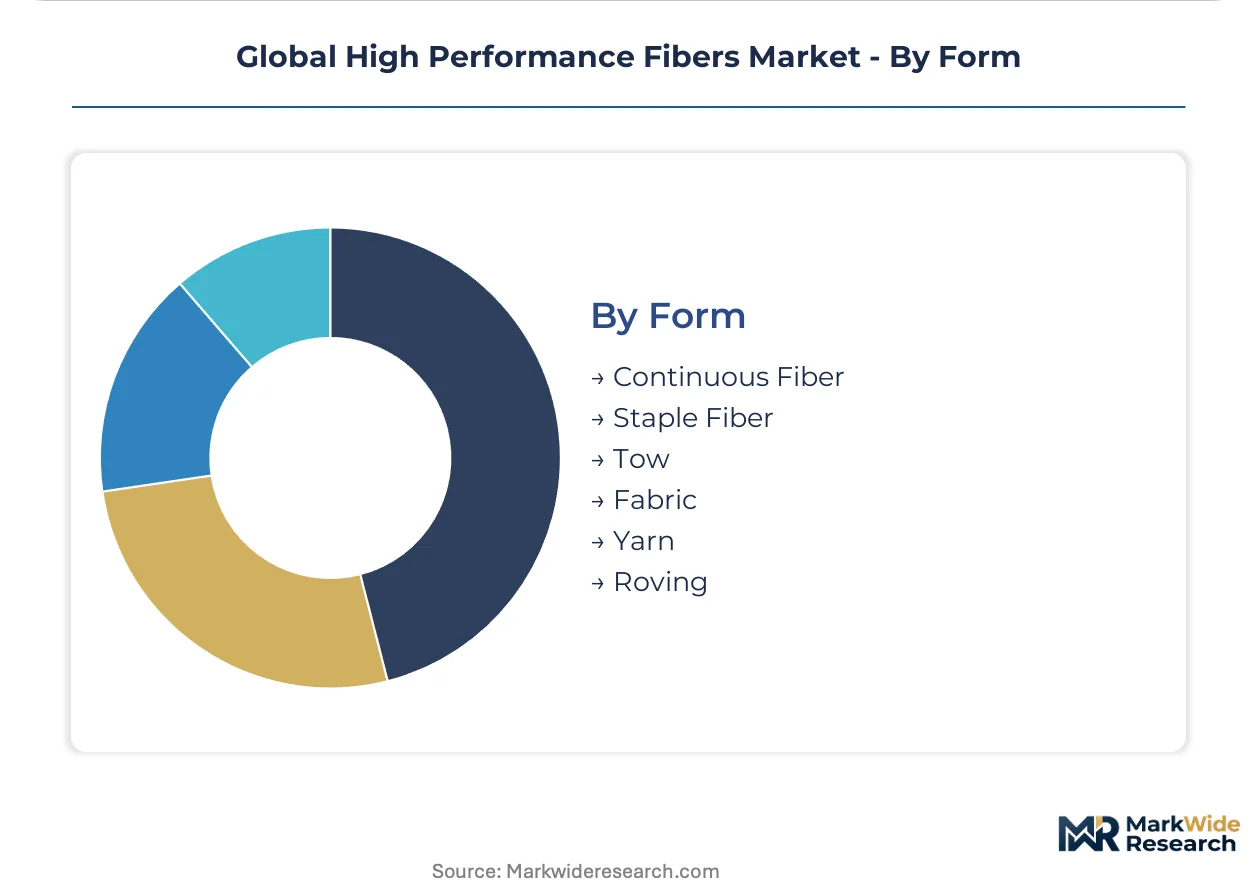
Form:
Form selection determines processing compatibility, with continuous fiber requiring the most specialized handling equipment and technician training.
- Continuous Fiber:Unidirectional filaments for automated fiber placement and filament winding. Aerospace and wind energy applications in the US, Germany, and China specify continuous forms for structural load paths.
- Tow:Bundled filaments sized for specific resin systems and processing methods. 12K and 24K tow counts dominate aerospace qualification standards.
- Fabric:Woven and non-crimp textiles for hand layup and resin transfer molding. Marine and industrial composite shops prefer fabric forms for complex geometry accommodation.
- Yarn:Twisted filaments for textile processing and sewing applications. Protective apparel and industrial sewing threads utilize aramid and UHMWPE yarns.
- Roving:Untwisted bundles for pultrusion and spray-up processes. Construction and infrastructure applications favor roving for rebar and grating manufacture.
- Staple Fiber:Short-cut filaments for nonwoven mats and thermoplastic compounding. Automotive interior panels and filtration media specify staple forms for molding efficiency.
Continuous Fiber carries the highest value per kilogram. Fabric forms are expanding most quickly as out-of-autoclave processing spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EPA emissions rules and EU carbon border adjustments is bifurcating supply chains. Producers are relocating capacity to jurisdictions with lower compliance costs while maintaining qualification tracks for premium markets.
United States
Commercial aviation recovery and defense procurement sustain aerospace-grade carbon fiber consumption. FAA Part 25 certification timelines lock in supplier relationships for decades. The Pacific Northwest and South Carolina host concentrated composite fabrication clusters serving Boeing and defense contractors.
China
Domestic capacity expansion for wind energy and electric vehicle battery enclosures reduces import dependency. MIIT dual carbon goals and GB standards tighten production emissions thresholds. The Yangtze River Delta and Shandong Peninsula concentrate new precursor oxidation and carbonization lines.
Germany
Automotive OEMs redirect procurement toward certified low-carbon fiber sources under EU Green Deal lifecycle accounting. REACH substance restrictions on solvent-based sizing chemistries force reformulation of surface treatments. Bavaria and Baden-Württemberg anchor thermoplastic composite development for structural automotive components.
Japan
Aerospace-grade PAN precursor production concentrates among three producers, creating single-source vulnerability for qualified manufacturers. METI industrial policy supports sustained investment in ballistic protection and industrial rope applications. The Chubu region around Nagoya maintains integrated precursor-to-fiber manufacturing corridors.
India
PLI scheme incentives for domestic advanced materials manufacturing offer first-mover positioning for aramid and carbon fiber production. Defense procurement and infrastructure rehabilitation drive baseline demand. Gujarat and Maharashtra host emerging composite fabrication capacity serving industrial and marine applications.
Global High Performance Fibers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue thermoplastic composite welding and out-of-autoclave processing. The vendor base stratifies across integrated precursor-to-fiber manufacturers, specialized aramid spinners, and regional glass fiber commodity suppliers. Three archetypes dominate: vertically integrated Japanese conglomerates controlling aerospace-grade precursor supply; European chemical multinationals with diversified polymer portfolios; and Chinese state-backed entities scaling domestic carbon fiber capacity. Competitive moves concentrate on securing long-term offtake agreements with wind energy developers and backward integration into PAN production.
Among Japanese integrated producers, Toray Industries, Inc. and Teijin Ltd. exemplify the precursor-to-fiber control archetype. Toray anchors the carbon fiber value chain through captive PAN supply, while Teijin occupies a parallel position in aramid fibers. DuPont represents the diversified polymer multinational model with historical strength in para-aramid protective applications. These three entities sit within distinct competitive vectors—Japanese integration versus American polymer diversification—yet all face common pressure from Chinese capacity expansion and EU carbon accounting requirements.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Teijin Ltd. |
| DuPont |
| Honeywell International Inc. |
| Hexcel Corporation |
| Mitsubishi Chemical Corporation |
| SGL Carbon |
| Solvay |
| Owens Corning |
| Others |
Supply & Pricing Matrix
Automotive OEM procurement mandates for EU Green Deal carbon accounting are forcing fiber producers to reconfigure precursor sourcing and absorb certification costs, compressing margins in standard grades while amplifying premiums for qualified low-carbon supply.
Pricing Analysis
Distributor margins on carbon fiber tow collapse under direct-to-OEM contracting pressure as wind energy developers and aerospace primes consolidate procurement panels. Three-tier pricing structure across aerospace-grade, industrial-grade, and recycled fiber tiers separates qualification-burdened supply from commodity replacement. Cost compression in industrial-grade carbon fiber intensifies because Chinese capacity expansion outpaces demand absorption. Wind energy buyers exhibit highest price sensitivity; defense contractors show least.
Supply Chain Analysis
Composite technician shortages in South Carolina and Bavaria constrain precursor-to-fabrication throughput despite installed oxidation line capacity. Manufacturing gravity centers on Japan for aerospace-grade PAN, China for industrial carbon fiber, and Germany for thermoplastic composite development. Supply chains draw from acrylonitrile feedstocks, PAN precursor, and sized tow intermediates. Single-source vulnerability in Japanese precursor supply creates structural risk. Distribution runs through qualified Tier 1 fabricators holding FAA-approved processor status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
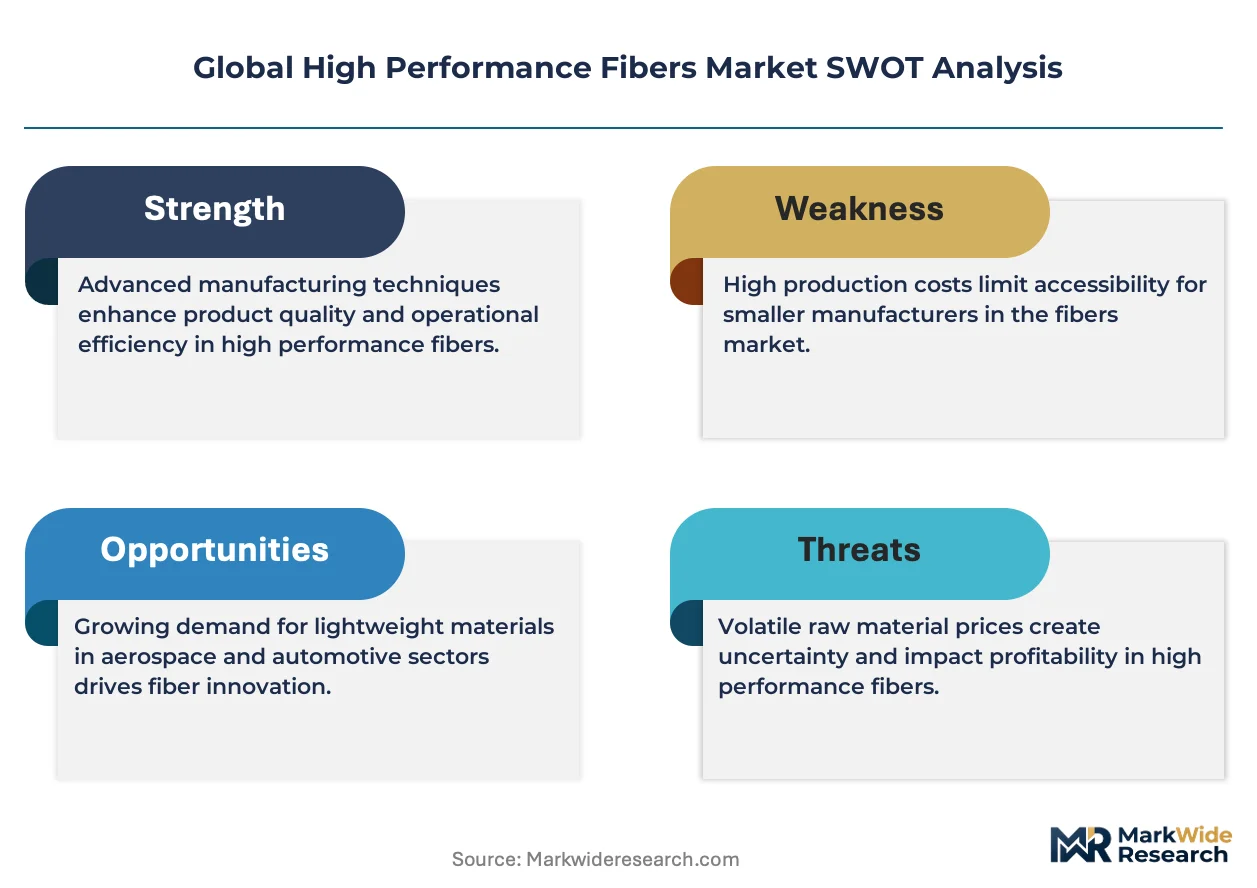
This market offers margin-expansion pathways through thermoplastic composite welding cost-down and premium-tier qualification for EU carbon-accounted supply.
For Market Incumbents: Anticipate Chinese state-backed capacity erosion in industrial-grade segments by securing long-term offtake with European automotive OEMs under EU Green Deal compliance tiers. Deepen upstream control over PAN precursor through joint venture structures in India PLI zones. Accelerate water-based sizing chemistry R&D ahead of REACH substance restrictions.
For New Entrants and Emerging Players: Launch via direct qualification with FAA-streamlined certification pathways for thermoplastic composite structural components. White-space targets include India defense procurement and automotive battery enclosure supply. Penetrate through out-of-autoclave processing partnerships with Tier 1 fabricators seeking cycle-time reduction.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists holding captive renewable power and integrated precursor-to-fiber corridors. Long-term viability over the coming decade hinges on carbon-accounting compliance infrastructure. Target acquisition archetype: European thermoplastic composite welders with OEM qualification. Watch FAA certification timeline acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Secures supply continuity for qualified carbon fiber manufacturers facing Japanese concentration risk. |
| Thermoplastic Composite Welding Scale-Up | Enables automotive OEMs to achieve mass-production cycle times without autoclave bottlenecks. |
| EU Green Deal Carbon Certification | Unlocks premium procurement tiers with German automotive OEMs under lifecycle accounting mandates. |
| India PLI Scheme Manufacturing Entry | Captures first-mover positioning for defense and infrastructure composite demand under domestic incentives. |
| Recycled Fiber Supply Chain Parallel | Absorbs aerospace scrap volumes into automotive non-structural specifications at BMW and Mercedes-Benz. |
Research Methodology
Multiple input streams — primary interviews with fiber production executives, composite fabricator procurement leads, and wind energy developer engineering directors; secondary validation through customs trade data, ACC industry reports, SEC 10-K filings, and FAA certification databases; plus bottom-up and top-down triangulation — were reconciled to construct segment-level volume and value estimates.
Historical capacity utilization patterns were cross-referenced against panel input from aerospace OEM material qualification teams to anchor growth trajectories across the projection horizon. Segmentation modeling incorporated chemistry type, application qualification tier, end-use industry procurement sophistication, and geographic regulatory cluster. CAGRs were derived from demand elasticity coefficients calibrated to wind turbine scaling curves and automotive lightweighting content-per-vehicle trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acrylonitrile price volatility and REACH substance restriction acceleration. Forecasts reflect documented assumptions on certification timeline stability and dual-source procurement mandate enforcement. Material deviation in FAA policy streamlining or EU carbon border adjustment implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market
Synthetic Fibers
Performance Fabric Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Kevlar Fiber Market