
 Long Fiber Thermoplastics Market | 2026-2036
Long Fiber Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Long Fiber Thermoplastics Market Analysis
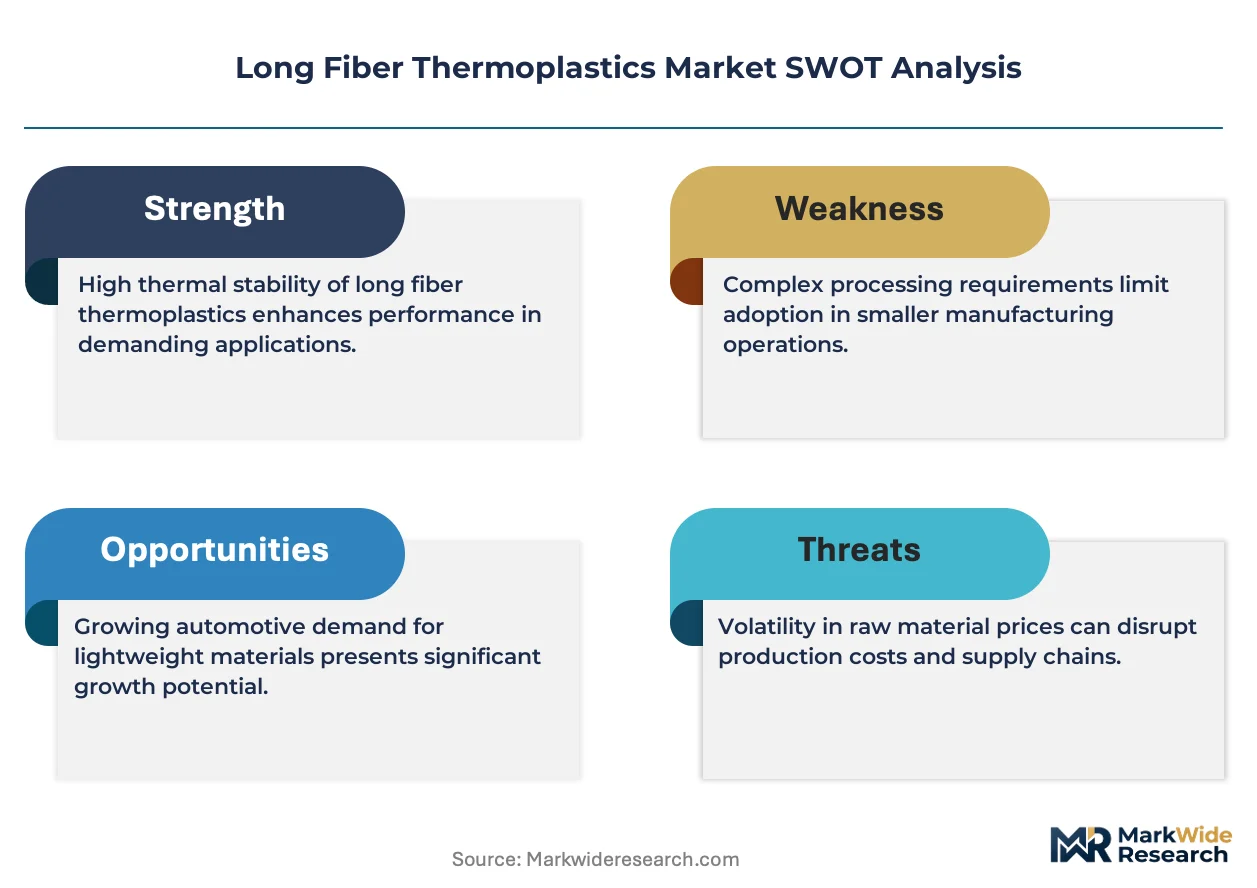
Modular material platforms is realigning how Tier-1 suppliers specify reinforced thermoplastics for vehicle programs. Celanese Corporation leverages its global compounding network to supply automotive-grade long fiber polypropylene across multiple continents. SABIC anchors its position through backward integration into polymer feedstock and specialized long fiber pellet production. RTP Company specializes in custom-engineered compounds that address niche performance thresholds for electrical and structural applications.
Long fiber thermoplastics are composite materials containing reinforcing fibers typically 10 millimeters or longer, dispersed within a thermoplastic matrix to achieve stiffness-to-weight ratios competitive with metals while enabling injection molding processing. Polyamide formulations command premium positioning in under-hood and structural applications where thermal resistance and mechanical load-bearing justify higher material costs. Injection molding technology dominates volume throughput for complex geometries, though compression molding retains stronghold positions in larger automotive panels where fiber orientation control proves critical.
The EPA regulates volatile organic compound emissions from composite manufacturing processes, while NHTSA fuel economy standards indirectly accelerate lightweight material substitution in vehicle platforms. ISO 9001 and IATF 16949 quality frameworks govern supplier qualification pathways that constrain market access for uncertified compounders. Stakeholders must monitor evolving recyclability mandates and closed-loop material certification requirements as automakers reset procurement criteria around circular economy compliance.
Market Dynamics
Automotive OEMs are compressing vehicle platform development cycles while simultaneously tightening material specifications for circularity compliance, forcing compounders to reengineer long fiber thermoplastic formulations for dual performance-recyclability targets.
Growth Catalysts
- NHTSA fuel economy standards:Corporate Average Fuel Economy mandates in the United States are accelerating metal-to-plastic substitution in structural vehicle components, with long fiber thermoplastics capturing underbody and front-end module applications.
- Stuttgart manufacturing corridor:Germany's automotive engineering cluster around Porsche and Mercedes-Benz operations is concentrating demand for glass-mat thermoplastic composites in battery enclosure housings and seat structures.
- Injection molding advances:Screw design improvements and real-time fiber orientation control systems are expanding processable part complexity while maintaining mechanical performance thresholds.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices fluctuate with naphtha cracking economics and regional refinery utilization, compressing compounder margins during upstream supply disruptions.
- Glass fiber supply concentration:High-performance roving production clusters in China and select European sites create geographic vulnerability for North American compounders seeking qualified reinforcement supply.
- Recyclate quality degradation:Fiber length attrition during reprocessing cycles limits closed-loop material utilization rates below virgin compound performance specifications.
Strategic Opportunities
- India automotive localization:Production-Linked Incentive schemes for advanced chemistry cell manufacturing are stimulating domestic EV platform development requiring lightweight structural materials.
- Wind blade root inserts:Thermoplastic composite transition pieces are displacing thermoset alternatives in turbine blade manufacturing, leveraging recyclable end-of-life processing.
- EU Green Deal circularity mandates:End-of-Life Vehicle Directive revisions will mandate minimum recycled content thresholds, creating preferential procurement positioning for certified circular material suppliers.
Industry Challenges
- IATF 16949 certification timelines:New compounder qualification pathways require 12-18 month audit cycles before automotive Tier-1 supplier approval, constraining market entry velocity.
- Fiber-matrix interface engineering:Sizing chemistry optimization for polyamide and polypropylene matrices demands specialized polymer science expertise in short supply across the technical workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Fiber Thermoplastics Market |
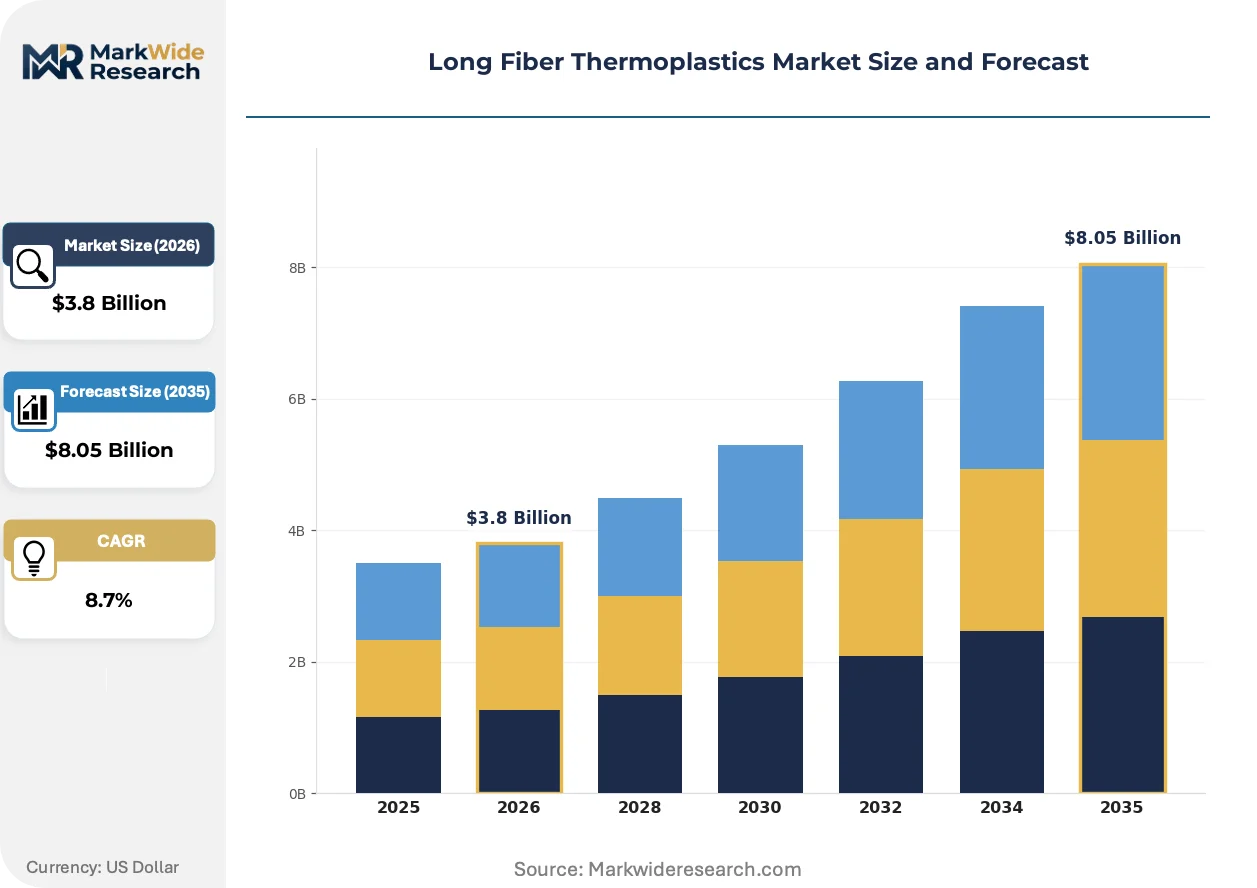
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Polyethylene, Polycarbonate End User: Aerospace, Automotive, Consumer Goods, Construction Technology: Injection Molding, Compression Molding, Thermoforming, Extrusion Application: Interior Components, Structural Parts, Automotive Trim, Electrical Components |
| Companies Covered | Celanese Corporation, SABIC, RTP Company, BASF SE, Solvay, Avient Corporation, Asahi Kasei Corporation, LANXESS, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Fiber Thermoplastics Market Emerging Trajectories
Material-process integration is compressing the traditional separation between compound design and molding parameter optimization, with real-time quality feedback loops reshaping how specifications are validated and locked.
Continuous fiber-reinforced thermoplastic tapes are consolidating their position in automotive structural components requiring unidirectional load-bearing capacity. BMW and Audi chassis engineering teams are specifying these materials for floor pan and cross-member applications. The technology is consolidating competitive positioning against both steel stampings and carbon fiber composites in the 200-400 MPa strength range.
REACH authorization procedures for legacy flame retardant additives are forcing reformulation of polyamide compounds used in electrical connector housings. Compounders are accelerating halogen-free phosphorus-nitrogen system validation to maintain EU market access. German automotive electrical suppliers face the most compressed compliance timelines given their concentration of connector production.
Automotive material qualification is compressing as platform engineering teams adopt digital twin validation for crash and fatigue performance. Virtual molding simulation is displacing physical tool trial iterations for fiber orientation prediction. This behavioral shift is most pronounced in Wolfsburg and Munich engineering centers where Volkswagen and BMW have integrated simulation platforms directly into supplier technical reviews.
Long Fiber Thermoplastics Market Segmentation
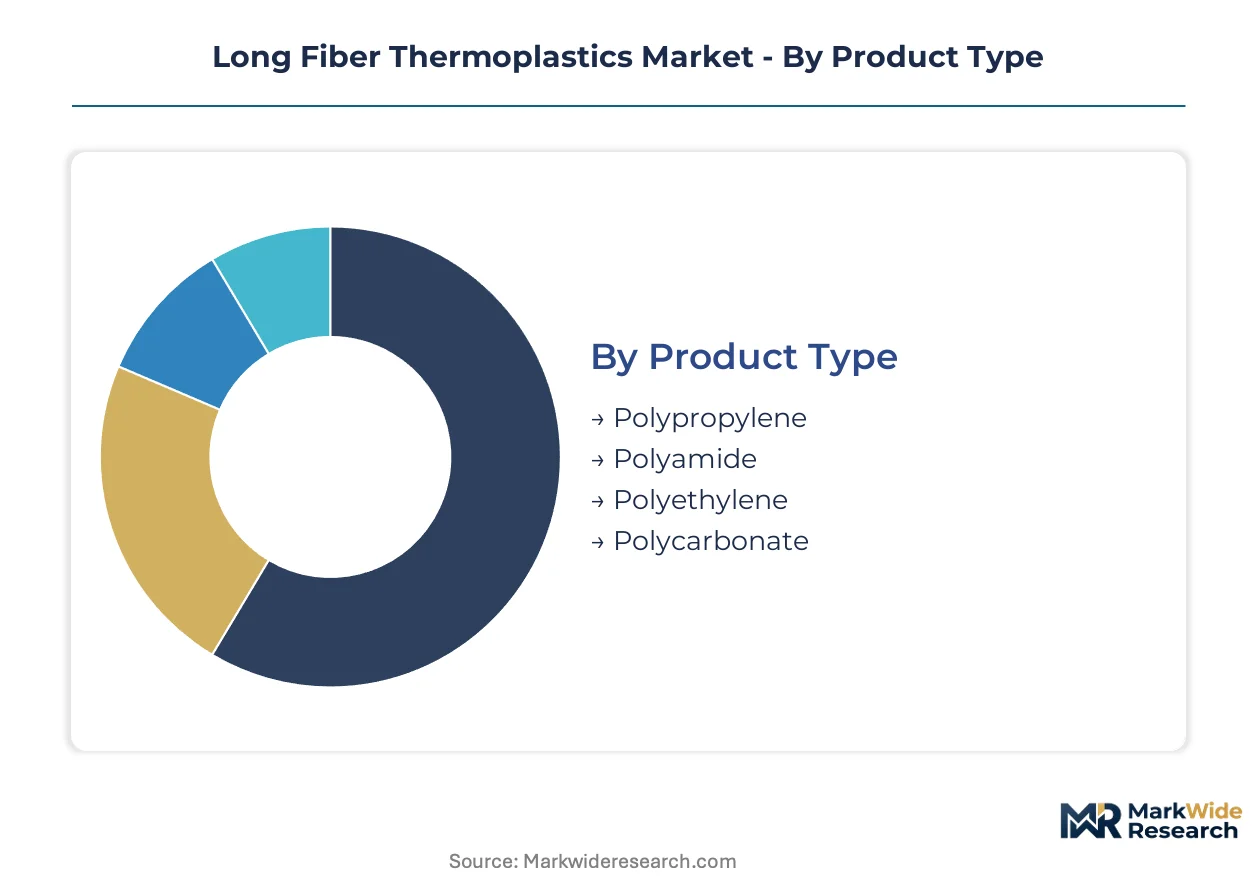
Long fiber thermoplastic formulations diverge sharply across resin chemistry and processing methodology, with each combination locking in distinct performance ceilings and cost positions that reshape how compounders prioritize R&D investment and manufacturing footprint.
Product Type:
Supply concentration in polymer feedstock determines which resin platforms compounders can scale reliably across automotive qualification cycles.
- Polypropylene:Glass-fiber-reinforced polypropylene dominates volume throughput due to favorable cost-to-stiffness ratios and established automotive recycling streams. Stuttgart-area OEMs specify this grade for battery tray assemblies and seat structures where impact resistance and lightweighting targets converge.
- Polyamide:PA6 and PA66 formulations deliver superior thermal resistance for under-hood applications. German and US automakers concentrate procurement of heat-stabilized grades for engine covers and charge air coolers where continuous-use temperatures exceed 150°C.
- Polyethylene:Lower-density options serve consumer goods and non-structural automotive applications where chemical resistance outweighs modulus requirements.
- Polycarbonate:Transparent and ignition-resistant grades address electrical housings and interior glazing where aesthetic and flame-retardant specifications intersect.
Polypropylene absorbs the bulk of installed capacity; polyamide is expanding most quickly as electrification raises thermal management demands.
End User:
Automotive qualification timelines stretch 18-24 months, forcing compounders to sequence capacity additions around confirmed platform awards rather than speculative demand.
- Automotive:Structural components, front-end modules, and underbody shields consume the highest tonnage. BMW and Volkswagen engineering teams in Wolfsburg and Munich drive specification of continuous-fiber-reinforced grades for floor pans and cross-members.
- Aerospace:Cabin interior panels and secondary structures leverage flame-retardant polyamide grades. Boeing and Airbus Tier-2 suppliers concentrate procurement through FAA-certified compounders with AS9100 traceability systems.
- Consumer Goods:Power tool housings and sporting equipment demand impact-resistant formulations with shorter qualification cycles than transportation sectors.
- Construction:Temporary works and modular building systems explore pultruded profiles where reprocessability offers end-of-life advantages over thermoset alternatives.
Automotive commands the deepest supplier relationships; aerospace is climbing the fastest as thermoplastic composites displace thermosets in cabin applications.
Technology:
Process selection locks in fiber orientation control, cycle time economics, and geometric complexity limits that compounders cannot reverse without reformulation.
- Injection Molding:Screw designs with optimized L/D ratios and fiber-friendly geometries enable complex automotive components. Real-time orientation monitoring systems from KraussMaffei and Engel are reshaping how Wolfsburg engineers validate structural performance.
- Compression Molding:Glass-mat thermoplastic (GMT) and organic sheet processes dominate larger panels where unidirectional strength is prioritized. Porsche operations around Stuttgart specify these for hood assemblies and seat pans.
- Thermoforming:Heated blank forming serves lower-volume interior trim where tooling amortization across shorter runs improves economics.
- Extrusion:Profile production for construction and industrial applications leverages continuous output efficiency with limited geometric complexity.
Injection molding holds the broadest equipment installed base; compression molding is gaining share fastest as battery enclosure sizes increase.
Application:
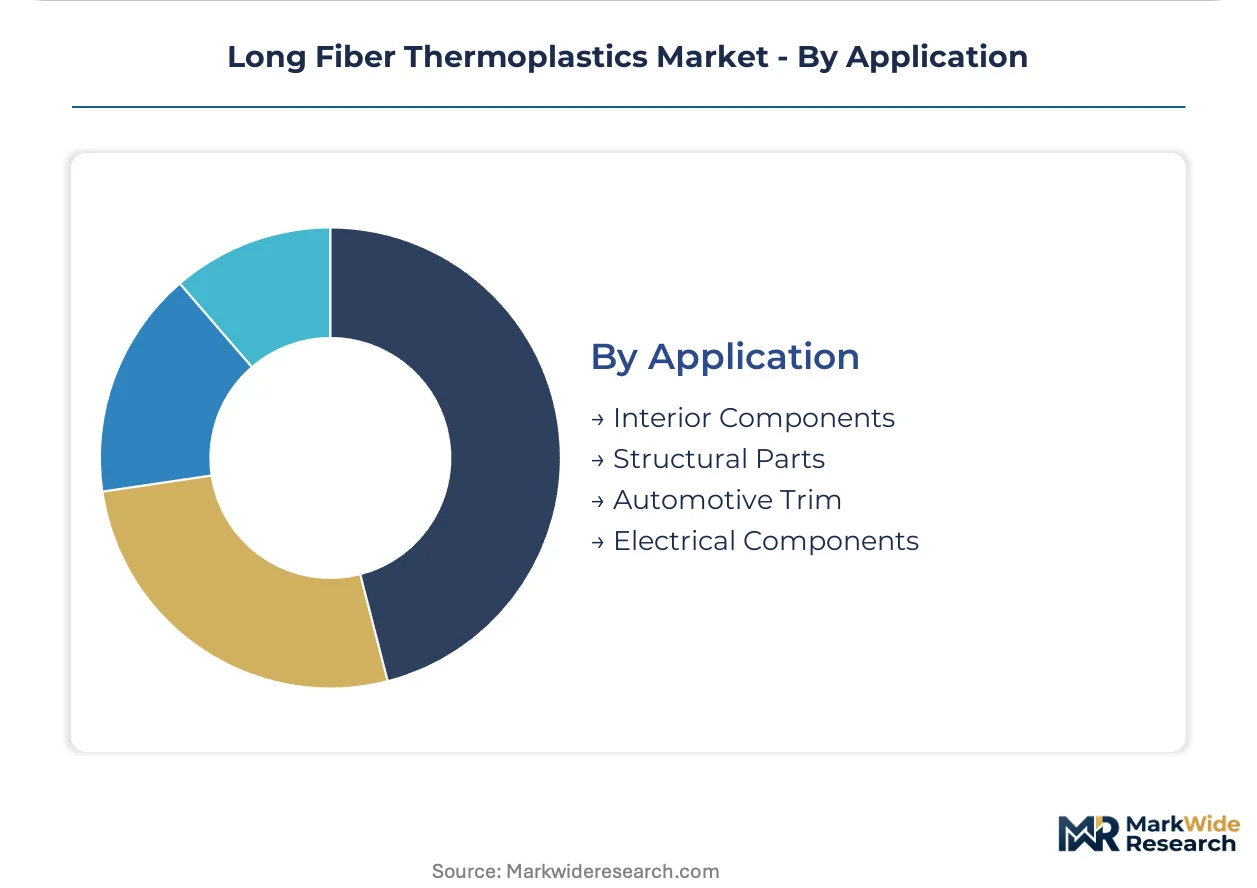
Performance thresholds and regulatory exposure vary dramatically across vehicle zones, forcing compounders to maintain multiple grade certifications per OEM platform.
- Structural Parts:Load-bearing components including front-end carriers, bumper beams, and seat structures require highest fiber loading and orientation control. NHTSA crash standards indirectly drive specification of 40-50% glass-filled grades.
- Interior Components:Dashboard carriers, door panels, and console structures balance aesthetics with VOC emissions compliance. ECHA REACH restrictions on flame retardants are forcing reformulation of polyamide grades for German electrical suppliers.
- Automotive Trim:Class-A surface requirements limit fiber exposure and demand specialized molding surface finishes.
- Electrical Components:Connector housings and high-voltage enclosures require tracking resistance and halogen-free flame retardancy under EU Green Deal circularity mandates.
Structural parts absorb the majority of qualified compound volume; electrical components are expanding most quickly as EV architectures multiply high-voltage connection points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing clusters in Germany, the United States, China, Japan, and India concentrate long fiber thermoplastics demand through platform-specific material qualifications tied to lightweighting mandates and electrification timelines.
Germany
Battery enclosure housings and seat structures from Porsche and Mercedes-Benz operations concentrate procurement around Stuttgart. The EU's End-of-Life Vehicle Directive tightens material recovery mandates across member states. Wolfsburg engineering centers drive specification of continuous-fiber-reinforced grades for Volkswagen floor pans and cross-members.
United States
NHTSA Corporate Average Fuel Economy standards accelerate metal-to-plastic substitution in underbody and front-end module applications. The EPA regulates volatile organic compound emissions from composite manufacturing processes. Michigan-based automotive Tier-1 suppliers source glass-mat thermoplastic compounds for bumper beams and structural carriers.
China
Domestic EV platform development stimulates demand for lightweight structural materials in battery tray assemblies. MIIT dual carbon goals pressure automakers toward recyclable thermoplastic solutions. Yangtze River Delta manufacturing corridors around Shanghai concentrate compounding capacity for local OEM supply.
Japan
Heat-stabilized polyamide grades for under-hood applications serve Toyota and Honda electrification programs. METI industrial policy supports advanced materials R&D through designated technology clusters. Nagoya-area engineering centers validate fiber orientation control systems for injection molding processes.
India
Production-Linked Incentive schemes for advanced chemistry cell manufacturing stimulate domestic EV structural material demand. BIS quality frameworks govern supplier qualification for automotive applications. Tamil Nadu automotive corridors around Chennai attract compounding investments for localized OEM supply.
Long Fiber Thermoplastics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation development and automotive qualification pathways. Market structure tilts toward consolidated supply at the resin and compounding tiers, with fragmentation among custom compounders serving niche performance thresholds. Three archetypes dominate: integrated polymer producers with captive feedstock, independent compounders with automotive certification depth, and regional specialists leveraging geographic proximity to manufacturing clusters. Capacity expansion and backward integration into polymer feedstock represent the dominant competitive moves.
Among integrated polymer producers, Celanese Corporation and SABIC anchor the supply tier through global compounding networks and feedstock control. RTP Company exemplifies the independent compounder archetype with custom-engineered formulations. These three entities represent distinct strategic positions: resin-backed scale, feedstock integration, and application-specific engineering depth.
| Leading Market Players |
|---|
| Celanese Corporation |
| SABIC |
| RTP Company |
| BASF SE |
| Solvay |
| Avient Corporation |
| Asahi Kasei Corporation |
| LANXESS |
| Daicel Corporation |
| Others |
Supply Flow & Price Mechanics
Injection molding advances with real-time fiber orientation control are compressing cycle times while concentrating qualified equipment supply among KraussMaffei and Engel installations in Germany and Japan, simultaneously reshaping per-part cost economics and locking in geographic premiums for technical workforce access.
Pricing Analysis
Short lead-time premiums for automotive-grade long fiber polypropylene compound supply separate urgent platform qualification timelines from standard contract offtake arrangements. Three-tier pricing structure across premium, standard, and economy levels stratifies by IATF 16949 certification status and fiber loading percentage, with OEM direct contracts commanding favorable terms over distributor spot purchases. Cost compression in standard-grade polypropylene compounds is intensifying because propylene monomer volatility feeds directly into compounder margin structures. Tier-2 automotive suppliers exhibit highest price sensitivity due to limited pass-through mechanisms, while battery enclosure OEMs show lowest sensitivity given performance-critical specifications.
Supply Chain Analysis
Technical workforce availability in Stuttgart, Wolfsburg, and Munich manufacturing corridors constrains expansion velocity for qualified compounding operations serving Porsche and Mercedes-Benz platforms. Glass fiber roving supply concentrates in China, Germany, and Belgium, while polymer feedstock production clusters in the US Gulf Coast, Rotterdam, and Singapore. Raw material dependencies on naphtha-derived propylene, high-performance glass rovings, and specialized sizing chemistries create multi-point vulnerability. Single-source concentration for qualified automotive-grade sizing chemistry generates qualification risk. Distribution runs through captive logistics networks from integrated producers and regional distributor partnerships for independent compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long fiber thermoplastics supply is tightening around qualified IATF 16949 certification slots, with 12-18 month audit cycles constraining new capacity activation and propping pricing power for certified incumbents.
For Market Incumbents: Anticipate margin compression from recycled-content mandates under EU Green Deal circularity revisions by securing backward integration into polymer feedstock and glass fiber roving supply. Defensive consolidation through acquisition of regional compounders with established OEM relationships in India and China addresses emerging EV platform localization. Priority lever rests on captive sizing chemistry R&D to differentiate fiber-matrix interface performance. For New Entrants and Emerging Players: Digital-channel route through virtual molding simulation partnerships offers lower-friction entry into Wolfsburg and Munich engineering centers where BMW and Volkswagen have integrated supplier technical reviews. White-space targets concentrate in India Production-Linked Incentive zones for advanced chemistry cell manufacturing and wind blade root insert applications displacing thermoset alternatives. Most penetrable segment is non-automotive industrial applications with compressed qualification cycles. Go-to-market angle emphasizes recyclable end-of-life processing credentials against thermoset incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated polymer producers seeking automotive qualification depth and geographic footprint expansion. Long-term viability frames around circular economy compliance certification as automakers reset procurement criteria. Acquisition target archetype is IATF 16949-certified regional compounders with established Tier-1 supplier relationships in Germany or the US Midwest. Signal to watch is EU End-of-Life Vehicle Directive recycled content threshold announcements as inflection indicator for certified circular material supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | SABIC and Celanese anchor margin control through captive propylene supply and specialized pellet production. |
| IATF 16949 Certification Investment | Twelve-to-eighteen month audit cycles create defensive moats against uncertified compounders seeking automotive access. |
| Recycled Content Formulation Development | EU Green Deal circularity mandates will require minimum thresholds, preferencing suppliers with closed-loop validation. |
| Regional Compounding Footprint Expansion | Tamil Nadu and Yangtze River Delta corridors attract capacity for localized EV battery enclosure supply. |
| Virtual Molding Simulation Partnership | KraussMaffei and Engel platform integration with Wolfsburg engineering centers reshapes supplier technical review access. |
Methodological Framework
Multi-period observation of automotive platform qualification timelines, compounding capacity additions, and OEM lightweighting procurement patterns anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, compounding plant managers, and technical R&D directors at glass fiber producers. Secondary validation drew from customs and trade data, SEC 10-K filings of listed compounders, vehicle production databases, and IHS Markit registration data. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrix framing connected resin chemistry availability, fiber loading specifications, and processing technology penetration to end-use application demand across automotive, aerospace, consumer goods, and construction segments. Modeled dimensions spanned resin platform, reinforcement type, manufacturing process, and regional production cluster. CAGRs derived from regression analysis of historical qualification volumes and projected platform engineering timelines. Industry-specific forecast inputs included NHTSA fuel economy standard stringency trajectories and EU End-of-Life Vehicle Directive implementation schedules.
The model holds under stable automotive production volumes and continued electrification capex commitment; deviation in propylene monomer supply disruptions or glass fiber trade restriction implementation would shift compound availability and pricing trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Polyester Tire Cord Fabrics Market