
 Synthetic Fiber Market | 2026-2036
Synthetic Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Fiber Market Intelligence
Large-scale project financing for new petrochemical feedstock and polymerization facilities is rewriting the terms of competition in bulk fiber production. This capital-intensive model favors giants like Reliance Industries Limited, which leverages its integrated refining operations. In contrast, DuPont de Nemours Inc. specializes in high-performance aramids and specialty fibers. Toray Industries Inc. also differentiates through advanced carbon fiber and technical textile innovations, focusing on high-margin applications.
Synthetic fibers are man-made filaments produced through chemical synthesis, primarily involving the polymerization of petroleum-derived monomers. These materials are engineered for specific properties such as high tensile strength, elasticity, and resistance to moisture, differentiating them from natural fibers. Polyester remains the dominant product type by volume due to its versatility and low production cost. The automotive interiors application represents a high-value segment where durability and aesthetic standards drive demand for specialized nylon and polyester fabrics.
Regulatory frameworks like the EU's REACH directive govern the chemical inputs used in fiber production. In parallel, emissions standards from the US EPA and textile quality mandates like China's GB standards shape manufacturing practices and market access. Producers now face a strategic decision between investing in advanced chemical recycling infrastructure and optimizing existing linear production models for cost-efficiency.
Market Dynamics
The competitive landscape is defined by a fundamental tension between the scale-driven economics of bulk commodity fibers and the innovation-led, high-margin potential of specialty materials. This bifurcation forces producers to choose between massive capital investment in integrated feedstock production and focused R&D in advanced polymers for niche applications.
Growth Catalysts
- Technical Textile Demand:The automotive sector's requirement for durable, lightweight, and aesthetically pleasing interior materials like specialized polyester and nylon for seating, headliners, and carpets drives high-value fiber consumption.
- Bio-Based Innovations:The development and commercialization of bio-based polyesters, derived from renewable sources, offer a pathway to reduce dependence on petrochemical feedstocks and meet corporate sustainability mandates.
- China's Industrial Policy:National standards like the GB framework and state support for advanced manufacturing in China create a concentrated, high-volume demand center for both commodity and technical synthetic fibers for domestic use and export.
Market Restraints
- Feedstock Price Volatility:Dependence on petroleum-derived monomers such as purified terephthalic acid (PTA) and monoethylene glycol (MEG) exposes fiber producers to significant cost instability tied to global crude oil price fluctuations.
- Regulatory Compliance Burden:The European Union's REACH regulation imposes stringent chemical registration and evaluation requirements, increasing compliance costs and potentially restricting the use of certain additives or catalysts in fiber synthesis.
- Threat from Advanced Natural Fibers:Performance enhancements in natural fibers and cellulosics like lyocell, coupled with their perceived sustainability benefits, present a growing substitution threat in apparel and home textile applications.
Strategic Opportunities
- Smart and E-Textiles:Integrating conductive fibers into fabrics creates opportunities in wearable technology, healthcare monitoring, and automotive sensors, opening a new high-margin application frontier beyond traditional apparel and furnishings.
- Circular Economy Mandates:Government policies promoting a circular economy, especially in Europe, create a strong business case for investing in chemical recycling technologies that can convert post-consumer textile waste back into virgin-quality fiber.
- Manufacturing Growth in South Asia:The expansion of textile and apparel manufacturing in countries like India and Vietnam presents an opportunity to develop new supply chains and customer bases outside the established hub of China.
Industry Challenges
- High Capital Intensity:Building new, globally competitive polymerization and feedstock facilities requires immense capital expenditure, creating high barriers to entry and favoring large, established chemical and energy conglomerates.
- Navigating Global Standards:Manufacturers face significant operational complexity in ensuring products comply with a divergent set of international regulations, including the EU's REACH, US EPA emissions rules, and China's GB quality standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Fiber Market |
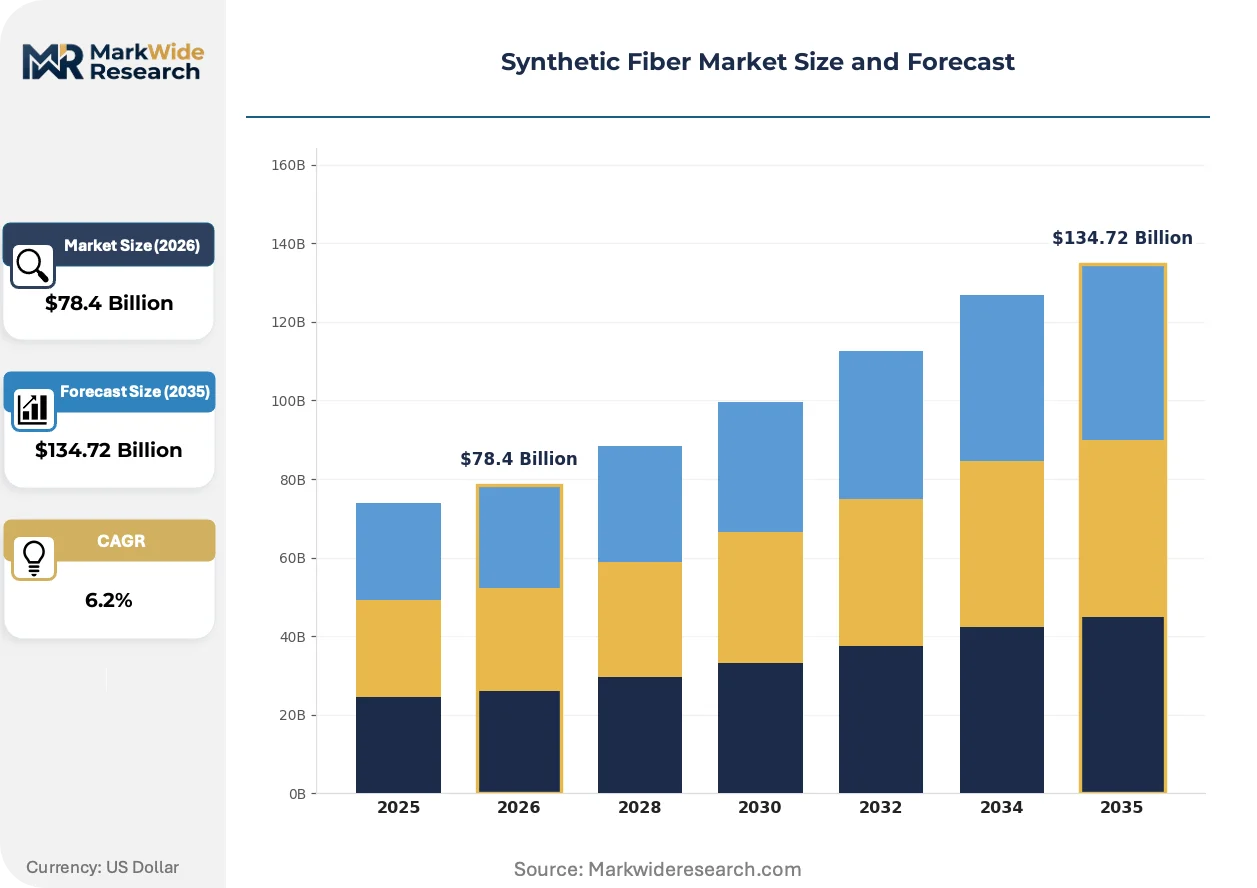
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Acrylic, Spandex Application: Textiles, Automotive Interiors, Home Furnishings, Industrial Fabrics End User: Fashion Industry, Sportswear, Upholstery Manufacturers, Technical Textiles Technology: Weaving, Knitting, Nonwoven, Braiding |
| Companies Covered | China Petroleum & Chemical Corporation (Sinopec), Teijin Limited, Reliance Industries Limited, Mitsubishi Chemical Group Corporation, Lenzing AG, Indorama Corporation, Toray Industries Inc., Bombay Dyeing & Manufacturing Company Limited, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Fiber Market Strategic Shifts & Innovations
The industry's evolution is driven by a dual focus on performance and sustainability. Material science advancements are creating fibers with novel properties for technical applications, while circular production models are fundamentally altering the lifecycle of high-volume polymers like polyester.
Advanced chemical recycling processes break down post-consumer polyester waste into its constituent monomers, which can be re-polymerized into virgin-quality material. Apparel brands and consumer goods companies are increasingly adopting fibers made through this process to meet ambitious circularity and recycled-content targets. This technology is rendering obsolete the purely linear, petroleum-to-landfill production model for synthetic textiles by creating a viable closed-loop alternative.
Extended Producer Responsibility (EPR) frameworks for textiles, particularly within the European Union, are gaining legislative momentum. These regulations make fiber producers and apparel brands financially responsible for the collection, sorting, and recycling of post-consumer garments. This shift most directly impacts producers of low-cost polyester for the fast-fashion industry, compelling them to invest in recycling solutions or design for circularity.
A distinct behavioral change is evident as industrial buyers increasingly specify materials based on sustainability credentials, not just technical performance and price. This trend is displacing traditional procurement models and creating a preference for suppliers holding certifications like the Global Recycled Standard (GRS) or bluesign® approval. The shift is most pronounced in the performance apparel and corporate uniform segments in North America and Europe.
Synthetic Fiber Market Segmentation
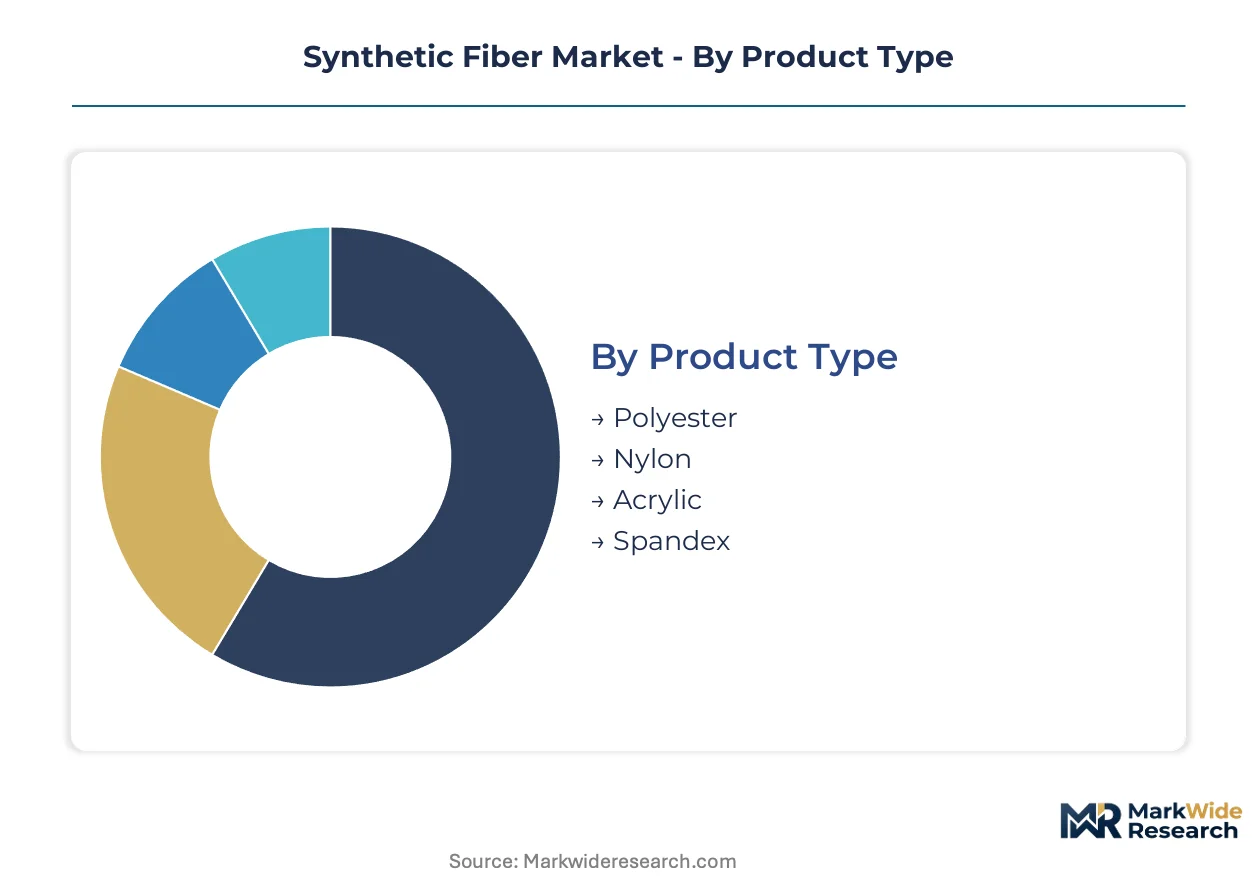
Segmenting the synthetic fiber market provides critical insights into the diverse material properties and application requirements driving demand. This granular view reveals how innovations in fiber chemistry and processing technologies address specific end-user needs across various industries. Understanding these distinctions is essential for strategic planning and resource allocation within the complex value chain.
Product Type:
Product types in the synthetic fiber market exhibit varying innovation cycles, with some materials undergoing rapid formulation changes while others maintain long-standing production processes.
- Polyester:This dominant synthetic fiber is produced through the polymerization of petroleum-derived monomers, offering high strength, wrinkle resistance, and quick-drying properties. Demand concentrates in the apparel and automotive interiors sectors, particularly in China, driven by its versatility and cost-effectiveness.
- Nylon:A polyamide fiber known for its exceptional tensile strength, elasticity, and abrasion resistance, making it suitable for demanding applications. Significant consumption occurs in automotive components and high-performance sportswear across Germany and the United States, valuing its durability and performance characteristics.
- Acrylic:Provides a soft, wool-like texture, making it a preferred choice for knitwear, blankets, and carpets, primarily in European home textile markets.
- Spandex:Highly valued for its extreme elasticity and recovery properties, spandex is integral to performance apparel, activewear, and intimate garments worldwide.
Polyester anchors the volume base while Spandex gains share at the steepest rate.
Application:
Different applications for synthetic fibers command distinct margin profiles, reflecting varying performance requirements and material specifications.
- Automotive Interiors:This high-value segment utilizes specialized nylon and polyester fabrics for seating, headliners, and carpets, prioritizing durability, aesthetic appeal, and flame retardancy. Demand is robust in major automotive manufacturing hubs like Germany and Japan, driven by stringent OEM standards.
- Industrial Fabrics:Materials engineered for specific technical functions such as filtration, geotextiles, and protective clothing, requiring high tensile strength, chemical resistance, and thermal stability. Significant demand emerges from infrastructure projects and manufacturing sectors in China and India.
- Textiles:Encompasses a broad range of apparel, fashion, and home textiles, representing a large volume segment for polyester, nylon, and acrylic fibers.
- Home Furnishings:Utilizes synthetic fibers for carpets, upholstery, drapes, and bedding, where durability, stain resistance, and aesthetic variety are key purchasing criteria.
Automotive Interiors and Industrial Fabrics represent high-value segments where performance specifications drive material selection.
End User:
End-user industries for synthetic fibers demonstrate distinct sustainability mandates and procurement priorities, influencing material choices.
- Technical Textiles:Industries requiring fabrics with specific functional properties such as medical textiles, protective wear, and agricultural fabrics, prioritizing material science innovations. Demand is strong in advanced economies like Germany and the US, driven by specialized R&D.
- Sportswear:This segment demands synthetic fibers with moisture-wicking, breathability, elasticity, and lightweight properties for athletic apparel and footwear. North America and Europe show substantial consumption due to active lifestyle trends and brand innovation.
- Fashion Industry:A major consumer of synthetic fibers, particularly polyester, influenced by fast-fashion cycles, cost efficiency, and the increasing adoption of recycled content.
- Upholstery Manufacturers:Specify synthetic fibers for durability, stain resistance, and aesthetic appeal in furniture production for residential and commercial spaces.
Technical Textiles prioritize advanced material properties, while the Fashion Industry remains a dominant volume consumer.
Technology:
The processing technologies for synthetic fibers vary significantly in complexity and capital intensity, impacting final product characteristics.
- Nonwoven:This technology produces fabrics by bonding fibers mechanically, thermally, or chemically, without weaving or knitting, enabling high versatility for specialized applications. Demand concentrates in medical and hygiene products across the US and Europe, driven by single-use requirements.
- Weaving:A traditional method involving the interlacing of two distinct sets of yarns at right angles to form a fabric, widely used for apparel and home textiles. Established manufacturing bases in India and Vietnam drive significant adoption of this process.
- Knitting:Creates fabrics with inherent elasticity and drape by interlocking loops of yarn, predominantly used for comfortable apparel and certain technical textiles.
- Braiding:Involves intertwining three or more strands to produce ropes, cords, and specialized industrial composites requiring high strength and specific geometric structures.
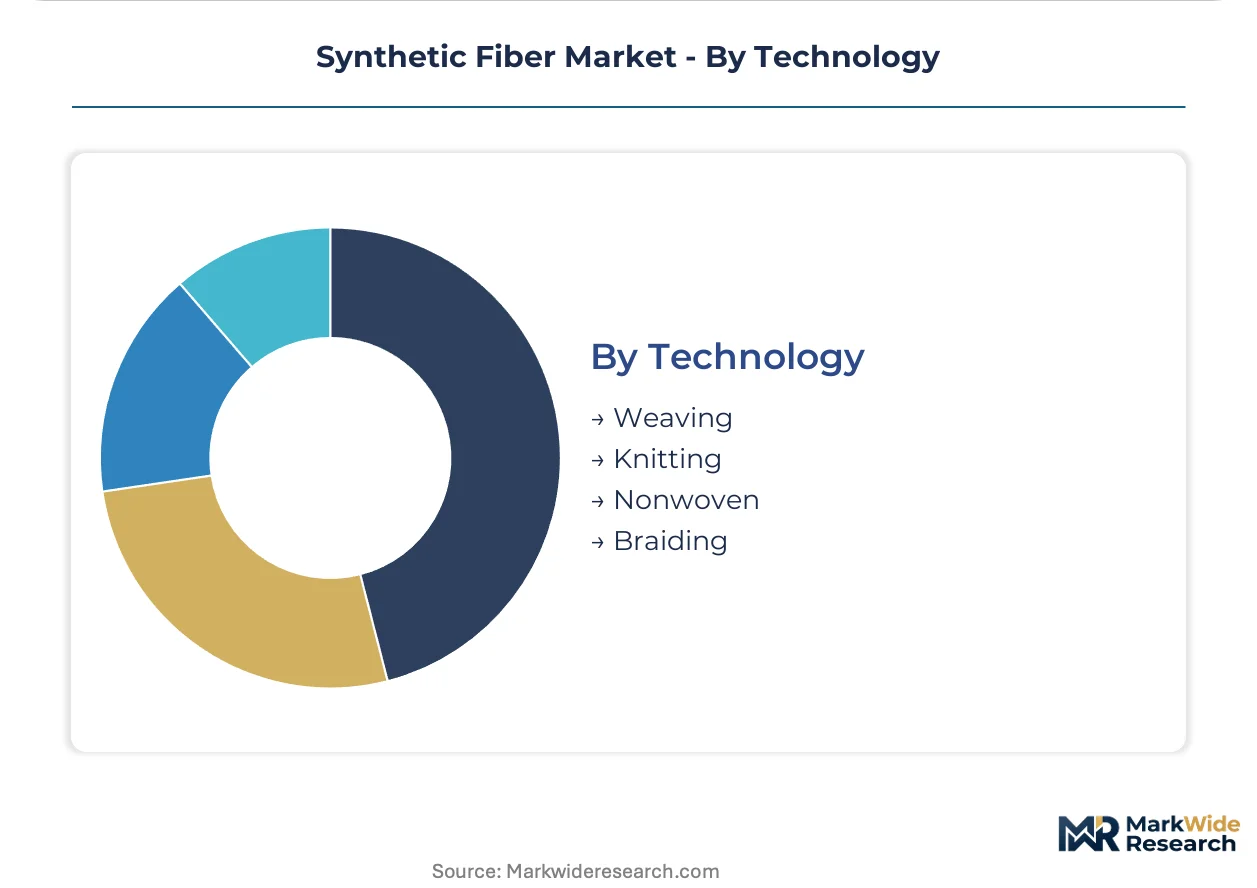
Nonwoven technologies are experiencing rapid innovation for specialized uses, while Weaving maintains its foundational role in textile production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The synthetic fiber market exhibits a complex regional dynamic, with certain geographies acting as net exporters of finished textiles and others as primary consumers of specialized fibers. This balance influences investment in both upstream polymerization capacity and downstream manufacturing capabilities. Global trade flows for synthetic fibers are increasingly shaped by regional production efficiencies and consumer preferences.
China
China remains a dominant force, driven by robust demand from its advanced manufacturing and textile export sectors, particularly for polyester in automotive interiors. The country's GB standards and state support for advanced manufacturing shape production practices and market access. Industrial clusters in the Yangtze River Delta and Pearl River Delta drive high-volume production and global textile exports.
Germany
German demand for synthetic fibers centers on high-performance applications in automotive components and technical textiles, alongside specialized sportswear. The EU's REACH directive significantly influences chemical inputs and manufacturing processes for fiber producers operating within the region. Advanced manufacturing hubs in Bavaria and North Rhine-Westphalia focus on specialized R&D and high-value fiber production.
United States
United States consumption is significant in automotive interiors, high-performance sportswear, and specialized medical textiles, valuing durability and functional properties. US EPA emissions rules and other federal regulations impact manufacturing practices and material sourcing for synthetic fiber producers. The Southeast region, particularly around North Carolina, continues to be a hub for specialized fiber production and nonwoven technology innovation.
India
India's expanding textile and apparel manufacturing, coupled with significant infrastructure projects, drives substantial demand for synthetic fibers, especially polyester and nylon. The Indian government's PLI scheme for textiles aims to boost domestic manufacturing and promote high-value fiber production. Major textile hubs in Gujarat and Maharashtra are increasing their capacity for both commodity and technical fiber processing.
Synthetic Fiber Market Key Industry Players
On the supply side, the industry is characterized by a dual structure, where a few large, integrated chemical and energy conglomerates coexist with specialized fiber manufacturers. Strategic archetypes include scale-driven commodity producers, innovation-focused specialty fiber developers, and vertically integrated textile manufacturers. Companies pursue capital expansion for feedstock production and strategic partnerships for advanced recycling technologies to secure market position. This bifurcation forces producers to choose between massive capital investment in integrated feedstock production and focused R&D in advanced polymers for niche applications.
Specialists in high-performance materials and advanced technical textiles include DuPont de Nemours Inc., which exemplifies a focus on high-value aramids and other specialty fibers. Toray Industries Inc. also occupies a position in advanced carbon fiber and technical textile innovations, differentiating through its expertise in high-margin applications. Meanwhile, Reliance Industries Limited represents the scale-driven end of the market, leveraging its integrated refining operations to anchor bulk fiber production. These players demonstrate the varied strategies employed to capture different segments of the synthetic fiber value chain, from commodity volume to niche performance.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation (Sinopec) |
| Teijin Limited |
| Reliance Industries Limited |
| Mitsubishi Chemical Group Corporation |
| Lenzing AG |
| Indorama Corporation |
| Toray Industries Inc. |
| Bombay Dyeing & Manufacturing Company Limited |
| DuPont de Nemours Inc. |
| Others |
Cost & Logistics Intelligence
The Suez Canal shipping corridor's fluctuating freight costs directly influence the pricing of bulk synthetic fibers, especially given the concentrated supply from Asian manufacturing hubs, which then impacts downstream price differentiation for apparel and industrial textiles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for specialized synthetic fibers. Price differentiation emerges from quality grade, Global Recycled Standard (GRS) certification, and customization levels for technical textiles. Pricing softness reflects intense competition in commodity polyester segments, particularly from Chinese producers. Fast-fashion brands exhibit the highest price sensitivity, while automotive interior manufacturers prioritize performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, supporting large-volume transactions between petrochemical giants and fiber producers. Geographic supply concentrates predominantly in China, India, and Vietnam. The industry relies on petroleum-derived monomers like purified terephthalic acid (PTA) and monoethylene glycol (MEG). Commodity price volatility for crude oil presents a significant structural risk. Distribution runs through a network of integrated chemical conglomerates and specialized textile distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption, driven by the emergence of advanced chemical recycling technologies and circular economy mandates.
For Market Incumbents:
Insulate core business lines by investing heavily in advanced chemical recycling infrastructure to create closed-loop material streams. Deepen vertical integration into bio-based feedstock production to mitigate feedstock price volatility. Control key intellectual property for high-performance specialty fibers, guarding against new entrants in niche applications. Secure long-term supply agreements with major automotive and technical textile brands.
For New Entrants and Emerging Players:
Pursue white-space opportunities in bio-based polyester and smart textiles, targeting the performance apparel segment in North America and Europe. Focus on niche applications requiring high sustainability credentials, leveraging certifications like bluesign® approval for market entry. Develop agile manufacturing processes to offer customized, smaller-batch specialty fibers. Emphasize partnerships with innovative apparel brands seeking circular solutions.
For Investors and Strategic Acquirers:
The EU's Extended Producer Responsibility (EPR) frameworks reshape the acquisition landscape for textile recycling technologies. Long-term viability favors firms with robust intellectual property in chemical recycling or proprietary bio-based polymer formulations. Target specialty fiber manufacturers with established positions in high-value technical textile segments. The signal to watch is the increasing legislative momentum for mandatory recycled content targets in apparel and automotive applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Chemical Recycling | Enables conversion of post-consumer waste into virgin-quality material, meeting circularity mandates. |
| Investment in Bio-Based Polymer R&D | Reduces reliance on petrochemical feedstocks and aligns with corporate sustainability goals. |
| Strategic Partnerships for Smart Textiles | Accelerates market entry into high-margin wearable technology and healthcare monitoring applications. |
| Certification for Sustainable Production | Enhances market access and brand preference among industrial buyers with sustainability mandates. |
| Geographic Expansion into South Asia | Develops new supply chains and customer bases in expanding textile manufacturing hubs. |
Research Approach
A spread of perspectives from R&D directors, procurement managers, sustainability leads, and textile engineers converged on the working assumptions for the synthetic fiber market. This analysis combined insights from extensive primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included industry association reports, customs and trade data, company financial filings, and global regulatory databases. Bottom-up and top-down triangulation ensured data consistency.
The demand-supply-balance framing guided the analytical framework across the projection horizon. Segmentation dimensions included product type, application, end user, technology, and regional production capacity. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected market drivers. Key industry-specific forecast inputs included global petroleum prices and textile waste volumes available for recycling.
Sensitivities concentrate around geopolitical shifts affecting raw material availability and evolving regulatory landscapes. Forecasts reflect assumptions documented through stakeholder consensus and quantitative modeling. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Americas Spandex Market