
 Consumer Electronics Extended Warranty Market | 2026-2036
Consumer Electronics Extended Warranty Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Extended Warranty Market Analysis
Unbundling of warranty terms from retail purchase is decoupling coverage decisions from point-of-sale pressure. Asurion leverages its direct-to-consumer platform to sustain recurring engagement beyond initial device transactions. SquareTrade anchors its competitive stance through transparent flat-rate pricing structures that reduce buyer friction at online checkout.
Consumer electronics extended warranty denotes a service contract extending manufacturer defect coverage beyond standard terms, typically spanning one to five years and specifying repair, replacement, or reimbursement protocols contingent on failure mode. These instruments transfer residual device risk from owners to underwriters while generating predictable service revenue streams for issuers. Smartphone coverage dominates premium volume pools given elevated repair costs for OLED displays and foldable hinge mechanisms. Accidental damage protection represents the fastest-expanding service type as liquid immersion and screen fracture incidents outpace mechanical failure rates in portable devices. Third-party providers capture disproportionate margin in online retail channels where comparison shopping erodes authorized dealer attachment rates.
The Federal Trade Commission's Magnuson-Moss Warranty Act provisions govern disclosure standards in the United States, compelling explicit terms that reduce deceptive marketing exposure. The EU's CE marking framework and emerging Digital Product Passport requirements are extending traceability obligations to warranty fulfillment chains across European markets. China's State Administration for Market Regulation enforces format contract regulations that constrain unfair exclusion clauses in domestically sold electronics coverage. Stakeholders must monitor how right-to-repair legislation in multiple jurisdictions redefines the boundary between warranty service and independent repair eligibility.
Market Dynamics
The EU Green Deal's right-to-repair mandates are forcing warranty providers to restructure service obligations, decoupling authorized repair exclusivity from coverage validity and opening fulfillment networks to independent technicians across member states.
Growth Catalysts
- OLED Display Fragility:Foldable smartphones and curved-edge panels drive accidental damage protection attachment as screen replacement costs exceed $400 per incident.
- EU Digital Product Passport:Traceability requirements under emerging CE marking extensions create compliance-driven warranty standardization across European electronics supply chains.
- China Premium Handset Bundling:Domestic manufacturers attach multi-year extended coverage to flagship releases, normalizing protection plan expectations among urban consumers.
Market Restraints
- Authorized Service Network Concentration:Repair parts availability remains restricted to manufacturer-certified channels in Germany and France, inflating fulfillment costs for third-party underwriters.
- Lithium-Ion Battery Degradation:Portable device power cell replacement cycles accelerate faster than warranty term structures accommodate, creating coverage-value mismatches.
- FTC Magnuson-Moss Disclosure Burden:Explicit terms requirements increase compliance overhead for direct-to-consumer marketing campaigns in the United States.
Strategic Opportunities
- India Tier-2 Urban Expansion:Smartphone penetration in cities like Pune and Jaipur outpaces organized retail warranty penetration, creating white space for mobile-first distribution models.
- AI-Powered Claims Automation:Computer vision diagnostic tools reduce adjudication friction for screen damage verification, compressing resolution timelines from days to hours.
- Japan METI Circular Economy Incentives:Subsidies for repair-over-replacement business models align extended warranty economics with sustainability-mandated refurbishment obligations.
Industry Challenges
- Foldable Hinge Calibration Expertise:Mechanical complexity of emerging form factors exceeds technician training pipeline capacity, creating service quality variance across fulfillment networks.
- Cross-Border Data Localization:Claims processing platforms face fragmentation as China's SAMR data governance rules diverge from GDPR requirements for European policyholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Extended Warranty Market |
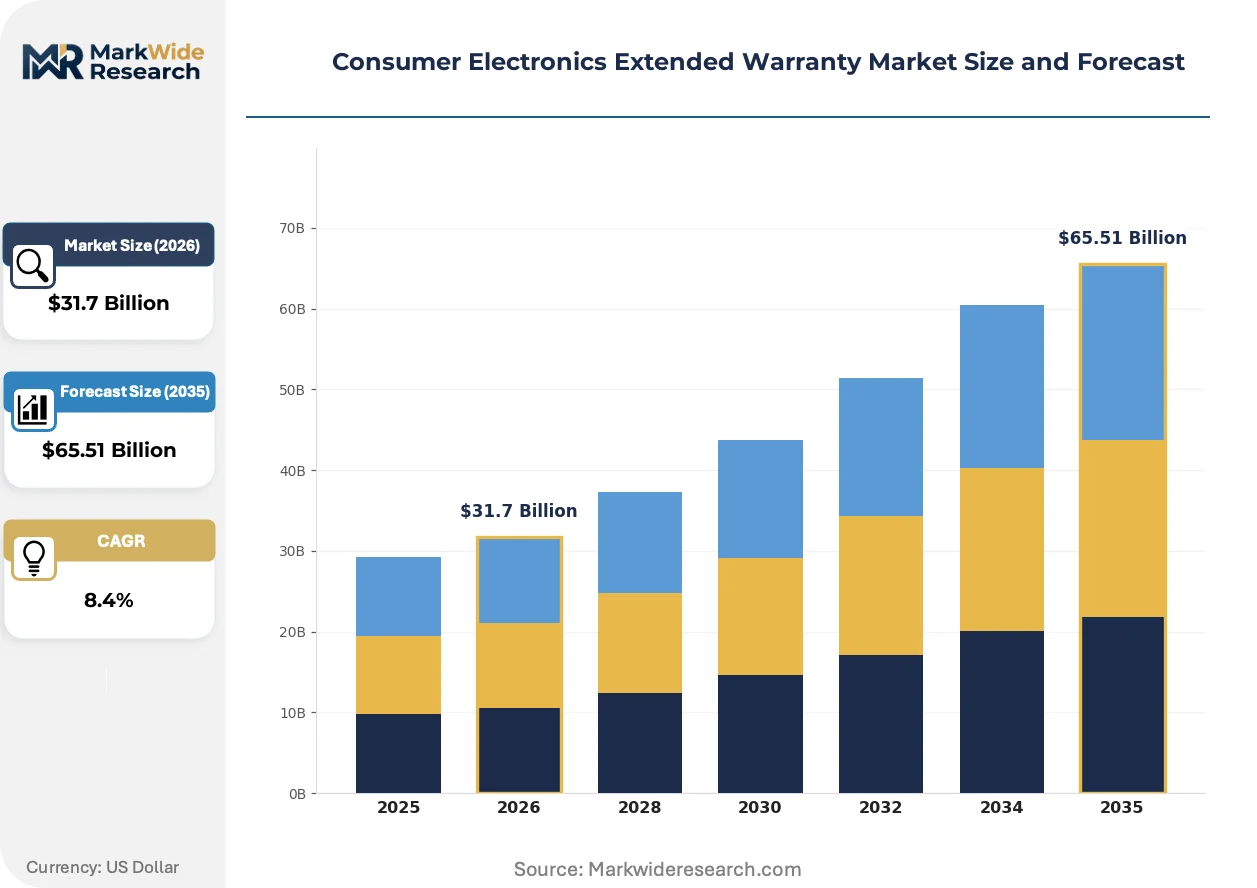
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $65.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Televisions, Home Appliances Service Type: Accidental Damage, Mechanical Failure, Replacement, Repair End User: Retail Consumers, Corporates, Educational Institutions, Government Agencies Distribution Channel: Online Retailers, Authorized Dealers, Direct Sales, Third-party Providers |
| Companies Covered | AXA, Amazon.com, Asurion, American International Group, Allianz Assistance, SquareTrade, AmTrust Financial, OneAssist Consumer Solutions, Assurant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Extended Warranty Market Emerging Trajectories
Embedded diagnostic telemetry and usage-based coverage pricing are restructuring how underwriters assess device risk, shifting from static term contracts to dynamic premium adjustments tied to actual handling patterns.
Parametric warranty triggers using accelerometer and gyroscope data are expanding into mid-tier smartphone segments, enabling instant claim approval without physical inspection. Asian handset manufacturers in South Korea and Taiwan embed these sensors as standard, accelerating adoption among price-sensitive buyers. This sensor integration is expanding into warranty pricing models that reward low-impact usage with discounted renewal rates.
REACH substance restrictions on repair adhesives and solvents are compelling European warranty providers to certify alternative bonding materials for screen assembly replacement. German and Italian service centers now source compliant thermal pastes and display laminates at 15-20% cost premiums. Component suppliers with pre-certified green chemistry portfolios capture preferential procurement status from major underwriters.
Unbundling of protection plans from point-of-sale transactions shifts purchase timing to post-activation windows, compressing attachment rate dependencies on retail staff training. Direct-to-consumer digital channels in the United States and United Kingdom now account for the majority of new policy issuance outside carrier stores. This behavioral pivot concentrates marketing spend on retargeting campaigns rather than retail commission structures.
Consumer Electronics Extended Warranty Market Segmentation
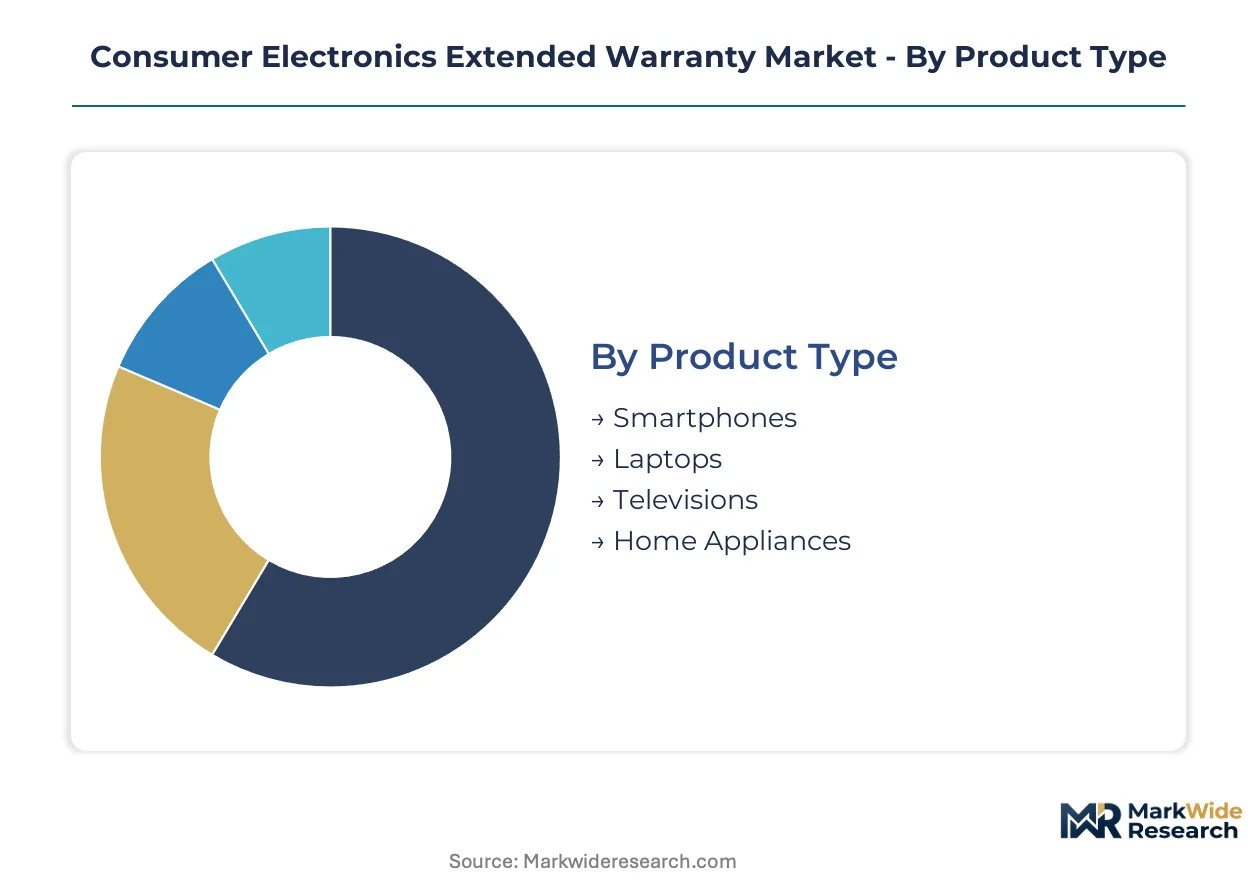
Extended warranty providers calibrate coverage terms, pricing models, and fulfillment networks around distinct product risk profiles and purchase behaviors. Segmentation precision determines attachment rates, loss ratios, and customer lifetime value across divergent device categories and buyer types.
Product Type:
Display technology fragility and repair cost asymmetries create divergent warranty economics across device categories.
- Smartphones:OLED and foldable displays command replacement costs exceeding $400 per incident, concentrating premium protection plan demand among flagship handset owners. Urban consumers in China bundle multi-year coverage with premium releases, normalizing extended warranty expectations.
- Laptops:Enterprise fleet deployments and remote work permanence sustain corporate volume pools, though consumer attachment lags as device replacement cycles extend beyond typical warranty terms. Battery degradation outpaces standard coverage windows, creating value perception gaps.
- Televisions:Large-format panel replacement economics favor protection plans for screens above 65 inches, where single-incident repair costs approach 40% of original purchase price.
- Home Appliances:Smart connectivity features expand failure modes beyond mechanical components to firmware and sensor arrays, complicating traditional coverage definitions.
Smartphones lead on scale; accidental damage protection for foldable displays leads on momentum.
Service Type:
Failure mode specificity shapes underwriting risk pools and claims adjudication infrastructure requirements.
- Accidental Damage:Liquid immersion and screen fracture incidents outpace mechanical failure rates in portable devices, expanding fastest among smartphone protection plans. Parametric triggers using accelerometer data enable instant claim approval without physical inspection.
- Mechanical Failure:Component defect coverage retains standardized pricing structures but faces margin compression as manufacturer quality improvements extend mean time between failures.
- Replacement:Total device swap provisions concentrate in premium tiers where repair cost thresholds exceed economic viability, common in high-end laptop and flagship smartphone segments.
- Repair:Refurbishment obligations under Japan METI circular economy incentives align extended warranty economics with sustainability mandates, subsidizing repair-over-replacement business models.
Accidental damage leads on scale; parametric instant-approval repair services lead on momentum.
End User:
Procurement authority and volume concentration determine pricing power and service level customization depth.
- Retail Consumers:Individual purchasers exhibit high price sensitivity to flat-rate structures, driving SquareTrade's transparent online checkout positioning. Direct-to-consumer channels now dominate policy issuance outside carrier stores in the United States and United Kingdom.
- Corporates:Fleet-scale deployments negotiate customized coverage terms with dedicated service level agreements, prioritizing device uptime over per-unit premium minimization.
- Educational Institutions:One-to-one device programs create predictable volume pools with standardized device configurations, simplifying risk assessment and enabling bulk pricing.
- Government Agencies:Procurement regulations mandate specific disclosure standards under FTC Magnuson-Moss provisions in the United States, increasing compliance overhead for contract fulfillment.
Retail consumers lead on scale; corporate fleet programs lead on momentum.
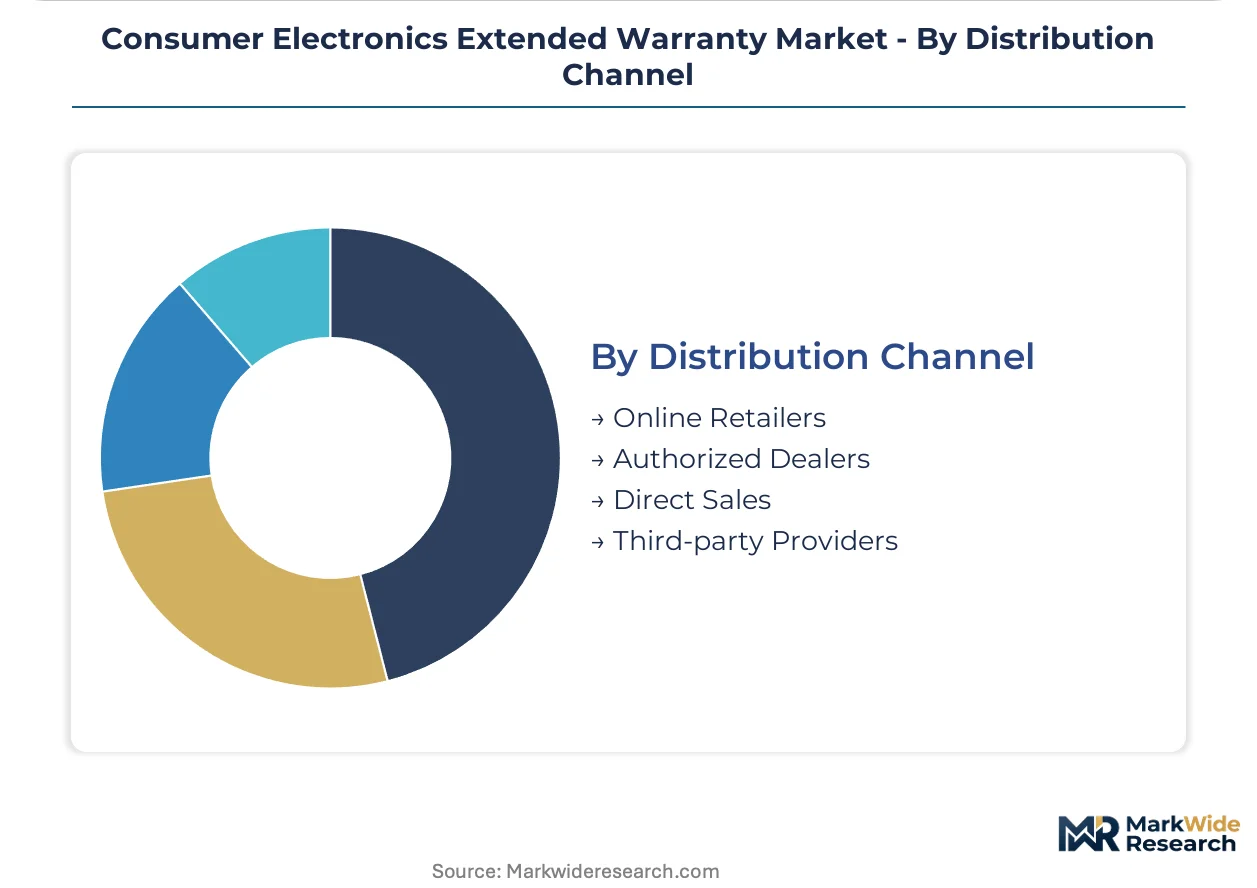
Distribution Channel:
Channel economics determine attachment rate dependencies and customer acquisition cost structures.
- Online Retailers:Comparison shopping functionality erodes authorized dealer attachment rates, concentrating third-party provider margin capture in digital checkout flows. Unbundling from point-of-sale transactions shifts purchase timing to post-activation windows.
- Authorized Dealers:Manufacturer-certified channels retain repair parts exclusivity in Germany and France, inflating fulfillment costs for competing underwriters while sustaining premium positioning.
- Direct Sales:Asurion leverages its direct-to-consumer platform to sustain recurring engagement beyond initial device transactions, reducing retail commission dependencies.
- Third-party Providers:Independent underwriters capture disproportionate margin where regulatory fragmentation—between China's SAMR data governance and GDPR requirements—creates operational complexity.
Online retailers lead on scale; direct-to-consumer platforms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumer electronics extended warranty industry traces its commercial scale to post-war American retail, where department stores first bundled service contracts with appliance sales. European and Asian markets subsequently developed distinct regulatory frameworks and distribution cultures around these instruments.
United States
Direct-to-consumer digital channels now dominate policy issuance outside carrier stores, with unbundling shifting purchase timing to post-activation windows. The FTC Magnuson-Moss Warranty Act governs disclosure standards, compelling explicit terms that reduce deceptive marketing exposure. California and Texas concentrate third-party provider headquarters, where Asurion leverages its platform for recurring engagement beyond initial transactions.
China
Domestic manufacturers attach multi-year extended coverage to flagship handset releases, normalizing protection plan expectations among urban consumers. The State Administration for Market Regulation enforces format contract regulations constraining unfair exclusion clauses in domestically sold electronics coverage. Shenzhen and Beijing anchor premium bundling activity, with Yangtze River Delta cities driving volume through organized retail partnerships.
Germany
Authorized service network concentration restricts repair parts availability to manufacturer-certified channels, inflating fulfillment costs for third-party underwriters. REACH substance restrictions on repair adhesives and solvents compel warranty providers to certify alternative bonding materials for screen assembly replacement. Bavaria and North Rhine-Westphalia host major service center networks where compliant thermal pastes and display laminates command procurement premiums.
Japan
METI circular economy incentives subsidize repair-over-replacement business models, aligning extended warranty economics with sustainability-mandated refurbishment obligations. Embedded diagnostic telemetry enables usage-based coverage pricing restructuring risk assessment toward dynamic premium adjustments. Tokyo and Osaka metropolitan areas concentrate parametric warranty trigger development using accelerometer and gyroscope data for instant claim approval.
United Kingdom
Comparison shopping functionality erodes authorized dealer attachment rates, concentrating third-party provider margin capture in digital checkout flows. GDPR requirements for claims processing create operational complexity diverging from other jurisdictions' data governance rules. London and Southeast England anchor direct-to-consumer marketing spend, with retargeting campaigns replacing traditional retail commission structures.
Consumer Electronics Extended Warranty Market Vendor Landscape
The competitive structure tilts toward diversified insurance conglomerates with consumer-facing technology platforms. Market concentration remains moderate, with tiered positioning separating integrated underwriters from specialized warranty administrators. Three archetypes dominate: legacy insurers with captive warranty subsidiaries, technology-native administrators leveraging direct distribution, and retail-embedded service contract issuers. Geographic expansion and portfolio diversification constitute the primary competitive vectors, with players acquiring regional licenses and adding adjacent device categories to core smartphone coverage.
Among diversified insurance groups, AXA and Allianz Assistance exemplify the integrated underwriter archetype, combining balance sheet capacity with European regulatory expertise. Asurion and SquareTrade occupy positions within the technology-native tier, with the former representing direct-to-consumer platform development and the latter anchoring transparent flat-rate pricing structures. These four entities collectively illustrate the strategic divergence between insurance-backed and technology-driven market approaches.
| Leading Market Players |
|---|
| AXA |
| Amazon.com |
| Asurion |
| American International Group |
| Allianz Assistance |
| SquareTrade |
| AmTrust Financial |
| OneAssist Consumer Solutions |
| Assurant |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up warranty administrators anchor pricing discipline through captive repair networks, compressing third-party fulfillment margins while sustaining premium positioning for integrated underwriters with balance sheet capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates consumer electronics extended warranty markets, with premium tiers bundling accidental damage and expedited replacement while economy tiers cover mechanical failure only. Price differentiation hinges on coverage breadth and device replacement value thresholds, with flagship smartphone protection commanding multiples over entry-tier laptop coverage. Cost compression in economy tiers is intensifying because online comparison shopping erodes attachment rates at checkout. Retail consumers exhibit highest price sensitivity to flat-rate structures, while corporate fleet buyers prioritize uptime guarantees over per-unit premium minimization.
Supply Chain Analysis
Domestic-content mandates under EU Green Deal right-to-repair provisions are reshaping sourcing patterns, compelling warranty providers to certify independent technician networks and alternative bonding materials for screen assembly replacement. Repair parts availability draws from manufacturer-certified channels in Germany, France, and Japan, with third-party underwriters sourcing compliant thermal pastes and display laminates at procurement premiums. Single-source vulnerability concentrates in OLED panel replacement components, where authorized dealer exclusivity constrains fulfillment network expansion. Distribution runs through direct-to-consumer digital platforms in the United States and United Kingdom, with carrier stores and organized retail partnerships sustaining volume in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer electronics extended warranty market functions as a stable compounder, with device replacement cost escalation and repair complexity sustaining recurring revenue pools across economic cycles.
For Market Incumbents: Extend platform capabilities into embedded diagnostic telemetry and usage-based pricing models, capturing dynamic risk assessment advantages as parametric triggers displace static term contracts. Fortify authorized service network exclusivity in Germany and France against right-to-repair regulatory encroachment through pre-certified technician training pipeline investments. Vertical integration into claims adjudication automation compresses resolution timelines from days to hours, defending margin position against technology-native entrants. For New Entrants and Emerging Players: AI-powered computer vision diagnostic tools offer a technology-first wedge into screen damage verification workflows, bypassing incumbent physical inspection infrastructure. Target India's tier-2 urban markets—Pune, Jaipur, Hyderabad—where smartphone penetration outpaces organized retail warranty attachment, enabling mobile-first distribution models. Pursue white-label partnerships with domestic handset manufacturers bundling coverage with premium releases, mirroring China market normalization patterns. For Investors and Strategic Acquirers: Valuations sit cheapest among regional warranty administrators lacking direct-to-consumer platform scale or balance sheet backing. The consumer electronics extended warranty sector offers 5-10 year visibility through embedded device protection normalization and repair-cost inflation. Acquisition focus: technology-native administrators with parametric claims infrastructure and India market licenses. Watch for inflection in foldable handset adoption rates, which concentrate premium protection plan demand through elevated hinge calibration and display replacement costs.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Platform Development | Accelerometer-triggered instant approval compresses adjudication timelines from days to hours for screen damage. |
| Independent Technician Network Certification | EU Green Deal compliance decouples authorized repair exclusivity from coverage validity across member states. |
| Usage-Based Coverage Pricing Launch | Embedded diagnostic telemetry enables dynamic premium adjustments tied to actual device handling patterns. |
| India Tier-2 Market Expansion | Mobile-first distribution models capture white space in Pune and Jaipur where organized retail penetration lags. |
| Green Chemistry Procurement Standard | REACH-compliant thermal pastes and display laminates secure preferential supplier status from major underwriters. |
Methodological Framework
Direct dialogue with warranty operations executives, claims adjudication specialists, device manufacturer service strategy leads, and insurance underwriter product managers grounded qualitative findings, cross-referenced against regulatory filings from the FTC and EU CE marking frameworks, customs data on repair component trade flows, and SEC disclosures from diversified insurance groups. Bottom-up triangulation against top-down market sizing validated volume estimates across the analysis window.
Segment-level outputs across product type, service type, end user, and distribution channel dimensions were modeled through the projection horizon, with CAGRs derived from historical attachment rate trajectories, device replacement cost inflation curves, and regulatory implementation timelines. Foldable handset adoption forecasts and right-to-repair legislative progression served as category-specific demand drivers.
The model holds under steady regulatory implementation schedules and continued device complexity escalation; deviation in tariff exposure for repair components or accelerated battery degradation cycles would shift loss ratio assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Solar Panel Warranty Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Cannabis Crop Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Cargo Insurance Market
Insurance
Art Insurance Market
Insurance
Digital Insurance Market
Insurance
AI in Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Endowment Insurances Market
Insurance
Insurance Analytics Market
Insurance
France Car Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Insurance Big Data Analytics Market