
 Takaful Market | 2026-2036
Takaful Market Size, Share, and Industry Trends Forecast 2026-2036
Takaful Market Intelligence
Subscription-based family Takaful coverage is shifting how insurers monetize long-term relationships with policyholders. Etiqa leverages its bancassurance network to dominate retail distribution across Malaysia. Prudential BSN Takaful Berhad differentiates through specialized health Takaful products targeting middle-income households. Salama Islamic Arab Insurance Company anchors its competitive position in the GCC through general Takaful lines.
Takaful denotes a cooperative insurance system grounded in Islamic principles where participants contribute to a shared pool for mutual protection against defined risks, operating through mudarabah or wakala contracts with strict Shariah board oversight. Its primary commercial purpose centers on providing risk mitigation instruments compliant with Islamic commercial law, prohibiting riba, gharar, and maysir. Family Takaful commands the deepest premium pools due to long-term savings-linked structures, while health Takaful exhibits the fastest trajectory as national health reforms across Muslim-majority economies expand mandatory coverage. Distribution through bancassurance channels captures superior margins where Islamic banking penetration is highest.
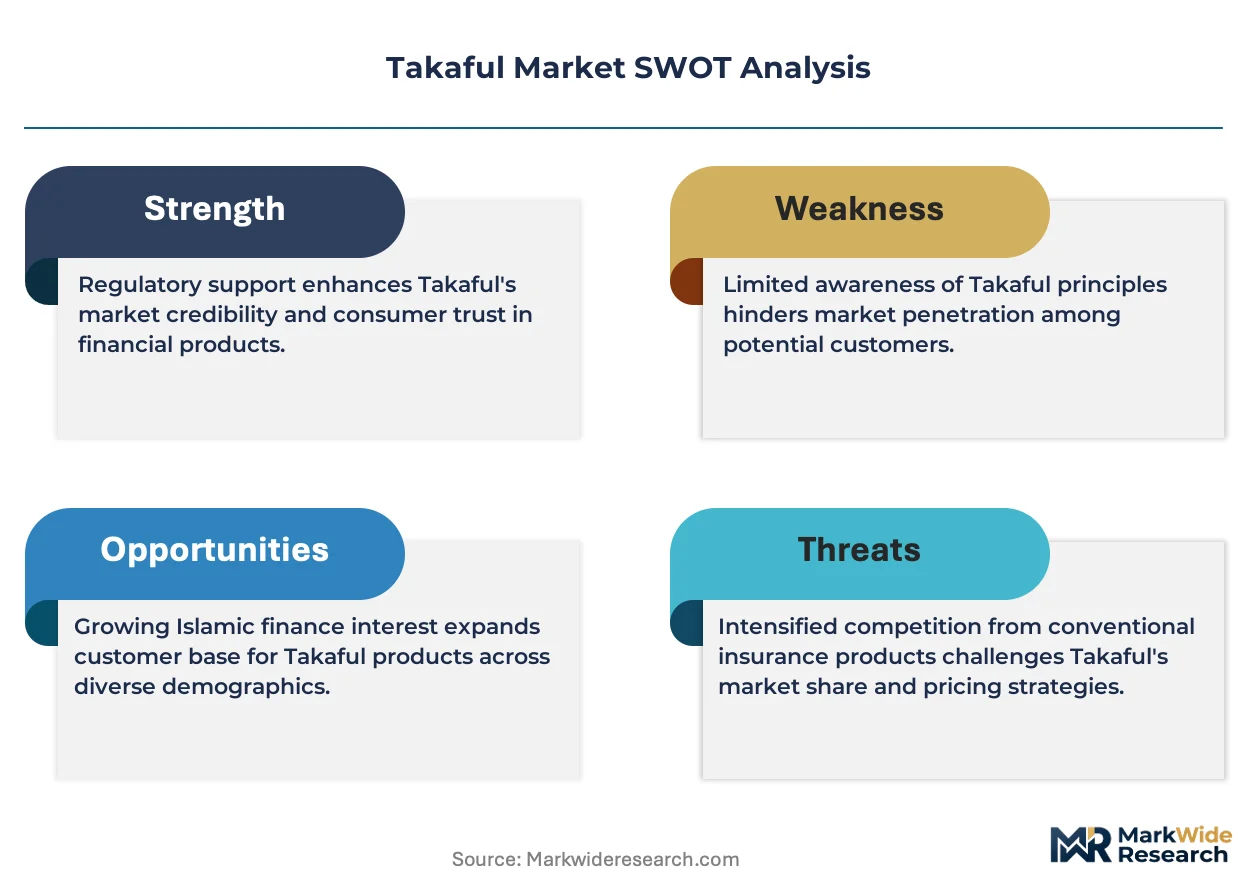
Malaysia's Bank Negara Malaysia and the Securities Commission Malaysia enforce Shariah governance frameworks that mandate independent advisory boards and segregated Takaful funds. Saudi Arabia's SAMR and the UAE's central insurance authority impose capital adequacy and retakaful requirements that shape product design and market entry. Indonesia's OJK regulates takaful operators through dedicated sharia business unit rules that influence solvency standards. Stakeholders must monitor evolving regulatory harmonization between national Islamic finance authorities and conventional insurance equivalence agreements.
Market Dynamics
Shariah-compliant digital underwriting platforms are modularizing policy issuance and claims processing across Muslim-majority economies, compressing operational costs while expanding retail accessibility to cooperative insurance products.
Growth Catalysts
- Mandatory Health Coverage Reforms:National health insurance mandates across Indonesia and Saudi Arabia are accelerating household participation in health Takaful schemes. OJK regulations in Indonesia require universal coverage expansion by 2025.
- Islamic Banking Penetration:Bancassurance distribution networks in Malaysia leverage existing Islamic banking relationships to reduce customer acquisition costs. Bank Negara Malaysia's regulatory framework permits seamless cross-selling through sharia-compliant channels.
- Wakala Contract Standardization:Standardized agency-based Takaful structures are simplifying fund management and profit distribution. SAMR in Saudi Arabia has issued specific capital treatment rules for wakala-based general Takaful products.
Market Restraints
- Retakaful Capacity Constraints:Limited reinsurance availability within sharia-compliant frameworks forces operators to retain higher risk exposure. GCC markets face particular scarcity of retakaful providers.
- Shariah Scholar Scarcity:Qualified Islamic jurists capable of serving on independent advisory boards command premium compensation. Malaysia and Indonesia compete for the same finite pool of AAOIFI-certified scholars.
- Conventional Insurance Substitution:Price-competitive conventional products in price-sensitive segments divert potential Takaful participants. UAE and Saudi Arabian markets show particular vulnerability to this switching behavior.
Strategic Opportunities
- Micro-Takaful Penetration:Bangladesh and Pakistan present substantial underpenetrated demand for low-premium cooperative coverage. Agricultural and informal sector workers lack accessible sharia-compliant risk products.
- Digital-First Distribution:Mobile-first policy issuance through fintech partnerships bypasses traditional agent networks. Indonesia's OJK permits sandbox testing for app-based Takaful onboarding.
- Family Takaful Savings Integration:Long-term savings-linked structures align with mandatory pension reforms across GCC states. SAMR guidelines encourage hybrid protection-investment products for expatriate workers.
Industry Challenges
- Actuarial Talent Shortage:Dual-qualified professionals combining conventional insurance mathematics with sharia jurisprudence remain scarce. Training programs at IIUM and INCEIF cannot match operator demand.
- Legacy System Integration:Core policy administration platforms require expensive reconfiguration to support mudarabah profit-sharing calculations. Malaysian operators report 18-24 month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Takaful Market |
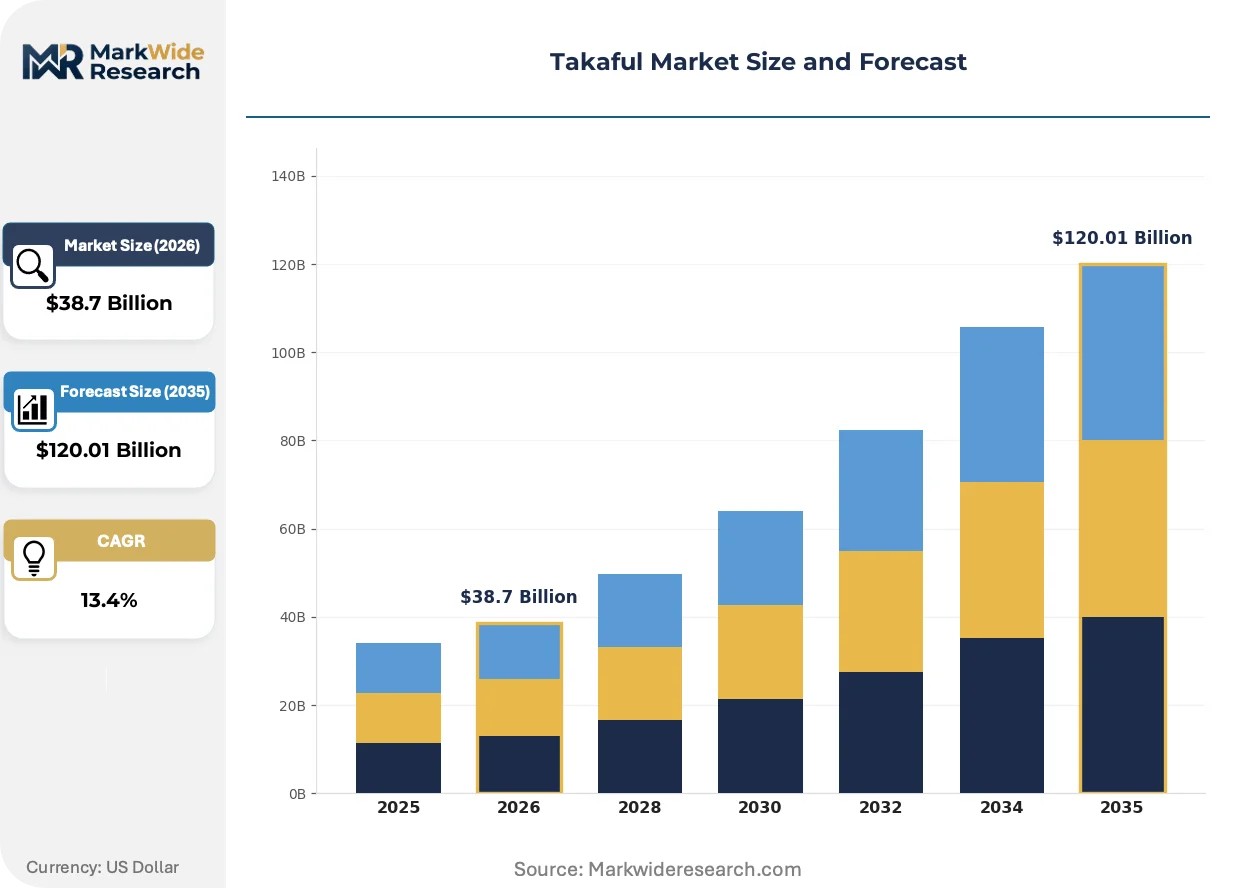
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $120.01 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Family Takaful, General Takaful, Health Takaful, Investment Takaful Distribution Channel: Agents, Brokers, Bancassurance, Direct Sales Customer Type: Individuals, Corporates, SMEs, Government End User: Retail Clients, Businesses, Non-Profit Organizations, Institutional Investors |
| Companies Covered | Takaful Emarat, Qatar Islamic Insurance Company, Abu Dhabi National Takaful Co., Great Eastern Takaful Berhad, Syarikat Takaful Malaysia, Prudential BSN Takaful Berhad, Etiqa, HSBC Amanah Malaysia Berhad, Salama Islamic Arab Insurance Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Takaful Market Strategic Shifts & Innovations
Cooperative insurance architecture is undergoing fundamental restructuring as digital infrastructure, regulatory harmonization, and demographic shifts reshape how risk pools form and operate across Islamic finance jurisdictions.
Blockchain-enabled smart contracts are modularizing claims settlement workflows by automating verification against predefined sharia-compliant conditions. Malaysian Takaful operators piloting these systems report 40% reduction in dispute resolution cycles. The technology is modularizing traditional two-tier governance structures into transparent, participant-auditable fund management layers.
AAOIFI's revised sharia standards on Takaful operations are harmonizing contract definitions across Malaysia, Saudi Arabia, and UAE regulatory frameworks. This standardization reduces product development friction for multi-jurisdictional operators. Family Takaful providers with GCC and Southeast Asian licenses are consolidating product architectures to exploit regulatory convergence.
Subscription-based coverage models are displacing single-premium family Takaful structures among millennial policyholders in Indonesia and Malaysia. Digital-native distributors bundle monthly micro-payments with Islamic banking transaction accounts. This behavioral shift concentrates in urban Indonesian markets where OJK permits flexible contribution schedules.
Takaful Market Segmentation
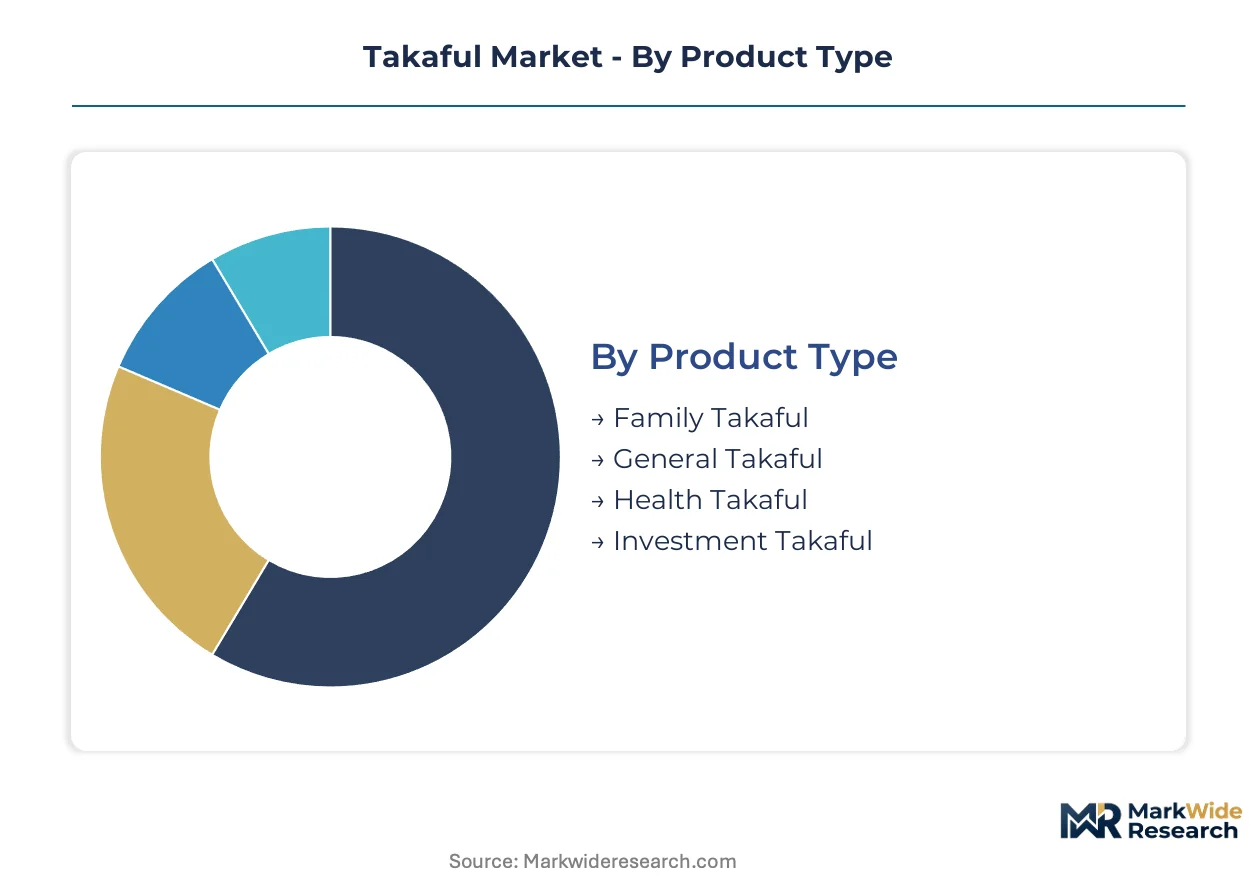
Takaful operators structure product architectures around sharia compliance depth, distribution economics, and participant risk profiles. Segmentation choices directly determine capital allocation between mudarabah profit-sharing pools and wakala fee-based structures across Southeast Asian and GCC markets.
Product Type:
Standardization dominates savings-linked structures while risk-only products permit greater contractual variation across jurisdictions.
- Family Takaful:Long-term savings-linked cooperative structures combine protection with investment components through mudarabah contracts. Demand concentrates in Malaysia and Indonesia where Bank Negara Malaysia and OJK mandate segregated participant funds with explicit profit-sharing schedules.
- Health Takaful:Medical expense reimbursement and critical illness coverage operate through wakala or hybrid models. Saudi Arabia's SAMR universal coverage mandates and Indonesia's BPJS integration are accelerating household penetration fastest across Muslim-majority economies.
- General Takaful:Property and liability protection for commercial assets.
- Investment Takaful:Capital-appreciation focused vehicles with embedded takaful protection.
Leading the category by volume: Family Takaful. Expanding most quickly: Health Takaful.
Distribution Channel:
Cost-to-acquire varies dramatically by channel density and existing financial infrastructure penetration.
- Bancassurance:Islamic banking networks provide pre-qualified customer bases with established sharia compliance relationships. Malaysian operators leveraging Maybank and CIMB Islamic distribution report superior persistency rates versus agent-sourced policies.
- Agents:Commission-based individual representatives dominate rural Indonesian markets where OJK permits flexible qualification tiers.
- Brokers:Corporate placement specialists handle large commercial general takaful accounts.
- Direct Sales:Digital-first onboarding through mobile applications and web platforms.
Highest margin capture: Bancassurance. Fastest channel expansion: Direct Sales.
Customer Type:
Contract complexity escalates with participant scale and governance requirements.
- Individuals:Retail participants seeking family protection and savings accumulation. Malaysian middle-income households drive recurring premium structures through salary deduction arrangements with Islamic employers.
- Corporates:Large employers arranging group health and term coverage for expatriate workforces. Saudi Arabia's SAMR guidelines encourage hybrid protection-investment products for this segment.
- SMEs:Small and medium enterprises with limited risk management departments.
- Government:Public sector employee schemes and social protection programs.
Deepest premium pools: Individuals. Steepest expansion trajectory: Corporates.
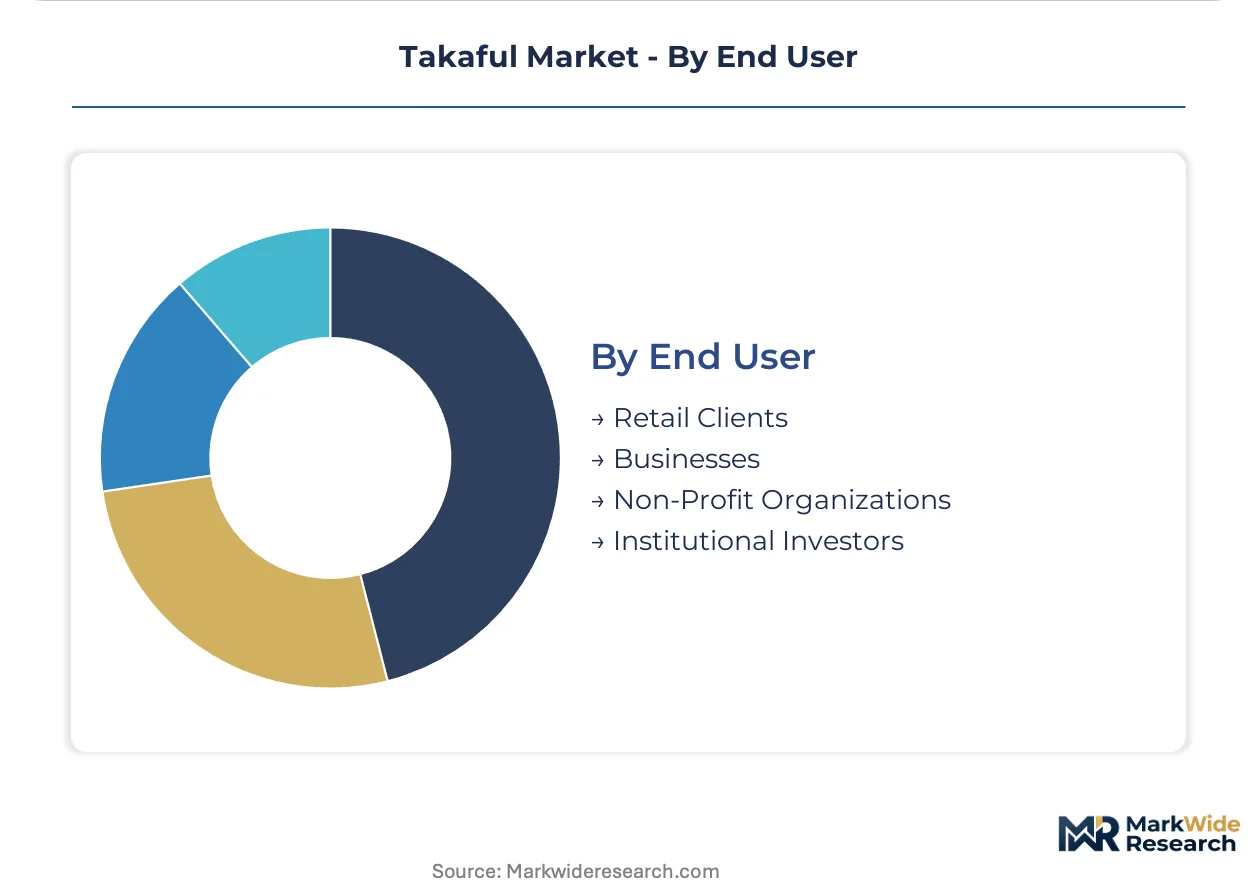
End User:
Risk pooling mechanics differ fundamentally between commercial profit motives and cooperative mutual protection.
- Retail Clients:Individual and household participants in family and health takaful schemes. Indonesian urban millennials are shifting subscription-based micro-payment models through OJK-sandboxed fintech partnerships.
- Businesses:Commercial entities seeking asset protection and employee benefits. GCC construction and logistics sectors generate concentrated general takaful demand.
- Non-Profit Organizations:Charitable and waqf-based entities with unique governance requirements.
- Institutional Investors:Pension funds and sovereign vehicles allocating to investment takaful.
Volume concentration: Retail Clients. Gaining share fastest: Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia generates the deepest Takaful premium pools through mature Islamic finance infrastructure, while Gulf Cooperation Council states concentrate high-value family Takaful demand. Indonesia's regulatory mandates are accelerating household penetration fastest across Muslim-majority economies.
Malaysia
Bank Negara Malaysia's Shariah governance frameworks mandate segregated participant funds with explicit profit-sharing schedules. Family Takaful dominates premium volumes through bancassurance networks anchored by Maybank and CIMB Islamic distribution. Kuala Lumpur's Labuan International Business and Financial Centre hosts regional retakaful capacity serving Southeast Asian operators.
Saudi Arabia
SAMR's universal health coverage mandates and wakala contract standardization are accelerating household participation in cooperative insurance schemes. The regulator has issued specific capital treatment rules for agency-based general Takaful products. Riyadh anchors the kingdom's largest Takaful operator concentration, with Jeddah handling commercial general lines for Red Sea logistics and construction sectors.
Indonesia
OJK regulations requiring universal coverage expansion by 2025 are driving health Takaful adoption among previously uninsured households. The regulator permits sandbox testing for app-based Takaful onboarding through fintech partnerships. Jakarta and Surabaya concentrate digital-native distribution targeting urban millennials with subscription-based micro-payment models.
United Arab Emirates
The UAE's central insurance authority imposes capital adequacy and retakaful requirements that shape product design for domestic and expatriate populations. Dubai International Financial Centre hosts regional headquarters for multi-jurisdictional operators serving GCC markets. Abu Dhabi concentrates sovereign-linked family Takaful schemes for public sector employees.
Qatar
Qatar Central Bank regulations enforce Shariah board independence and fund segregation for domestic Takaful operators. Natural gas sector expatriate workforces generate concentrated group health and term coverage demand. Doha's financial district hosts specialist retakaful capacity serving underpenetrated markets across the Gulf Cooperation Council.
Takaful Market Key Industry Players
Capital-heavy Takaful operators with captive retakaful arrangements compete with asset-light digital distributors relying on third-party reinsurance treaties. The market structure fragments across bancassurance-anchored incumbents, specialist health Takaful providers, and emerging fintech-enabled platforms. Three archetypes dominate: Islamic banking-integrated conglomerates, standalone Takaful specialists, and hybrid conventional-sharia operators. Competitive moves concentrate on bancassurance network expansion and digital-first customer acquisition partnerships.
Within the bancassurance-integrated tier, Etiqa and HSBC Amanah Malaysia Berhad exemplify operators leveraging existing Islamic banking relationships to reduce customer acquisition costs. Among standalone specialists, Salama Islamic Arab Insurance Company anchors competitive positioning in general Takaful lines across GCC markets. Prudential BSN Takaful Berhad occupies a distinct position through health Takaful specialization targeting middle-income households. These three operators represent contrasting strategic archetypes: banking-conglomerate distribution power, regional generalist scale, and product-focused segmentation.
| Leading Market Players |
|---|
| Takaful Emarat |
| Qatar Islamic Insurance Company |
| Abu Dhabi National Takaful Co. |
| Great Eastern Takaful Berhad |
| Syarikat Takaful Malaysia |
| Prudential BSN Takaful Berhad |
| Etiqa |
| HSBC Amanah Malaysia Berhad |
| Salama Islamic Arab Insurance Company |
| Others |
Cost & Logistics Intelligence
Bank Negara Malaysia's Shariah governance frameworks mandate segregated participant funds with explicit profit-sharing schedules, gating both qualified supply and premium-tier pricing access for operators seeking bancassurance distribution partnerships.
Pricing Analysis
Margin tightening in subscription-based family Takaful reflects digital-native distributors bundling monthly micro-payments with Islamic banking transaction accounts. Pricing stratifies across mudarabah profit-sharing tiers, wakala fee-based structures, and hybrid protection-investment products, with certification depth and bancassurance channel access as primary differentiation drivers. Cost compression accelerates in health Takaful as OJK-mandated universal coverage expansion forces competitive rate-setting. Retail participants in Indonesian urban markets exhibit highest price sensitivity, while GCC expatriate corporate schemes show lowest elasticity due to employer-sponsored structures.
Supply Chain Analysis
Dual-sourcing requirements for retakaful capacity force Malaysian and Indonesian operators to maintain relationships with both Labuan International Business and Financial Centre providers and Doha-based specialists. The supply chain draws from Malaysia, Saudi Arabia, and UAE as primary hubs for Shariah-compliant reinsurance capacity. Raw material dependencies center on actuarial talent pools, AAOIFI-certified scholar networks, and digital underwriting platform infrastructure. Single-source vulnerability concentrates in qualified Islamic jurist availability, where Malaysia and Indonesia compete for finite AAOIFI-certified talent. Distribution runs through bancassurance networks anchored by Islamic banking relationships, supplemented by direct digital onboarding through OJK-sandboxed fintech partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Takaful market is becoming a vertical-integration race, with operators pursuing captive retakaful arrangements to secure capacity and reduce dependency on third-party sharia-compliant reinsurance treaties.
For Market Incumbents: Deepen backward integration into retakaful capacity through Labuan International Business and Financial Centre licensing or Doha-based specialist partnerships to defend against retakaful scarcity constraining risk retention. Reinforce bancassurance channel control through exclusive distribution arrangements with Maybank and CIMB Islamic networks, while accelerating legacy system reconfiguration to support mudarabah profit-sharing calculations before digital-native distributors capture millennial subscription demand. For New Entrants and Emerging Players: Begin with micro-Takaful penetration in Bangladesh and Pakistan agricultural sectors, where informal sector workers lack accessible sharia-compliant risk products and regulatory barriers remain lower than mature Southeast Asian markets. Target OJK-sandboxed fintech partnerships for app-based onboarding in Indonesian urban millennial segments, leveraging subscription-based micro-payment models that bypass traditional agent commission structures. For Investors and Strategic Acquirers: SAMR's issuance of specific capital treatment rules for wakala-based general Takaful products is the leading indicator that Saudi Arabia's regulatory convergence will consolidate multi-jurisdictional operator architectures around standardized contract definitions. Position for acquisition of standalone Takaful specialists with GCC and Southeast Asian dual licensing, as AAOIFI harmonization reduces product development friction. Watch for OJK universal coverage mandate acceleration as the signal for Indonesian health Takaful inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Retakaful Capacity Integration | Captive reinsurance arrangements through Labuan and Doha hubs reduce dependency on scarce sharia-compliant capacity. |
| Digital-First Distribution Launch | OJK-sandboxed fintech partnerships enable mobile-first onboarding that bypasses traditional agent network economics. |
| Shariah Scholar Certification Investment | AAOIFI-certified jurist pipelines at IIUM and INCEIF secure advisory board independence amid talent scarcity. |
| Cross-Border Product Architecture Consolidation | Harmonized mudarabah and wakala structures exploit regulatory convergence between Malaysia, Saudi Arabia, and UAE. |
| Bancassurance Network Expansion | Exclusive distribution through Maybank and CIMB Islamic captures pre-qualified customer bases with established sharia relationships. |
Research Approach
Multi-period observation of premium pool formation, regulatory filing patterns, and Shariah board composition changes anchored the trend analysis, supplemented by interviews with Takaful product development executives, Bank Negara Malaysia regulatory affairs leads, OJK licensing officers, bancassurance channel managers at Islamic banks, and retakaful underwriting specialists. Secondary validation drew from SAMR insurance regulatory circulars, AAOIFI sharia standards documentation, OJK sandbox approval records, and Labuan IBFC licensing databases. Bottom-up participant fund flow analysis triangulated against top-down regulatory mandate impact assessment.
The input-output matrix framed projections across product type segmentation, distribution channel economics, customer scale governance requirements, and end-user risk pooling mechanics. Modeled dimensions included mudarabah versus wakala contract structures, bancassurance versus direct digital channel penetration, and retail versus corporate participant profiles. CAGRs were derived from premium volume trajectory analysis against regulatory mandate implementation timelines, incorporating Shariah scholar supply constraints and retakaful capacity availability as industry-specific forecast inputs.
Underlying measurement precision varies by segment; health Takaful expansion trajectories carry tighter precision than micro-Takaful penetration estimates due to OJK mandate clarity versus informal sector data scarcity. Forecasts reflect assumptions around regulatory harmonization pace, AAOIFI standard adoption rates, and digital infrastructure deployment timelines. Deviation in retakaful capacity expansion or Shariah scholar pipeline output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
India Liability Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Microinsurance Market
Insurance
Reinsurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Income Protection Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Trade Credit Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Engineering Insurance Market