
 UK Commercial Insurance Market | 2026-2036
UK Commercial Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Commercial Insurance Market Intelligence
Modular policy bundling is consolidating buyer preference across the UK commercial insurance landscape. Aviva plc leverages its multi-line platform to anchor mid-market clients with integrated property and liability solutions. Allianz Insurance plc competes through engineering-led risk services that extend into construction and manufacturing verticals. Lloyd's of London sustains its position in specialty and excess lines through syndicate-based capital deployment.
UK commercial insurance encompasses risk-transfer instruments designed to indemnify businesses against property damage, third-party liability, operational interruption, and emerging digital perils, with policies typically structured around named perils, aggregate limits, and claims-made or occurrence triggers. The primary purpose centers on stabilizing enterprise cash flows and satisfying contractual or regulatory risk-financing obligations. Property insurance dominates premium volume among policy types, reflecting persistent exposure to flood, fire, and supply-chain disruption across industrial estates. Cyber insurance represents the fastest-expanding segment as ransomware frequency and regulatory notification mandates intensify. SME customer types generate the most dynamic growth pool, though corporations retain superior margin profiles through customized coverage and captive alternatives.
The Prudential Regulation Authority and Financial Conduct Authority jointly govern carrier solvency and conduct standards, while the UK government's Building Safety Act imposes new liability cascades on construction insurers. These frameworks elevate capital charges for long-tail lines and mandate clearer policy-wording transparency, directly shaping product design and distribution economics. Stakeholders must monitor how the transition from Solvency II to the UK-specific prudential regime alters competitive dynamics between domestic carriers and international branches.
Market Dynamics
The Prudential Regulation Authority's recalibration of capital adequacy requirements is compressing carrier balance-sheet capacity while simultaneously accelerating demand for modular, multi-line coverage bundles among mid-market enterprises.
Growth Catalysts
- The Building Safety Act:New liability cascades imposed by this UK legislation are compelling construction firms to expand professional indemnity and latent-defect coverage, directly expanding premium pools for long-tail lines.
- SME digitalization:Small and medium enterprises across Greater London and the South East are consolidating procurement of property and liability packages, creating concentrated demand for integrated policy architectures.
- Cyber-physical convergence:Industrial IoT deployments in manufacturing and logistics estates are generating correlated risk exposures that favor bundled property-cyber policies over standalone coverage.
Market Restraints
- Reinsurance capacity tightening:Lloyd's syndicates and international reinsurers are constraining retrocession capacity for UK catastrophe-exposed property lines, elevating net retention burdens for primary carriers.
- Long-tail reserve volatility:Asbestos and historical pollution liabilities continue to distort loss-development triangles, forcing the Prudential Regulation Authority to impose heavier capital charges on employers' liability and public liability writers.
- Interest rate compression on matching portfolios:Solvency II-derived discounting methodologies penalize carriers writing long-duration casualty business, compressing reported returns on capital.
Strategic Opportunities
- Parametric flood coverage:River-basin sensor networks and satellite precipitation data are enabling index-triggered products for commercial estates in Yorkshire and the Midlands, bypassing traditional loss-adjustment costs.
- UK-specific prudential regime transition:The post-Solvency II framework is expected to reduce reporting burdens for domestic mutual insurers, creating regulatory arbitrage opportunities against international branch competitors.
- Embedded insurance APIs:Commercial property platforms and B2B marketplaces are opening distribution channels that bypass traditional broker networks, capturing digitally native SME segments.
Industry Challenges
- Actuarial talent scarcity in cyber lines:The shortage of professionals capable of modeling ransomware frequency and severity distributions is constraining product rollout velocity for emerging digital-peril coverage.
- Legacy policy administration integration:Carriers attempting to deploy modular, usage-based commercial products face friction from decades-old core systems that cannot support real-time rating or mid-term coverage adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Commercial Insurance Market |
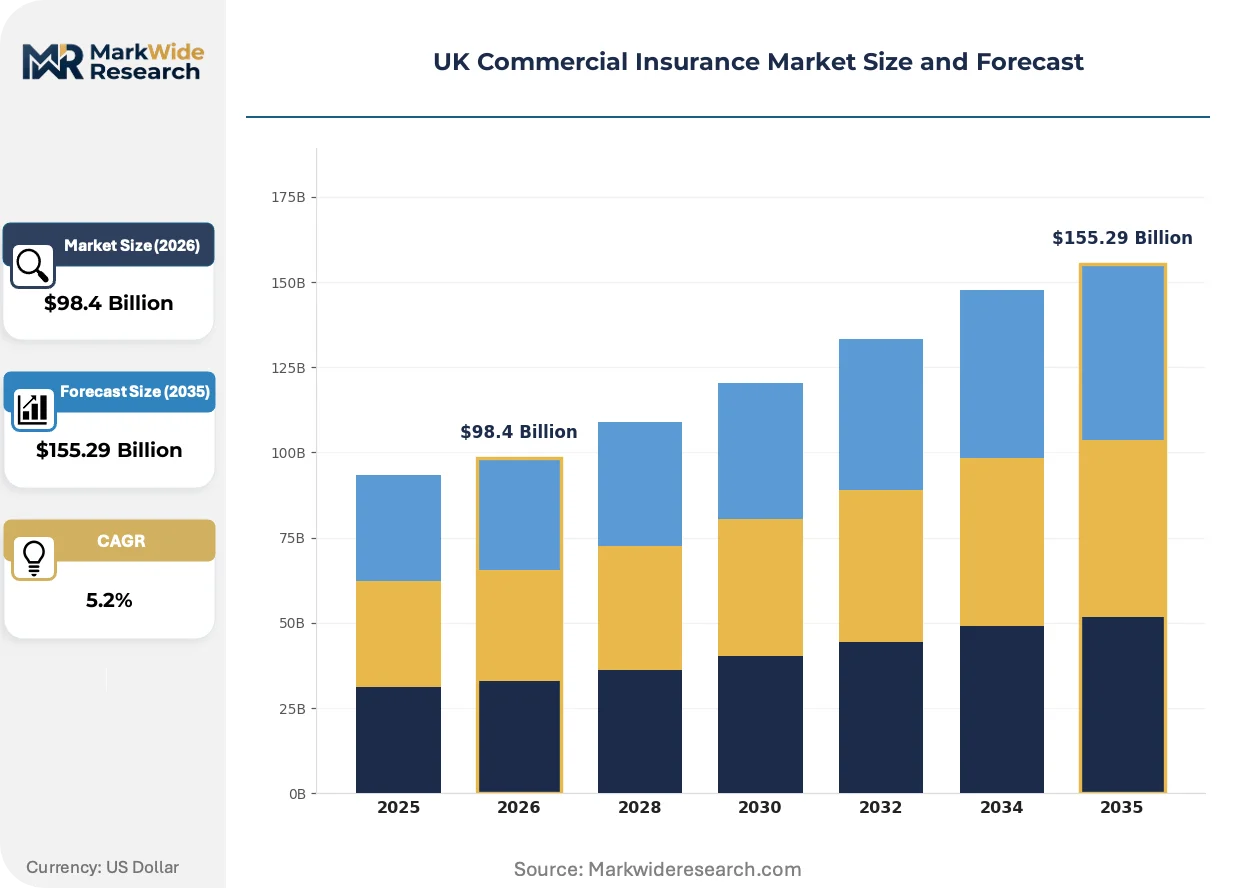
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $155.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
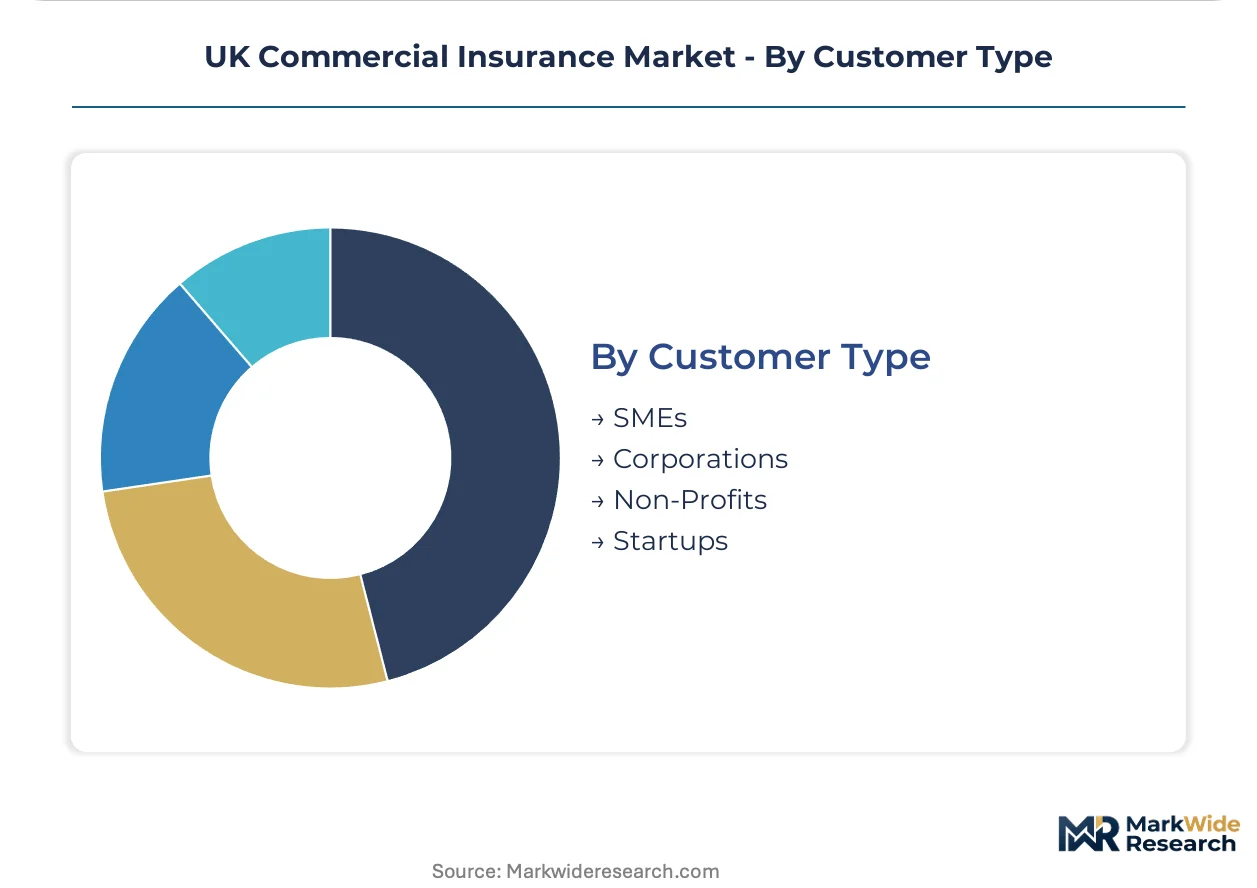
| Segmentation | Industry Vertical: Manufacturing, Retail, Construction, Transportation Policy Type: Property Insurance, Liability Insurance, Business Interruption, Cyber Insurance Coverage Level: Basic Coverage, Comprehensive Coverage, Customized Coverage, Excess Coverage Customer Type: SMEs, Corporations, Non-Profits, Startups |
| Companies Covered | Aviva plc, Allianz Insurance plc, AXA UK, RSA Insurance Group Limited, AIG, Lloyd's of London, Zurich Insurance UK, Royal & Sun Alliance, NFU Mutual, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Commercial Insurance Market Strategic Shifts & Innovations
Artificial intelligence and machine learning architectures are penetrating underwriting workflows, transforming risk selection from static rule-engines toward dynamic, data-enriched decision systems that compress quote-to-bind cycles.
Telematics-enabled commercial motor and fleet coverage is unifying vehicle operation data with driver behavior analytics. Logistics operators and delivery platforms are adopting these programs at accelerating velocity. The technology is unifying risk engineering with continuous premium adjustment, collapsing the traditional annual renewal cycle into fluid, exposure-adjusted pricing.
The UK government's transition toward a domestic prudential regime is dismantling Solvency II-derived reporting obligations. This regulatory shift is reducing compliance overhead for mutual carriers and specialist Lloyd's syndicates. Domestic insurers with streamlined data architectures are responding faster than international branches burdened by dual-reporting requirements.
Mid-market enterprises are consolidating insurance procurement through digital broker platforms that disintermediate traditional face-to-face placement. Risk managers at manufacturing and professional services firms are migrating to these channels, attracted by transparent pricing and self-service policy adjustments. This behavioral pivot is most visible in Greater London, where platform-based placement now captures a material share of SME commercial package business.
UK Commercial Insurance Market Segmentation

Segmentation in UK commercial insurance reveals how carriers balance standardized product economics against bespoke risk engineering. Each dimension—industry exposure, peril coverage, policy architecture, and buyer scale—shapes capital allocation and distribution strategy differently.
Industry Vertical:
Customization intensity varies sharply across this category, with heavy industrial exposures demanding tailored risk engineering while retail portfolios accept more standardized terms.
- Manufacturing:Policies integrate machinery breakdown, product liability, and supply-chain contingent business interruption. Demand clusters in the West Midlands and North West, where factory estates face elevated fire and equipment failure frequencies.
- Construction:Professional indemnity and latent-defect coverage dominate following the Building Safety Act. Greater London contractors are expanding risk-transfer portfolios as project complexity and cladding liability exposures intensify.
- Retail:Standardized property and public liability bundles predominate. High-street operators in the South East consolidate procurement through digital broker platforms.
- Transportation:Fleet motor and cargo policies leverage telematics for usage-adjusted pricing. Logistics operators across the Midlands adopt these programs for continuous premium calibration.
Leading the category by volume: Manufacturing. Expanding most quickly: Construction.
Policy Type:
Premium volume concentration aligns with peril frequency, while margin profiles favor emerging lines where actuarial uncertainty limits competition.
- Property Insurance:Named-peril coverage for fire, flood, and theft generates the largest premium pool. Industrial estates in Yorkshire and the Midlands drive persistent demand as climate volatility intensifies.
- Cyber Insurance:Claims-made coverage for ransomware, data breach response, and regulatory notification mandates. SMEs across Greater London are purchasing standalone policies as digital-peril awareness spreads.
- Liability Insurance:Third-party bodily injury and property damage protection. Employers' liability remains compulsory, with long-tail reserve volatility elevating capital charges under PRA requirements.
- Business Interruption:Indemnification for gross profit loss following insured perils. Pandemic-related disputes have tightened policy wording and sub-limit structures.
Property Insurance dominates premium volume. Cyber Insurance gains share fastest.
Coverage Level:
Margin structures widen as coverage depth increases, with excess and customized tiers commanding specialized underwriting expertise.
- Comprehensive Coverage:All-risk property and broad-form liability protection for mid-market enterprises. Corporations in the South East favor this tier for contractual compliance and lender requirements.
- Customized Coverage:Bespoke limits, endorsements, and captive-fronting arrangements. Large manufacturers negotiate these structures to align with enterprise risk management frameworks.
- Basic Coverage:Named-peril property and minimum statutory liability limits. Cost-constrained startups and micro-enterprises in peripheral regions select this tier.
- Excess Coverage:Catastrophe layers and umbrella liability above primary programs. Lloyd's syndicates specialize here, deploying surplus lines capacity for hard-to-place risks.
Comprehensive Coverage leads by policy count. Customized Coverage delivers superior unit economics.
Customer Type:
Acquisition cost and retention dynamics diverge sharply between high-velocity SME segments and relationship-intensive corporate accounts.
- SMEs:Small and medium enterprises purchasing bundled property-liability packages. Digital-native firms in Greater London and the South East consolidate procurement through embedded insurance APIs and broker platforms.
- Corporations:Large enterprises with customized programs, captive alternatives, and multi-national extensions. Risk managers at these firms demand integrated risk engineering and claims advocacy.
- Startups:Early-stage ventures with limited loss history and volatile exposure profiles. InsurTech distribution channels target this segment with rapid-quote, usage-adjusted products.
- Non-Profits:Charities and social enterprises seeking trustees' indemnity and event liability coverage. Premium sensitivity here favors mutual and specialist carriers.
SMEs generate the most dynamic growth pool. Corporations retain superior margin profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK generates commercial insurance premium domestically through its London market hub and regional carrier networks, with consumption concentrated in Greater London and the South East while underwriting capacity distributes across industrial centers nationwide.
Greater London and the South East
SME digitalization and bundled property-liability procurement dominate demand growth. The Prudential Regulation Authority's capital adequacy requirements reshape carrier balance-sheet strategies for firms operating here. Lloyd's of London anchors specialty and excess lines capacity, while digital broker platforms capture material shares of mid-market commercial package business.
Midlands
Manufacturing estates and logistics operators drive persistent property and fleet motor coverage needs. The Building Safety Act imposes new liability cascades on construction insurers active across Birmingham and the West Midlands. Industrial IoT deployments in manufacturing favor bundled property-cyber policies over standalone coverage.
North England
Yorkshire and the Midlands generate concentrated demand for parametric flood coverage as climate volatility intensifies. River-basin sensor networks enable index-triggered products that bypass traditional loss-adjustment costs. Factory estates here face elevated fire and equipment failure frequencies requiring integrated machinery breakdown coverage.
Scotland
Energy and marine exposures sustain demand for specialty commercial lines. The Financial Conduct Authority's conduct standards govern carrier operations alongside PRA solvency requirements. Aberdeen's energy sector clusters drive customized risk-transfer portfolios for offshore and construction projects.
Wales and Northern Ireland
Cost-constrained micro-enterprises and startups select basic named-peril property and minimum statutory liability limits. Regional mutual carriers and specialist insurers target premium-sensitive non-profits and social enterprises here. Embedded insurance APIs open distribution channels that bypass traditional broker networks for digitally native SME segments.
UK Commercial Insurance Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Multi-line platforms anchor mid-market clients with integrated solutions, while engineering-led risk services extend into construction and manufacturing verticals. Syndicate-based capital deployment sustains positions in specialty and excess lines. Dominant competitive moves include modular policy bundling to consolidate buyer preference and regulatory arbitrage through streamlined data architectures.
Within the multi-line platform tier, Aviva plc and Allianz Insurance plc exemplify carriers leveraging scale to anchor integrated property and liability solutions. Lloyd's of London occupies a position representing syndicate-based specialty capacity deployment. These three entities sit within distinct strategic archetypes: domestic conglomerate diversification, international engineering-led services, and market-based surplus lines specialization.
| Leading Market Players |
|---|
| Aviva plc |
| Allianz Insurance plc |
| AXA UK |
| RSA Insurance Group Limited |
| AIG |
| Lloyd's of London |
| Zurich Insurance UK |
| Royal & Sun Alliance |
| NFU Mutual |
| Others |
Cost & Logistics Intelligence
The ABI premium rate index cascades through carrier balance sheets into tiered pricing structures for SME and corporate buyers, with reinsurance cost pass-throughs amplifying pressure on mid-market policy bundles.
Pricing Analysis
Margin tightening in SME commercial packages reflects reinsurance cost pass-throughs and elevated capital charges under PRA requirements. Three-tier pricing structure across premium, standard, and economy levels segments buyers by claims history and coverage breadth. Price differentiation hinges on risk engineering intensity and broker channel commission structures. Cost-constrained micro-enterprises in peripheral UK regions exhibit highest price sensitivity, while London-based corporations with captive alternatives negotiate from strength.
Supply Chain Analysis
Single-source vulnerability sits with Bermuda and London reinsurance markets for catastrophe-exposed property lines. Capacity concentrates in Lloyd's syndicates, continental European retrocession panels, and Bermudian collateralized vehicles. Raw material dependencies include actuarial talent pools, proprietary claims data repositories, and regulatory capital instruments. Tariff exposure on cross-border reinsurance treaties elevates net retention burdens for primary carriers. Distribution runs through accredited broker networks, managing general agents, and emerging embedded insurance APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK commercial insurance market operates as a vertical-integration race, with carriers pursuing backward integration into proprietary risk data assets to escape commoditized broker-channel economics.
For Market Incumbents: Deploy captive reinsurance vehicles to retain profitable risk layers currently ceded to Bermudian markets. Consolidate mid-market SME books through digital broker platform acquisitions, neutralizing InsurTech distribution threats. Deepen risk engineering capabilities in construction and cyber lines where actuarial talent scarcity protects margin profiles. For New Entrants and Emerging Players: Premium-to-economy tier gaps in parametric flood coverage for Yorkshire and Midlands commercial estates present white-space entry points. Target digitally native SMEs in Greater London through embedded insurance APIs integrated with commercial property platforms. Pursue MGA partnerships with Lloyd's syndicates to access surplus lines capacity without balance-sheet buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor mutual insurers with streamlined Solvency II reporting architectures in Scotland and Northern England. Long-term viability over a five-to-ten-year window rests on regulatory arbitrage execution against international branch competitors. Monitor PRA capital recalibration announcements as inflection signals for carrier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Index-triggered flood coverage bypasses traditional loss-adjustment costs for Yorkshire estates. |
| API Distribution Integration | Embedded insurance channels capture digitally native SME segments outside broker networks. |
| Cyber Risk Modeling Investment | Proprietary ransomware frequency datasets differentiate pricing in fastest-expanding coverage line. |
| Regulatory Arbitrage Positioning | Streamlined UK prudential regime reporting reduces compliance overhead against international branches. |
| Mutual Insurer Acquisition | Regional mutuals with captive member bases offer defensive market share in premium-sensitive segments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with underwriting directors, broker network heads, risk engineering specialists, and SME procurement officers combined with PRA solvency returns, Lloyd's market data, and ABI premium statistics. Bottom-up policy count and premium volume estimates triangulated against top-down carrier balance-sheet aggregates.
Granularity-level modeling dissected the market across industry vertical, policy type, coverage depth, and customer scale dimensions. CAGRs derived from fitted growth curves applied to segment-level baseline estimates across the projection horizon. Forecast inputs incorporated regulatory capital charge trajectories, reinsurance capacity availability, and SME digitalization penetration rates.
Inputs from Lloyd's market repositories and PRA regulatory databases were available through the study window; gaps in syndicate-level claims development triangles introduce uncertainty bands around long-tail liability projections. Forecasts reflect documented assumptions regarding interest rate matching portfolio performance and cyber loss frequency trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Jewelry Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Takaful Insurance Market
Insurance
Business Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Agriculture Insurance Market