
 India Liability Insurance Market | 2026-2036
India Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Liability Insurance Market Insights
Embedded risk advisory services bundled with liability policies is expanding beyond traditional indemnity structures. Tata AIG General Insurance leverages its multinational reinsurance partnerships to sustain competitive capacity in product liability lines. HDFC ERGO General Insurance anchors its position through bancassurance distribution density across tier-2 and tier-3 cities. ICICI Lombard General Insurance differentiates via technology-led claims automation that compresses settlement cycles for commercial clients.
Liability insurance constitutes a risk-transfer mechanism where insurers assume legal obligation for third-party bodily injury, property damage, or financial loss arising from insured operations, with policy terms specifying per-occurrence limits, aggregate caps, and retroactive dates. Coverage type segments reveal public liability as the mature volume base while professional indemnity accelerates fastest, driven by litigation against consultants, architects, and IT service firms. End user segmentation shows healthcare providers generating concentrated margin pools due to elevated malpractice exposure and specialized underwriting expertise required.
IRDAI governs solvency margins and product filing protocols, while RBI oversight affects insurers with banking parentage through consolidated financial regulation. India's evolving consumer protection jurisprudence and proposed class-action frameworks amplify third-party damage awards, directly expanding limit requirements in commercial liability placements. Stakeholders must monitor judicial precedent on vicarious liability and emerging cyber liability extensions as these forces reshape coverage architecture and pricing models.
Market Dynamics
IRDAI's tightened solvency margin requirements are compressing insurer capital deployment flexibility while simultaneously forcing product redesigns that embed risk advisory services alongside traditional indemnity structures.
Growth Catalysts
- PLI scheme manufacturing incentives:India's Production Linked Incentive scheme draws industrial capacity expansion into Maharashtra and Gujarat, generating concentrated liability coverage demand from new manufacturing facilities.
- Consumer protection jurisprudence evolution:Proposed class-action frameworks and expanding vicarious liability precedent are elevating damage award ceilings, compelling enterprises to purchase higher-limit commercial liability placements.
- Cyber liability extension:Digital infrastructure penetration across IT services and financial sectors creates novel first-party and third-party cyber exposure requiring specialized underwriting expertise.
Market Restraints
- Reinsurance capacity concentration:Indian primary carriers remain dependent on Lloyd's and Singapore-based reinsurance treaties for product liability and directors-and-officers lines, creating pricing volatility when global retrocession markets tighten.
- Actuarial data scarcity:Limited historical claims experience for emerging cyber and professional indemnity segments forces conservative reserving assumptions that inflate premium loadings.
- Judicial delay infrastructure:Commercial court backlogs in Delhi and Mumbai extend liability claim resolution timelines, trapping capital and eroding investment income on technical reserves.
Strategic Opportunities
- Tier-2 and tier-3 city penetration:Bancassurance distribution density remains underdeveloped in Indore, Lucknow, and Coimbatore, creating whitespace for embedded liability products sold through banking channels.
- Parametric trigger innovation:Index-based liability coverage tied to operational downtime metrics offers settlement acceleration for manufacturing clients frustrated with traditional claims investigation cycles.
- Healthcare malpractice specialization:Nursing home chains and diagnostic laboratory networks generate concentrated margin pools requiring dedicated underwriting units with clinical risk assessment capabilities.
Industry Challenges
- Legacy core system integration:Mid-sized insurers struggle to embed AI-driven claims automation into decades-old policy administration platforms without disrupting regulatory reporting pipelines.
- Specialized underwriting talent scarcity:Professional indemnity and cyber liability lines demand actuaries with dual domain expertise in both quantitative modeling and sector-specific operational risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Liability Insurance Market |
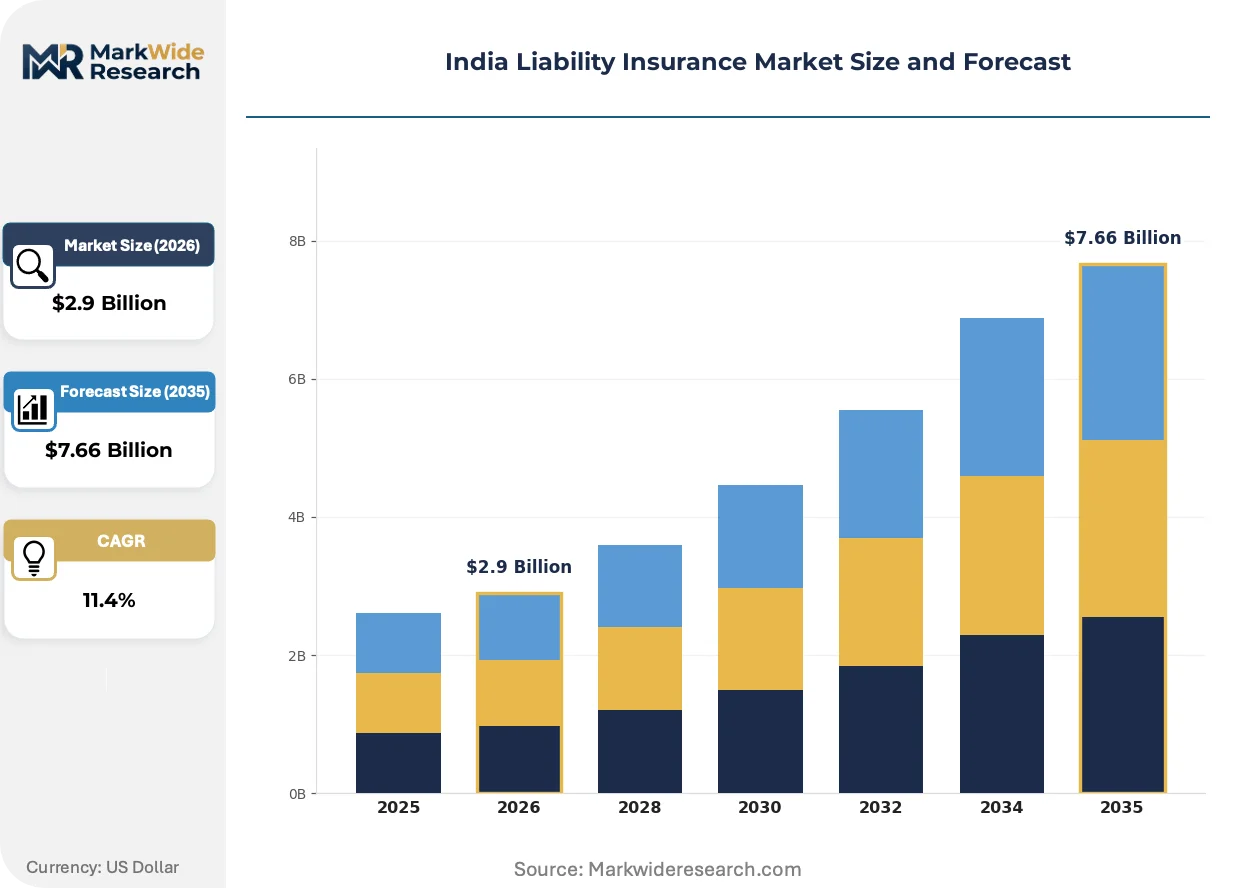
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $7.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Public Liability, Product Liability, Employer's Liability, Professional Indemnity End User: Manufacturers, Service Providers, Healthcare Providers, Educational Institutions Policy Duration: Short-Term, Long-Term, Multi-Year, Renewable Premium Type: Standard Premium, No-Claim Bonus, Customized Premium, Adjustable Premium |
| Companies Covered | Tata AIG General Insurance, Iffco Tokio General Insurance, Bajaj Allianz General Insurance, Liberty General Insurance, Kotak Zurich General Insurance, HDFC ERGO General Insurance, SBI General Insurance, Raheja QBE General Insurance, ICICI Lombard General Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Liability Insurance Market Trends and Innovations
Telematics and IoT sensor integration are transforming liability underwriting from retrospective risk pooling into real-time exposure monitoring, with implications for pricing granularity and loss prevention service bundling.
Blockchain-enabled smart contracts are expanding into commercial liability placements, particularly for parametric coverage triggers. Manufacturing clients in Gujarat's chemical corridors adopt these instruments to automate indemnity payments when predefined operational thresholds breach. This compression of settlement cycles is expanding into professional indemnity lines as law firms and consultancies seek faster resolution mechanisms.
IRDAI's sandbox framework for regulatory experimentation permits pilot programs for on-demand liability coverage. Insurers test micro-duration policies activated by gig-economy platform worker status changes. The framework's 2024 expansion to include B2B commercial lines is accelerating product development for project-specific contractor liability.
Corporate risk managers are consolidating vendor relationships, demanding bundled property-casualty programs with unified claims handling. Mumbai-headquartered enterprises increasingly specify technology-enabled loss adjustment services as procurement criteria, displacing traditional commission-based broker arrangements with fee-based advisory models. This concentration of purchasing authority is most visible among pharmaceutical and IT services exporters facing international contractual liability requirements.
India Liability Insurance Market Segmentation
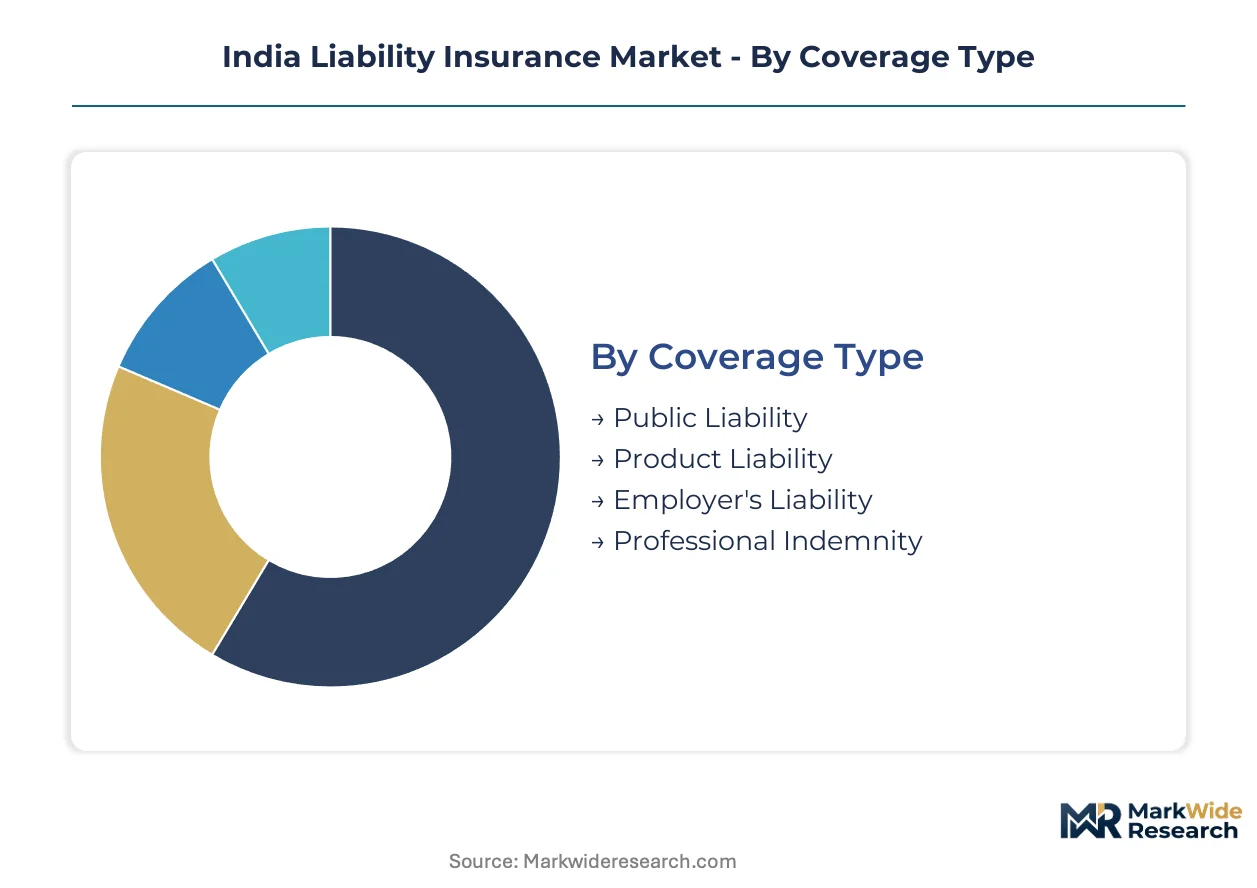
Liability coverage architectures in India diverge sharply across operational risk profiles, with manufacturing-heavy states driving volume concentration while service-sector litigation exposure commands premium rate elevation. Segment boundaries increasingly blur as bundled property-casualty programs displace standalone placements among corporate risk managers.
Coverage Type:
Public liability dominates policy count volume across Maharashtra and Gujarat industrial corridors, while professional indemnity captures disproportionate premium yield from litigation-prone service sectors.
- Public Liability:Third-party bodily injury and property damage coverage triggered by premises operations or completed work. Manufacturing facilities in Gujarat's chemical belt generate dense policy placements driven by statutory mandate under Factories Act and environmental tribunal enforcement.
- Professional Indemnity:Financial loss protection for negligent acts, errors, or omissions in professional service delivery. IT consultancies in Bengaluru and Hyderabad drive demand concentration as client contracts increasingly specify E&O coverage minimums for software implementation and data processing engagements.
- Product Liability:Coverage for bodily injury or property damage arising from defective products sold or distributed. Pharmaceutical and automotive component exporters in Pune and Chennai purchase elevated limits to satisfy EU and US importer contractual requirements.
- Employer's Liability:Statutory and common-law coverage for workplace injury claims beyond Employees' State Insurance Corporation benefits. Construction and logistics employers in National Capital Region face accelerating claim frequency from gig-worker classification disputes.
Mature deployment sits with public liability. Newer deployment is concentrated in professional indemnity.
End User:
Healthcare providers extract the steepest premium rates per rupee of limit, while manufacturers generate absolute volume through PLI-scheme capacity expansion.
- Manufacturers:Industrial enterprises with premises, product, and completed operations exposure. PLI beneficiaries in electronics and pharmaceuticals expand coverage footprints across Maharashtra and Tamil Nadu as production scales trigger statutory liability thresholds.
- Healthcare Providers:Hospitals, nursing homes, and diagnostic chains facing malpractice and vicarious liability exposure. Corporate hospital chains in Mumbai and Delhi purchase towered excess programs as consumer court award ceilings escalate.
- Service Providers:IT, financial, and professional service firms with errors-and-omissions and cyber liability needs. Fintech startups in Bengaluru and Gurgaon drive parametric cyber coverage experimentation under IRDAI sandbox protocols.
- Educational Institutions:Schools, colleges, and training centers managing student safety and employment practice liability. Private universities in Rajasthan and Uttar Pradesh expand coverage as regulatory scrutiny of campus safety intensifies.
Volume concentration rests with manufacturers. Margin expansion concentrates in healthcare providers.
Policy Duration:
Long-term placements reduce administrative burden for stable manufacturing operations, while project-specific short-term coverage aligns with construction and event liability needs.
- Long-Term:Annual or multi-annual policies with guaranteed renewal terms and stabilized pricing. Established manufacturing enterprises in Ahmedabad and Pune favor this structure to lock in capacity amid reinsurance market volatility.
- Short-Term:Duration-matched coverage for discrete projects, events, or contractual obligations. Infrastructure contractors executing NHAI road projects purchase 18-24 month terms aligned with construction completion milestones.
- Multi-Year:2-5 year policies with inflation-adjusted limits and premium escalation clauses. Multinational IT services exporters deploy these instruments to satisfy multi-year client contractual indemnity requirements.
- Renewable:Annual policies with automatic renewal provisions subject to claims experience review. Small and mid-tier enterprises in tier-2 cities prefer this flexibility amid operational uncertainty.
Stable operations favor long-term structures. Project-based deployment is expanding most quickly in short-term coverage.
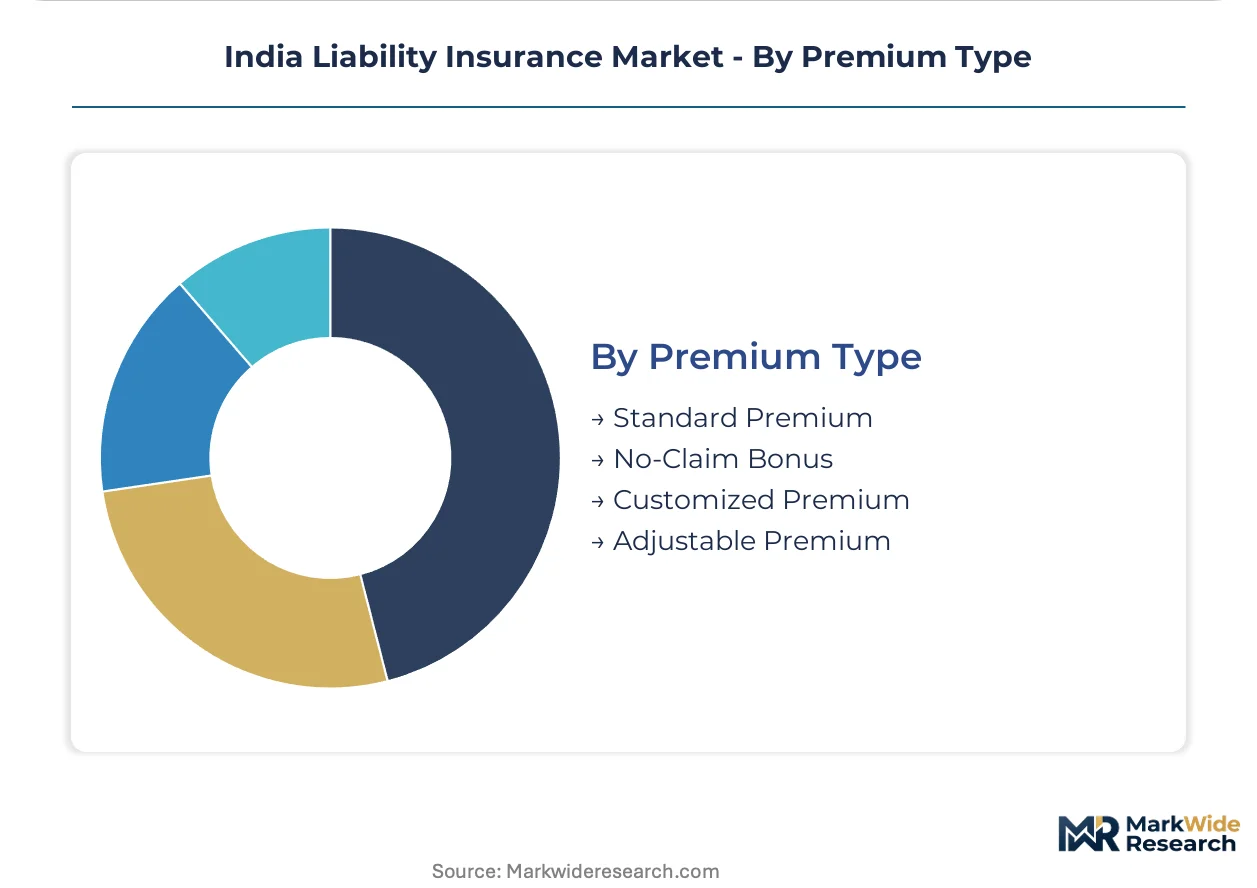
Premium Type:
Standard premium calculation dominates straightforward risk placements, while experience-rated structures penetrate sophisticated corporate accounts with measurable loss history.
- Standard Premium:Fixed rate applied to exposure base without modification for individual experience. Small enterprises and statutory-mandated coverage in tier-3 cities rely on this simplicity given limited actuarial data availability.
- No-Claim Bonus:Discount structures rewarding loss-free experience with progressive rate reductions. Fleet operators and manufacturing enterprises with mature safety management systems in Chennai and Coimbatore capture material savings through this mechanism.
- Customized Premium:Bespoke rating incorporating risk engineering assessments, loss control investments, and coverage modifications. Large pharmaceutical and chemical manufacturers negotiate these terms through captive brokerage arrangements.
- Adjustable Premium:Provisional rates subject to retrospective adjustment based on audited exposure or claims experience. Construction and infrastructure developers with variable project scales favor this structure to avoid overpayment during dormant periods.
Standard premium structures anchor the mass market. Adjustable and customized pricing is gaining share fastest among corporate accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial production concentrates in western and southern states, while liability consumption spreads nationwide as regulatory mandates tighten. Maharashtra and Gujarat generate the densest coverage placements, though Karnataka and Tamil Nadu accelerate fastest on services-sector litigation exposure.
Maharashtra
Corporate headquarters clusters in Mumbai and Pune drive commercial liability demand from pharmaceutical and IT services exporters. IRDAI's solvency margin tightening compels insurers to redesign product structures for these large accounts. The Mumbai-Pune industrial corridor generates concentrated professional indemnity placements as client contracts mandate E&O coverage minimums.
Gujarat
Chemical and petrochemical manufacturing in the Golden Corridor creates statutory public liability obligations under Factories Act enforcement. The state's PLI scheme beneficiaries expand coverage footprints as production scales trigger liability thresholds. Ahmedabad and Vadodara house dense underwriting capacity serving these process industries.
Karnataka
Bengaluru's IT consultancy ecosystem accelerates professional indemnity demand as software implementation contracts specify coverage requirements. Fintech startups drive parametric cyber coverage experimentation under IRDAI sandbox protocols. The city's diagnostic laboratory networks generate healthcare malpractice specialization opportunities.
Tamil Nadu
Automotive component and electronics manufacturing in Chennai and Coimbatore purchases product liability coverage for EU and US export compliance. Fleet operators capture no-claim bonus savings through mature safety management systems. The state's industrial density supports bancassurance distribution expansion into tier-2 cities.
Delhi-NCR
Construction and logistics employers face accelerating employer's liability claim frequency from gig-worker classification disputes. Commercial court backlogs in Delhi extend claim resolution timelines, trapping capital on technical reserves. The region's infrastructure contractors purchase short-term coverage aligned with NHAI project milestones.
India Liability Insurance Market Competitive Landscape
Top-tier vendors anchor the national tier through bancassurance density and multinational reinsurance partnerships, while mid-sized carriers compete on technology-led claims automation and sector specialization. The market structures around three archetypes: banking-parentage insurers leveraging distribution reach, standalone general insurers investing in underwriting expertise, and foreign joint ventures accessing global capacity. Competitive moves concentrate on parametric product innovation and tier-2 city penetration through embedded banking channels.
Within the banking-parentage tier, HDFC ERGO General Insurance and SBI General Insurance exemplify distribution-led positioning, while ICICI Lombard General Insurance occupies a technology-differentiated slot. Tata AIG General Insurance anchors the multinational partnership archetype through reinsurance access. These three represent distinct competitive vectors: bancassurance density, claims automation, and global capacity backing.
| Leading Market Players |
|---|
| Tata AIG General Insurance |
| Iffco Tokio General Insurance |
| Bajaj Allianz General Insurance |
| Liberty General Insurance |
| Kotak Zurich General Insurance |
| HDFC ERGO General Insurance |
| SBI General Insurance |
| Raheja QBE General Insurance |
| ICICI Lombard General Insurance |
| Others |
Pricing and Supply Chain Analysis
Corporate risk managers in Mumbai and Pune pharmaceutical and IT services exporters anchor pricing power through consolidated property-casualty procurement, compressing commission-based broker margins while elevating fee-based advisory models as the dominant commercial structure.
Pricing Analysis
Margin tightening in standard premium tiers reflects reinsurance treaty volatility at Lloyd's and Singapore markets, forcing primary carriers to cede capacity on product liability and directors-and-officers lines. Pricing stratifies across customized premium, no-claim bonus, and standard rate tiers, with differentiation hinging on risk engineering assessments and loss control investments. Cost-down pressure on small enterprises accelerates because IRDAI solvency margin tightening constrains insurer capital deployment flexibility. Manufacturing PLI beneficiaries in Gujarat demonstrate lowest price sensitivity due to statutory mandate requirements, while tier-3 city SMEs exhibit highest sensitivity amid limited actuarial data availability.
Supply Chain Analysis
Dual-sourcing requirements from corporate hospital chains and multinational IT exporters mandate reinsurance capacity qualification across both Lloyd's and Singapore treaty markets, preventing single-source dependency in capacity-constrained lines. Geographic supply concentration draws from United Kingdom, Singapore, and Bermuda for professional indemnity and cyber liability capacity. Raw material dependencies rest on actuarial talent pools, claims data infrastructure, and risk engineering expertise. Single-source vulnerability in reinsurance retrocession markets threatens pricing stability during global capacity contractions. Distribution runs through bancassurance channels, direct corporate brokerage, and embedded platform partnerships for gig-economy coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurers face a vertical-integration race into risk advisory services and claims technology infrastructure, with backward integration into real-time exposure monitoring via IoT sensor networks emerging as the critical downstream lever.
For Market Incumbents: Extend parametric trigger product development beyond Gujarat chemical corridors into professional indemnity lines, while deepening captive reinsurance structures to reduce Lloyd's market dependency. Consolidate vendor relationships through unified property-casualty claims handling platforms that displace fragmented broker arrangements. Threat from fintech startups experimenting under IRDAI sandbox protocols demands accelerated technology investment. For New Entrants and Emerging Players: Bancassurance partnerships in Indore, Lucknow, and Coimbatore offer whitespace penetration for embedded liability products sold through underdeveloped banking channels. Target tier-2 city manufacturing enterprises with adjustable premium structures aligned to PLI scheme production scaling. Healthcare malpractice specialization for nursing home chains and diagnostic networks represents the most penetrable segment given underwriting talent scarcity. For Investors and Strategic Acquirers: The window for entry favors technology-differentiated mid-cap insurers with AI-driven claims automation capabilities and sector-specific underwriting units. Long-term viability hinges on regulatory sandbox positioning and parametric product pipelines. Watch IRDAI class-action framework implementation as the inflection signal for limit requirement expansion and premium rate elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Expansion | Blockchain-enabled smart contracts automate indemnity payments for Gujarat manufacturing clients when operational thresholds breach. |
| Bancassurance Channel Deepening | HDFC ERGO and SBI General leverage banking parentage density to capture tier-2 city manufacturing liability placements. |
| Healthcare Malpractice Specialization | Dedicated underwriting units with clinical risk assessment capabilities capture concentrated margin pools from corporate hospital chains. |
| Cyber Liability Product Development | Fintech startups in Bengaluru and Gurgaon drive experimentation under IRDAI sandbox protocols for first-party and third-party coverage. |
| Reinsurance Capacity Diversification | Tata AIG sustains competitive product liability capacity through multinational reinsurance partnerships beyond Lloyd's concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with risk managers, underwriting directors, reinsurance brokers, and IRDAI officials alongside IRDAI annual reports, RBI consolidated financial disclosures, and Lloyd's market capacity data. Bottom-up policy count analysis and top-down premium aggregation triangulated market sizing across coverage type, end user, and regional segments.
Reconciliation of premium volume streams, policy duration distributions, and limit requirement trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include coverage architecture, end-use vertical, policy duration structure, and premium calculation methodology. CAGRs derived from regression analysis against PLI scheme manufacturing output, litigation frequency trends, and reinsurance pricing cycles.
Caveats apply where judicial precedent on vicarious liability, IRDAI solvency margin recalibration, or global reinsurance market contraction could materially shift the outlook. Deviation in class-action framework implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Horse Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Embedded Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Event Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Crime Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Jewelry Insurance Market