
 Trade Credit Insurance Market | 2026-2036
Trade Credit Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Trade Credit Insurance Market Intelligence
Whole turnover policy tiers with enhanced risk analytics is redrawing competitive boundaries in trade credit insurance. Allianz Trade leverages proprietary buyer databases across European markets to sustain underwriting precision. Atradius anchors its position through deep specialization in SME portfolios across Southern Europe. Zurich Insurance Group competes by extending integrated surety and credit coverage platforms for multinational clients.
Trade credit insurance is a financial risk transfer instrument where insurers indemnify policyholders against losses from buyer default, insolvency, or protracted payment delay, typically covering commercial receivables with policy limits expressed as percentages of invoice value or aggregate turnover. Its primary commercial purpose is to protect working capital and enable supplier financing by converting uncertain receivables into bankable collateral. Whole turnover coverage dominates premium volumes due to its comprehensive portfolio approach, while single buyer policies capture concentrated demand from capital goods exporters managing large-contract exposures. SME client segments represent the fastest-growing enrollment pool as digital onboarding platforms reduce policy issuance friction and minimum premium thresholds.
EU Solvency II capital requirements shape insurer reserve adequacy and pricing models across European markets, while the UK's Prudential Regulation Authority mandates stress testing for credit risk concentrations in insurer portfolios. The EU Green Deal taxonomy is beginning to influence coverage eligibility for sustainable trade flows. Stakeholders must monitor how central bank digital currency pilots and real-time payment infrastructures alter default detection timelines and policy trigger structures.
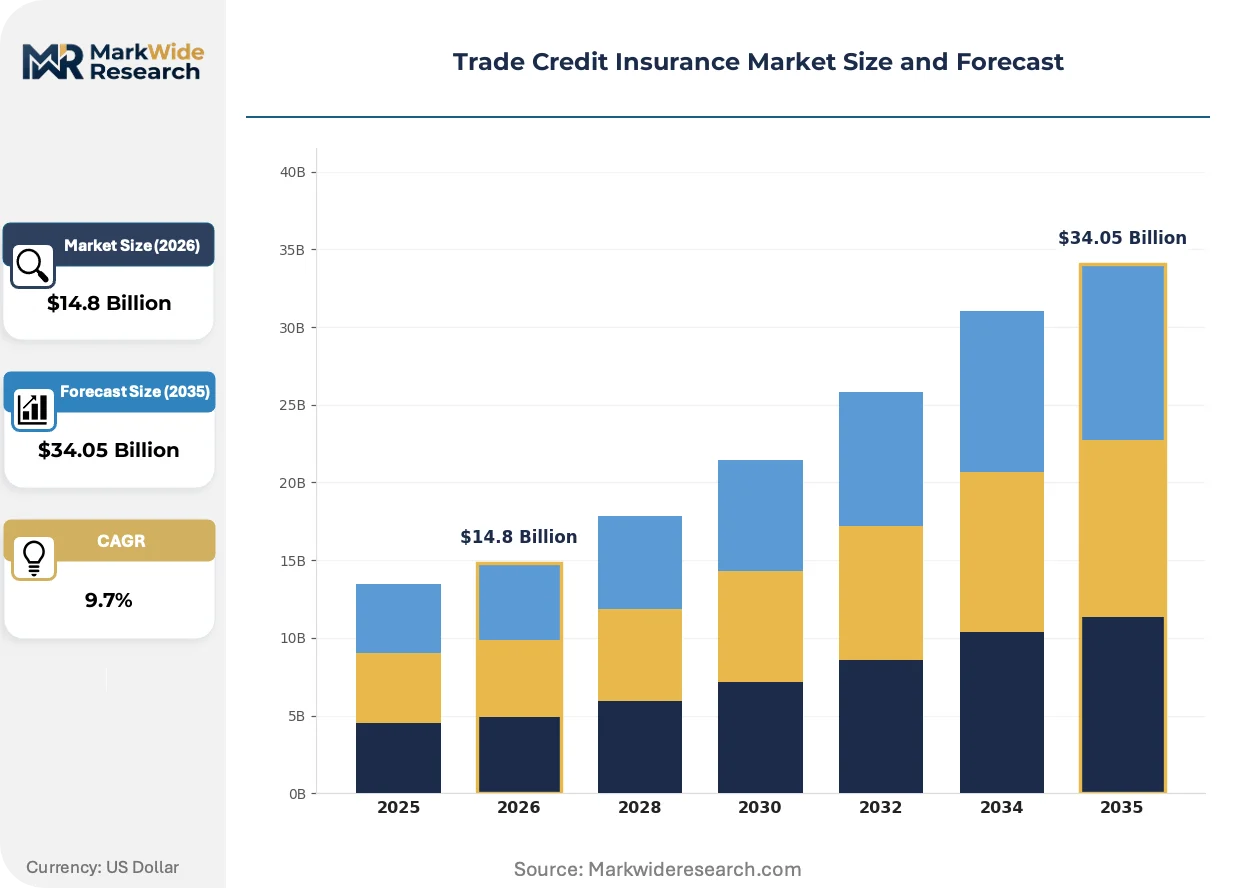
Market Dynamics
Basel III capital adequacy rules are compressing bank lending to trade-exposed SMEs, redirecting working capital protection demand toward private credit risk transfer instruments and insurer-backed supply chain finance structures.
Growth Catalysts
- EU Solvency II reserve frameworks:Harmonized capital requirements across European markets enable cross-border policy portability, reducing frictional costs for multinational credit portfolios.
- Supply chain finance digitization:API-connected trade platforms embed credit coverage into invoice financing workflows, collapsing onboarding timelines for SME policyholders.
- Germany's Mittelstand export concentration:Dense networks of capital goods exporters generate concentrated demand for whole-turnover policies with protracted default triggers.
Market Restraints
- Reinsurance capacity cyclicality:Catastrophe bond spreads and retrocession pricing volatility transmit directly to trade credit policy attachment points and limit structures.
- Buyer database fragmentation:Insurers lack unified insolvency registries across Southern European jurisdictions, degrading loss prediction accuracy for cross-border receivables.
- Proprietary scoring opacity:Opaque algorithmic risk ratings complicate policyholder dispute resolution and regulatory examination in multiple member states.
Strategic Opportunities
- Central bank digital currency pilots:Real-time settlement infrastructures in France and Italy collapse payment delay detection windows, enabling parametric policy triggers.
- Sustainable trade taxonomy alignment:EU Green Deal coverage eligibility criteria create premium differentiation for ESG-certified supply chain finance.
- Surety-credit convergence:Integrated contract bond and receivables coverage platforms capture construction and engineering procurement consolidation.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals combining trade finance expertise with machine learning deployment stalls predictive model refinement.
- Legacy system integration friction:Core policy administration platforms resist real-time data ingestion from emerging trade finance APIs, delaying digital product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trade Credit Insurance Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Buyer, Whole Turnover, Excess of Loss, Bonding Client Type: Corporates, SMEs, Multinational Companies, Government Agencies Coverage Type: Domestic, Export, Specific Transactions, Multi-Currency Industry Vertical: Manufacturing, Retail, Construction, Services |
| Companies Covered | AIG Trade Credit, AXA, Allianz Trade, Zurich Insurance Group, Liberty Mutual Insurance Company, Atradius, Chubb, QBE Insurance Group, Coface, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trade Credit Insurance Market Strategic Shifts & Innovations
Algorithmic buyer risk scoring is compressing underwriting cycles while regulatory data-sharing mandates and procurement centralization reshape how coverage is distributed and priced across trade finance ecosystems.
Artificial intelligence-driven behavioral scoring models analyze payment pattern anomalies across unstructured trade documents, enabling dynamic limit adjustments without manual intervention. Mid-market exporters in the Benelux region are adopting these tools fastest, with policy issuance friction collapsing to under 48 hours. Traditional annual policy reviews are displacing static coverage structures with continuous monitoring architectures that trigger automatic limit modifications.
The EU AI Act's risk classification framework for credit scoring algorithms mandates human-in-the-loop decision protocols for high-risk automated underwriting systems. Insurers must now maintain explainability documentation and bias audit trails for machine learning models used in limit-setting. German and Dutch carriers are restructuring data science teams to embed compliance checkpoints directly into model deployment pipelines, adding 3-6 month development cycles.
Buyers are consolidating procurement through integrated supply chain finance platforms that bundle credit coverage with invoice discounting and dynamic discounting. This channel compression is eroding standalone policy distribution through traditional insurance brokers. The shift is most pronounced in automotive and electronics manufacturing supply chains, where OEM treasury departments mandate platform-embedded coverage as a supplier qualification requirement.
Trade Credit Insurance Market Segmentation
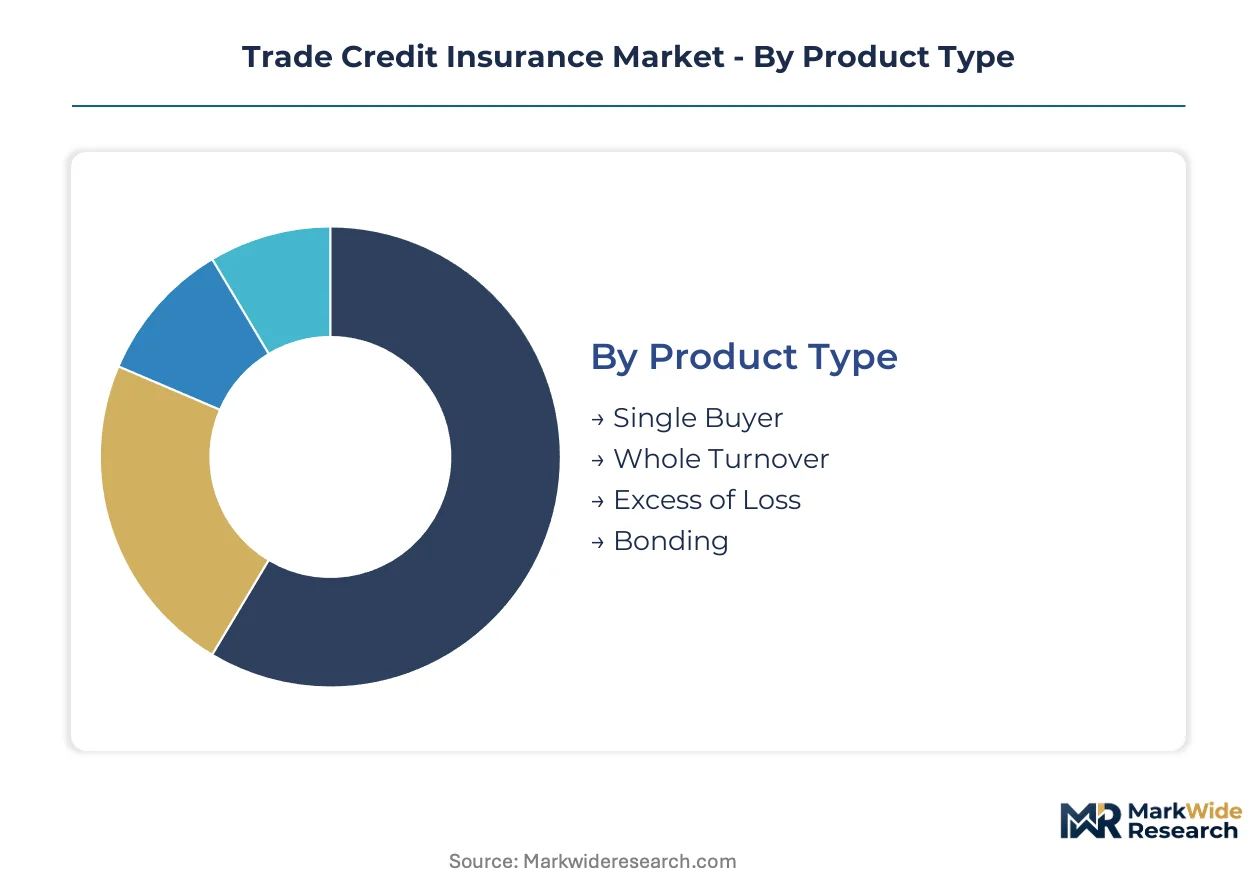
Trade credit insurance segmentation reveals how policy structures align with distinct risk transfer needs across buyer concentrations, client scale, and geographic exposure. Insurers calibrate pricing models and limit-setting protocols differently for each segment, creating specialized underwriting competencies that resist commoditization.
Product Type:
Single buyer policies face acute substitution pressure from self-insurance and captive structures as large exporters internalize credit risk assessment capabilities.
- Single Buyer:Covers individual high-value contracts or named counterparties with tailored limits and protracted default triggers. German capital goods exporters concentrate demand here as project finance structures require transaction-specific indemnity terms aligned with contract milestones.
- Whole Turnover:Comprehensive portfolio coverage protecting all domestic and export receivables under unified policy terms. Mittelstand manufacturers anchor premium volumes through this structure as Basel III compression forces working capital protection into insurer-backed facilities.
- Excess of Loss:Catastrophic layer coverage attaching above aggregate self-retention thresholds for sophisticated risk managers. Large corporates deploy this to optimize capital efficiency under Solvency II-aligned treasury frameworks.
- Bonding:Contract surety instruments guaranteeing performance obligations alongside credit risk transfer. Construction procurement consolidation in Benelux markets drives integrated surety-credit platform adoption.
Whole turnover anchors the volume base while excess of loss gains share at the steepest rate as corporate risk retention strategies mature.
Client Type:
Cost tier differentiation separates bespoke servicing models for multinational treasury departments from standardized digital onboarding for smaller accounts.
- Corporates:Mid-to-large enterprises with dedicated credit management functions seeking policy integration with ERP systems. French and Italian manufacturers dominate this tier as supply chain finance digitization accelerates.
- SMEs:Small and medium enterprises with limited internal credit expertise driving fastest enrollment expansion through API-connected platforms. Southern European jurisdictions show concentrated uptake as bank lending retrenchment redirects demand.
- Multinational Companies:Complex cross-border receivables portfolios requiring multi-jurisdictional policy coordination and centralized limit management. These clients command premium pricing power through bundled global programs.
- Government Agencies:Sovereign and quasi-sovereign procurement entities with specialized indemnity requirements and extended payment terms. Export credit agency collaboration shapes coverage structures in this tier.
SMEs expand enrollment most rapidly while multinationals defend the margin base through program complexity.
Coverage Type:
Application focus distinguishes domestic receivables protection from export-oriented structures with currency and political risk overlays.
- Domestic:Coverage limited to in-country buyer defaults with streamlined claims processing and localized insolvency registry integration. German and Dutch markets show mature penetration here.
- Export:Cross-border receivables protection incorporating country risk assessment and foreign buyer credit evaluation. EU Green Deal alignment increasingly filters eligibility for sustainable trade flows.
- Specific Transactions:One-off coverage for isolated high-value shipments or project milestones without annual policy commitment. Spot demand fluctuates with commodity price volatility.
- Multi-Currency:Integrated foreign exchange and credit risk protection for invoicing in non-functional currencies. Eurozone exporters hedging dollar and sterling exposures concentrate demand.
Export coverage commands premium positioning while domestic policies scale through volume efficiency.
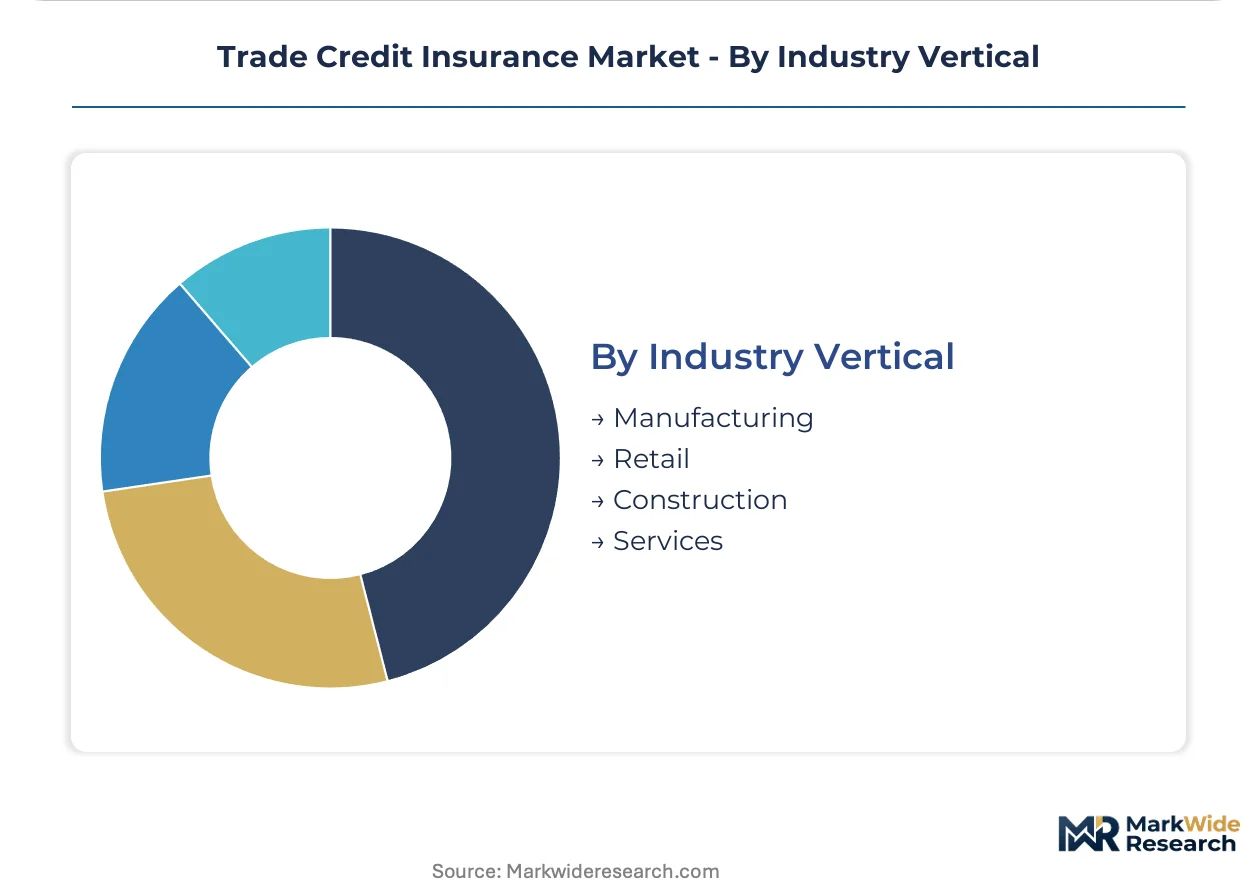
Industry Vertical:
Supply concentration in automotive and electronics OEMs dictates platform-embedded coverage requirements that reshape distribution economics.
- Manufacturing:Capital goods and industrial component producers with extended payment terms and concentrated buyer dependencies. German Mittelstand density makes this the largest premium contributor.
- Retail:Consumer goods distributors and wholesalers facing seasonal demand fluctuations and thin margin pressure. Benelux trading houses show concentrated uptake here.
- Construction:Project-based contractors requiring performance bond integration with receivables protection. Surety-credit convergence products capture this vertical.
- Services:Intangible receivables from consulting, logistics, and technology providers with limited collateral value. Underwriting complexity restricts carrier participation.
Manufacturing anchors premium volumes while services climbs fastest as digital trade platforms reduce intangible risk assessment friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting working capital protection demand toward insurer-backed instruments as bank lending retrenchment accelerates across major trading economies. The analysis tracks how regulatory frameworks and industrial clustering reshape credit risk transfer uptake in five concentrated markets.
Germany
Mittelstand manufacturers anchor premium volumes through whole-turnover policies as Basel III compression forces export-heavy SMEs away from traditional bank facilities. The Federal Financial Supervisory Authority (BaFin) mandates stress testing for credit risk concentrations in insurer portfolios. Bavaria's machinery clusters around Munich and Nuremberg drive concentrated demand for protracted default triggers aligned with project finance milestones.
France
Central bank digital currency pilots in Paris and Lyon are collapsing payment delay detection windows, enabling parametric policy structures for real-time settlement infrastructures. The EU AI Act's risk classification framework mandates human-in-the-loop protocols for automated underwriting systems. Île-de-France's automotive OEM treasury departments are mandating platform-embedded coverage as supplier qualification requirements.
United Kingdom
The Prudential Regulation Authority's credit risk concentration mandates are reshaping insurer reserve adequacy models for cross-border receivables portfolios. Post-Brexit regulatory divergence from Solvency II is creating friction for multinational policy coordination. London's specialty insurance market is developing excess-of-loss structures for sophisticated corporate risk retention strategies.
Italy
Southern European SME enrollment expansion concentrates here as digital onboarding platforms reduce policy issuance friction and minimum premium thresholds. The EU Green Deal taxonomy is beginning to filter coverage eligibility for sustainable trade flows through Milan and Turin export corridors. Lombardy's textile and machinery exporters are adopting API-connected trade platforms that embed credit coverage into invoice financing workflows.
Netherlands
Benelux trading houses are driving retail sector uptake through seasonal demand fluctuation coverage with thin margin protection. Algorithmic buyer risk scoring adoption is compressing underwriting cycles for mid-market exporters in Amsterdam and Rotterdam corridors. The Dutch Authority for the Financial Markets (AFM) is examining opaque algorithmic risk ratings that complicate policyholder dispute resolution.
Trade Credit Insurance Market Key Industry Players
Listed leaders compete with private specialists across capital adequacy and buyer database depth. The market exhibits tiered consolidation with three large diversified carriers commanding premium volumes while mid-size specialists capture SME segments through digital velocity. Strategic archetypes separate database-driven underwriters, integrated surety-credit platforms, and API-native digital entrants. Dominant competitive moves include proprietary data asset accumulation and supply chain finance platform partnerships.
Within the database-specialist tier, Allianz Trade and Atradius exemplify divergent geographic anchoring strategies. Allianz Trade occupies a position calibrated to European market density through proprietary buyer databases, while Atradius represents deep SME portfolio specialization across Southern European jurisdictions. Zurich Insurance Group sits within the integrated platform archetype, converging surety and credit coverage for multinational procurement consolidation. These three carriers illustrate how underwriting precision, regional focus, and product breadth define competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| AIG Trade Credit |
| AXA |
| Allianz Trade |
| Zurich Insurance Group |
| Liberty Mutual Insurance Company |
| Atradius |
| Chubb |
| QBE Insurance Group |
| Coface |
| Others |
Cost & Logistics Intelligence
EU Solvency II capital reserve requirements gate both insurer market entry and premium tier differentiation, compressing margins for carriers lacking proprietary buyer databases while rewarding those with advanced risk analytics capabilities. This regulatory filter simultaneously shapes supply chain partner selection and pricing power distribution across policy distribution channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy service levels, with premium tiers commanding placement through integrated surety-credit platforms and real-time limit adjustments. Price differentiation hinges on proprietary database depth and API integration sophistication, with digital-native carriers undercutting traditional annual policy structures. Pricing pressure stems from reinsurance capacity cyclicality transmitting volatility to policy attachment points. SMEs exhibit highest price sensitivity, while multinational treasury departments prioritize coverage integration over premium minimization.
Supply Chain Analysis
Just-in-time risk assessment architectures dominate carrier operations, with real-time data ingestion from trade finance APIs displacing quarterly policy reviews. Proprietary buyer databases concentrate in Germany, the Netherlands, and the United Kingdom, where dense Mittelstand networks and advanced insolvency registries feed underwriting models. Raw material dependencies center on commercial receivables data streams, payment pattern repositories, and cross-border transaction records. Single-source vulnerability persists where carriers rely exclusively on national credit bureaus. Distribution runs through integrated supply chain finance platforms that embed coverage into invoice discounting workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
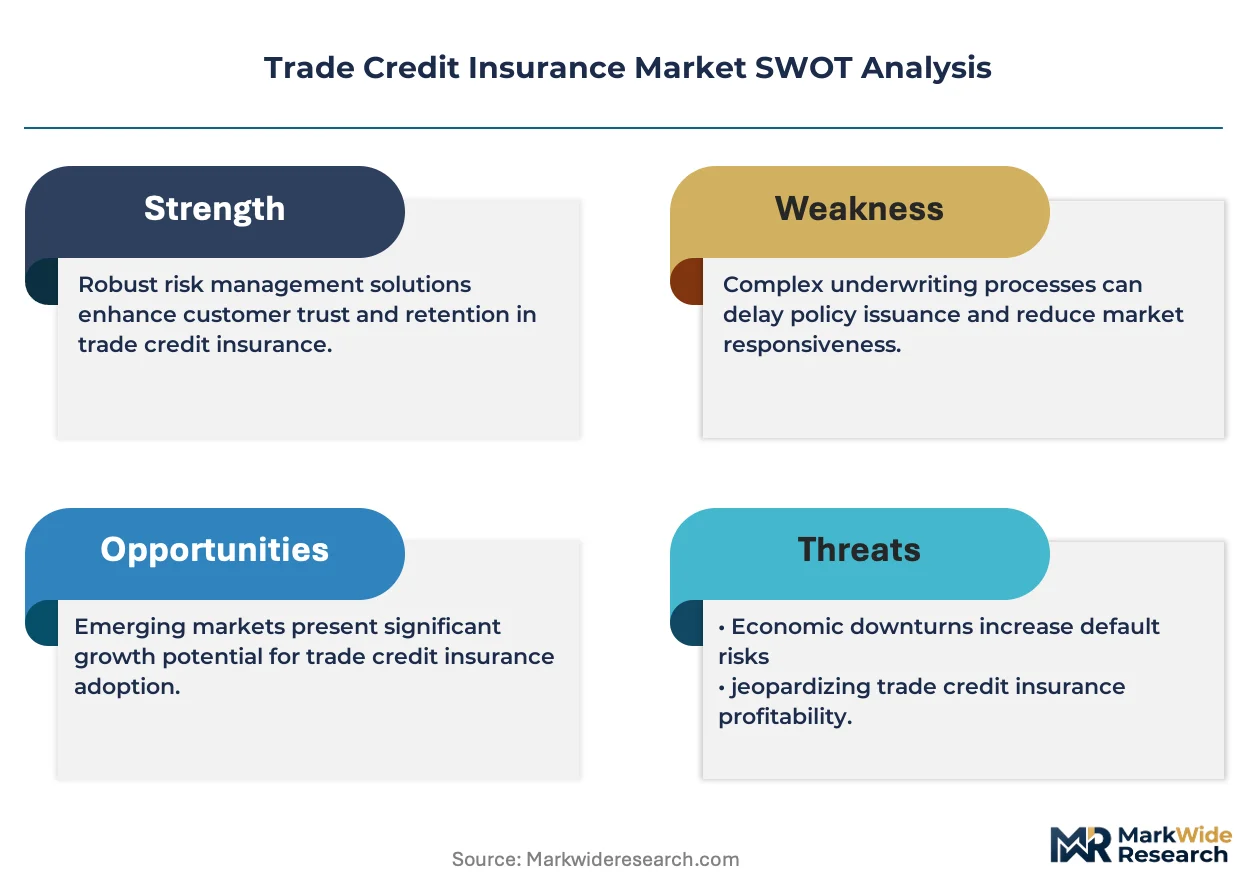
Trade credit insurance functions as a service-attach layer where continuous risk monitoring and claims management subscriptions expand faster than standalone policy premiums. Recurring revenue from API-connected limit management and automated buyer scoring now outpaces traditional annual renewal growth.
For Market Incumbents: Shield core SME portfolios against digital-native entrants by accelerating proprietary database investments and securing exclusive supply chain finance platform partnerships. Capacity addition in Southern European jurisdictions addresses buyer database fragmentation degrading cross-border loss prediction. Certification investment in EU AI Act-compliant explainability documentation defends against regulatory examination friction.
For New Entrants and Emerging Players: Solvency II compliance fast-tracks through specialized excess-of-loss structures targeting corporate risk retention strategies, bypassing whole-turnover volume competition with incumbent carriers. White-space concentrates in services sector intangible receivables coverage, where underwriting complexity restricts established participation. API-native onboarding for mid-market exporters in Benelux corridors offers the most penetrable entry vector.
For Investors and Strategic Acquirers: The EU AI Act's risk classification framework reshapes the acquisition landscape by elevating carriers with embedded compliance infrastructure above algorithmically opaque competitors. Long-term viability centers on database depth and platform integration rather than premium scale alone. Target acquisition archetypes include Southern European specialists with dense SME portfolios and proven digital onboarding velocity. The signal to watch is central bank digital currency pilot expansion collapsing payment delay detection windows and enabling parametric policy structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Database Expansion | Deepening buyer risk profiles in Germany's Mittelstand clusters sharpens underwriting precision against competitors. |
| API Platform Integration | Embedding coverage into invoice financing workflows captures SME enrollment through reduced issuance friction. |
| Solvency II Compliance Investment | Explainability documentation and bias audit trails satisfy BaFin and AFM examination protocols. |
| Surety-Credit Convergence | Integrated contract bond and receivables platforms capture Benelux construction procurement consolidation. |
| Parametric Policy Development | Real-time settlement triggers in France and Italy enable coverage aligned with CBDC infrastructure pilots. |
Research Approach
The analysis maps whole-turnover, single buyer, excess-of-loss, and bonding product segments, each validated through underwriters, risk analysts, supply chain finance platform operators, and SME treasury managers. Primary interviews with credit insurance executives and broker network heads combined with secondary validation from BaFin regulatory filings, EU Solvency II disclosure templates, and trade finance API documentation. Bottom-up policy issuance data and top-down premium volume estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models client type, coverage type, and industry vertical dimensions alongside digital integration sophistication tiers. CAGRs derived from policy enrollment trajectories and premium rate movements incorporate reinsurance capacity pricing, Basel III bank lending compression, and SME platform adoption curves as forecast inputs.
Underlying assumptions cover stable regulatory capital requirements and continued bank lending retrenchment, with deviation risk concentrated in reinsurance market volatility and central bank digital currency deployment timelines. Revision becomes warranted when CBDC pilot expansion crosses thresholds enabling widespread parametric policy restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Takaful Market
Insurance
Germany Travel Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Europe EV Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Embedded Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Aviation Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Global Flood Insurance Market
Insurance
Insurance Claims Services Market
Insurance
New Zealand Property and Casualty Insurance Market