
 Parametric Insurance Market | 2026-2036
Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Parametric Insurance Market Analysis
Traditional indemnity-based settlement is shifting toward automated parametric triggers that eliminate claims disputes and accelerate payouts. Swiss Re leverages its catastrophe modeling infrastructure to design bespoke index structures for corporate buyers. Munich Re anchors its agricultural portfolio through multi-peril crop coverage tied to satellite-derived vegetation indices. Descartes Underwriting specializes in climate-risk parametric solutions for underserved regions.
Parametric insurance is a risk-transfer mechanism where policy payouts are triggered automatically by predefined objective indices—such as wind speed thresholds, rainfall millimeters, or seismic intensity readings—rather than assessed physical damage. IoT sensors and big data analytics enable real-time data verification that reduces moral hazard and operational overhead for underwriters. Weather index insurance dominates product volume due to its applicability across farming and energy sectors, while blockchain-based smart contracts represent the fastest-growing technology segment as carriers automate execution and reduce administrative friction. Brokers retain the largest distribution share, though insurtech firms are capturing digital-native buyers through API-embedded policy issuance.
EU Solvency II capital requirements shape how European carriers reserve against parametric catastrophe exposures, while IRDAI guidelines in India mandate index-based crop insurance penetration targets that expand addressable rural markets. The country's national insurance regulator and state-level agricultural departments coordinate premium subsidies that lower farmer entry barriers. Stakeholders must monitor how evolving climate attribution science affects index calibration precision and regulatory acceptance of parametric triggers as substitutes for conventional loss verification.
Market Dynamics
Automated trigger mechanisms are compressing settlement cycles from months to days, eliminating loss-adjustment overhead and rewiring carrier-capital efficiency across agricultural and catastrophe lines.
Growth Catalysts
- IRDAI index-based crop mandates:India's insurance regulator enforces penetration targets that expand addressable rural markets through subsidized premium structures.
- IoT sensor networks:Real-time data verification from distributed ground stations reduces moral hazard and operational friction for underwriters pricing weather-index contracts.
- Agricultural cooperatives:Emerging-economy farming collectives in sub-Saharan Africa and Southeast Asia are aggregating demand for drought and flood protection at village scale.
Market Restraints
- Basis risk in index calibration:Mismatches between parametric triggers and actual farm-level losses undermine farmer trust and policy renewal rates.
- Capital reserve requirements:EU Solvency II frameworks impose stringent catastrophe exposure reserves that constrain European carriers' parametric deployment capacity.
- Satellite data dependency:Coverage gaps in remote sensing infrastructure over equatorial regions limit product viability for certain geographies.
Strategic Opportunities
- Blockchain smart-contract automation:Distributed ledger execution eliminates administrative friction and accelerates payout settlement finality.
- Micro-grid energy protection:Solar and wind installations in island nations represent underpenetrated demand for weather-indexed revenue stabilization.
- US Inflation Reduction Act climate provisions:Federal incentives for resilient infrastructure expand corporate buyer budgets for parametric risk transfer.
Industry Challenges
- Climate attribution science gaps:Evolving methodologies for linking specific weather events to long-term patterns complicate index precision and regulatory acceptance.
- Legacy system integration:Established carriers face technical debt when embedding API-driven parametric platforms into core policy administration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parametric Insurance Market |
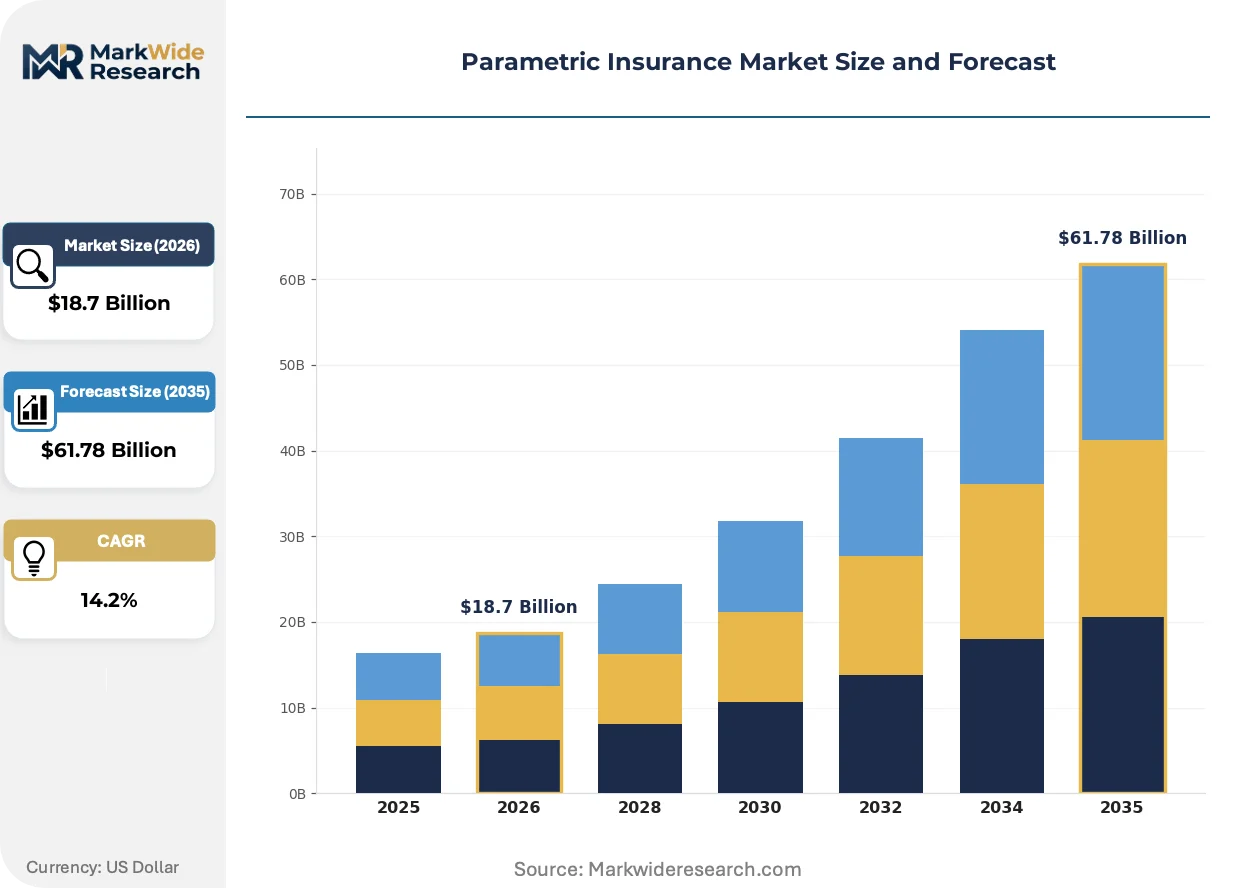
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Index Insurance, Disaster Relief Coverage, Crop Insurance, Event Cancellation Insurance End User: Agriculture, Tourism, Energy, Real Estate Technology: IOT Sensors, Big Data Analytics, Blockchain, Cloud Computing Distribution Channel: Direct Sales, Brokers, Online Platforms, Insurtech Firms |
| Companies Covered | AXA SA, Chubb Limited, Swiss Re, QBE Insurance Group, Berkshire Hathaway, Munich Re, Zurich Insurance Group, Descartes Underwriting, Allianz SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parametric Insurance Market Emerging Trajectories
Distributed data infrastructure is fragmenting traditional underwriting monopolies, enabling granular risk pricing at previously unviable scale.
API-embedded policy issuance is modularizing distribution architecture. Insurtech platforms now embed parametric contracts directly into supply-chain software used by commodity traders and agricultural processors. This bypasses broker intermediation for digital-native buyers while compressing issuance cycles from weeks to minutes. The structural consequence is disintermediation pressure on traditional distribution channels serving price-sensitive segments.
EU Green Deal sustainability disclosure requirements are forcing corporate risk managers to document climate resilience expenditures. Large European industrials now allocate dedicated budgets for parametric protection against regulatory non-compliance penalties. German automotive suppliers and Dutch agribusinesses lead adoption, treating index-based coverage as audit-ready risk mitigation.
Buyer procurement patterns favor pre-negotiated master policies with automatic renewal triggers. Energy traders and agricultural cooperatives now contract multi-year frameworks with escalating coverage limits tied to asset expansion. This shift concentrates purchasing authority at headquarters level while reducing local autonomy. The pattern is most visible in India, where state-level farming federations centralize negotiations with national carriers.
Parametric Insurance Market Segmentation
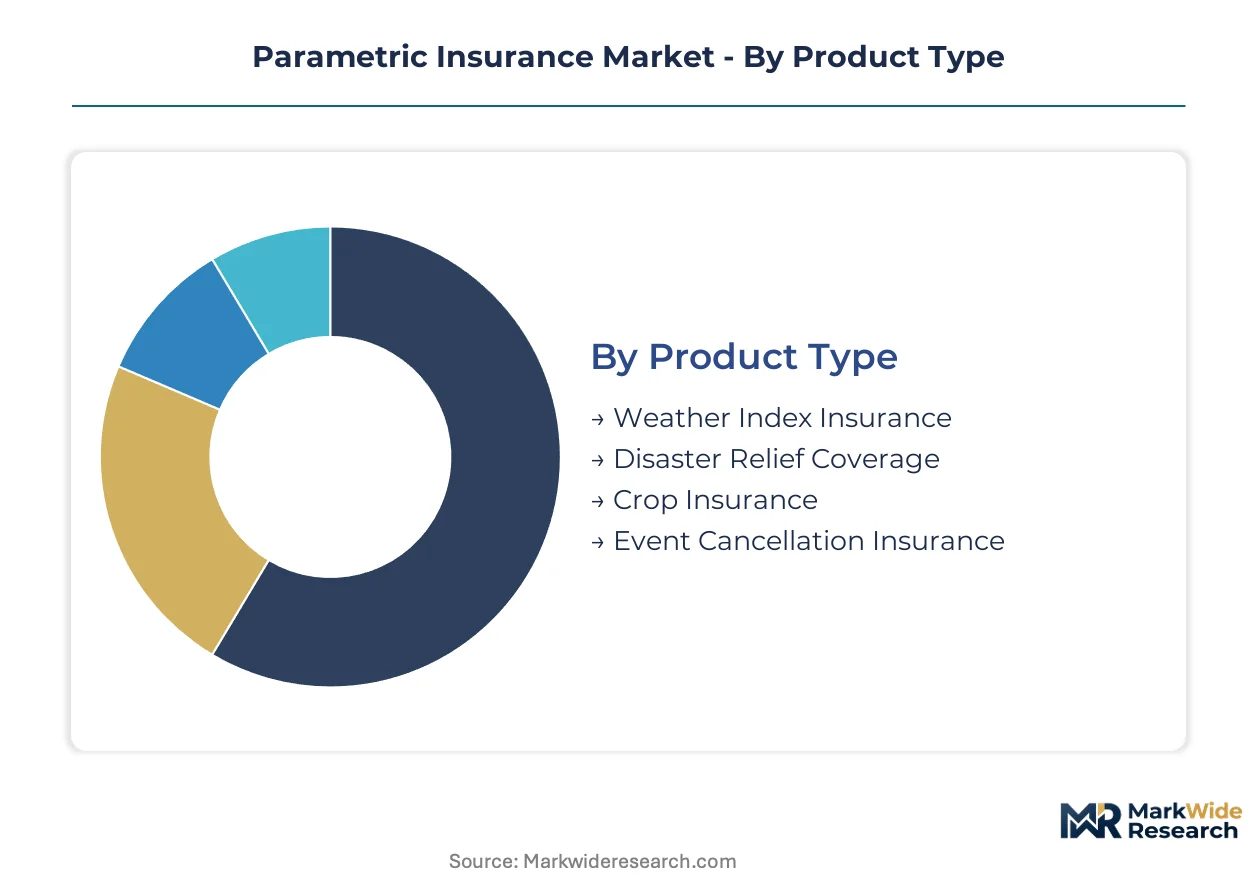
Parametric insurance products diverge sharply in trigger design and data infrastructure requirements. Each segment category reflects distinct underwriting economics and buyer procurement patterns that reshape carrier capital allocation.
Product Type:
Supply concentration in weather-index products dominates carrier balance sheets, while specialized lines command premium pricing for bespoke calibration.
- Weather Index Insurance:Parametric contracts triggered by rainfall millimeters, temperature thresholds, or wind speed readings. Demand concentrates in India where IRDAI-mandated crop schemes and monsoon-dependent farming communities require rapid liquidity after climate shocks.
- Disaster Relief Coverage:Government and NGO-backed instruments paying upon seismic intensity or flood stage measurements. Caribbean island nations and Pacific Ring of Fire jurisdictions anchor procurement volumes as sovereign buyers seek immediate post-catastrophe funding without loss-adjustment delays.
- Crop Insurance:Vegetation index products using satellite-derived NDVI readings to trigger payments. Sub-Saharan African cooperatives aggregate village-level demand for drought protection.
- Event Cancellation Insurance:Ticket revenue protection tied to named peril triggers including extreme weather or terrorism indices. Music festivals and sporting events in exposed coastal zones drive niche adoption.
Weather Index Insurance absorbs the bulk of installed capacity; Disaster Relief Coverage is expanding most quickly.
End User:
Buyer sophistication varies dramatically across sectors, with agricultural procurement scaling through cooperative structures while energy buyers demand multi-asset portfolio coverage.
- Agriculture:Farming collectives and agricultural processors purchasing drought, flood, and heat stress protection. India's state-level federations centralize negotiations with national carriers under subsidized premium frameworks.
- Tourism:Resorts, cruise operators, and destination management companies acquiring hurricane and pandemic-triggered revenue protection. Caribbean and Southeast Asian operators lead adoption.
- Energy:Solar and wind developers hedging against irradiance or wind speed shortfalls. Island nation micro-grids represent underpenetrated demand for weather-indexed revenue stabilization.
- Real Estate:Commercial property owners securing catastrophe liquidity for mortgage covenant compliance. German automotive suppliers and Dutch agribusinesses treat index-based coverage as audit-ready risk mitigation under EU Green Deal disclosure requirements.
Agriculture captures the dominant share of policy count; Energy is gaining share fastest as renewable asset financing mandates parametric coverage.
Technology:
Data infrastructure investments determine underwriting precision and settlement automation, with distributed ledger execution eliminating administrative friction.
- IOT Sensors:Ground-based weather stations and soil moisture probes providing hyperlocal trigger verification. Networks reduce moral hazard for underwriters pricing village-scale contracts in emerging economies.
- Big Data Analytics:Catastrophe modeling platforms processing satellite imagery and historical loss databases. Swiss Re leverages this infrastructure to design bespoke index structures for corporate buyers.
- Blockchain:Smart contract execution automating payout settlement upon oracle-fed trigger confirmation. This segment climbs the fastest as carriers seek finality without manual claims processing.
- Cloud Computing:Scalable data storage and processing enabling real-time index monitoring. Supports API-embedded policy issuance compressing issuance cycles from weeks to minutes.
Big Data Analytics underpins the majority of active underwriting capacity; Blockchain is scaling most rapidly through insurtech platform integration.
Distribution Channel:
Channel economics fragment as digital-native buyers bypass traditional intermediation, rewiring commission structures and customer acquisition costs.
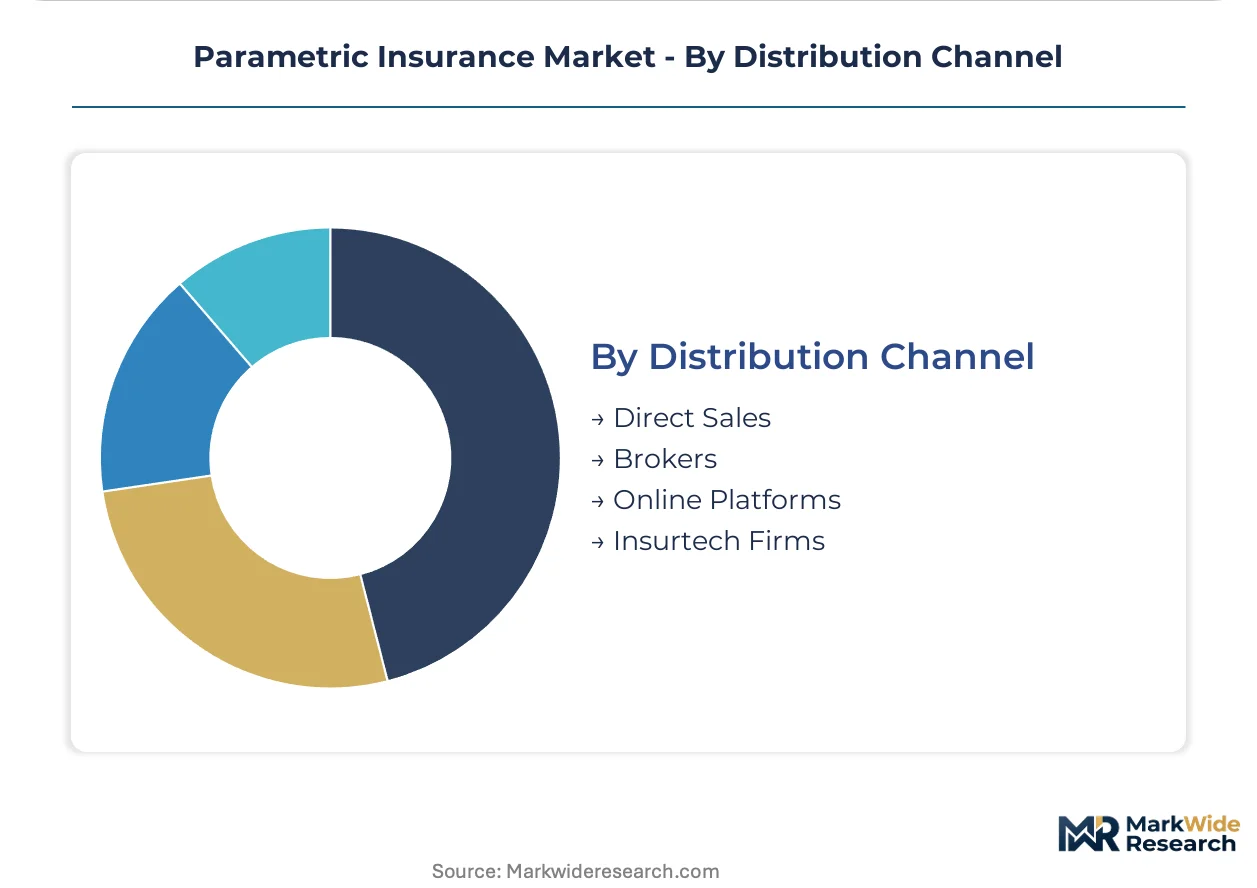
- Direct Sales:Carrier-employed teams serving large corporate accounts with bespoke index design. Energy traders and agricultural cooperatives favor pre-negotiated master policies with automatic renewal triggers.
- Brokers:Traditional intermediaries retaining largest distribution share through relationship-based placement. Serves price-sensitive segments requiring education on parametric basis risk.
- Online Platforms:Digital marketplaces enabling self-service quote and bind for standardized products. Captures small and medium enterprise demand.
- Insurtech Firms:API-embedded distribution integrating parametric contracts into supply-chain software. Platforms now embed policies directly into commodity trader workflows, disintermediating broker channels for digital-native buyers.
Brokers retain the dominant share of premium flow; Insurtech Firms are climbing the fastest through embedded finance partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India anchors parametric insurance demand through IRDAI-mandated crop schemes and monsoon-dependent agricultural communities seeking rapid post-disaster liquidity. Sub-Saharan African cooperatives and Caribbean sovereign buyers are scaling adoption of automated trigger mechanisms for drought and hurricane protection.
India
Agricultural cooperatives in Maharashtra and Gujarat aggregate village-level demand for drought-indexed coverage. IRDAI enforces penetration targets for index-based crop insurance that expand addressable rural markets through subsidized premium structures. The state-level farming federations in Punjab and Haryana centralize negotiations with national carriers under multi-year framework agreements.
United States
Energy traders and agricultural processors in the Midwest seek multi-peril crop coverage and weather-indexed revenue stabilization. The Inflation Reduction Act climate provisions expand corporate buyer budgets for parametric risk transfer against resilient infrastructure mandates. Solar and wind developers in Texas and California anchor procurement volumes for irradiance and wind speed shortfall protection.
Germany
Automotive suppliers and agribusinesses treat index-based coverage as audit-ready risk mitigation under EU Green Deal sustainability disclosure requirements. Solvency II capital frameworks shape how carriers reserve against parametric catastrophe exposures. The industrial clusters in Bavaria and North Rhine-Westphalia concentrate demand for regulatory compliance-linked protection.
Brazil
Agricultural cooperatives in Mato Grosso and São Paulo scale coverage against drought and flood risks for soy and corn production. The country's national agricultural insurance program coordinates premium subsidies that lower farmer entry barriers. Satellite-derived vegetation index products gain traction among large-scale farming operations in the Cerrado region.
Caribbean Nations
Sovereign buyers in Jamaica, Barbados, and Trinidad and Tobago procure disaster relief instruments paying upon seismic intensity or flood stage measurements. The Caribbean Catastrophe Risk Insurance Facility pools regional demand for immediate post-catastrophe funding without loss-adjustment delays. Island micro-grids represent underpenetrated demand for weather-indexed revenue stabilization.
Parametric Insurance Market Vendor Landscape
Strategic partnerships dominate the current landscape as carriers integrate IoT sensor networks and blockchain execution platforms into core operations. The vendor base concentrates among tier-one global reinsurers with catastrophe modeling infrastructure, specialized climate-risk underwriters, and insurtech platforms embedding API-driven distribution. Three archetypes define competitive positioning: scale-driven reinsurers leveraging proprietary data assets, niche specialists designing bespoke index structures for underserved regions, and technology-forward platforms automating smart-contract settlement. Portfolio diversification into agricultural and energy lines, alongside geographic expansion through emerging-economy cooperative networks, represent the dominant competitive vectors.
Within the scale-driven tier, Swiss Re and Munich Re occupy positions as archetypal global reinsurers with established catastrophe modeling infrastructure. Descartes Underwriting sits within the specialist tier as a representative climate-risk parametric underwriter focused on underserved markets. These three entities exemplify how carrier archetypes align with distinct buyer segments—from corporate purchasers seeking bespoke index design to agricultural cooperatives requiring village-scale coverage.
| Leading Market Players |
|---|
| AXA SA |
| Chubb Limited |
| Swiss Re |
| QBE Insurance Group |
| Berkshire Hathaway |
| Munich Re |
| Zurich Insurance Group |
| Descartes Underwriting |
| Allianz SE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainability disclosure requirements gate both qualified supply and premium-tier pricing access, as carriers with verified catastrophe modeling infrastructure command rate advantages while non-compliant underwriters face exclusion from corporate procurement panels.
Pricing Analysis
Volume concentrates in standardized weather-index products with thin margins, while margin pools in bespoke corporate structures requiring proprietary data assets. Price differentiation hinges on calibration precision and settlement automation—carriers with blockchain-enabled smart contracts extract premium pricing for finality guarantees. Cost compression in agricultural lines intensifies because IRDAI-mandated subsidies cap farmer premiums. Smallholder cooperatives exhibit acute price sensitivity; energy traders with multi-year frameworks show lowest sensitivity.
Supply Chain Analysis
Parametric underwriting rests on satellite imagery providers concentrated in the United States, European catastrophe modeling firms, and Asian IoT sensor manufacturers. Critical inputs include orbital remote sensing data, ground-based weather station networks, and distributed ledger execution platforms. Single-source vulnerability in satellite coverage over equatorial regions creates supply chain risk for African and Southeast Asian contracts. Distribution runs through broker intermediaries for price-sensitive segments, while API-embedded platforms serve digital-native buyers directly.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric insurance occupies a technology-transition phase as blockchain smart contracts displace manual claims processing infrastructure across carrier operations.
For Market Incumbents: Extend proprietary catastrophe modeling capabilities into multi-peril agricultural indices before insurtech platforms capture cooperative procurement. Deepen vertical integration into satellite data partnerships to defend calibration precision advantages. Solvency II reserve requirements threaten European carriers who delay automation investments.
For New Entrants and Emerging Players: Island nation micro-grid operators represent an underserved buyer archetype with unmet demand for weather-indexed revenue stabilization. Caribbean sovereign disaster relief instruments and Southeast Asian village-scale cooperatives offer the most penetrable entry points. Embed parametric contracts directly into energy trading platforms to bypass established broker channels.
For Investors and Strategic Acquirers: IRDAI enforcement actions against basis-risk miscalibration are the leading indicator that regulatory scrutiny is concentrating underwriting authority among carriers with verified index precision. Long-term viability favors platforms combining IoT ground networks with smart-contract settlement automation. Acquisition targets should demonstrate proven oracle-fed trigger execution and cooperative distribution partnerships. Watch for climate attribution science advances that validate parametric triggers as substitutes for conventional loss verification.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Contract Platform Integration | Blockchain execution eliminates manual claims friction and accelerates settlement finality for agricultural cooperatives. |
| Satellite Data Partnership Expansion | Orbital imagery agreements with European Space Agency and NASA anchor vegetation index calibration precision. |
| Cooperative Distribution Network Buildout | Village-scale aggregator relationships in India and Brazil lower customer acquisition costs below broker channels. |
| Multi-Peril Index Product Launch | Combined drought-flood-heat coverage commands premium pricing from large-scale farming operations in Cerrado region. |
| API-Embedded Policy Issuance | Direct integration into commodity trader workflows disintermediates traditional broker intermediation for energy buyers. |
Methodological Framework
Independent corroboration across carrier underwriting executives, agricultural cooperative managers, and insurtech platform engineers underwrites the qualitative findings, supplemented by IRDAI regulatory filings, EU Solvency II disclosure reports, and satellite imagery provider technical specifications. Bottom-up demand aggregation from farming federations and top-down capacity assessment from reinsurer balance sheets were cross-validated.
Historical reference periods anchored the forecast window to pre-pandemic baseline penetration rates and post-IRDAI-mandate expansion phases. The analytical framework segmented by trigger type, buyer sophistication tier, and technology infrastructure maturity. CAGRs were derived from policy count trajectories and average premium per contract trends. Forecast inputs incorporated climate attribution science advancement curves and cooperative network expansion timelines.
Revisions become necessary when regulatory acceptance of parametric triggers shifts, satellite coverage gaps persist over target geographies, or blockchain oracle reliability failures materialize. A small set of named triggers—IRDAI mandate enforcement intensity, Solvency II reserve rule amendments, and climate litigation outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United States Bancassurance Market
Insurance
China Liability Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Boiler Insurance Market
Insurance
France Car Insurance Market
Insurance
Global SME Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Africa Insurance Market