
 Netherlands Property and Casualty Insurance Market | 2026-2036
Netherlands Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Property and Casualty Insurance Market Insights
Dutch reinsurance capacity from Lloyd's of London syndicates is realigning toward parametric flood products for low-lying provinces. Achmea Schadeverzekeringen leverages its mutual structure to sustain pricing discipline in agricultural coverage. Nationale-Nederlanden Schadeverzekering anchors corporate property portfolios through integrated risk engineering services.
Property and casualty insurance in the Netherlands encompasses indemnity contracts covering physical asset damage, third-party liability, and business interruption losses, with underwriting grounded in probabilistic catastrophe modeling and Solvency II capital reserving. Its primary purpose is to transfer financial risk from households and enterprises to diversified risk pools backed by reinsurance treaties. Auto insurance dominates premium volume among product types due to mandatory third-party liability requirements, while business interruption coverage expands fastest as Dutch SMEs adopt supply-chain risk transfer following recent logistics disruptions. Brokers control the largest share of distribution channel flow, though online platforms capture disproportionate growth among digitally native customer segments.
De Nederlandsche Bank enforces Solvency II compliance with strict own-risk assessments, while the Dutch Authority for Consumers and Markets scrutinizes premium transparency under EU insurance distribution rules. Climate stress testing from the European Insurance and Occupational Pensions Authority is reshaping capital allocation toward flood-exposed regions. Stakeholders must monitor whether parametric triggers or traditional indemnity structures win preference as sea-level adaptation costs escalate.
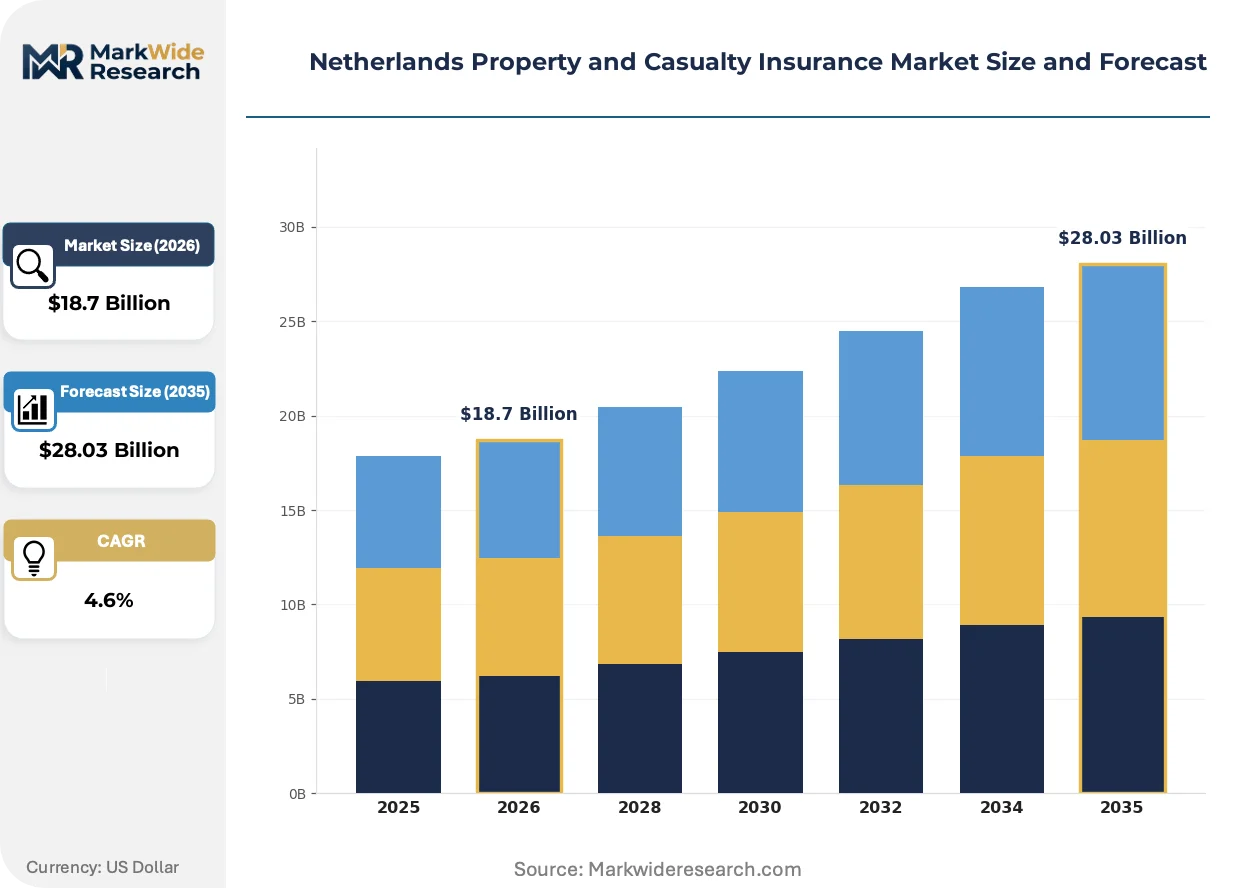
Market Dynamics
EU Green Deal building renovation mandates are forcing Dutch insurers to recalibrate capital reserves against climate-adaptive construction coverage, while flood risk modeling from Lloyd's syndicates reshapes premium differentiation across the Randstad corridor.
Growth Catalysts
- EU Green Deal mandates:Building renovation requirements expand coverage demand for climate-resilient commercial properties across Dutch urban centers.
- Parametric flood triggers:Reinsurance capacity from London syndicates enables faster claims settlement for low-lying provinces facing sea-level pressure.
- Supply-chain risk transfer:Dutch SMEs adopt business interruption coverage following logistics disruptions in Rotterdam port operations.
Market Restraints
- Catastrophe model uncertainty:Probabilistic flood modeling lacks historical calibration for extreme weather scenarios beyond 2050 projections.
- Solvency II capital intensity:Own-risk assessments require elevated reserving for climate-exposed portfolios, compressing underwriting capacity.
- Reinsurance concentration:Lloyd's syndicate capacity dependence creates single-source vulnerability for parametric product lines.
Strategic Opportunities
- Zeeland coastal underpenetration:Agricultural mutual structures face limited competition in flood-prone rural municipalities.
- Integrated risk engineering:Corporate property portfolios demand bundled loss prevention services beyond traditional indemnity structures.
- Digital distribution platforms:Online channels capture digitally native segments underserved by broker-dominated flows.
Industry Challenges
- Catastrophe modeling talent scarcity:Solvency II stress testing requires specialized actuarial expertise in climate scenario analysis.
- Legacy system integration:Parametric trigger automation demands API connectivity with decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Property and Casualty Insurance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homeowners Insurance, Renters Insurance, Auto Insurance, Business Interruption Insurance Customer Type: Individuals, Small Businesses, Large Enterprises, Non-Profit Organizations Coverage Type: Liability Coverage, Property Coverage, Comprehensive Coverage, Collision Coverage Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | Achmea Schadeverzekeringen, Nationale-Nederlanden Schadeverzekering, ASR Schadeverzekering, Univé Schade, De Goudse Verzekeringen, Aegon Schadeverzekering, Zurich Insurance, Lloyd's of London, Interpolis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Property and Casualty Insurance Market Trends and Innovations
Parametric insurance architecture is absorbing traditional indemnity market share as Dutch carriers seek settlement speed advantages over competitors relying on loss adjustment processes.
Telematics-enabled usage-based auto coverage is absorbing risk selection precision from conventional rating factors. Younger policyholders in Amsterdam and Utrecht metropolitan zones adopt pay-per-mile structures at three times the rate of rural counterparts. This shift is absorbing standard annual premium models into dynamic pricing frameworks tied to real-time driving behavior.
EIOPA climate stress testing mandates reshape capital allocation toward flood-exposed Dutch provinces. The European Insurance and Occupational Pensions Authority requires forward-looking scenario analysis for sea-level rise impacts. Property underwriters in South Holland and North Holland respond by embedding elevation data into granular pricing tiers.
Broker channel disintermediation accelerates as direct-to-consumer platforms capture mid-market commercial lines. Digital native SMEs in Eindhoven tech corridors bypass traditional intermediaries for instant quote-to-bind workflows. This behavioral pivot concentrates in Randstad urban corridors where procurement cycles compress below 48 hours.
Netherlands Property and Casualty Insurance Market Segmentation
Dutch property and casualty insurers segment portfolios to align capital reserves with divergent risk profiles across consumer and commercial lines. Product-level granularity enables Solvency II compliance while channel differentiation captures procurement behavior shifts among digitally native segments.
Product Type:
Replacement cycles for policy structures accelerate as climate adaptation mandates force coverage redesign across commercial real estate portfolios.
- Homeowners Insurance:Dwelling and contents coverage structured around rebuild cost indices rather than market valuations. Demand clusters in Randstad urban corridors where flood risk modeling from Lloyd's syndicates drives premium tiering for elevated properties versus ground-floor exposures.
- Auto Insurance:Mandatory third-party liability dominates premium volume through statutory minimum coverage requirements. Telematics-enabled usage-based products from direct carriers absorb risk selection precision in Amsterdam and Utrecht metropolitan zones where younger policyholders adopt pay-per-mile structures.
- Renters Insurance:Contents-only coverage with limited liability extensions for tenant-caused damage.
- Business Interruption Insurance:Supply-chain risk transfer products expanding fastest among Rotterdam port-dependent SMEs.
Volume placements concentrate in Auto Insurance; the faster expansion belongs to Business Interruption Insurance.
Customer Type:
Cost tier segmentation separates price-sensitive retail accounts from corporate portfolios requiring integrated risk engineering services.
- Large Enterprises:Corporate property portfolios demanding bundled loss prevention and captive alternative structures. Concentration in South Holland and North Holland where elevation data integration enables granular pricing for flood-exposed facilities.
- Small Businesses:Standardized package policies with modular extensions for professional liability and cyber coverage. Procurement through digital platforms accelerates in Eindhoven tech corridors where quote-to-bind cycles compress below 48 hours.
- Individuals:Mass-market personal lines distributed through broker networks and direct channels.
- Non-Profit Organizations:Specialized coverage for volunteer liability and mission-critical property assets.
Revenue gravity centers on Large Enterprises; Small Businesses climb the fastest as digital distribution penetration deepens.
Coverage Type:
Application-driven segmentation distinguishes first-party property damage from third-party liability exposures with divergent reserving requirements.
- Property Coverage:Physical asset indemnity against fire, flood, and storm perils with catastrophe modeling from Lloyd's syndicates informing capital allocation. Demand concentrates in Zeeland coastal municipalities where agricultural mutual structures face limited competition.
- Liability Coverage:Third-party bodily injury and property damage protection with strict own-risk assessments under De Nederlandsche Bank supervision. Corporate purchasers in Rotterdam port operations drive expansion following logistics disruption litigation.
- Comprehensive Coverage:All-risk protection combining named perils with unspecified damage extensions.
- Collision Coverage:First-party auto physical damage with telematics-informed deductibles.
Underwriting capacity concentrates in Property Coverage; Liability Coverage gains share fastest as professional lines expand.
Distribution Channel:
Customer type and procurement velocity determine channel selection between advisory intermediaries and automated platforms.
- Brokers:Advisory-led placement controlling largest share of commercial lines flow through negotiated treaty access and claims advocacy. Dominance persists in corporate property portfolios requiring risk engineering coordination.
- Online Platforms:Instant quote-to-bind workflows capturing disproportionate growth among digitally native segments. Penetration accelerates in Randstad urban corridors where mid-market SMEs bypass traditional intermediaries.
- Direct Sales:Captive agent networks and insurer-owned channels for standardized personal lines.
- Agents:Tied representatives with exclusive territorial appointments in rural municipalities.
Transaction volume concentrates in Brokers; Online Platforms expand most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's port infrastructure anchors Dutch risk transfer demand, with marine cargo and logistics underwriting concentrated in South Holland's industrial corridor. Randstad urbanization patterns concentrate property exposure across interconnected metropolitan zones.
Randstad
Flood risk modeling from Lloyd's syndicates drives premium differentiation across Amsterdam, Rotterdam, The Hague, and Utrecht metropolitan clusters. De Nederlandsche Bank mandates elevation-based capital reserves under Solvency II climate stress testing. Corporate property portfolios in South Holland demand bundled risk engineering services as sea-level adaptation costs escalate.
Brabant
Eindhoven's technology corridor accelerates digital distribution adoption among SME policyholders seeking sub-48-hour quote-to-bind cycles. The Dutch Authority for Consumers and Markets scrutinizes premium transparency for online platform transactions. Mid-market commercial lines bypass traditional broker networks in this southern industrial zone.
Zeeland
Agricultural mutual structures sustain pricing discipline in flood-prone coastal municipalities with limited competitor presence. EU Green Deal building renovation mandates expand coverage demand for climate-resilient rural properties. Achmea Schadeverzekeringen leverages cooperative membership models to retain farm policyholders facing parametric trigger alternatives.
Northern Netherlands
Groningen and Friesland provinces exhibit underpenetrated commercial lines penetration relative to Randstad density. Telematics-enabled auto coverage from direct carriers absorbs younger policyholders in Leeuwarden and Groningen urban centers. Provincial regulatory alignment with national Solvency II implementation lags southern corridor sophistication.
Netherlands Property and Casualty Insurance Market Competitive Landscape
Established mutual insurers occupy the standard tier; emerging digital entrants pursue direct-to-consumer distribution through automated underwriting platforms. The Dutch property and casualty market exhibits moderate concentration, with cooperative structures retaining agricultural and personal lines dominance while stock companies anchor corporate commercial portfolios. Three archetypes prevail: mutual insurers with member-based governance, integrated financial conglomerates with cross-selling capabilities, and international reinsurers supplying catastrophe capacity. Competitive dynamics center on parametric product innovation and digital channel expansion.
Within the mutual insurer archetype, Achmea Schadeverzekeringen and Univé Schade exemplify cooperative structures leveraging member loyalty to defend core personal lines positions. Nationale-Nederlanden Schadeverzekering represents the integrated financial conglomerate tier, anchoring corporate property portfolios through risk engineering bundling. These three occupy positions across distinct capital structures rather than competing directly for identical policyholder segments.
| Leading Market Players |
|---|
| Achmea Schadeverzekeringen |
| Nationale-Nederlanden Schadeverzekering |
| ASR Schadeverzekering |
| Univé Schade |
| De Goudse Verzekeringen |
| Aegon Schadeverzekering |
| Zurich Insurance |
| Lloyd's of London |
| Interpolis |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent concentration in the Randstad corridor feeds directly into labor-cost differentials that separate premium risk-engineering bundles from stripped-down indemnity products. Lloyd's syndicate capacity pricing for parametric flood coverage sets the ceiling against which Dutch carriers calibrate their standard-tier offerings.
Pricing Analysis
Risk engineering service bundling defines the premium tier, while unbundled indemnity-only structures populate the economy segment. Three-tier pricing structure across premium, standard, and economy levels reflects divergent levels of loss prevention advisory, claims advocacy, and captive alternative access. Pricing pressure stems from Solvency II capital intensity compressing underwriting capacity for climate-exposed portfolios. Small businesses in Eindhoven tech corridors exhibit highest price sensitivity, driving digital platform adoption; large enterprises with Rotterdam port dependencies accept premium pricing for integrated risk engineering.
Supply Chain Analysis
Freight and logistics costs for Lloyd's syndicate reinsurance capacity concentrate supply chain exposure in London, Bermuda, and Zurich as primary catastrophe capacity sources. Dutch carriers draw from this triad for parametric flood triggers, traditional treaty structures, and collateralized alternative capital. Single-source vulnerability concentrates in London market capacity for Zeeland coastal agricultural lines. Distribution runs through broker networks for commercial placements, while direct platforms capture personal lines flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
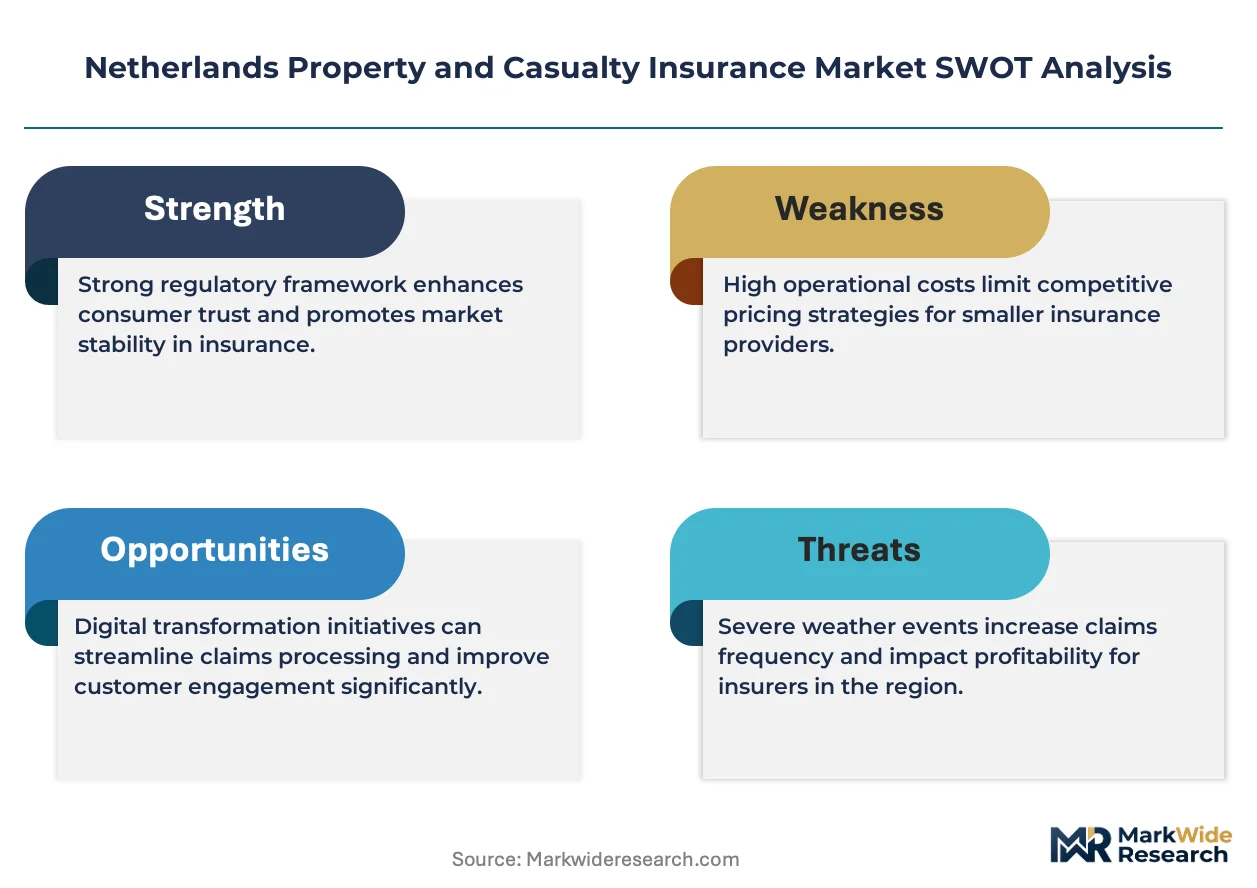
This market reads as supply-constrained: Lloyd's syndicate capacity rationing for parametric products props pricing power for carriers with established London relationships.
For Market Incumbents: Deepen captive alternative structures for Rotterdam port-dependent corporates facing liability coverage expansion from logistics disruption litigation. Fortify elevation-data integration capabilities before EIOPA climate stress testing mandates harden capital requirements. Prioritize API connectivity investments to automate parametric trigger settlement against digital entrant speed advantages.
For New Entrants and Emerging Players: Launch via direct-to-consumer platforms targeting telematics-enabled auto coverage in Amsterdam and Utrecht metropolitan zones where younger policyholders abandon annual premium models. Exploit Zeeland coastal agricultural mutual underpenetration with cooperative-competing membership structures. Lead with sub-48-hour quote-to-bind workflows to bypass entrenched broker relationships in Brabant SME segments.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated financial conglomerates possessing risk engineering bundling capabilities given EIOPA climate stress testing catalysts. Long-term viability favors carriers with diversified reinsurance treaty access beyond Lloyd's concentration. Watch parametric trigger adoption rates among Zeeland farm policyholders as inflection signal for mutual structure disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Architecture | Lloyd's syndicate capacity enables faster settlement than traditional loss adjustment processes. |
| Telematics Platform Integration | Amsterdam and Utrecht policyholders adopt usage-based auto coverage at triple rural rates. |
| Risk Engineering Service Bundling | Corporate property portfolios in South Holland demand loss prevention beyond indemnity structures. |
| Digital Distribution Expansion | Eindhoven tech corridor SMEs bypass brokers for instant quote-to-bind workflows. |
| Climate Stress Testing Compliance | De Nederlandsche Bank mandates elevation-based capital reserves under Solvency II frameworks. |
Research Methodology
De Nederlandsche Bank regulatory filings, EIOPA climate stress testing disclosures, and Lloyd's of London market capacity reports formed the secondary backbone for this analysis. Primary interviews with property underwriters, reinsurance treaty brokers, actuarial risk modelers, and SME procurement officers in Rotterdam and Eindhoven corridors validated quantitative assumptions. Bottom-up policy count triangulation against top-down premium volume estimates anchored market size calculations.
Historical trendline analysis across written premium volumes and loss ratio patterns informed projection trajectories throughout the forecast period. Segmentation modeling incorporated product type, customer scale tier, coverage structure, and distribution channel dimensions with regional granularity for Randstad, Brabant, Zeeland, and Northern Netherlands clusters. CAGRs derived from trend extrapolation adjusted for EU Green Deal mandate impacts and parametric product displacement rates.
Regulatory implementation delays, catastrophe model recalibration events, and reinsurance capacity shocks are the dominant revision risks to forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Japan Parametric Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Financial Guarantee Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
France Liability Insurance Market
Insurance
France Car Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Estonia Property and Casualty Insurance Market
Insurance
Fire Insurance Market
Insurance
Workers Compensation Insurance Market