
 Disability Insurance Market | 2026-2036
Disability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Disability Insurance Market Analysis
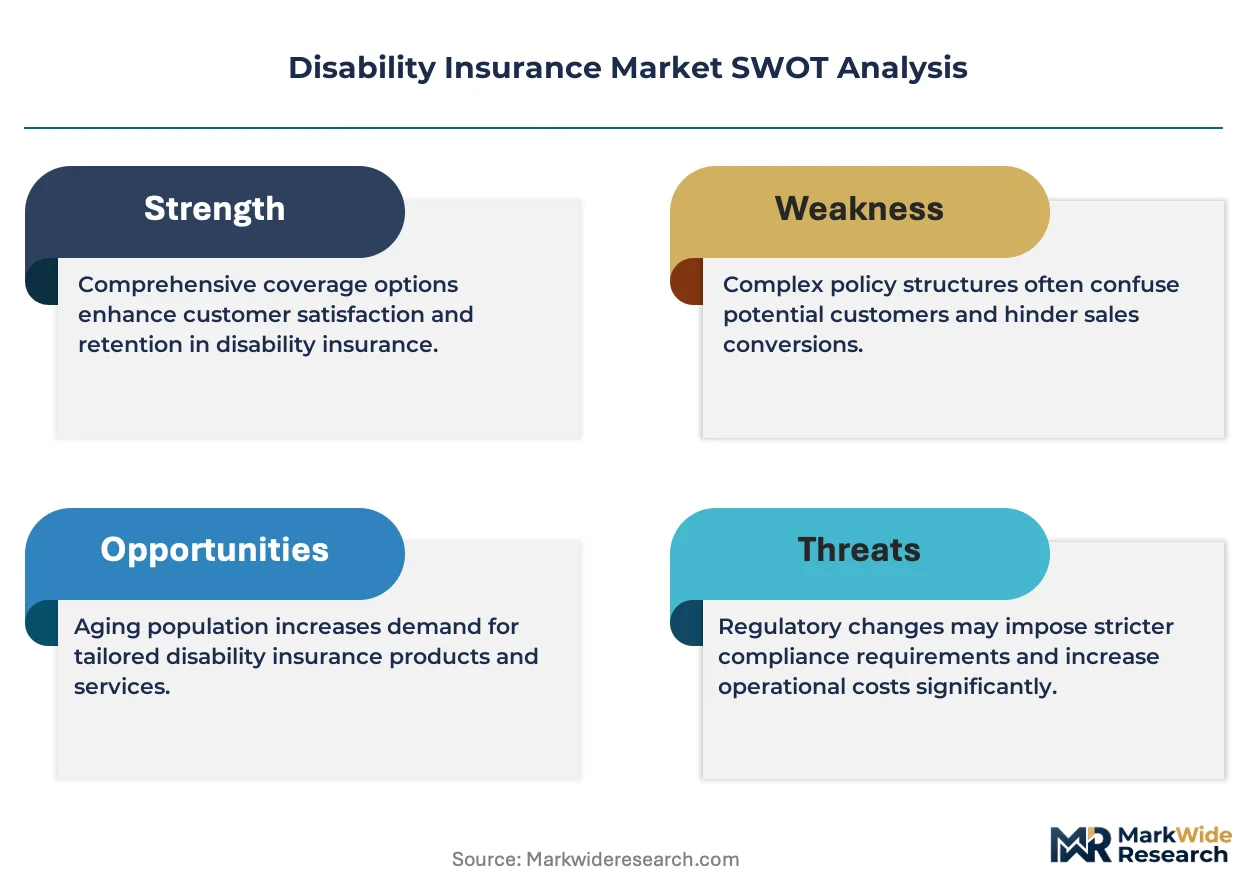
The EU AI Act is expanding compliance obligations for automated claims processing, forcing insurers to restructure disability underwriting workflows. Unum leverages its occupational specialization to navigate these algorithmic transparency mandates. Hartford anchors its position through employer channel control across Fortune 500 accounts.
Disability insurance provides income replacement benefits triggered by medically certified incapacity to perform occupational duties, with benefit periods spanning weeks to retirement age and elimination periods typically ranging from 30 to 180 days. Its primary commercial purpose is to protect wage continuity for workers and reduce employer exposure to statutory sick-pay liabilities. Long-term disability products dominate premium pools due to extended benefit durations and higher per-policy values, while group plans sustain volume leadership through payroll-deduction distribution efficiency. Own-occupation coverage differentiates at the high-income segment where professional specialty definitions command premium pricing.
OSHA workplace safety standards, HIPAA medical privacy rules, and state-level insurance commissioner solvency requirements collectively shape product design and market access across US jurisdictions. The EU Green Deal's occupational health extensions and REACH chemical exposure tracking are pressuring European carriers to integrate environmental risk factors into disability pricing models. Stakeholders must monitor how biometric wearables and predictive health analytics reshape claims adjudication before regulatory frameworks crystallize.
Market Dynamics
Algorithmic transparency mandates under the EU AI Act are forcing disability insurers to reconstruct automated underwriting workflows, creating compliance-driven product differentiation while elevating operational costs across European jurisdictions.
Growth Catalysts
- Occupational Health Extensions:The EU Green Deal mandates environmental risk tracking in workplace safety protocols, compelling German employers to expand private disability supplementation beyond statutory minimums.
- Technology Sector Coverage Mandates:Silicon Valley employers are extending long-term disability benefits as competitive talent retention instruments amid acute engineering labor shortages.
- Biometric Integration:Wearable health monitoring is expanding into claims verification processes, enabling real-time incapacity documentation that accelerates benefit adjudication timelines.
Market Restraints
- Medical Data Fragmentation:HIPAA interoperability limitations create friction in electronic health record exchanges between US providers and disability carriers, elongating elimination period verifications.
- Reinsurance Capacity Concentration:London and Bermuda markets dominate catastrophic disability risk absorption, creating pricing volatility when natural catastrophe reserves deplete.
- Long-Tail Liability Mismatch:Extended benefit durations stretching to retirement age expose carriers to decades-long inflation and medical cost escalation uncertainties.
Strategic Opportunities
- Gig Economy Penetration:Platform workers across Spain and Italy remain substantially uninsured, creating white space for modular short-term disability products with weekly premium structures.
- Predictive Analytics Convergence:Machine learning integration with occupational health databases enables pre-claim intervention programs that reduce incidence rates among high-risk employer segments.
- Embedded Distribution:Payroll software providers are emerging as affinity channels, allowing real-time enrollment during onboarding workflows without broker intermediation.
Industry Challenges
- Actuarial Talent Scarcity:Specialized disability pricing expertise concentrated among aging practitioners in Hartford and London creates succession risk as retirement waves accelerate.
- Legacy System Integration:Mainframe policy administration platforms at established carriers resist API connectivity with modern claims management suites, delaying real-time data flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disability Insurance Market |
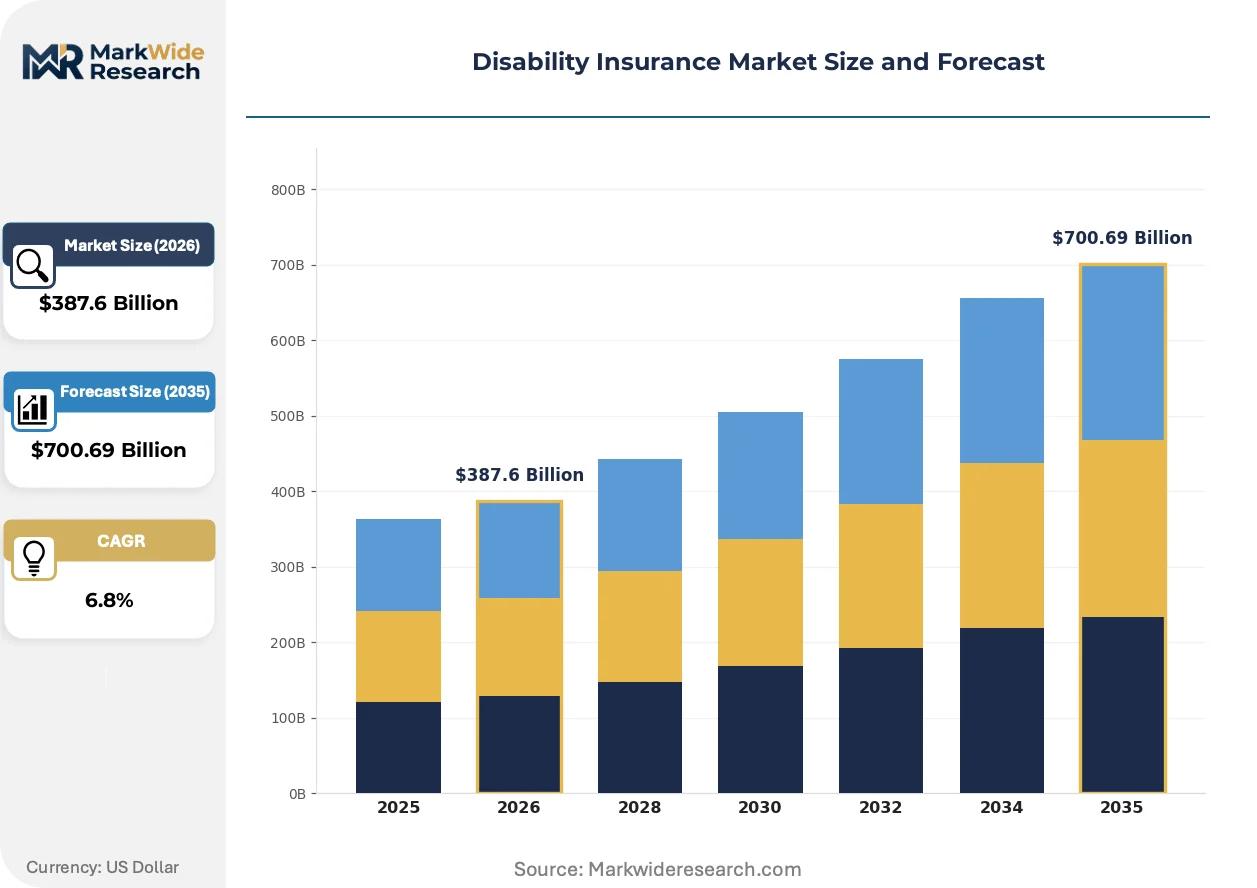
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Term Disability, Long-Term Disability, Critical Illness Insurance, Income Protection Insurance Service Type: Individual Plans, Group Plans, Employer-Sponsored Plans, Government Programs Client Type: Self-Employed, Small Businesses, Corporations, Non-Profits Coverage Type: Own Occupation, Any Occupation, Partial Disability, Total Disability |
| Companies Covered | Unum, Hartford, Lincoln Financial, New York Life, MetLife, Principal Financial Group, The Standard, Guardian, Mutual of Omaha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disability Insurance Market Emerging Trajectories
Digital health infrastructure is compressing traditional claims cycles while regulatory fragmentation across Atlantic jurisdictions forces parallel product development tracks. Insurers must simultaneously modernize customer interfaces and reconstruct backend adjudication engines.
Telemedicine-enabled disability verification is expanding into routine claims assessment, allowing remote physician consultations to replace in-person medical examinations for non-complex musculoskeletal conditions. Mid-market employers with distributed workforces are adopting this channel most aggressively. The technology is compressing elimination period durations from ninety to thirty days in competitive group contracts.
The EU AI Act's algorithmic accountability requirements are mandating explainable decision trees for automated claim denials, forcing carriers to abandon black-box predictive models in European operations. This regulatory friction is diverging product architectures between EU and US jurisdictions. German carriers are responding by establishing dedicated compliance functions that document each automated determination pathway.
Employer procurement committees are unbundling disability from bundled group benefits packages, negotiating standalone contracts with occupational specialization rather than accepting default carrier arrangements. This disintermediation of traditional broker-consolidated purchasing is most pronounced among Fortune 1000 technology and professional services firms. California and Massachusetts employers are leading this unbundling movement due to state-specific coverage mandates that exceed standard package configurations.
Disability Insurance Market Segmentation
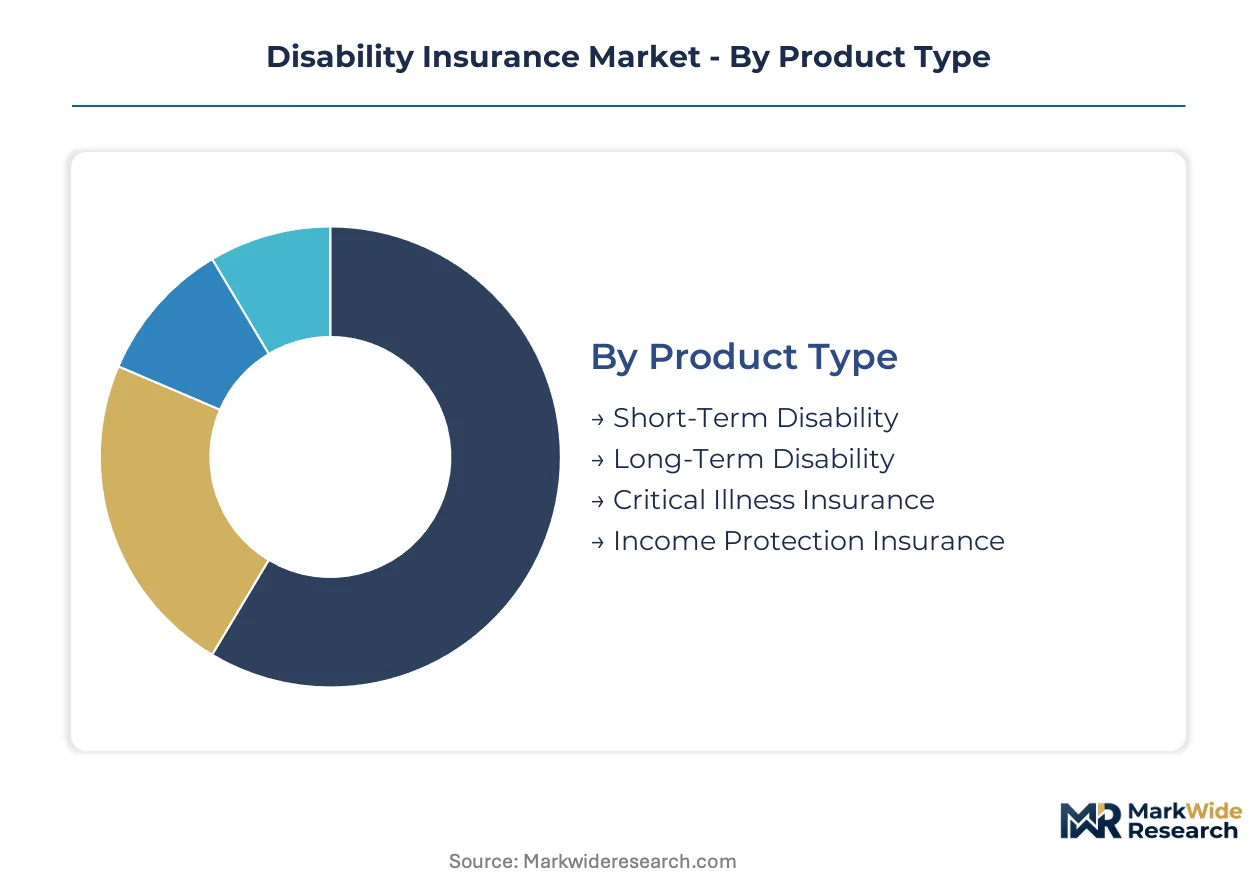
Disability insurance segmentation reflects divergent capital deployment strategies across policy duration, distribution infrastructure, and risk-pooling mechanics. Underwriting complexity varies dramatically between short-tail individual products and long-tail group liabilities requiring decades of reserve maintenance.
Product Type:
Long-term disability products demand the heaviest upfront capital reserves due to benefit durations extending to retirement age and inflation-linked payout obligations.
- Short-Term Disability:Covers income replacement for temporary incapacities lasting under six months, typically triggered by pregnancy, surgery recovery, or acute injury. Demand concentrates among mid-sized employers in Germany seeking to supplement statutory sick-pay gaps during the first 90 days of absence.
- Long-Term Disability:Provides extended income replacement from six months through retirement age, with own-occupation definitions commanding premium pricing for high-income professionals. German occupational disability reforms and aging workforce demographics intensify demand for private supplementation beyond statutory minimums.
- Critical Illness Insurance:Lump-sum payments upon diagnosis of specified conditions rather than income replacement streams.
- Income Protection Insurance:Broader coverage umbrella integrating multiple incapacity triggers with flexible benefit structures.
Long-term disability absorbs the bulk of installed capacity; short-term disability is expanding most quickly among platform employers seeking modular coverage.
Service Type:
Group plans generate volume leadership through payroll-deduction distribution efficiency, while individual plans require heavier marketing spend per policy acquisition.
- Group Plans:Employer-aggregated coverage with simplified underwriting and automatic enrollment via payroll systems. Technology firms across California and Massachusetts are unbundling these from bundled benefits packages to negotiate standalone occupational specialization.
- Employer-Sponsored Plans:Partially subsidized coverage where employers absorb premium costs as talent retention instruments. Silicon Valley engineering employers extend these benefits amid acute labor shortages, with coverage mandates expanding under evolving workplace safety protocols.
- Individual Plans:Direct-to-consumer policies requiring full medical underwriting and higher per-unit acquisition costs.
- Government Programs:Statutory minimums creating baseline coverage floors that private markets supplement.
Group plans dominate premium volume; employer-sponsored configurations are climbing the fastest as competitive talent instruments.
Client Type:
Corporations command dedicated underwriting teams and customized policy terms, while small businesses strain standard product economics with higher per-capita servicing costs.
- Corporations:Fortune 500 accounts with complex multi-jurisdictional coverage needs and dedicated claims management requirements. Hartford anchors market position through channel control across these accounts, leveraging scale for proprietary policy terms.
- Small Businesses:Firms with under 100 employees facing limited product choice and higher relative premiums due to adverse selection risk in small pools.
- Self-Employed:Platform workers and independent contractors lacking employer aggregation benefits.
- Non-Profits:Mission-driven organizations with constrained budgets seeking value-oriented coverage configurations.
Corporations anchor revenue concentration; self-employed segments show steepest expansion trajectory as gig economy penetration creates white space for modular products.
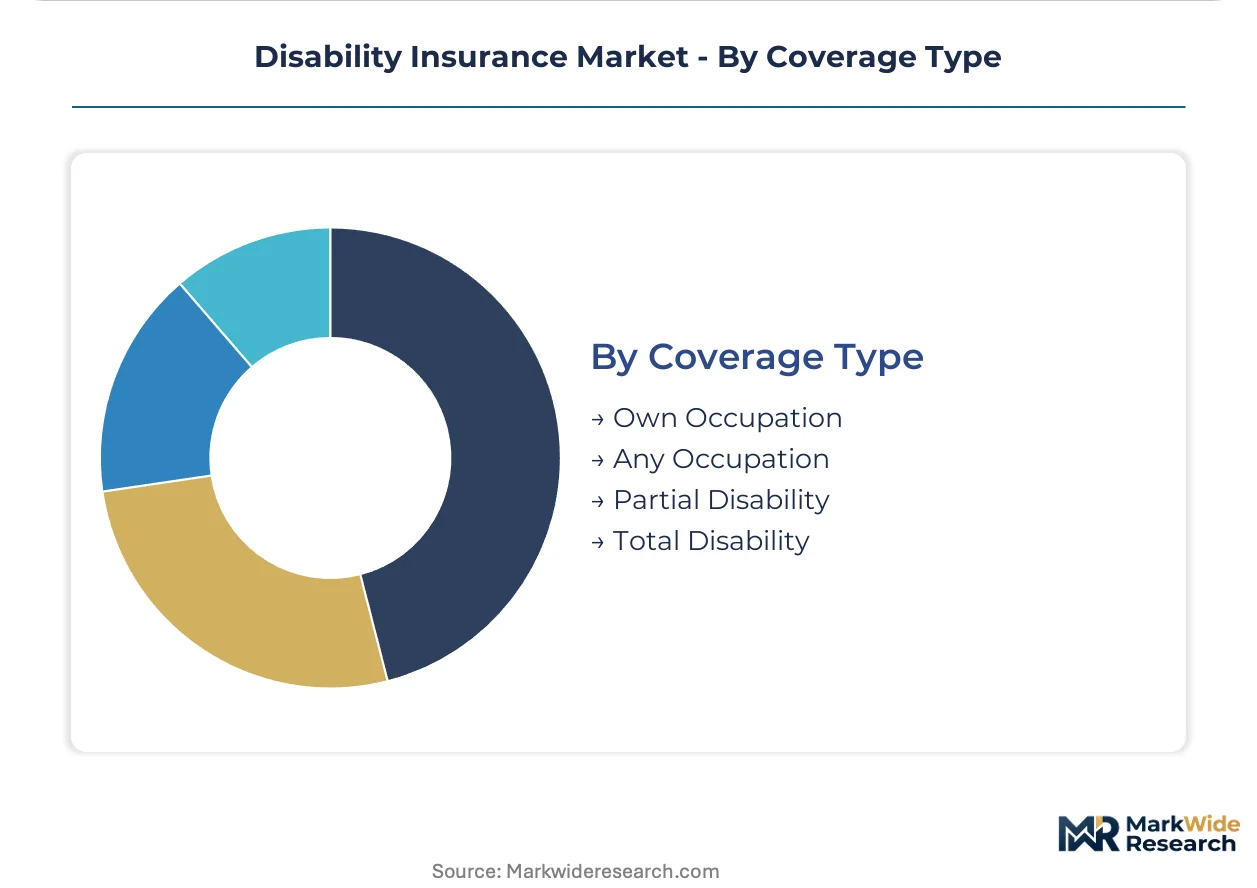
Coverage Type:
Own-occupation definitions require specialized actuarial modeling and legal reserve structures, elevating capital intensity relative to broader any-occupation formulations.
- Own Occupation:Benefits triggered when insured cannot perform specific professional duties, regardless of capacity for alternative work. High-income physicians, attorneys, and executives in Massachusetts and California command premium pricing for these specialty definitions.
- Any Occupation:Stricter threshold requiring incapacity for all gainful employment, reducing claim incidence and premium levels.
- Total Disability:Complete incapacity formulations with binary claim determination.
- Partial Disability:Proportional benefits for reduced work capacity, requiring complex residual earnings calculations.
Own occupation absorbs the bulk of high-value policy capacity; partial disability is gaining share fastest as return-to-work programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hartford anchors North American disability insurance underwriting capacity, with the metropolitan corridor hosting concentrated actuarial talent pools and legacy carrier headquarters that shape product development cycles across the continent.
United States
OSHA workplace safety standards and HIPAA medical privacy rules create dual compliance layers for carriers operating across state jurisdictions. Massachusetts and California employers lead the unbundling movement, negotiating standalone occupational specialization contracts rather than accepting default broker-consolidated packages. The San Francisco Bay Area technology corridor drives demand for extended long-term disability benefits as competitive talent retention instruments.
Germany
Aging workforce demographics and occupational disability reforms intensify private supplementation needs beyond statutory minimums. The EU Green Deal mandates environmental risk tracking in workplace safety protocols, compelling employers to expand coverage. The Rhine-Ruhr industrial cluster sees concentrated demand from manufacturing employers integrating REACH chemical exposure data into underwriting submissions.
United Kingdom
GDPR medical data governance and Financial Conduct Authority solvency requirements shape product design for Lloyd's syndicates and domestic carriers. London's reinsurance market absorbs catastrophic disability risk from global portfolios. The City of London financial district generates specialized own-occupation demand among high-income professional services firms.
Canada
Health Canada occupational health extensions and provincial workers' compensation harmonization create regulatory complexity for multi-jurisdictional employers. Toronto's financial services corridor concentrates group plan underwriting expertise. Ontario technology employers are extending disability benefits amid engineering labor competition with US markets.
France
ANSM medical device oversight and CNIL biometric data restrictions constrain wearable-enabled claims verification deployments. The EU AI Act's algorithmic transparency mandates force reconstruction of automated underwriting workflows. Paris-based multinational employers navigate these compliance obligations while maintaining cross-border coverage consistency.
Disability Insurance Market Vendor Landscape
Premium-margin players sit above commodity-margin players across occupational specialization depth, with own-occupation definitions commanding pricing power while any-occupation formulations compete on cost efficiency. The market structure consolidates around three strategic archetypes: legacy carriers with employer channel control, mutual insurers with policyholder governance structures, and specialized occupational underwriters with medical risk expertise. Dominant competitive moves include unbundling from bundled group benefits packages and embedded distribution partnerships with payroll software providers.
Within the legacy carrier tier, Unum and Hartford exemplify divergent positioning strategies. Unum occupies a position emphasizing occupational specialization to navigate algorithmic transparency mandates. Hartford anchors market presence through employer channel control across Fortune 500 accounts. Lincoln Financial sits within the mutual insurer archetype, representing policyholder-governed capital deployment in long-tail disability liabilities.
| Leading Market Players |
|---|
| Unum |
| Hartford |
| Lincoln Financial |
| New York Life |
| MetLife |
| Principal Financial Group |
| The Standard |
| Guardian |
| Mutual of Omaha |
| Others |
Supply Flow & Price Mechanics
Employer unbundling of disability coverage from consolidated benefits packages is forcing carriers to restructure pricing models and supply chain configurations around standalone occupational specialization rather than bundled cost averaging.
Pricing Analysis
Value-based pricing anchored to claim outcome predictability and return-to-work success rates now dominates employer-sponsored configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by own-occupation definition precision, biometric integration depth, and embedded vocational rehabilitation services. Cost compression in standard-tier group plans is intensifying because payroll software providers are disintermediating traditional broker commissions. Small businesses with under 100 employees exhibit highest price sensitivity due to adverse selection risk pooling, while Fortune 500 technology employers prioritize outcome guarantees over premium minimization.
Supply Chain Analysis
ISO 27001 and SOC 2 certification requirements for claims data handling are gating vendor participation in carrier technology stacks. Actuarial talent concentrates in Hartford, London, and Bermuda, while biometric sensor manufacturing feeds from Taiwan, South Korea, and China. Single-source vulnerability in London and Bermuda reinsurance markets creates pricing volatility when catastrophic disability reserves deplete. Distribution runs through employer payroll systems, payroll software provider APIs, and residual broker channels for complex multi-jurisdictional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance mandates and algorithmic transparency requirements are accelerating consolidation as smaller carriers lack capital to reconstruct automated underwriting workflows.
For Market Incumbents: Extend occupational specialization depth to defend pricing power against payroll software disintermediation. Acquire predictive analytics capabilities to preempt claim incidence through pre-claim intervention programs. Hartford and Unum should deepen employer channel control before embedded distribution partnerships lock in competitor relationships. For New Entrants and Emerging Players: The gap between premium own-occupation pricing and economy any-occupation tiers creates white space for modular short-term disability products targeting platform workers in Spain and Italy. Gig economy penetration remains substantially underdeveloped. A weekly premium structure distributed through freelance marketplace integrations offers the most penetrable entry vector. For Investors and Strategic Acquirers: The window for entry favors specialized occupational underwriters with medical risk expertise and established compliance documentation for EU AI Act algorithmic accountability. Long-term viability hinges on 5-10 year regulatory framework stability across Atlantic jurisdictions. Watch for biometric wearable integration mandates in German occupational health extensions as the inflection indicator for technology-enabled claims verification scale.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Compliance | EU AI Act mandates force reconstruction of automated underwriting workflows across German and French operations. |
| Embedded Distribution Partnership | Payroll software API integrations disintermediate traditional broker channels for mid-market employer acquisition. |
| Biometric Claims Verification | Wearable health monitoring accelerates benefit adjudication timelines for musculoskeletal condition documentation. |
| Occupational Specialization Unbundling | Fortune 1000 technology employers negotiate standalone contracts with specialty definitions beyond bundled packages. |
| Pre-Claim Intervention Programs | Machine learning integration with occupational health databases reduces incidence rates among high-risk employer segments. |
Methodological Framework
SEC 10-K filings, NAIC statutory financial statements, and EU insurance supervisory authority reports formed the secondary backbone of this analysis. Primary interviews with disability underwriting executives, actuarial pricing directors, employer benefits procurement managers, and reinsurance placement specialists were conducted across Hartford, London, and Frankfurt. Bottom-up policy count and premium volume estimates were triangulated against top-down carrier balance sheet analysis.
Historical trendline analysis of statutory disability premium growth and claim incidence patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product type, service configuration, client size tier, and coverage definition granularity. CAGRs were derived from fitted growth curves calibrated to regulatory reform implementation timelines and workforce demographic shifts. Forecast inputs included German occupational disability reform penetration rates and technology sector employer coverage mandate expansion.
Underlying measurement precision varies by segment; group plan volume estimates carry tighter precision than individual policy counts due to consolidated carrier reporting. Forecasts reflect assumptions about EU AI Act implementation uniformity and HIPAA interoperability advancement timelines. A model refresh is warranted upon material change in biometric wearable regulatory classification or reinsurance capacity availability in London and Bermuda markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Extended Warranty Market
Insurance
Europe Parametric Insurance Market
Insurance
Financial Protection Market
Insurance
Green Insurance Market
Insurance
India Online Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
United States Commercial Insurance Market
Insurance
Parametric Insurance Market
Insurance
Takaful Insurance Market
Insurance
India Dental Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Entertainment Insurance Market
Insurance
Art Insurance Market