
 Reinsurance Carriers Market | 2026-2036
Reinsurance Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Reinsurance Carriers Market Analysis
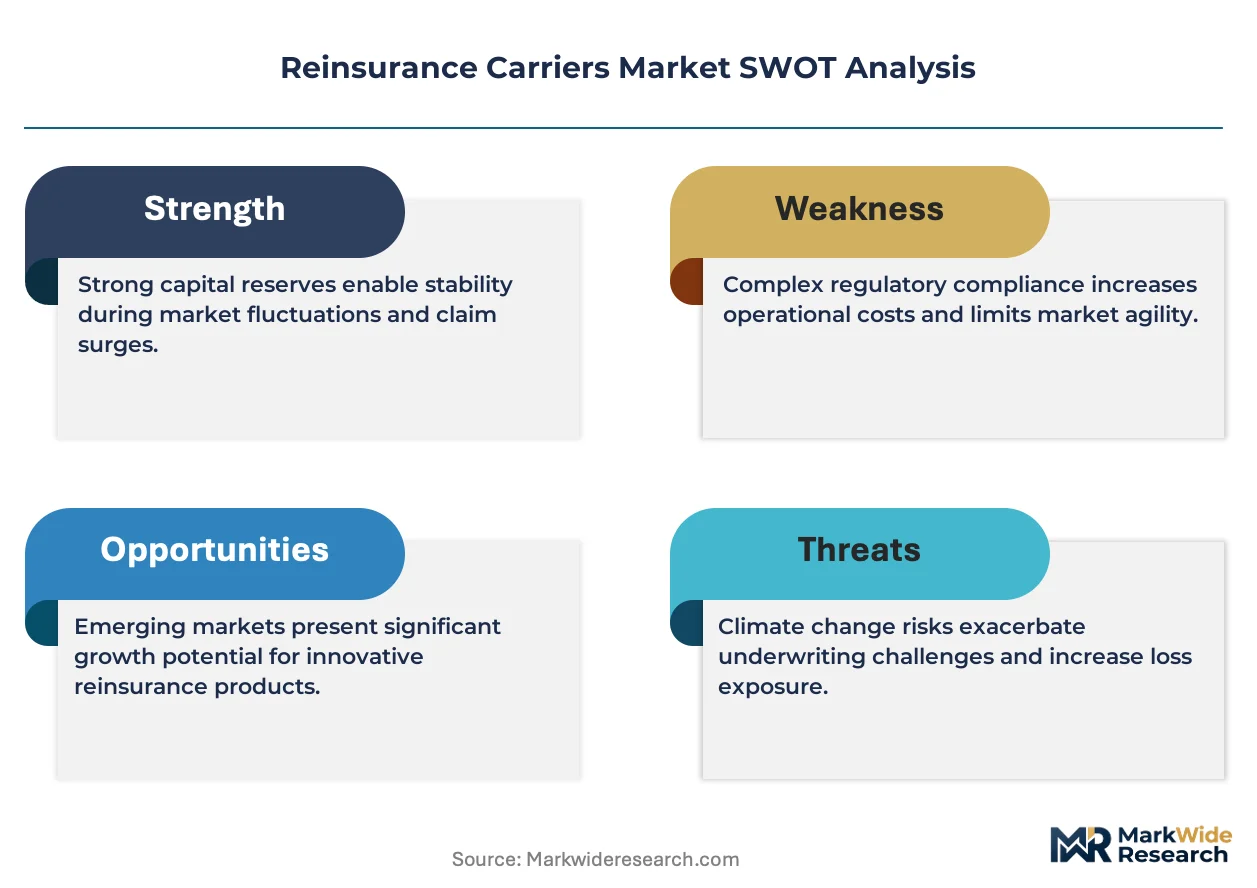
Alternative capital from insurance-linked securities is broadening the reinsurance capacity available for peak peril coverage, compressing traditional pricing layers while creating new structural opportunities for risk transfer. Munich Re leverages its century-long data archives and direct client relationships to sustain pricing power in property catastrophe lines. Swiss Re anchors global nat-cat modeling capabilities, allowing it to compete in complex agricultural and flood portfolios where technical precision differentiates offerings. Hannover Re specializes in long-tail casualty reinsurance, occupying a niche where underwriting discipline and reserve adequacy determine franchise value.
A reinsurance carrier assumes portions of insurance risk from primary insurers in exchange for premium, utilizing probabilistic catastrophe models, stochastic simulation, and layered capital structures to price and reserve against correlated loss events. Property reinsurance dominates premium volume as climate volatility elevates frequency-severity dynamics in wind and flood exposures, while life reinsurance generates stable fee income from mortality and longevity swaps tied to pension de-risking. Treaty arrangements command the majority of ceded premiums because insurers prefer automatic coverage for predictable risk volumes, though facultative placements retain margin importance for complex commercial risks outside standard treaty terms.
Solvency II in Europe, the Bermuda Monetary Authority's insurance code, and state-level credit for reinsurance rules across the United States collectively shape capital adequacy requirements, collateral demands, and cross-border market access for carriers. The National Association of Insurance Commissioners model law on credit for reinsurance determines whether U.S. cedents can recognize capital relief from non-admitted reinsurers, directly influencing where carriers domicile and how they structure collateral trusts. Stakeholders must monitor how climate stress testing mandates from supervisors in Bermuda, Switzerland, and the United Kingdom reshape capital charges and pricing assumptions for peak peril exposures.
Market Dynamics
Alternative capital from insurance-linked securities is compressing traditional reinsurance pricing layers while simultaneously expanding capacity for peak peril coverage, forcing incumbent carriers to differentiate through modeling sophistication and client relationships.
Growth Catalysts
- Solvency II capital requirements:European cedents face risk-based capital charges that push them toward proportional reinsurance treaties and structured solutions that optimize regulatory capital efficiency.
- Climate volatility in coastal property:Insurers in Florida, Texas, and California are expanding catastrophe treaty purchases as modeled wind and flood severity trends accelerate.
- Parametric triggers:Satellite-based index settlement mechanisms are accelerating claim payments for agricultural and natural disaster portfolios, reducing basis risk disputes.
Market Restraints
- Collateral trust costs:Non-admitted reinsurers must post 100% collateral under NAIC model law, elevating capital costs for Bermuda and London carriers competing in U.S. property lines.
- Model convergence risk:RMS and AIR Worldwide catastrophe models dominate peak peril pricing, creating systemic blind spots when underlying assumptions prove inaccurate.
- Long-tail casualty reserving:Social inflation in U.S. liability lines has eroded reserve adequacy across multiple underwriting years, compressing capital availability.
Strategic Opportunities
- Cyber reinsurance expansion:Silent cyber exposure in property treaties and standalone cyber capacity shortages create white space for carriers with granular data and scenario modeling capabilities.
- Longevity swap growth:UK and Dutch pension funds are de-risking mortality exposure through reinsurance structures, generating stable fee income independent of underwriting cycles.
- Fronting arrangements:Captive formation in Vermont and Bermuda allows reinsurers to access primary insurance cash flows while ceding risk to affiliated vehicles.
Industry Challenges
- Catastrophe modeler talent scarcity:Stochastic simulation expertise and geospatial analytics skills command premium compensation, constraining carrier expansion into complex agricultural and flood portfolios.
- Legacy system integration:Treaty administration platforms from the 1990s impede real-time data exchange with cedents, delaying bordereaux processing and collateral adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinsurance Carriers Market |
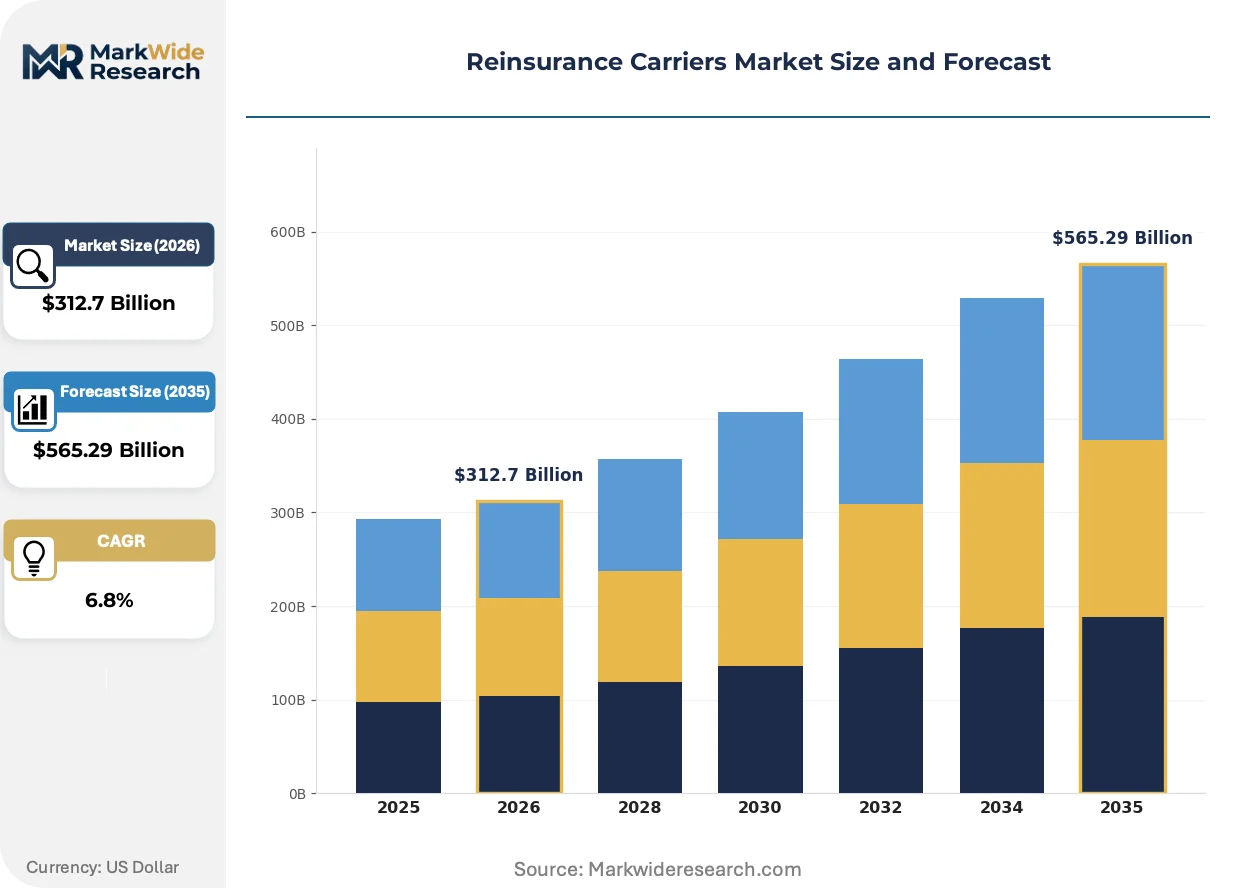
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Reinsurance, Casualty Reinsurance, Life Reinsurance, Health Reinsurance Client Type: Insurers, Captives, Governments, Corporates Service Type: Facultative, Treaty, Proportional, Non-Proportional Distribution Channel: Brokers, Direct Sales, Online Platforms, Reinsurance Exchanges |
| Companies Covered | Munich Re, Swiss Re, Hannover Re, Berkshire Hathaway, SCOR, Reinsurance Group of America, Everest Re, Renaissance Re, China Reinsurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinsurance Carriers Market Emerging Trajectories
Distributed ledger technology and satellite-based monitoring are restructuring how risk is verified, priced, and settled across treaty and facultative placements.
Blockchain-enabled smart contracts are decentralizing the settlement layer for parametric catastrophe bonds. ILS fund managers in Bermuda and Singapore are piloting automated oracle-triggered payments for earthquake and windstorm indices, eliminating multi-month loss adjustment processes. This compression of settlement latency is decentralizing traditional claims infrastructure and reducing frictional costs for peak peril coverage.
Climate stress testing mandates from the Bermuda Monetary Authority and the UK's Prudential Regulation Authority are elevating capital charges for unmodeled tail risks. Carriers must now demonstrate resilience against 1-in-200 year scenarios across multiple peril regions simultaneously. European cedents are responding by purchasing aggregate stop-loss protection and diversifying reinsurance panels across Lloyd's, continental Europe, and Bermuda.
Primary insurers are unbundling facultative placement workflows from treaty administration, creating specialized broker channels for complex commercial risks. Mid-sized U.S. property insurers now channel 40% of facultative premium through digital placement platforms that aggregate capacity from multiple reinsurers. This channel fragmentation is most pronounced in Texas and California commercial property, where risk complexity exceeds standard treaty terms.
Reinsurance Carriers Market Segmentation
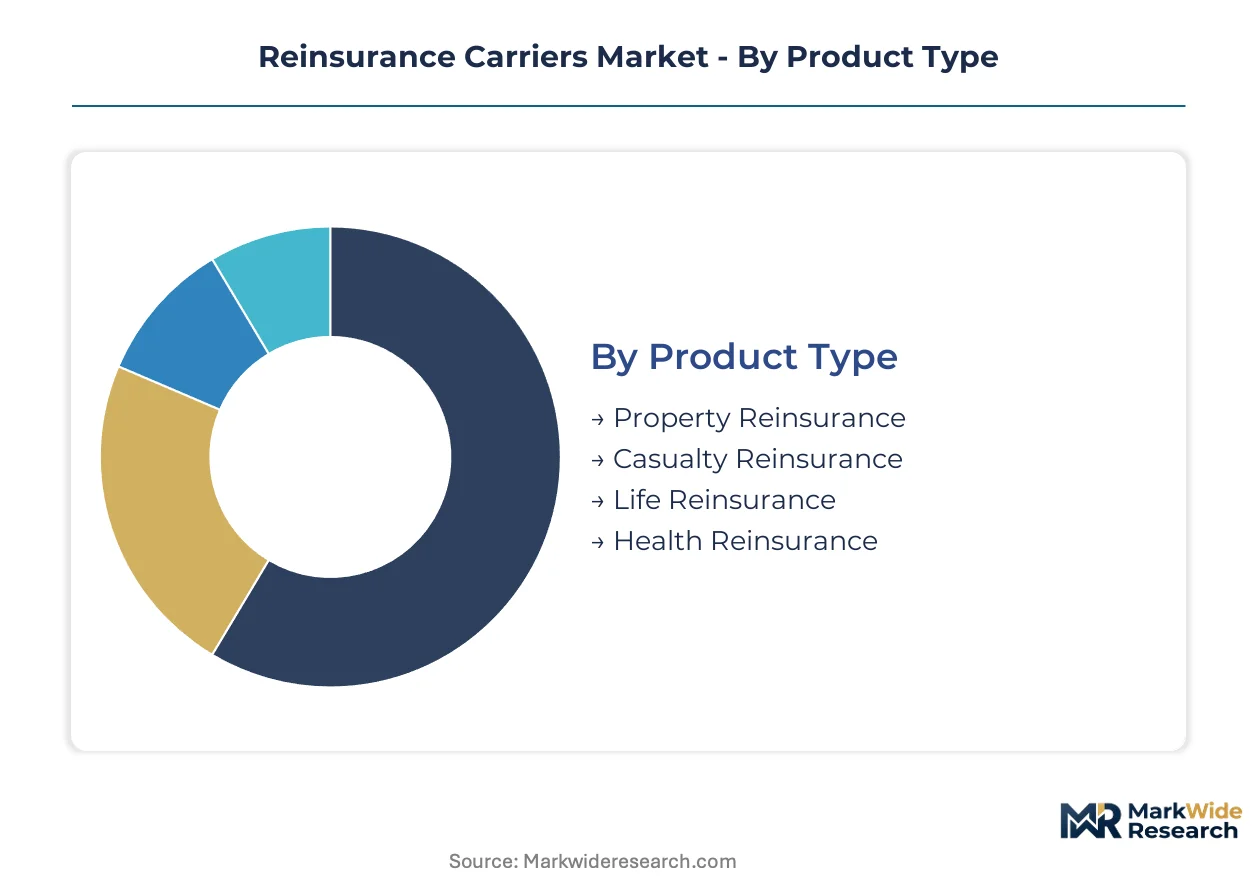
Reinsurance carriers structure their offerings across multiple dimensions that determine capital deployment, pricing methodologies, and client relationship intensity. Each segmentation axis reveals distinct margin profiles and regulatory treatment that shape competitive positioning.
Product Type:
Property reinsurance commands the largest premium volume as climate volatility intensifies frequency-severity dynamics, while life and health lines generate fee income with different capital intensity profiles.
- Property Reinsurance:Covers wind, flood, earthquake, and fire exposures through catastrophe treaties and per-risk excess layers. Demand concentrates in Florida, Texas, and California coastal zones where primary insurers face modeled severity escalation and regulatory pressure to maintain solvency margins.
- Casualty Reinsurance:Encompasses liability, workers' compensation, and professional lines with long-tail reserving challenges. Social inflation in U.S. liability lines has eroded reserve adequacy, compressing capital availability for multi-year underwriting commitments.
- Life Reinsurance:Provides mortality and longevity risk transfer through coinsurance and modified coinsurance structures.
- Health Reinsurance:Covers medical expense and disability exposures, often through quota share arrangements with specialized health insurers.
Today's leader: Property Reinsurance. Tomorrow's challenger: Life Reinsurance as pension de-risking accelerates longevity swap demand.
Client Type:
Insurers dominate ceded premium flows, though captive formation and government risk pools are expanding alternative demand channels with distinct contracting terms.
- Insurers:Primary carriers ceding risk to optimize capital efficiency under Solvency II and risk-based capital frameworks. European cedents in Germany, France, and Italy lead proportional treaty purchases to manage regulatory charges.
- Captives:Bermuda and Vermont domiciled vehicles accessing reinsurance markets through fronting arrangements. Corporate risk managers leverage captives to retain predictable layers while transferring peak exposures.
- Governments:Sovereign catastrophe pools and public risk financing entities seeking aggregate stop-loss protection.
- Corporates:Large enterprises purchasing finite risk and structured solutions outside traditional insurance channels.
Insurers retain the deepest treaty relationships. Captives are climbing the fastest as corporate risk retention strategies mature.
Service Type:
Treaty arrangements generate recurring premium streams through automatic coverage mechanisms, while facultative placements command higher margins for complex risks outside standard terms.
- Facultative:Individual risk placement for commercial properties exceeding treaty capacity or falling outside coverage definitions. Mid-sized U.S. property insurers now channel substantial facultative premium through digital placement platforms aggregating capacity from multiple reinsurers.
- Treaty:Automatic coverage for predictable risk volumes through quota share, surplus share, or excess of loss structures. Treaty administration platforms from legacy systems impede real-time data exchange, delaying bordereaux processing.
- Proportional:Quota share and surplus share arrangements where reinsurer participates in premium and losses proportionally.
- Non-Proportional:Excess of loss and stop-loss structures providing catastrophic layer protection.
Treaty structures anchor premium volume. Facultative placements are expanding most quickly as digital distribution fragments traditional broker channels.
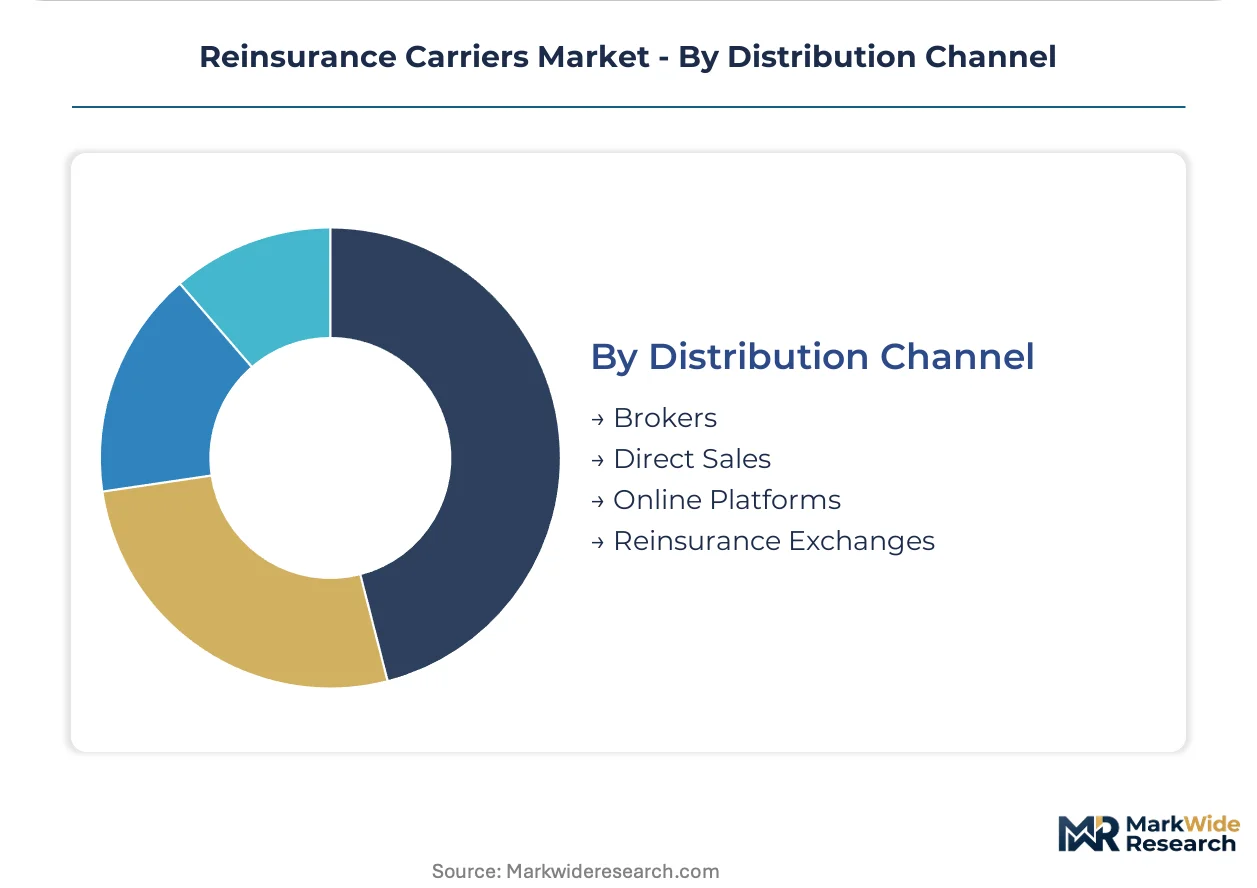
Distribution Channel:
Brokers intermediate the majority of premium placement, though direct sales and digital platforms are compressing frictional costs for standard treaty renewals.
- Brokers:Traditional intermediaries providing market access, placement negotiation, and claims advocacy. Lloyd's brokers in London and wholesale brokers in New York dominate complex commercial risk placement.
- Direct Sales:Reinsurer-cedent relationships bypassing intermediary commission for large treaty renewals. Munich Re and Swiss Re leverage century-long direct client relationships to sustain pricing power.
- Online Platforms:Digital placement systems aggregating capacity and streamlining quote comparison. Texas and California commercial property risks increasingly flow through these channels.
- Reinsurance Exchanges:Trading platforms facilitating standardized risk transfer and secondary market liquidity.
Brokers defend the core placement function. Online platforms represent the steepest expansion trajectory as algorithmic pricing penetrates standard treaty lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bermuda's concentration of insurance-linked securities vehicles and catastrophe modeling expertise anchors global reinsurance capacity for peak peril coverage.
United States
Florida, Texas, and California coastal property insurers are expanding catastrophe treaty purchases as modeled wind and flood severity trends accelerate. The National Association of Insurance Commissioners model law on credit for reinsurance determines whether U.S. cedents can recognize capital relief from non-admitted reinsurers. New York and Chicago host the largest broker intermediation clusters for complex commercial risk placement.
Bermuda
Alternative capital flows into ILS vehicles domiciled on the island are broadening capacity for peak peril coverage while compressing traditional pricing layers. The Bermuda Monetary Authority's insurance code and climate stress testing mandates reshape capital charges for unmodeled tail risks. Hamilton's concentration of catastrophe bond issuers and collateralized reinsurance vehicles attracts global risk transfer demand.
Switzerland
European cedents in Germany, France, and Italy lead proportional treaty purchases to manage Solvency II risk-based capital charges. FINMA's regulatory framework governs reinsurer solvency and cross-border market access. Zurich anchors global nat-cat modeling capabilities and serves as headquarters for carriers competing in complex agricultural and flood portfolios.
Singapore
Government risk pools and sovereign catastrophe financing entities in Southeast Asia seek aggregate stop-loss protection through Singapore-domiciled structures. The Monetary Authority of Singapore's regulatory sandbox facilitates parametric trigger innovation for satellite-based index settlement. The city-state's ILS fund managers pilot automated oracle-triggered payments for regional earthquake and windstorm indices.
United Kingdom
UK and Dutch pension funds are de-risking mortality exposure through longevity swaps, generating stable fee income for life reinsurance specialists. The Prudential Regulation Authority's climate stress testing mandates elevate capital charges for unmodeled tail risks. Lloyd's of London brokers dominate complex commercial risk placement and facultative channel fragmentation for Texas and California property risks.
Reinsurance Carriers Market Vendor Landscape
Global majors compete with regional champions across capital deployment sophistication and client relationship depth. The market structure concentrates around diversified multi-line carriers with century-long data archives, specialized mono-line underwriters occupying casualty or life niches, and alternative capital vehicles disrupting peak peril pricing. Three strategic archetypes dominate: integrated reinsurance groups with proprietary modeling capabilities, ILS-focused managers leveraging third-party capital, and state-affiliated carriers with domestic market privileges. Competitive moves center on portfolio diversification into cyber and longevity lines, plus fronting arrangements that access primary insurance cash flows through captive vehicles.
Within the integrated reinsurance tier, Munich Re, Swiss Re, and Hannover Re exemplify distinct specialization patterns. Munich Re represents the diversified property-catastrophe archetype with direct client relationships sustaining pricing power. Swiss Re occupies the technical modeling position, anchoring global nat-cat capabilities that differentiate agricultural and flood offerings. Hannover Re exemplifies the long-tail casualty specialist, where underwriting discipline and reserve adequacy determine franchise value in liability lines eroded by social inflation.
| Leading Market Players |
|---|
| Munich Re |
| Swiss Re |
| Hannover Re |
| Berkshire Hathaway |
| SCOR |
| Reinsurance Group of America |
| Everest Re |
| Renaissance Re |
| China Reinsurance Group |
| Others |
Supply Flow & Price Mechanics
Traditional treaty capacity and collateralized ILS layers diverge sharply in capital cost structures, with this bifurcation compressing pricing for peak peril coverage while elevating collateral posting burdens for non-admitted carriers competing in U.S. property lines. The resulting tiered cost dynamics reshape how reinsurers domicile, structure collateral trusts, and allocate capital between Bermuda-domiciled ILS vehicles and European balance-sheet carriers.
Pricing Analysis
Input-cost pass-through from catastrophe model licensing and stochastic simulation infrastructure flows directly into treaty pricing, with RMS and AIR Worldwide model fees embedded in carrier expense ratios. Price differentiation rests on proprietary data archive depth and direct cedent relationship tenure, with century-long incumbents commanding premium layers while alternative capital compresses standard treaty rates. Pricing pressure stems from ILS capacity inflows into Bermuda collateralized structures, squeezing traditional carriers in Florida and California wind portfolios. Price sensitivity concentrates among mid-sized U.S. property insurers optimizing ceded premium ratios under state risk-based capital frameworks.
Supply Chain Analysis
Certification gating through Solvency II equivalence determinations and NAIC model law compliance restricts carrier market access, with Bermuda, Switzerland, and Singapore domiciles dominating ILS issuance and collateralized reinsurance capacity. Raw material dependencies center on catastrophe modeling software licenses, satellite-based parametric index data feeds, and actuarial talent pools concentrated in London and Zurich. Supply chain risk manifests in single-source vulnerability to RMS and AIR Worldwide model updates that reset pricing assumptions across peak peril portfolios. Distribution runs through Lloyd's brokers in London, wholesale intermediaries in New York, and emerging digital placement platforms aggregating capacity for Texas and California commercial property facultative risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reinsurance carriers market functions as a stable compounder anchored by climate volatility-driven demand for peak peril capacity, with treaty premium flows exhibiting low cyclicality relative to primary insurance underwriting cycles.
For Market Incumbents: Acquire proprietary catastrophe modeling capabilities and geospatial analytics talent pools to defend pricing power against ILS compression. Consolidate facultative broker relationships in Texas and California commercial property channels where digital platforms fragment traditional placement workflows. Invest in Solvency II-compliant structured solutions to capture European cedent capital efficiency mandates. For New Entrants and Emerging Players: Enter via cyber reinsurance white space where silent cyber exposure in property treaties and standalone capacity shortages create technical differentiation opportunities. Target longevity swap structuring for UK and Dutch pension fund de-risking mandates, leveraging parametric trigger expertise from Singapore regulatory sandbox programs. Deploy fronting arrangements through Vermont and Bermuda captive formations to access primary insurance cash flows. For Investors and Strategic Acquirers: Consolidation pressure builds where social inflation erodes long-tail casualty reserve adequacy and compresses capital availability for multi-year underwriting commitments. Life reinsurance specialists with longevity swap structuring capabilities represent priority acquisition archetypes given pension de-risking demand durability. Monitor Bermuda Monetary Authority climate stress testing mandate implementation as inflection signal for capital charge recalibration across peak peril portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Trigger Product Development | Automated satellite-based settlement reduces loss adjustment latency for agricultural and windstorm portfolios. |
| ILS Vehicle Formation | Bermuda-domiciled collateralized structures access alternative capital flows compressing traditional pricing layers. |
| Cyber Risk Modeling Investment | Granular scenario capabilities address silent cyber exposure and standalone capacity shortages in treaty portfolios. |
| Longevity Swap Structuring | UK and Dutch pension fund de-risking generates fee income independent of property-catastrophe underwriting cycles. |
| Digital Facultative Platform Integration | Mid-sized U.S. property insurer channel fragmentation creates broker relationship consolidation opportunities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reinsurance underwriting executives, catastrophe modeler technical leads, cedent risk management officers, and ILS fund portfolio managers with secondary validation. Secondary sources encompassed NAIC credit for reinsurance model law filings, Bermuda Monetary Authority insurance code disclosures, Solvency II regulatory technical standards, and Lloyd's market bordereaux processing data. Bottom-up treaty premium estimates by line and domicile triangulated against top-down macroeconomic capital flow indicators.
Segment-weighting approaches applied product type, client type, service type, and distribution channel dimensions across the projection horizon. CAGRs derived from stochastic simulation of modeled loss frequency trends, alternative capital inflow assumptions, and regulatory capital charge evolution. Industry-specific forecast inputs incorporated climate stress testing mandate implementation timelines and parametric trigger adoption curves in agricultural portfolios.
Inputs from regulatory filing databases and broker placement platform disclosures were available through the study window; gaps in proprietary cedent treaty term specifics introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding Solvency II equivalence maintenance and NAIC model law adoption consistency across U.S. states. A model refresh is warranted upon material change in Bermuda Monetary Authority climate stress testing capital charge calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Japan Parametric Insurance Market
Insurance
China Liability Insurance Market
Insurance
Property Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Art Insurance Market
Insurance
United States Bancassurance Market
Insurance
Cargo Insurance Market
Insurance
Reinsurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
India Online Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Aviation Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
United Kingdom Car Insurance Market