
 Africa Insurance Market | 2026-2036
Africa Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Insurance Market Intelligence
Mobile-first premium collection is broadening access beyond traditional branch networks. Sanlam Group leverages its bancassurance partnerships to sustain penetration in underserved rural municipalities. Old Mutual Limited anchors its competitive position through proprietary digital underwriting platforms. Discovery Limited differentiates via behavior-linked health products that integrate wearable data streams.
Insurance constitutes a risk-transfer mechanism where policyholders pay premiums in exchange for promise of indemnity against specified losses, with pricing calibrated through actuarial mortality tables, catastrophe modeling, and investment income projections. Life Insurance dominates premium volumes across Southern and East Africa, while Health Insurance captures expanding margin pools as national health systems remain underfunded. Online Platforms represent the fastest-growing distribution vector, though Agents still control last-mile penetration in peri-urban zones.
Kenya's Insurance Regulatory Authority enforces capital adequacy ratios and consumer protection standards that shape product design and market entry. South Africa's Financial Sector Conduct Authority governs market conduct and disclosure frameworks that dictate distribution compliance costs. Nigeria's National Insurance Commission mandates local retention requirements that influence reinsurance placement strategies. Stakeholders must monitor how regulatory divergence across national supervisors affects cross-border portfolio consolidation.
Market Dynamics
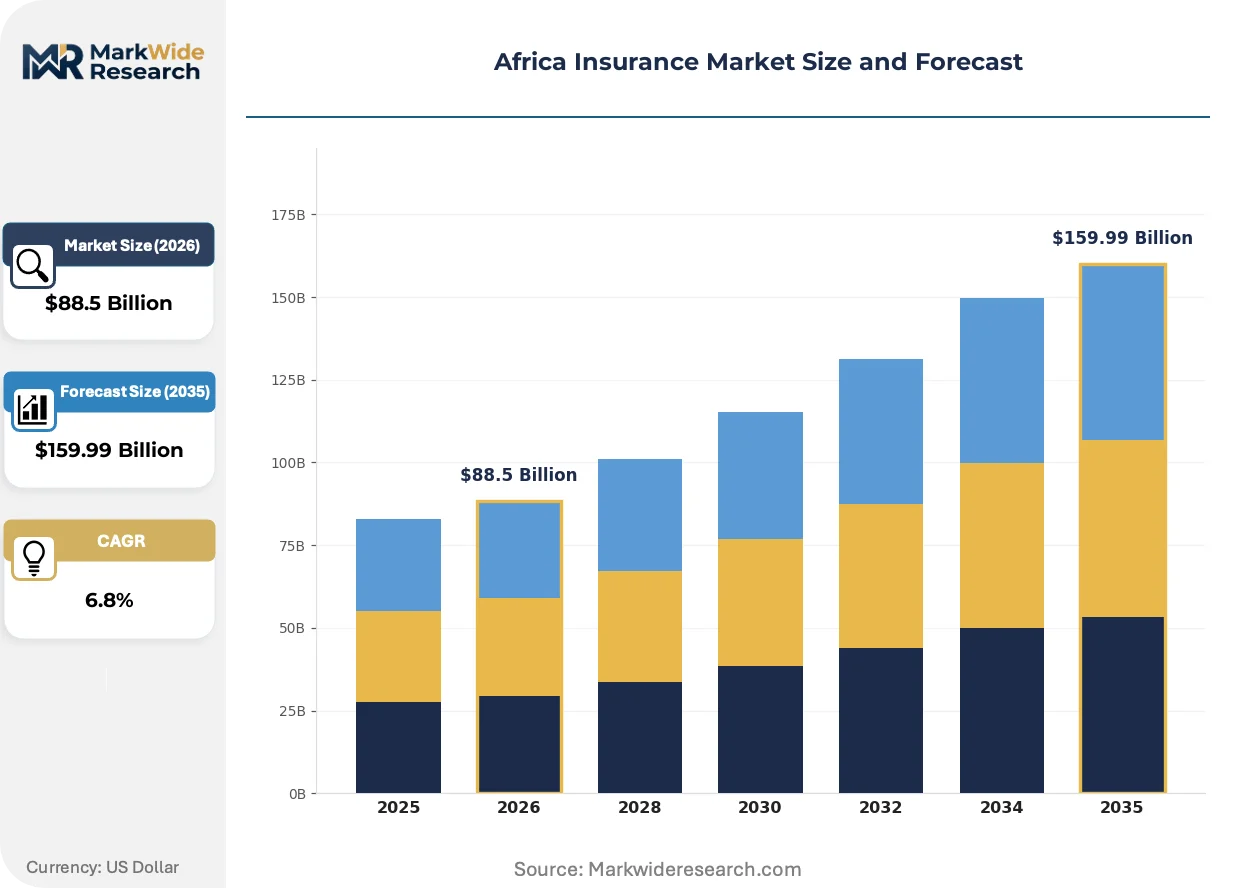
Mobile-first premium collection is converging with bancassurance mandates to restructure distribution economics across East and Southern Africa, compressing agent-dependent acquisition costs while expanding addressable populations beyond branch networks.
Growth Catalysts
- Kenya's IRA Bancassurance Mandate:Regulatory pressure forces banks to offer insurance products at point of sale, embedding coverage into routine financial transactions for informal sector workers previously excluded from formal channels.
- Parametric Weather Indexing:Satellite-triggered payouts eliminate claims adjustment delays for smallholder farmers, accelerating adoption of crop and livestock microinsurance across drought-exposed regions.
- Lagos Digital Corridor Concentration:Nigeria's southwestern urban cluster aggregates demand for API-integrated distribution platforms, enabling insurers to bypass legacy agent networks in Africa's most populous insurance market.
Market Restraints
- Reinsurance Capacity Squeeze:Global reinsurers restrict African treaty capacity following climate loss accumulation, forcing primary carriers to retain more catastrophe exposure or accept punitive pricing.
- Illiquid Long-Duration Liabilities:Local bond markets lack sufficient duration-matched instruments for life insurers to immunize guaranteed return products against interest rate volatility.
- Agent Commission Bloat:First-year commission structures consume 40-60% of premium in traditional channels, eroding embedded value and distorting product design toward high-surrender instruments.
Strategic Opportunities
- Ethiopia's Liberalization Window:The opening of Africa's second-most populous market to foreign insurers creates first-mover advantages in a jurisdiction with sub-1% penetration and state-dominated incumbents.
- Behavior-Linked Health Convergence:Wearable data streams enable dynamic pricing models that reward physical activity, differentiating coverage in South Africa's competitive medical scheme landscape.
- Informal Sector Aggregation Platforms:Cooperatives and savings groups in Tanzania and Uganda present embedded distribution channels for simplified term life and funeral products with minimal underwriting friction.
Industry Challenges
- Actuarial Talent Scarcity:Qualified mortality and morbidity modelers remain concentrated in South Africa and Kenya, constraining product development capacity in francophone and lusophone markets.
- Legacy Policy Administration Systems:Core systems built for conventional products resist reconfiguration for usage-based or parametric offerings, delaying digital product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Insurance Market |
| Market Size in 2026 | $88.5 Billion |
| Market Size in 2035 | $159.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Distribution Channel: Agents, Brokers, Direct Sales, Online Platforms Customer Type: Individuals, Small Businesses, Corporates, Institutions Coverage Type: Comprehensive, Third-Party, Basic, Optional Add-Ons |
| Companies Covered | Santam Limited, AIICO Insurance, Sanlam Group, Britam Holdings, AXA Mansard Insurance, Old Mutual Limited, Jubilee Holdings, Leadway Assurance Company Limited, Discovery Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Insurance Market Strategic Shifts & Innovations
Digitization is compressing distribution layers while regulatory mandates accelerate bancassurance penetration, creating structural pressure on traditional agent networks across multiple jurisdictions simultaneously.
Artificial intelligence underwriting engines are converging with alternative data sources including mobile money transaction histories and geospatial crop health indices. Insurers in Kenya and Nigeria deploy these tools to score informal sector applicants previously deemed uninsurable. The technology is converging with traditional risk assessment to collapse decision timelines from weeks to minutes.
South Africa's Financial Sector Conduct Authority has tightened disclosure frameworks for funeral and credit-linked products, mandating plain-language benefit illustrations and cooling-off period extensions. The regulation compresses mis-selling margins and elevates compliance costs for distributors. Microinsurance specialists are responding by unbundling product components and shifting toward direct digital acquisition to control disclosure sequencing.
Demand is rotating from bundled annual policies toward modular, pay-as-you-go coverage triggered by specific events or usage periods. Ride-hail drivers in Lagos and Nairobi purchase daily motor cover through mobile wallets rather than conventional annual contracts. This pattern is most visible in urban gig economy corridors where income volatility makes lump-sum premium payments prohibitive.
Africa Insurance Market Segmentation
Insurance markets fragment across risk transfer mechanisms, distribution economics, and buyer sophistication levels. Understanding these fault lines reveals where capital deploys most efficiently and which customer cohorts drive premium expansion.
Product Type:
Customization intensity varies from commoditized short-tail lines to bespoke long-duration contracts with embedded guarantees and investment components.
- Life Insurance:Long-duration contracts bundle mortality protection with savings or investment elements, requiring actuarial reserves matched to local bond market duration. Southern African carriers dominate premium volumes through group schemes and funeral products targeting informal sector households.
- Health Insurance:Medical schemes reimburse hospital and outpatient costs where national health systems leave coverage gaps. South Africa's medical scheme landscape absorbs the bulk of regional health premium as Discovery Limited and others compete on behavior-linked pricing models.
- Property Insurance:Short-tail contracts covering fire, theft, and natural perils with annual renewal cycles. Kenyan and Nigerian carriers concentrate here as mortgage lending and commercial real estate expansion accelerates.
- Liability Insurance:Professional indemnity and product liability coverage protecting against third-party claims. Penetration remains shallow outside South Africa's mature corporate market.
Most installed capacity flows through Life Insurance. Expansion is steepest in Health Insurance.
Distribution Channel:
Cost-to-serve economics separate high-touch relationship channels from automated acquisition at scale.
- Agents:Commission-based representatives control last-mile penetration in peri-urban zones where trust barriers persist. Kenya's Insurance Regulatory Authority bancassurance mandate is compressing traditional agent economics by embedding coverage at bank points-of-sale.
- Brokers:Independent intermediaries serve corporate accounts with complex risk placement and reinsurance negotiation needs. Lagos and Johannesburg brokerages dominate commercial placement across the continent.
- Direct Sales:Insurer-employed sales forces target standardized products through phone and branch networks. Old Mutual Limited and Sanlam Group maintain captive direct channels for mass-market penetration.
- Online Platforms:API-integrated digital distribution enables instant quoting and mobile wallet premium collection. Nigerian digital corridors and Kenyan mobile money ecosystems are accelerating adoption fastest.
Most premium volume currently runs through Agents. Online Platforms are gaining share fastest.
Customer Type:
Risk sophistication and purchasing power determine product complexity and service intensity requirements.
- Individuals:Retail buyers purchasing personal lines through agents, bancassurance, or mobile platforms. East African informal sector workers drive microinsurance deepening through cooperatives and savings groups.
- Small Businesses:SMEs seeking packaged coverage for property, liability, and key-person risks. Fragmented demand across Tanzania and Uganda creates aggregation opportunities for simplified term products.
- Corporates:Large enterprises with dedicated risk managers negotiating tailored programs and captive alternatives. South African and Nigerian mining, energy, and financial services sectors anchor commercial premium pools.
- Institutions:Government agencies, NGOs, and multilateral organizations procuring specialized coverage. Parametric weather indexing for agricultural development programs exemplifies this segment.
Most underwriting capacity serves Corporates. Individuals represent the steepest expansion trajectory.
Coverage Type:
Benefit breadth trades off against premium affordability across buyer segments.
- Comprehensive:All-risk protection with broad peril coverage and high sum insured limits. South African medical schemes and commercial property programs concentrate here.
- Third-Party:Minimum legal coverage protecting against liability to others. Motor third-party dominates regulatory minimum markets across East and West Africa.
- Basic:Stripped-down policies covering named perils only with capped benefits. Funeral insurance and hospital cash plans exemplify this tier for mass-market penetration.
- Optional Add-Ons:Modular extensions riders attaching to base contracts. Critical illness riders on life policies and personal accident extensions on motor coverage illustrate this flexibility.
Most policy count flows through Basic coverage. Optional Add-Ons are climbing the fastest as carriers unbundle components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors insurance demand concentration across West Africa, with its digital corridor aggregating API-integrated distribution platforms that bypass legacy agent networks in Nigeria's most populous market.
South Africa
Discovery Limited and Old Mutual Limited dominate premium volumes through proprietary digital underwriting platforms and behavior-linked health products. The Financial Sector Conduct Authority governs market conduct and disclosure frameworks that elevate compliance costs. Johannesburg's financial district concentrates actuarial talent and reinsurance negotiation capacity.
Kenya
Mobile-first premium collection expands addressable populations beyond traditional branch networks for informal sector workers. The Insurance Regulatory Authority mandates bancassurance expansion to deepen penetration and enforce capital adequacy ratios. Nairobi's tech ecosystem incubates parametric weather indexing startups serving smallholder farmers.
Nigeria
AXA Mansard Insurance and Leadway Assurance Company Limited compete for share in a market with sub-1% penetration and concentrated urban demand. The National Insurance Commission mandates local retention requirements that influence reinsurance placement strategies. Lagos corridor density enables insurers to bypass legacy agent networks through mobile wallet integration.
Ethiopia
Liberalization of Africa's second-most populous market creates first-mover advantages for foreign entrants against state-dominated incumbents. The country's national insurance regulator establishes entry frameworks for bancassurance partnerships. Addis Ababa's banking sector presents embedded distribution channels for simplified term life products.
Tanzania
Cooperatives and savings groups present aggregation platforms for funeral products with minimal underwriting friction. The country's national financial services authority supervises microinsurance deepening among informal sector workers. Dar es Salaam's port corridor concentrates commercial property demand as mortgage lending accelerates.
Africa Insurance Market Key Industry Players
Global majors compete with regional champions across distribution economics and digital underwriting capabilities. The vendor base structures around South African diversified financial services groups, Nigerian composite insurers, and Kenyan specialist health and life carriers. Three archetypes dominate: integrated bancassurance operators, mobile-first microinsurance platforms, and proprietary health data analytics specialists. Competitive moves concentrate on strategic partnerships with mobile money providers and portfolio diversification into parametric agricultural products.
Within the integrated financial services tier, Sanlam Group and Old Mutual Limited exemplify diversified operators leveraging bancassurance partnerships and captive direct channels for mass-market penetration. Discovery Limited occupies a distinct position among behavior-linked health specialists, differentiating through wearable data integration. Santam Limited anchors the short-tail property and casualty segment with concentrated presence in Southern African commercial lines.
| Leading Market Players |
|---|
| Santam Limited |
| AIICO Insurance |
| Sanlam Group |
| Britam Holdings |
| AXA Mansard Insurance |
| Old Mutual Limited |
| Jubilee Holdings |
| Leadway Assurance Company Limited |
| Discovery Limited |
| Others |
Cost & Logistics Intelligence
Premium-to-basic coverage bifurcation separates South Africa's behavior-linked medical schemes from East Africa's stripped-down funeral products, with that divergence manifesting in both commission-loaded pricing tiers and distribution infrastructure investments across divergent regulatory environments.
Pricing Analysis
Reinsurance treaty costs pass through to primary carrier pricing, compressing margins on catastrophe-exposed property lines while life insurers absorb duration mismatch penalties from illiquid local bond markets. Three-tier pricing structure across premium, standard, and economy levels reflects capital adequacy requirements, distribution channel economics, and actuarial talent concentration. Pricing pressure stems from mobile-first platforms collapsing acquisition costs in Kenya and Nigeria. Informal sector buyers exhibit highest price sensitivity, while South African corporate schemes tolerate premium loading for integrated wellness benefits.
Supply Chain Analysis
Bancassurance partnerships and mobile money integrations handle mass-market premium collection, displacing traditional agent networks in high-density urban corridors. Actuarial capacity concentrates in South Africa, Kenya, and Nigeria, while reinsurance capacity draws from London, Bermuda, and Singapore markets. Satellite data feeds, mobile transaction histories, and wearable biometric streams constitute critical input dependencies. Single-source vulnerability sits with global reinsurers restricting African treaty capacity. Distribution runs through API-integrated platforms, bank branch networks, and residual agent channels in peri-urban zones.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethiopia's sub-1% penetration against Kenya's IRA-mandated bancassurance expansion creates a regulatory-arbitrage window where first-mover licensing costs in Addis Ababa undercut Nairobi's compliance-burdened economics by a substantial margin.
For Market Incumbents: Deploy proprietary digital underwriting platforms to defend against mobile-first entrants collapsing acquisition timelines. Sanlam Group and Old Mutual Limited should deepen bancassurance exclusivity with tier-1 banking partners to lock out challenger distribution. Reinforce actuarial talent pipelines through targeted recruitment from South African universities to offset scarcity-driven compensation inflation. For New Entrants and Emerging Players: The premium-economy price-point gap in Nigerian health insurance creates entry space for modular, pay-as-you-go products bypassing annual contract structures. Target Lagos corridor gig economy workers through mobile wallet integration with ride-hail and delivery platforms. Capture Tanzania's cooperative-savings-group channel with simplified funeral products requiring minimal underwriting infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mobile-first microinsurance platforms possessing embedded distribution through M-Pesa or similar mobile money ecosystems. Long-term viability hinges on regulatory accommodation of alternative data underwriting across multiple jurisdictions. Watch for parametric weather indexing adoption rates among development finance institutions as the inflection signal for agricultural line scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Bancassurance Partnership Expansion | Embedding coverage at bank point-of-sale deepens penetration in Kenya's IRA-mandated market. |
| Parametric Product Development | Satellite-triggered payouts eliminate claims delays for drought-exposed smallholder farmers. |
| Mobile Wallet Integration | API-connected premium collection bypasses legacy agent networks in Lagos digital corridors. |
| Behavior-Linked Health Convergence | Wearable data streams enable dynamic pricing differentiation in South Africa's medical scheme landscape. |
| Ethiopia Market Entry | Liberalization window creates first-mover positioning against state-dominated incumbents. |
Research Approach
Multiple input streams — executive interviews with insurance regulatory authority officials, actuarial directors at composite carriers, and mobile money platform strategists — were reconciled against regulatory filings from Kenya's IRA, Nigeria's NAICOM, and South Africa's FSCA, plus reinsurance treaty disclosure documents and microinsurance performance databases. Primary fieldwork with distribution channel heads and bancassurance partnership managers supplemented secondary validation. Bottom-up policy count modeling and top-down premium aggregation were cross-checked for consistency.
Data-stream reconciliation across product type, distribution channel, customer segment, and coverage tier dimensions produced volume and value trajectories over the projection horizon. CAGRs were derived from trend extrapolation of mobile penetration rates, bancassurance attachment ratios, and informal sector aggregation platform adoption. Forecast inputs included regulatory mandate implementation timelines, reinsurance capacity allocation shifts, and mobile money transaction volume growth curves.
The model assumes a particular technology adoption path; alternative pathways for AI underwriting engines or parametric satellite triggers would alter the outlook if regulatory frameworks delay approval or data infrastructure proves insufficient. Forecasts reflect base-case assumptions regarding capital adequacy enforcement consistency and mobile network reliability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Entertainment Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Solar Panel Warranty Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Global Livestock Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Endowment Insurances Market
Insurance
EV Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Small Business Insurance Market
Insurance
Property Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Income Protection Insurance Market