
 Asia-Pacific Mobile Phone Insurance Market | 2026-2036
Asia-Pacific Mobile Phone Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mobile Phone Insurance Market Analytics
Subscription-based device protection is broadening the addressable market beyond traditional point-of-sale policies. Assurant Inc. leverages its carrier partnerships across Japan and South Korea to sustain recurring premium flows. Bajaj Allianz anchors its growth on direct-to-consumer digital distribution in India, while Samsung Electronics Co., Ltd. competes through integrated care programs bundled with flagship handset sales.
Asia-Pacific mobile phone insurance covers financial loss from physical damage, theft, and malfunction of cellular devices, with policies typically specifying repair cost caps, replacement timelines, and deductible tiers based on device retail value. Its commercial purpose centers on reducing consumer replacement friction and locking handset purchasers into multi-year carrier relationships. Screen Protection leads policy attachment rates at retail due to high-frequency claims, while Theft Coverage generates the strongest premium per unit among Premium-tier subscribers. Online Platforms now capture the fastest-growing distribution share as insurers bypass traditional broker networks.
India's IRDAI mandates solvency margins for non-life underwriters, while Australia's ASIC enforces disclosure standards for add-on insurance sold at retail. Japan's FSA supervises carrier-embedded product structures to prevent anti-competitive bundling. Stakeholders must monitor how data-localization requirements across ASEAN jurisdictions reshape claims-processing architecture and partner selection.
Market Dynamics
Corporate fleet managers across Asia-Pacific now bundle device protection into mobility contracts, shifting buyer composition from individual consumers to enterprise procurement desks and lengthening policy lifecycles.
Growth Catalysts
- India's PLI Scheme:Electronics manufacturing incentives expand local device assembly, growing the insurable base of domestically produced handsets. Tier-two and tier-three cities see first-time smartphone penetration deepen.
- Carrier-embedded distribution:Mobile network operators in Japan and South Korea integrate insurance at point of activation, reducing consumer friction and capturing subscribers at contract inception.
- Screen Protection attachment:High-frequency damage claims at retail drive policy bundling, with repair cost caps aligning consumer willingness-to-pay with premium pricing.
Market Restraints
- Data-localization mandates:ASEAN jurisdictions impose server-residency requirements for claims data, forcing insurers to re-architect processing infrastructure and raising compliance overhead.
- Replacement cycle extension:Device durability improvements and software longevity compress replacement frequency, reducing new-policy origination volumes in mature markets like Australia.
- ASIC disclosure standards:Australia's retail add-on insurance rules lengthen sales scripts and cooling-off periods, increasing acquisition costs for point-of-sale distribution.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:First-time smartphone users outside major metros lack insurance awareness, creating whitespace for direct-to-consumer digital education campaigns.
- Online platform distribution:Insurers bypass traditional broker networks through e-commerce partnerships, capturing faster-growing share with lower commission structures.
- IRDAI solvency framework:India's capital adequacy rules favor well-capitalized underwriters, creating consolidation tailwinds for compliant domestic players.
Industry Challenges
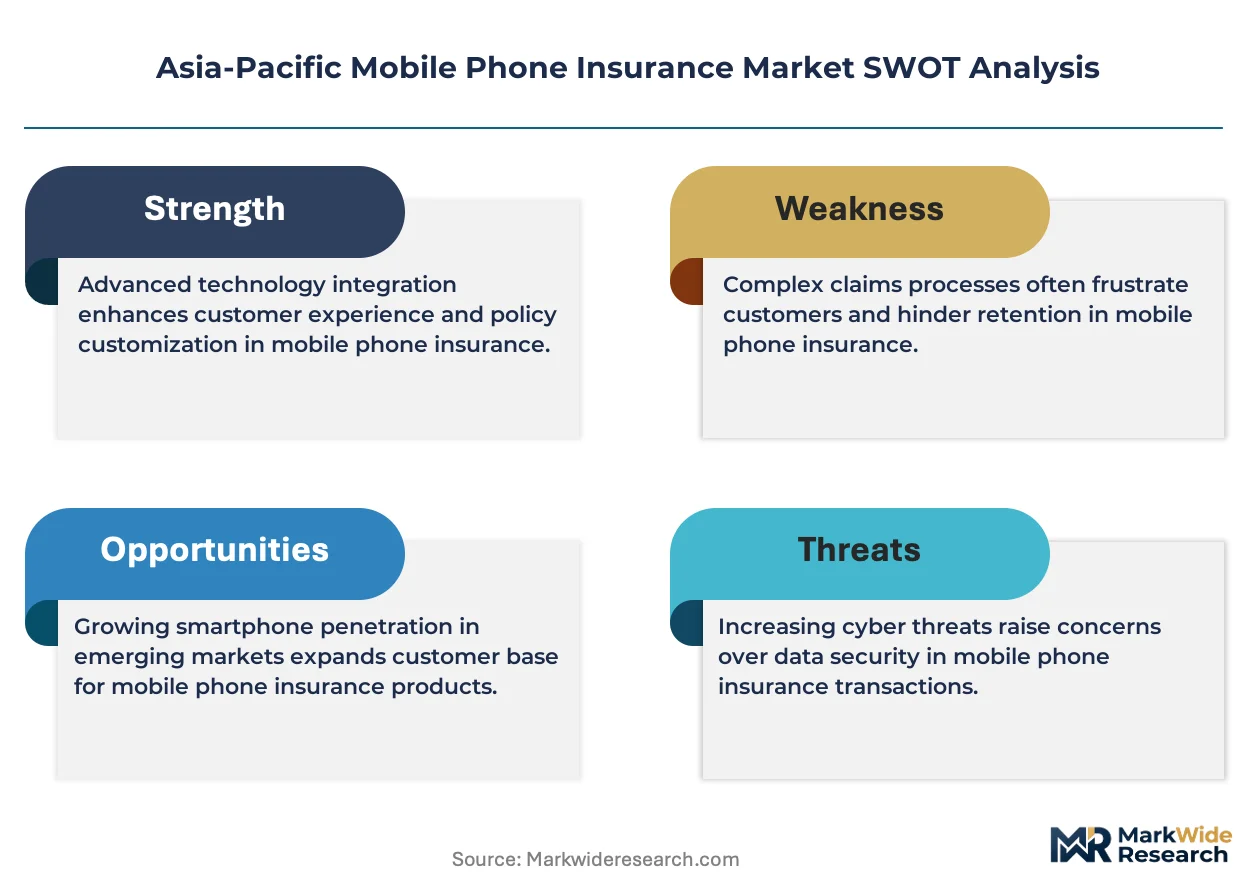
- Fraud detection capability gaps:Synthetic identity schemes and staged damage claims outpace manual verification workflows, requiring AI investment that strains mid-tier balance sheets.
- Legacy carrier system integration:API compatibility between insurer platforms and operator billing systems fragments across Japan's NTT docomo, KDDI, and SoftBank environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mobile Phone Insurance Market |
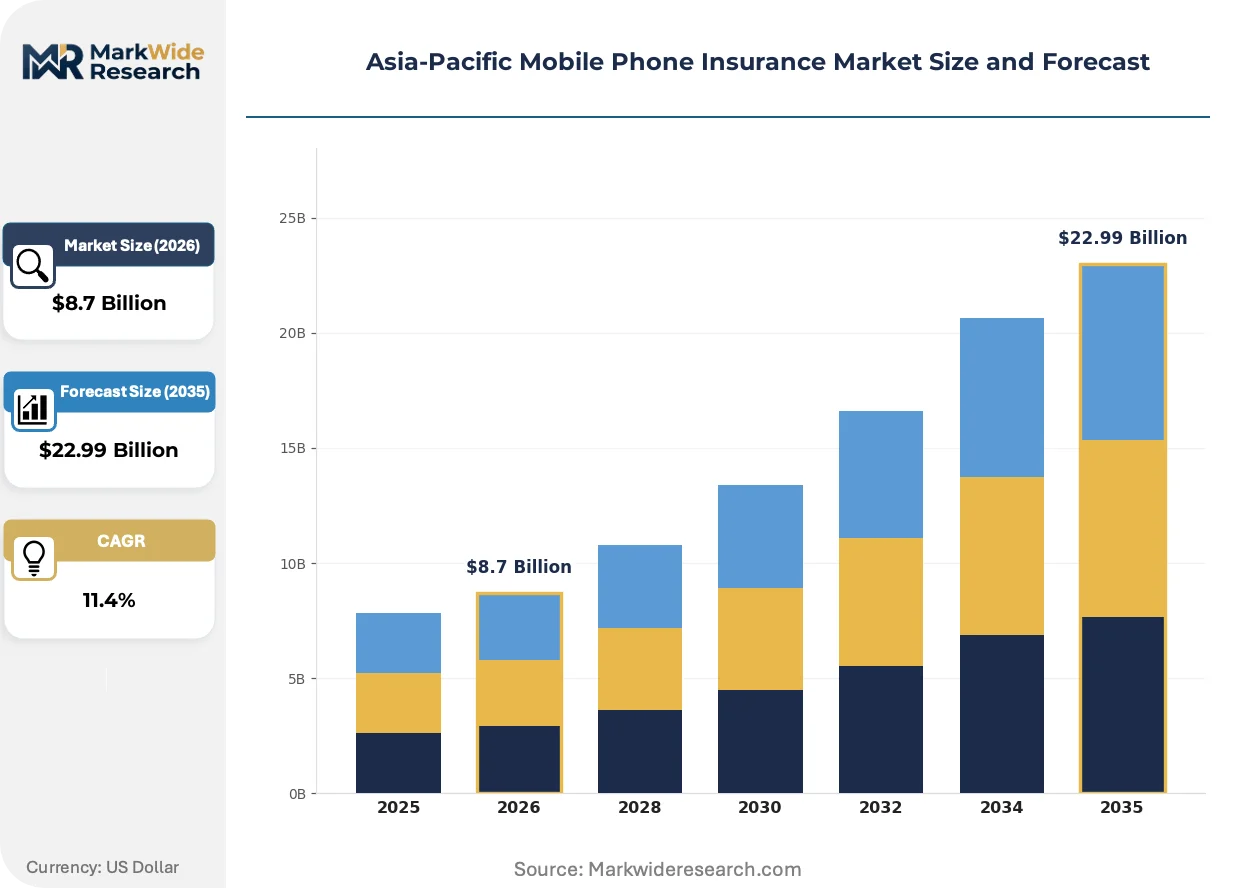
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screen Protection, Accidental Damage, Theft Coverage, Liquid Damage End User: Individual Consumers, Small Businesses, Corporates, Retailers Distribution Channel: Online Platforms, Retail Stores, Mobile Carriers, Insurance Brokers Premium Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Allianz Group, AIG, Assurant Inc., Asurion, Apple Inc., Samsung Electronics Co., Ltd., Bajaj Allianz, Safeware Inc., Warranty Asia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mobile Phone Insurance Market Evolving Landscape
Digital-first distribution models and embedded finance architectures are compressing policy origination timelines while expanding addressable segments beyond traditional retail attach points.
Telematics-enabled risk assessment is decentralizing underwriting authority from centralized actuarial teams to real-time device sensor data. Flagship handset manufacturers embed accelerometer and gyroscope diagnostics that detect drop events and liquid exposure automatically. Regional underwriters in South Korea and Australia pilot usage-based pricing that adjusts premiums to actual device handling patterns rather than static retail value tiers.
Japan's FSA carrier-embedded product supervision prevents anti-competitive bundling by mandating standalone policy availability. This regulatory architecture forces insurers to maintain dual distribution capabilities—embedded and direct—raising operational complexity but preserving consumer choice. Premium-tier subscribers respond by demanding unbundled Theft Coverage with higher per-unit premiums, shifting revenue mix toward high-margin segments.
Enterprise procurement desks now negotiate multi-year device protection as a standalone line item in mobility contracts, unbundling insurance from hardware lease rates. This purchasing pattern displaces individual consumer decision-making with centralized fleet management platforms. India's corporate sector exhibits the strongest momentum, where IT departments standardize protection across heterogeneous device fleets spanning Samsung, Apple, and domestic brands.
Asia-Pacific Mobile Phone Insurance Market Segmentation
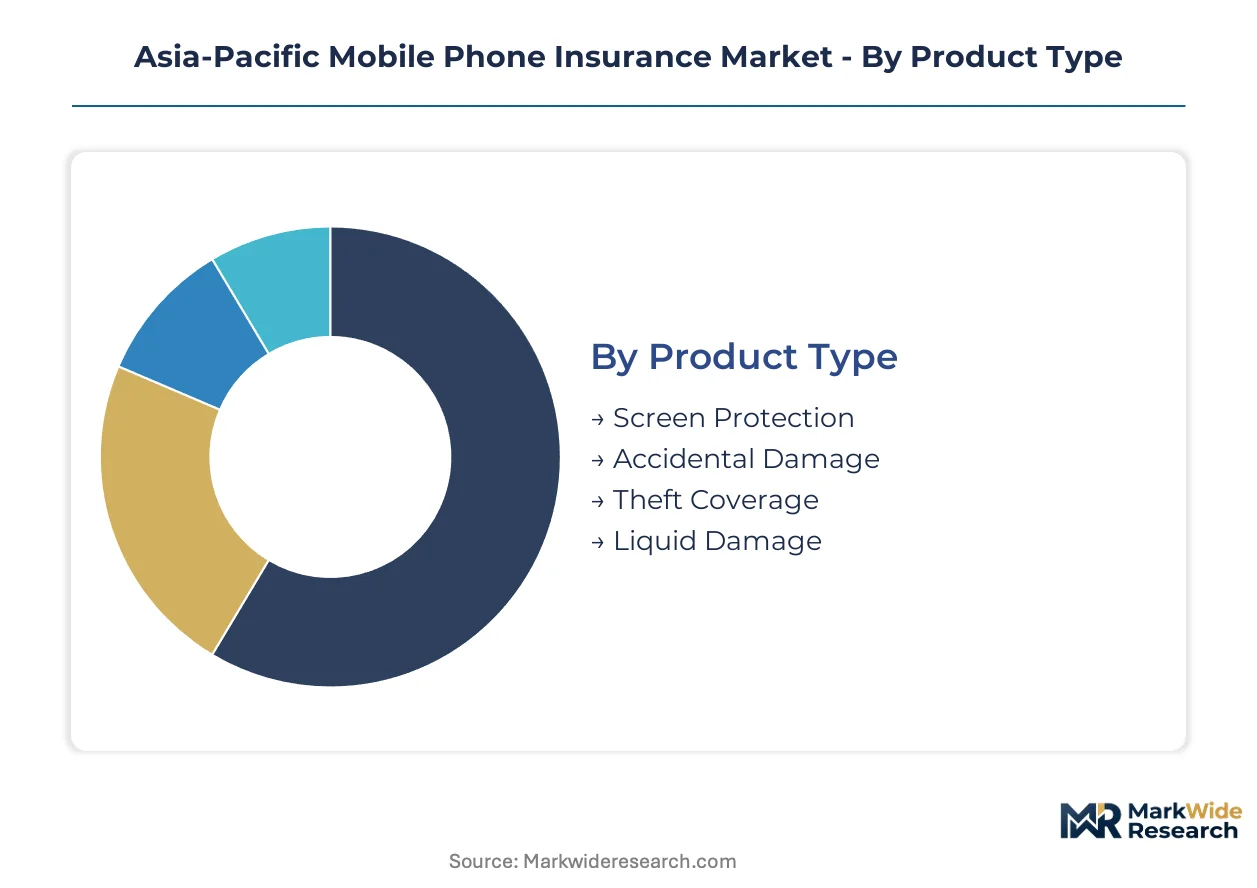
Segmentation in Asia-Pacific mobile phone insurance reveals how product design, buyer type, and channel economics interlock. Understanding these splits helps underwriters allocate capital across divergent risk profiles and distribution cost structures.
Product Type:
Standalone policies dominate high-frequency claims segments, while bundled offerings integrate lower-severity protections into carrier contracts.
- Screen Protection:Covers cracked display repairs with predefined cost caps and expedited turnaround commitments. India's tier-two cities drive attachment as first-time smartphone users prioritize visible damage mitigation over comprehensive coverage.
- Theft Coverage:Provides full device replacement upon verified police reporting and claim authentication. Premium-tier subscribers in South Korea and Japan generate the strongest per-unit economics due to higher device valuations and lower fraud incidence.
- Accidental Damage:Encompasses drop, impact, and pressure-related failures beyond screen-specific coverage. Small business procurement desks in Australia favor this mid-tier protection for field-deployed employee devices.
- Liquid Damage:Addresses corrosion and circuit failures from moisture exposure, with diagnostic thresholds varying by manufacturer warranty overlap. Southeast Asian humidity patterns elevate baseline claim frequency in Vietnam and Indonesia.
Screen Protection leads volumes today; Theft Coverage is gaining share fastest.
End User:
Cost tier segmentation separates price-sensitive individual purchasers from enterprise buyers negotiating fleet-scale terms.
- Individual Consumers:Single-device purchasers activating coverage at retail or through carrier channels. India's direct-to-consumer digital platforms capture this segment with simplified underwriting and instant policy issuance.
- Corporates:Fleet managers negotiating multi-year device protection as standalone contract line items. IT departments standardize coverage across heterogeneous device pools spanning multiple manufacturers and operating systems.
- Small Businesses:Owner-operated entities with 5-50 device fleets lacking dedicated procurement infrastructure. Brokers in Australia serve this segment through packaged business owner policies combining property and equipment coverage.
- Retailers:Merchant protection programs covering demonstration units, employee devices, and customer-facing transaction hardware. Japanese electronics chains embed this coverage into vendor-managed inventory arrangements.
Individual Consumers anchor premium volume; Corporates are expanding most quickly.
Distribution Channel:
Volume concentration tracks digital infrastructure maturity and carrier market structure across the region.
- Mobile Carriers:Point-of-activation embedding at contract inception, prevalent in Japan and South Korea's concentrated operator markets. NTT docomo, KDDI, and SoftBank environments require API-compatible insurer integration.
- Online Platforms:E-commerce partnerships and direct insurer websites bypassing traditional broker commissions. India's Bajaj Allianz leverages this channel for scalable customer acquisition outside tier-one metros.
- Retail Stores:Point-of-sale attachment at electronics merchants and manufacturer flagship locations. Samsung Electronics Co., Ltd. integrates care programs here with flagship handset transactions.
- Insurance Brokers:Independent intermediaries serving commercial accounts and complex multi-device placements. Australia's ASIC disclosure standards lengthen sales processes but preserve advisory relationships.
Mobile Carriers dominate policy origination; Online Platforms show the steepest expansion trajectory.
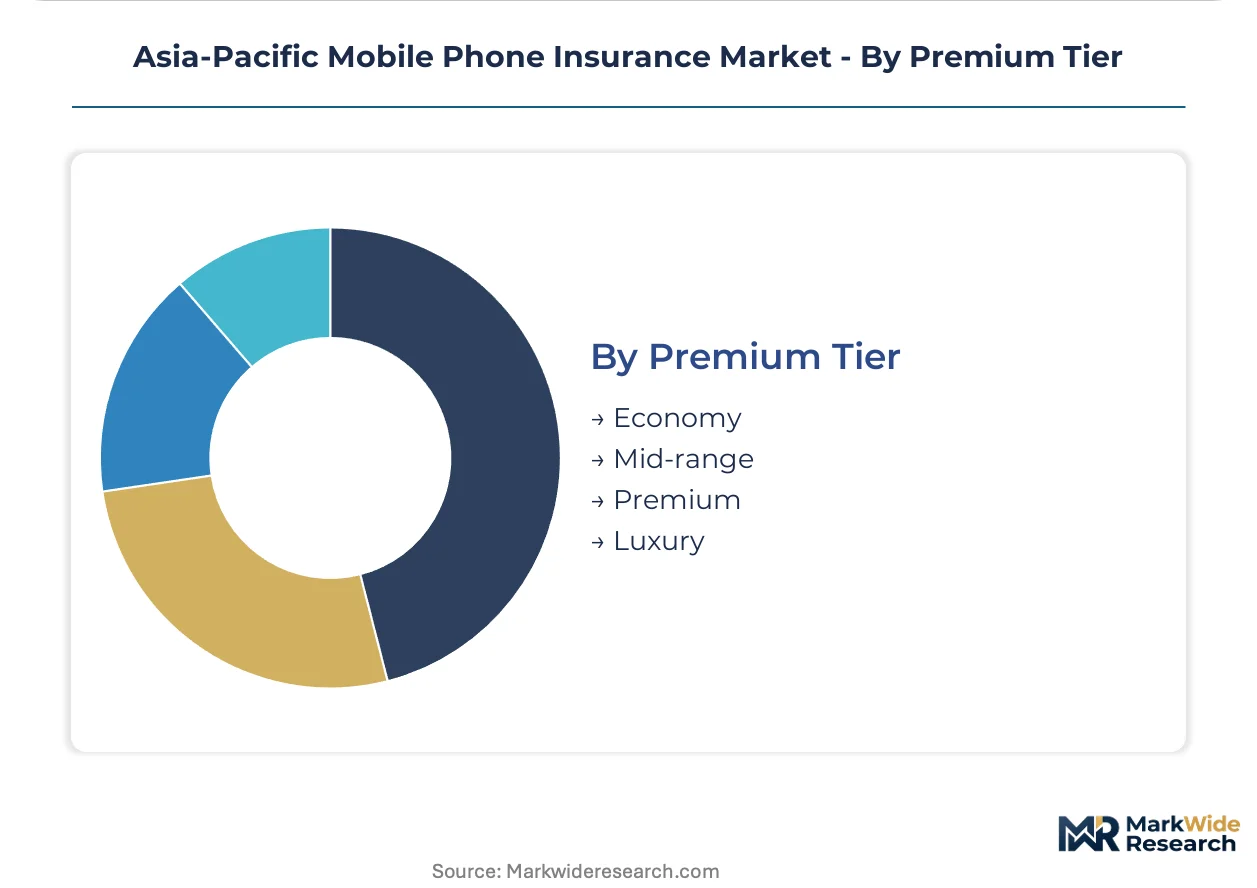
Premium Tier:
Margin structure stratifies across device retail value bands with corresponding deductible and service level differentiation.
- Premium:Flagship smartphone coverage with express replacement, international protection, and zero-deductible screen repair options. Assurant Inc. sustains recurring flows through carrier partnerships at this tier in Japan and South Korea.
- Economy:Entry-level device protection with capped repair benefits and extended replacement timelines. India's PLI scheme expands the insurable base of domestically assembled handsets qualifying for this tier.
- Mid-range:Balanced coverage for devices occupying the $300-600 retail band, the largest volume segment across Southeast Asia. Vietnamese and Indonesian first-time buyers concentrate here.
- Luxury:Ultra-premium device protection including concierge claims handling and bespoke replacement sourcing. Limited to specialized broker placements and manufacturer-direct programs.
Premium tier generates the highest margin per policy; Economy tier is climbing the fastest on volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme accelerates domestic device assembly faster than Australia's replacement cycle extension slows policy origination, creating divergent growth trajectories across the region.
India
First-time smartphone users in tier-two and tier-three cities deepen penetration outside metropolitan centers. The IRDAI mandates solvency margins for non-life underwriters, favoring well-capitalized domestic players. Maharashtra and Gujarat host expanding electronics manufacturing clusters where locally assembled handsets enlarge the insurable base.
Japan
Carrier-embedded distribution at NTT docomo, KDDI, and SoftBank captures subscribers at contract inception with minimal friction. The FSA supervises product structures to prevent anti-competitive bundling while mandating standalone policy availability. Tokyo anchors premium-tier recurring premium flows through established insurer-operator partnerships.
South Korea
Telematics-enabled risk assessment pilots usage-based pricing tied to accelerometer and gyroscope diagnostics. The MFDS framework intersects with consumer protection standards for device-linked financial products. Seoul Capital Area concentrates flagship handset ownership where Assurant Inc. sustains embedded carrier relationships.
Australia
ASIC disclosure standards for retail add-on insurance lengthen sales scripts and cooling-off periods, elevating acquisition costs. Small business procurement desks in Sydney and Melbourne favor mid-tier accidental damage coverage for field-deployed employee devices. Replacement cycle extension compresses new-policy origination as device durability improves.
Vietnam
First-time smartphone users outside Ho Chi Minh City and Hanoi lack insurance awareness, creating whitespace for direct-to-consumer digital education. Humidity patterns elevate baseline liquid damage claim frequency compared to temperate markets. Da Nang and emerging manufacturing zones see rising mid-range device adoption without corresponding protection penetration.
Asia-Pacific Mobile Phone Insurance Market Competitive Landscape
Top-tier vendors anchor carrier-embedded distribution, while mid-tier specialists pursue online platform bypass strategies. The market exhibits tiered concentration with global underwriters, domestic insurers, and manufacturer-integrated programs occupying distinct positions. Three archetypes dominate: multinational insurance groups with regional carrier partnerships, domestic digital-first underwriters leveraging direct distribution, and electronics manufacturers bundling care programs with hardware sales. Competitive moves center on API integration with operator billing systems and geographic expansion into underpenetrated Southeast Asian markets.
Among multinational insurance groups, Allianz Group and AIG represent established presence across multiple Asia-Pacific jurisdictions through diversified product portfolios. Assurant Inc. exemplifies the carrier-partnership archetype with sustained recurring premium flows in Japan and South Korea. Bajaj Allianz occupies a position within the domestic digital-first tier, leveraging direct-to-consumer distribution for scalable acquisition outside India's tier-one metros. Samsung Electronics Co., Ltd. anchors manufacturer-integrated competition through care programs bundled with flagship handset transactions.
| Leading Market Players |
|---|
| Allianz Group |
| AIG |
| Assurant Inc. |
| Asurion |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Bajaj Allianz |
| Safeware Inc. |
| Warranty Asia |
| Others |
Value Network & Pricing Analysis
Enterprise procurement desks negotiating multi-year fleet protection contracts are compressing premium margins and forcing underwriters to restructure cost allocation across repair networks and claims processing infrastructure. This buyer consolidation trend rewards insurers with captive service capabilities and penalizes those dependent on third-party repair aggregators.
Pricing Analysis
Capacity additions in India's electronics manufacturing zones are reshaping price floors for economy-tier coverage as locally assembled handsets expand the insurable base. Three-tier pricing structure across premium, mid-range, and economy levels segments buyers by device retail value and service level expectations. Price differentiation centers on repair turnaround commitments and deductible thresholds rather than coverage breadth alone. Cost compression in the economy tier is intensifying because domestic assembly under PLI incentives expands supply without corresponding demand sophistication.
Supply Chain Analysis
Single-source vulnerability sits with centralized claims processing platforms concentrated in Singapore and Hong Kong data centers. Repair parts sourcing draws from China, South Korea, and Taiwan for display assemblies and logic boards. Logistics chokepoints at ASEAN customs checkpoints delay replacement device fulfillment. Distribution runs through carrier-embedded billing systems in Japan and South Korea, direct-to-consumer platforms in India, and retail electronics chains across Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific mobile phone insurance functions as a stable compounder anchored by structural device penetration in underpenetrated Southeast Asian markets and recurring premium flows from carrier-embedded distribution in mature economies.
For Market Incumbents: To counter fraud detection capability gaps that strain manual verification workflows, invest in AI-powered claims authentication and accelerometer-based damage verification. API integration with NTT docomo, KDDI, and SoftBank billing systems preserves carrier-embedded distribution control against digital-first challengers. For New Entrants and Emerging Players: Capture whitespace in Vietnam and Indonesia where first-time smartphone users outside Ho Chi Minh City and Hanoi lack insurance awareness. Direct-to-consumer digital education campaigns bypass established broker networks and carrier relationships that dominate mature markets. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic digital-first underwriters leveraging IRDAI-compliant capital structures for consolidation tailwinds in India. The 5-10 year viability window favors platforms with integrated repair networks over pure underwriting plays. Watch telematics-enabled risk assessment adoption in South Korea as an inflection indicator for usage-based pricing migration across the region.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration | Accelerometer diagnostics enable usage-based pricing pilots in Seoul and Sydney. |
| Direct-to-Consumer Platform Launch | Bajaj Allianz demonstrates scalable acquisition outside India's tier-one metros. |
| Carrier API Standardization | Unified billing integration reduces fragmentation across Japan's operator environments. |
| Repair Network Captive Buildout | In-house service capabilities defend margin position against third-party aggregators. |
| Enterprise Fleet Contract Expansion | Standalone protection line items in mobility contracts lengthen policy lifecycles. |
Research Methodology
Bottom-up device protection modeling reconciled against top-down carrier partnership tracking forms the analytical core of this study. Primary interviews with insurance product managers, mobile network operator partnership leads, electronics retail category buyers, and corporate IT procurement officers combined with secondary validation from IRDAI solvency filings, ASIC disclosure registries, Japan FSA carrier supervision reports, and ASEAN data-localization compliance databases. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of policy origination volumes and premium retention rates established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, distribution channel, and premium tier. CAGRs were derived from fitted growth curves applied to device penetration forecasts and insurance attachment rate assumptions. Telematics adoption curves and PLI scheme production targets served as industry-specific forecast inputs.
Regulatory enforcement shifts, fraud detection technology adoption, and carrier partnership consolidation are the dominant revision risks to the outlook presented. Forecasts reflect assumptions about device replacement cycles, digital distribution penetration, and enterprise fleet standardization that may require adjustment as these variables evolve. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Bancassurance in ASEAN Market
Insurance
Peer to Peer Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Agricultural Insurance Market
Insurance
AI in Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
China Group Health Insurance Market
Insurance
Fire Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Europe Entertainment Insurance Market