
 MENA Health and Medical Insurance Market | 2026-2036
MENA Health and Medical Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Health and Medical Insurance Market Foresight
Comprehensive coverage tiers are rotating toward higher benefit limits and wider provider networks across the Gulf. Bupa Arabia leverages its specialized focus on Saudi corporate clients to sustain premium retention. Tawuniya anchors the largest insured population in the Kingdom through extensive government-linked contracts. Daman dominates Abu Dhabi's mandatory scheme, controlling access to the emirate's dominant hospital network.
Health and medical insurance in MENA constitutes risk-pooling financial instruments covering hospitalization, outpatient treatment, pharmaceuticals, and preventive care against premium payments, with policy terms typically specifying annual benefit ceilings, co-payment ratios, and network exclusivity clauses. Coverage type segments reveal a structural divergence: comprehensive plans capture the dominant share of premium value in the Gulf, while basic mandatory coverage saturates regulatory-minimum enrollment pools. Provider type dynamics show private insurers leading product innovation and network breadth, whereas hybrid models combining public oversight with private administration gain traction in markets seeking cost containment without full privatization.
Saudi Arabia's Council of Health Insurance enforces compulsory coverage for nationals and expatriates, while the UAE's health authorities mandate employer-sponsored schemes in Dubai and Abu Dhabi; Qatar's national health insurance framework similarly requires resident coverage through regulated private participation. These frameworks shape demand by criminalizing non-compliance, standardizing minimum benefits, and channeling enrollment toward approved insurer networks. Stakeholders must monitor evolving co-payment structures and network adequacy rules as Gulf states recalibrate cost-sharing between public budgets and private premium pools.
Market Dynamics
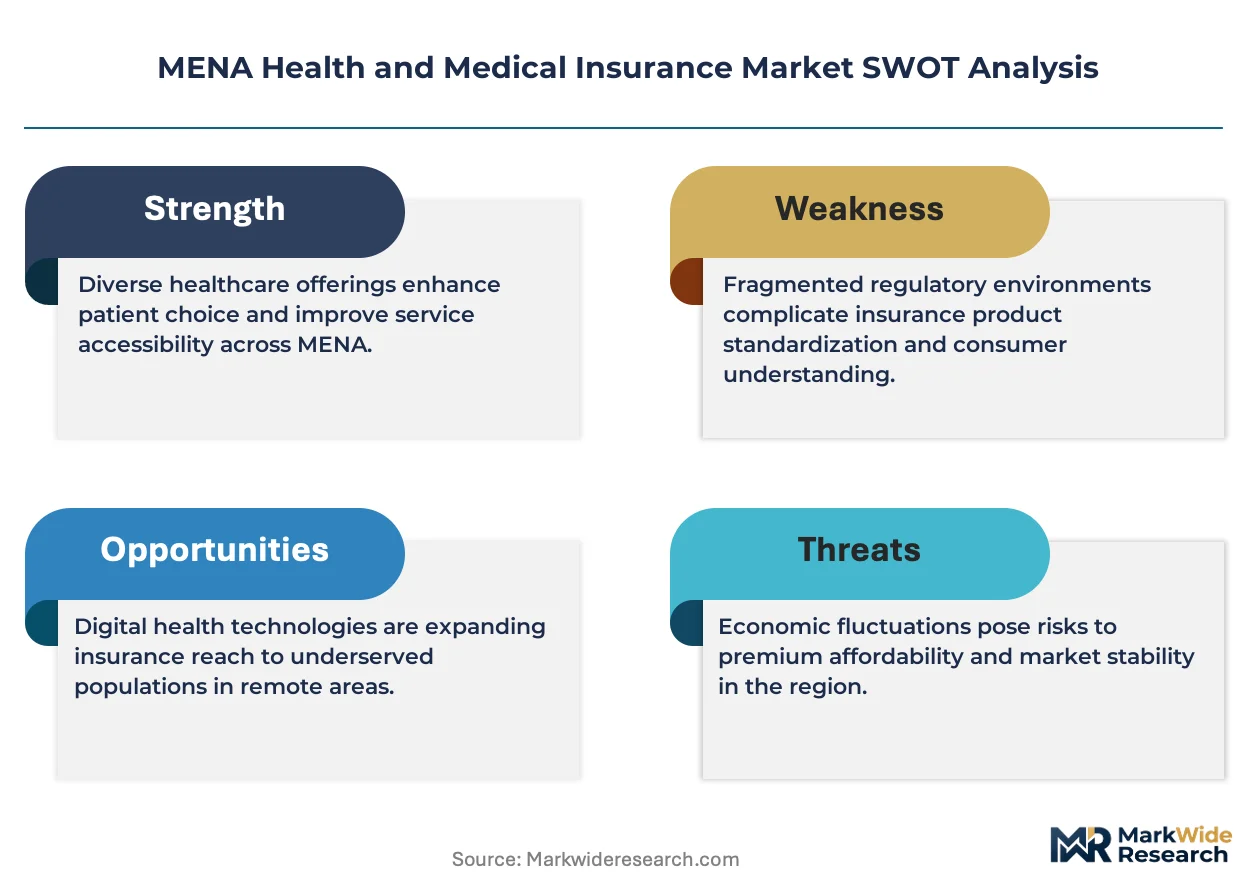
Mandatory employer-sponsored coverage frameworks across Gulf Cooperation Council states are compressing enrollment timelines and standardizing benefit floors, while private insurers race to differentiate through network breadth and digital service layers.
Growth Catalysts
- SFDA enforcement protocols:Saudi Arabia's Council of Health Insurance mandates criminal penalties for non-compliant employers, channeling millions of expatriate workers into approved private schemes.
- Expatriate workforce expansion:Construction, hospitality, and logistics sectors across the UAE and Qatar require bulk corporate coverage, sustaining premium volume in employer-sponsored pools.
- Telemedicine infrastructure:Remote consultation platforms are integrating with insurer apps, reducing outpatient cost ratios and expanding rural access beyond major hospital clusters.
Market Restraints
- Medical inflation differentials:Hospital service costs in Dubai and Abu Dhabi outpace premium adjustment cycles, squeezing combined ratios for comprehensive plan underwriters.
- Provider network concentration:Three hospital groups control over sixty percent of inpatient capacity in the UAE's northern emirates, limiting insurer negotiation leverage.
- Regulatory fragmentation:Separate health authorities in Dubai and Abu Dhabi maintain divergent minimum benefit schedules, complicating pan-emirate product design.
Strategic Opportunities
- Egypt's uninsured middle class:Private voluntary coverage penetration remains below fifteen percent outside Cairo and Alexandria, creating white space for digital-first distribution models.
- Chronic disease management bundles:Diabetes and cardiovascular care packages align with MOHAP preventive care incentives in Abu Dhabi, differentiating comprehensive tier offerings.
- Embedded insurance APIs:Banking and fintech platforms across Saudi Arabia are integrating health policy issuance into payroll and remittance workflows.
Industry Challenges
- Actuarial talent scarcity:GCC markets lack sufficient professionals trained in morbidity modeling for mixed-nationality risk pools, forcing reliance on external consulting capacity.
- Legacy core system integration:Established insurers struggle to connect decades-old policy administration platforms with real-time provider billing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Health and Medical Insurance Market |
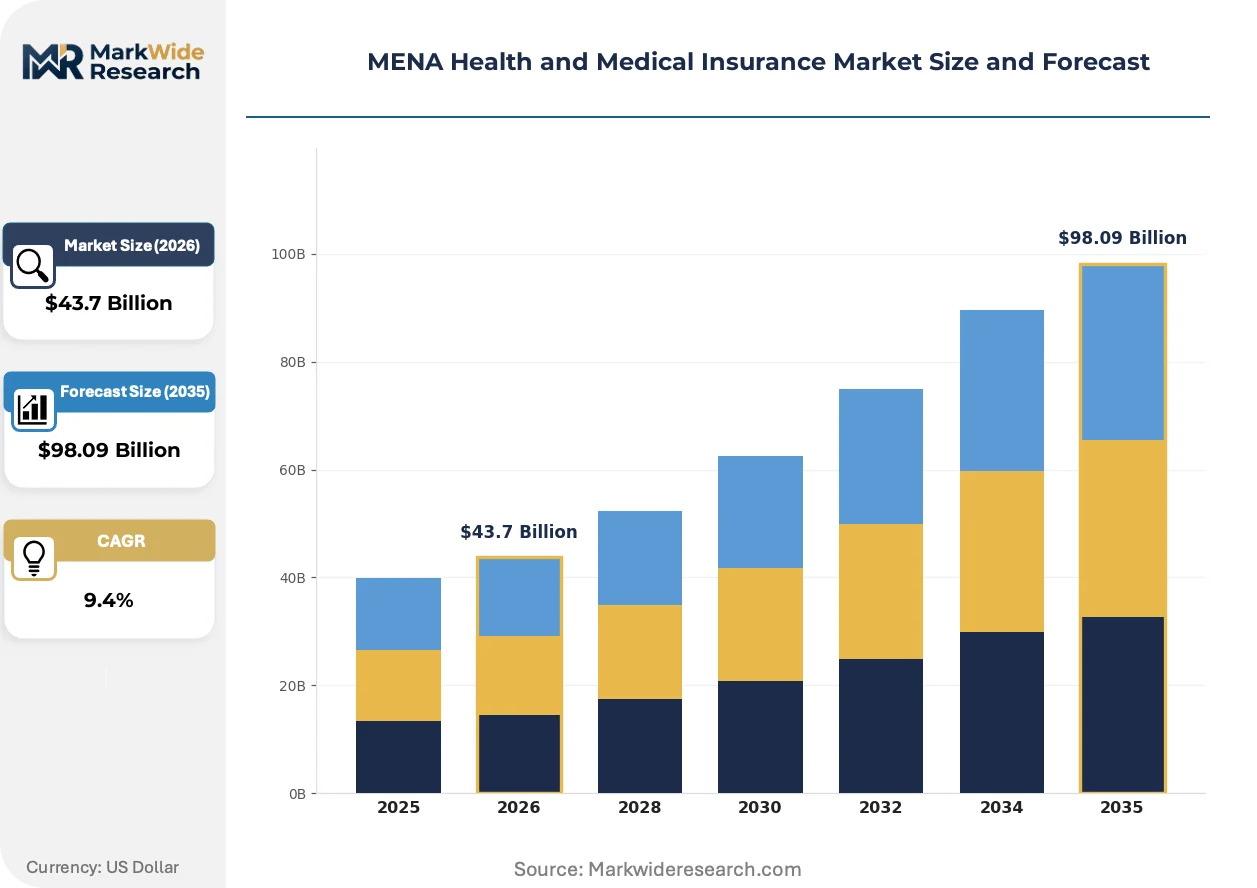
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $98.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Individual, Group, Family, Employer-Sponsored Coverage Type: Comprehensive, Basic, Supplemental, Catastrophic Provider Type: Private Insurers, Public Insurers, TPA, Hybrid Models Policy Duration: Short-Term, Long-Term, Annual, Lifetime |
| Companies Covered | Daman, Bupa Arabia, Tawuniya, MedGulf, GIG Gulf, AXA, Allianz, Oman Insurance Company, Qatar Insurance Company, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Health and Medical Insurance Market Shifts & Advancements
Digital distribution channels and AI-enabled claims processing are compressing operational cost structures across MENA insurance operations, while regulatory mandates continue elevating minimum benefit floors.
Claims automation platforms are bifurcating operational cost structures in the MENA insurance sector. Optical character recognition and natural language processing engines now process routine outpatient reimbursement requests without human intervention. Mid-sized insurers in Saudi Arabia and the UAE are adopting these systems fastest, shrinking administrative expense ratios while redirecting staff toward complex pre-authorization cases and network fraud detection.
MOHAP's mandatory health insurance scheme in Abu Dhabi continues tightening network adequacy standards for inpatient and emergency coverage. Insurers must now demonstrate geographic accessibility metrics within specified driving-time thresholds or face enrollment caps. This pressure is forcing Daman and competing administrators to expand hospital partnerships into Al Ain and western region facilities previously excluded from preferred networks.
Corporate procurement departments are consolidating broker relationships and demanding outcome-based performance guarantees from insurers. Large Saudi employers now tie renewal negotiations to measurable metrics including network satisfaction scores and claims turnaround times. This behavioral shift is most visible in Riyadh's banking and petrochemical sectors, where risk managers have centralized vendor selection authority previously held at divisional levels.
MENA Health and Medical Insurance Market Segmentation
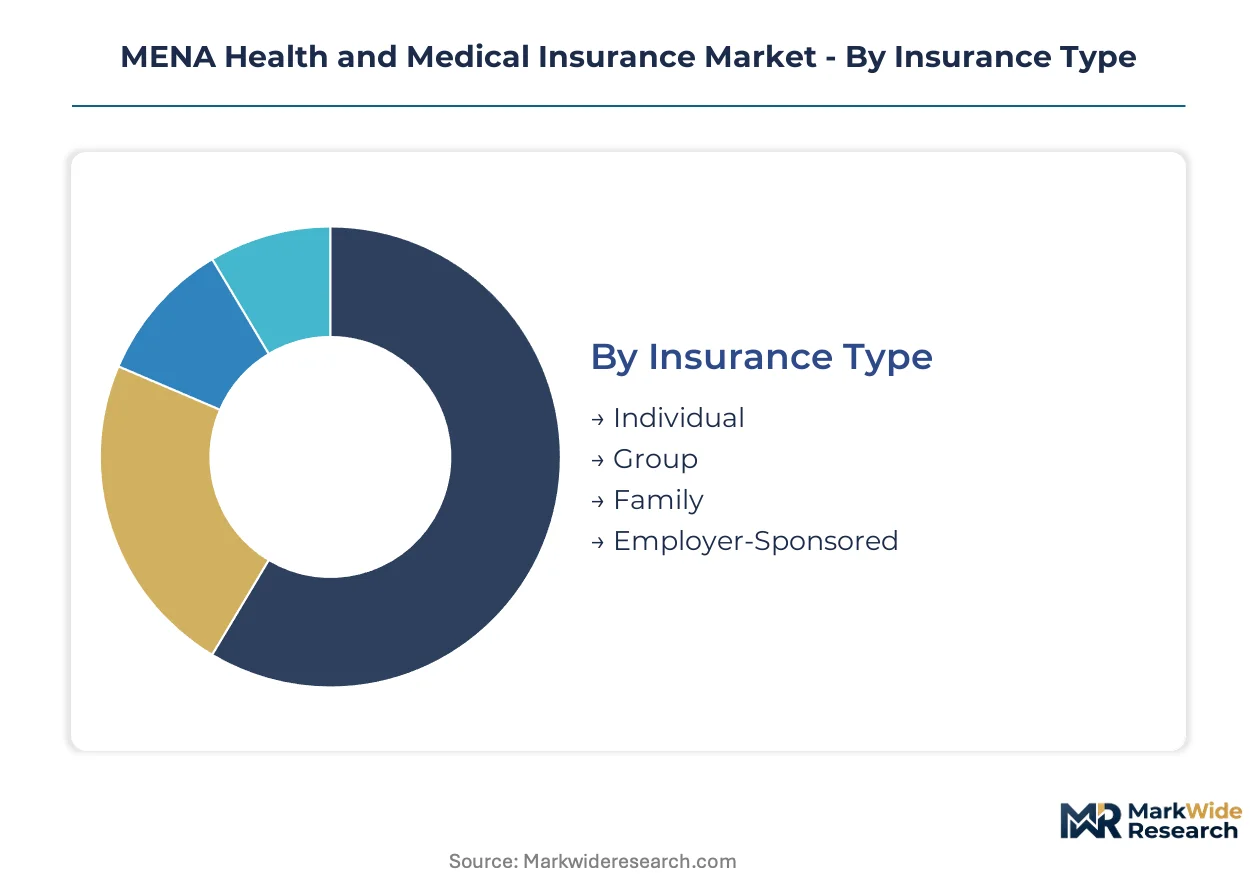
Segmentation in the MENA health insurance market reveals how regulatory mandates and workforce demographics split premium pools across distinct risk-bearing structures. Insurers design product architectures around employer obligation frameworks, coverage depth tiers, and administrative models that vary sharply between Gulf Cooperation Council states and North African markets.
Insurance Type:
Geographic distribution of demand varies sharply: employer-sponsored and group segments dominate Gulf markets with large expatriate workforces, while individual and family coverage concentrates in Egypt and Morocco where formal employment penetration remains lower.
- Individual:Self-purchased policies cover professionals, freelancers, and dependents outside corporate schemes. Demand clusters among Saudi nationals seeking enhanced benefits beyond mandatory employer coverage and Egyptian middle-class households in Cairo and Alexandria.
- Group:Bulk corporate contracts pool risk across employee bases, with construction and hospitality sectors in Qatar and the UAE driving volume. SFDA enforcement protocols in Saudi Arabia criminalize non-compliance, compressing enrollment timelines.
- Family:Multi-life policies bundle spouse and dependent coverage, appealing to mid-tier Saudi households and UAE residents seeking portability across emirates. Regulatory fragmentation between Dubai and Abu Dhabi complicates pan-emirate product design.
- Employer-Sponsored:Mandatory coverage frameworks in Saudi Arabia, the UAE, and Qatar channel expatriate workers into approved private schemes. This segment anchors premium volume across the Gulf.
Employer-sponsored coverage holds the largest share; momentum sits with group policies as corporate procurement departments consolidate broker relationships.
Coverage Type:
Cost tier stratification determines network access and claims ceilings, with comprehensive plans commanding premium pricing while basic coverage saturates regulatory minimum pools.
- Comprehensive:Extensive benefit limits cover hospitalization, outpatient treatment, pharmaceuticals, and preventive care with minimal co-payment exposure. Abu Dhabi's MOHAP scheme mandates network adequacy standards that force insurers to expand into Al Ain and western region facilities.
- Basic:Regulatory-minimum coverage satisfies mandatory enrollment laws with capped benefits and restricted provider networks. This tier saturates low-wage expatriate pools in Saudi Arabia and Qatar where employers seek cost containment.
- Supplemental:Gap-filling policies address dental, optical, and wellness services excluded from primary coverage. Demand is climbing the fastest among Saudi banking sector employees and UAE professionals seeking enhanced outpatient benefits.
- Catastrophic:High-deductible structures protect against severe illness and chronic disease complications. Diabetes and cardiovascular bundles align with MOHAP preventive care incentives, differentiating offerings in Abu Dhabi.
Comprehensive coverage holds the largest share; momentum sits with supplemental policies as employers expand voluntary benefit menus.
Provider Type:
Administrative model selection reflects market maturity and public-sector capacity, with hybrid structures gaining traction where governments seek cost containment without full privatization.
- Private Insurers:Commercial carriers lead product innovation and network breadth, competing on digital service layers and claims automation. Bupa Arabia and Tawuniya in Saudi Arabia leverage specialized corporate focus and government-linked contracts respectively.
- Public Insurers:State-backed schemes provide foundational coverage with subsidized premiums, prevalent in Egypt and Morocco where private penetration remains limited. These entities struggle with legacy core system integration.
- TPA:Third-party administrators handle claims processing and network management without bearing underwriting risk, expanding fastest in the UAE where Daman dominates Abu Dhabi's mandatory scheme.
- Hybrid Models:Public oversight combined with private administration channels enrollment toward regulated networks while containing fiscal exposure. Qatar's national health insurance framework exemplifies this approach.
Private insurers hold the largest share; momentum sits with hybrid models as Gulf states recalibrate cost-sharing between public budgets and private premium pools.
Policy Duration:
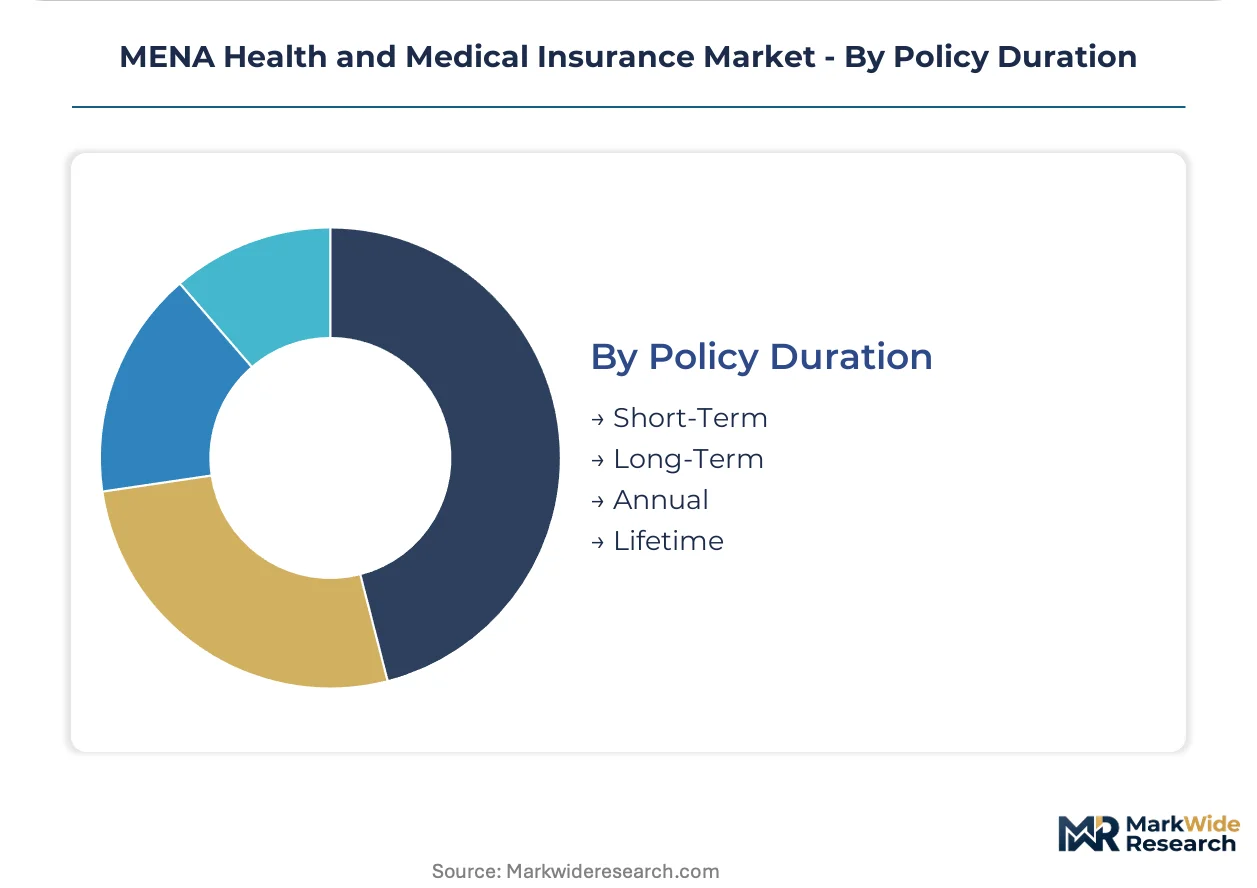
Contract length correlates with regulatory stability and employment security, with annual terms dominating mandatory schemes while lifetime coverage remains rare outside high-net-worth segments.
- Short-Term:Temporary policies cover visa processing gaps, seasonal workers, and probationary employment periods. Demand concentrates among construction sector expatriates in Qatar and the UAE with project-based contracts.
- Long-Term:Multi-year agreements lock in premium rates and benefit structures, appealing to Saudi corporate clients seeking budget predictability. Telemedicine infrastructure integration reduces outpatient cost ratios over extended horizons.
- Annual:Standard renewal cycles align with regulatory compliance calendars and employer fiscal years. This structure dominates across all Gulf Cooperation Council markets.
- Lifetime:Perpetual coverage guarantees insurability regardless of health status, restricted to premium-tier products with substantial capital reserves. Availability remains limited to specialized offerings in Dubai and Riyadh.
Annual policies hold the largest share; momentum sits with long-term contracts as corporate procurement demands outcome-based performance guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border premium flows within MENA remain structurally imbalanced, with Gulf-based insurers capturing outbound capital from North African markets while Egyptian and Moroccan carriers struggle to retain domestic risk pools.
United Arab Emirates
Abu Dhabi's mandatory health insurance scheme channels expatriate enrollment through Daman's administrative monopoly, while Dubai's competitive market fragments across multiple commercial underwriters. MOHAP's network adequacy standards now enforce geographic accessibility thresholds that force insurers to contract hospitals in Al Ain and western desert facilities. The Dubai International Financial Centre clusters regional headquarters for global carriers seeking Gulf market entry.
Saudi Arabia
The Council of Health Insurance criminalizes employer non-compliance, compressing enrollment timelines for millions of expatriate construction and hospitality workers. SFDA enforcement protocols standardize minimum benefits across basic and comprehensive tiers, limiting product differentiation. Riyadh's corporate banking sector drives demand for supplemental coverage beyond mandatory floors, with petrochemical employers consolidating broker relationships around outcome-based performance metrics.
Qatar
The national health insurance framework mandates resident coverage through regulated private participation, creating hybrid administrative structures that blend public oversight with commercial underwriting. Expatriate workforce expansion in LNG infrastructure and FIFA legacy hospitality sustains group policy volume. Doha's West Bay financial district concentrates insurance brokerage and TPA operations serving multinational contractors.
Egypt
Private voluntary coverage penetration remains below fifteen percent outside Cairo and Alexandria, leaving substantial uninsured middle-class demand for digital-first distribution models. The country's national pharmaceutical regulator maintains limited oversight of commercial health products, creating regulatory ambiguity for product innovation. New Cairo's satellite city development attracts private hospital investment that could anchor insurer network expansion.
MENA Health and Medical Insurance Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and network breadth, producing a tiered structure where scale-driven administrators anchor mandatory schemes while niche players capture supplemental voluntary demand. The market fragments across three strategic archetypes: government-linked monopolies controlling single-emirate mandatory pools, Saudi-focused corporate specialists leveraging regulatory proximity, and diversified Gulf operators spanning multiple jurisdictions. Consolidation pressure intensifies through broker relationship centralization and outcome-based procurement mandates from large corporate employers.
Among the government-linked tier, Daman exemplifies administrative scale through its Abu Dhabi mandate, while Bupa Arabia and Tawuniya occupy distinct positions within Saudi Arabia's corporate coverage segment. These three entities represent divergent competitive strategies—geographic exclusivity versus sectoral specialization versus government contract anchoring—that shape premium retention dynamics across their respective markets.
| Leading Market Players |
|---|
| Daman |
| Bupa Arabia |
| Tawuniya |
| MedGulf |
| GIG Gulf |
| AXA |
| Allianz |
| Oman Insurance Company |
| Qatar Insurance Company |
| Others |
Supply & Pricing Matrix
Sixty-day claims settlement cycles in Saudi Arabia's employer-sponsored pools concentrate pricing power with insurers possessing direct hospital network control, while compressed adjudication timelines in Dubai's competitive market fragment premium-setting authority across multiple underwriters. This lead-time differential between markets shapes how procurement departments negotiate outcome-based performance guarantees and where supply-side administrators invest in automation infrastructure.
Pricing Analysis
Corporate procurement departments anchor pricing negotiations through consolidated broker relationships and outcome-based performance guarantees. Three-tier pricing structure across premium, standard, and economy levels segments employer-sponsored pools in Saudi Arabia and the UAE, with premium tiers commanding wider provider networks and minimal co-payment exposure. Price differentiation hinges on network breadth and digital service integration, with basic mandatory tiers facing cost compression from SFDA enforcement protocols standardizing minimum benefits. Small and mid-sized employers in Qatar's construction sector exhibit highest price sensitivity, while Saudi petrochemical and banking sectors prioritize network satisfaction scores over premium minimization.
Supply Chain Analysis
Just-in-time claims processing preferences dominate among mid-sized insurers adopting optical character recognition and natural language processing platforms, though legacy core system integration challenges force strategic stockpiling of manual adjudication capacity for complex pre-authorization cases. Supply concentrates in Saudi Arabia, the UAE, and Qatar for mandatory scheme administration, with Egypt and Morocco serving emerging voluntary coverage demand. Raw material dependencies include hospital network contracts, pharmaceutical formulary agreements, and telemedicine platform licenses. Single-source vulnerability runs through Daman's administrative monopoly in Abu Dhabi and Tawuniya's government-linked contract anchoring in Riyadh. Distribution runs through employer-sponsored enrollment channels, broker-consolidated procurement, and embedded banking API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MENA health insurance sits as an early-cycle expansion story, with mandatory coverage laws across Gulf Cooperation Council states driving penetration from regulatory enforcement rather than voluntary adoption alone.
For Market Incumbents: Shield premium retention by deepening hospital network exclusivity in Saudi Arabia's corporate banking sector and accelerating claims automation deployment to compress administrative expense ratios. SFDA enforcement protocols threaten margin compression through standardized benefit floors, making vertical integration into telemedicine infrastructure the critical defensive lever against digital-native competitors. For New Entrants and Emerging Players: Anchor in Egypt's uninsured middle class outside Cairo and Alexandria, where private voluntary coverage penetration remains below fifteen percent and digital-first distribution models face limited incumbent saturation. Chronic disease management bundles for diabetes and cardiovascular care represent the most penetrable white space, with embedded insurance APIs through Saudi fintech payroll platforms offering the clearest go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because mandatory enrollment frameworks create durable enrollment moats for administrators with government-linked contracts. Target acquisition profiles center on TPAs with established hospital network contracts in underserved emirates and hybrid-model specialists bridging public oversight with private administration. The signal to watch is MOHAP network adequacy standard tightening, which would force enrollment caps and trigger consolidation among insurers lacking geographic accessibility metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Claims Automation Platform Deployment | Optical character recognition engines shrink administrative expense ratios for Saudi mid-sized insurers competing on turnaround speed. |
| Chronic Disease Management Bundle Launch | Diabetes and cardiovascular care packages align with MOHAP preventive care incentives in Abu Dhabi's comprehensive tier. |
| Embedded Insurance API Integration | Banking and fintech platforms across Saudi Arabia integrate health policy issuance into payroll and remittance workflows. |
| Network Adequacy Expansion | Daman and competing administrators contract Al Ain and western region hospitals to satisfy MOHAP geographic accessibility thresholds. |
| Broker Relationship Consolidation | Riyadh's petrochemical sector centralizes vendor selection authority, tying renewals to measurable network satisfaction scores. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with health insurance executives, hospital procurement managers, regulatory affairs specialists at SFDA and MOHAP, and corporate risk managers; alongside secondary validation through Council of Health Insurance enforcement protocols, MOHAP network adequacy filings, GPO contracts, and customs data on cross-border medical service flows. Bottom-up enrollment modeling by emirate and coverage tier triangulated against top-down premium pool estimates from regulatory disclosures.
Across the analysis window, the forecasting framework modeled demand by insurance type, coverage depth tier, provider administrative model, and policy duration segment, with CAGRs derived from regulatory mandate implementation timelines and expatriate workforce growth projections in construction, hospitality, and logistics sectors. Hospital service cost inflation differentials and telemedicine adoption curves served as industry-specific sensitivity inputs.
Decision-makers should treat outputs as directional under assumptions of sustained SFDA enforcement intensity and stable Gulf expatriate workforce composition; material deviation in regulatory compliance rates or macroeconomic migration patterns would warrant model refresh. Revision becomes warranted when medical inflation differentials between Dubai and Abu Dhabi outpace premium adjustment cycles beyond historical norms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Peru Insurance Market
Insurance
Germany Reinsurance Market
Insurance
Global Livestock Insurance Market
Insurance
Green Insurance Market
Insurance
Travel Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Insurance Analytics Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Cargo Insurance Market
Insurance
Workers Compensation Insurance Market