
 Asia-Pacific Critical Illness Insurance Market | 2026-2036
Asia-Pacific Critical Illness Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Critical Illness Insurance Market Insights
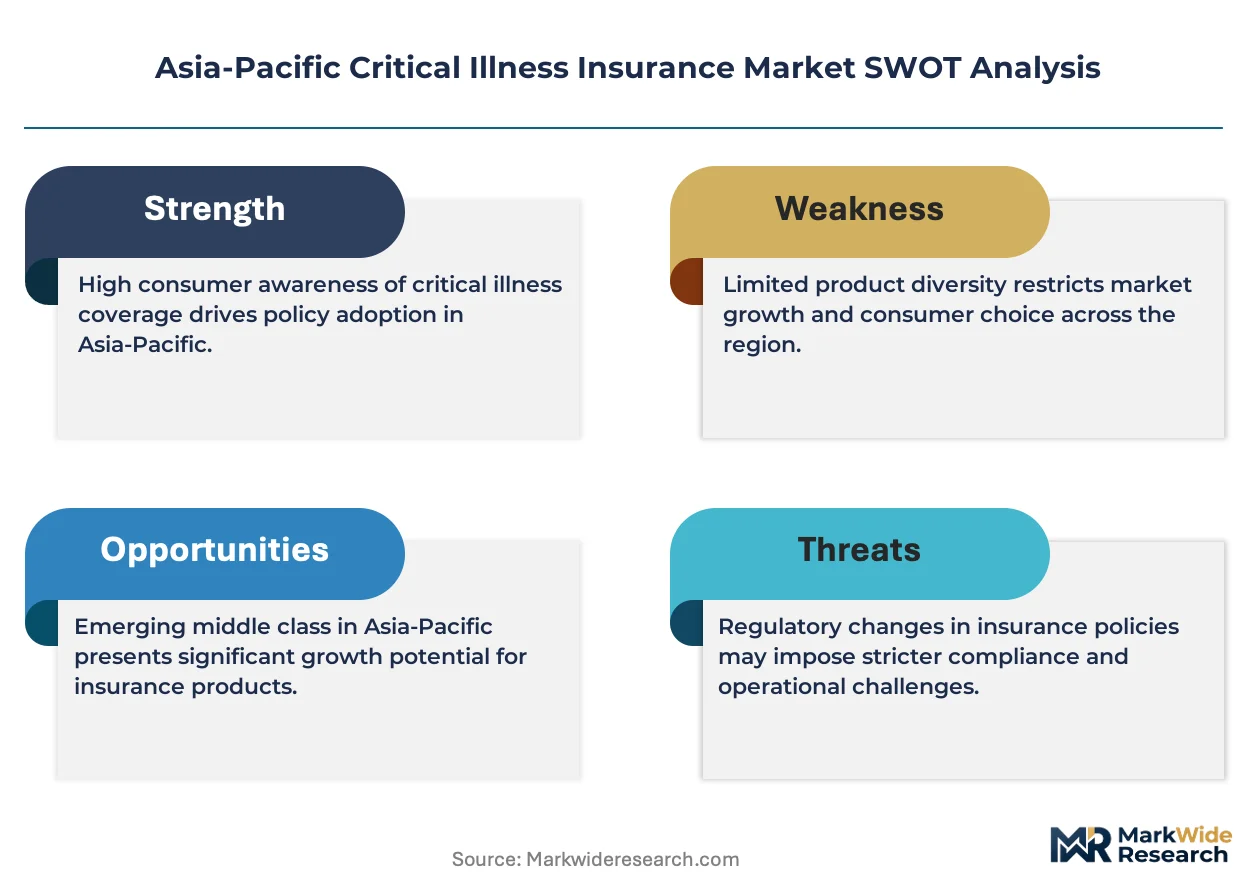
Actuarial talent scarcity across Southeast Asia is reorganizing how insurers price and reserve for critical illness products, forcing carriers to relocate analytical centers to Singapore and Sydney. AIA Group Limited leverages its pan-Asian agency network to sustain direct-to-consumer penetration in markets with underdeveloped broker infrastructure. Ping An Insurance anchors its competitive stance through proprietary health data ecosystems that integrate wearable monitoring with dynamic underwriting. Tokio Marine Holdings competes by dominating the corporate group policy segment in Japan's aging employer market.
Critical illness insurance constitutes a lump-sum indemnity contract triggered by diagnosis of specified life-threatening conditions—cancer, stroke, myocardial infarction—rather than reimbursement of actual medical expenditures, with benefit triggers defined by objective clinical criteria such as tumor staging or ejection fraction thresholds. The product's primary commercial purpose is to bridge the gap between national health system coverage and non-medical financial shocks including income loss, home modification, and caregiver expenses. Comprehensive coverage types command the deepest margin pools by bundling multiple condition triggers with survival period waivers, while basic plans face commoditization pressure from direct online platforms. Monthly premium payment frequencies are expanding fastest among gig-economy workers and younger individual buyers seeking liquidity preservation.
Australia's TGA, Japan's METI, and China's NMPA collectively shape product standards through divergent clinical definition requirements, survival period mandates, and advertising disclosure rules that determine which conditions qualify for payout and how policies must be sold. The EU AI Act's extraterritorial influence on algorithmic underwriting is beginning to affect multinational carriers operating across Asia-Pacific jurisdictions. Stakeholders must monitor whether China's SAMR accelerates standardization of critical illness definitions to reduce claims disputes, as this would compress product differentiation and redistribute competitive advantage toward scale players with superior mortality data.
Market Dynamics
Actuarial talent scarcity across Southeast Asia is forcing insurers to relocate analytical centers to Singapore and Sydney, fundamentally restructuring how critical illness products are priced and reserved across the region.
Growth Catalysts
- Corporate benefit expansion:Employer-sponsored group policies are accelerating coverage uptake among gig-economy workers and mid-tier enterprises across India and Indonesia.
- Out-of-pocket cost pressure:Rising medical expenditure gaps in China's tier-2 cities are pushing households toward supplemental lump-sum indemnity products.
- Wearable integration:Dynamic underwriting models using real-time biometric data are reducing adverse selection and expanding addressable risk pools.
Market Restraints
- Clinical definition fragmentation:Divergent tumor staging criteria between Australia's TGA and China's NMPA create product standardization barriers and claims dispute risk.
- Actuarial labor concentration:Analytical talent pools cluster in Singapore and Sydney, creating dependency bottlenecks for pricing functions across emerging markets.
- Survival period mandates:Japan's METI-required waiting periods compress policy attractiveness for acute-onset conditions like myocardial infarction.
Strategic Opportunities
- Vietnam and Philippines penetration:Insurance density below 3% of GDP in these markets creates first-mover advantage for simplified direct-to-consumer products.
- SAMR standardization:China's potential unification of critical illness definitions would reduce legal uncertainty and favor scale carriers with superior mortality data.
- Telemedicine convergence:Integration of remote diagnostic platforms with underwriting workflows enables real-time policy activation post-diagnosis.
Industry Challenges
- Legacy system integration:Incumbent carriers face technical debt when embedding API-connected health data ecosystems into core policy administration platforms.
- Cross-border data governance:The EU AI Act's extraterritorial algorithmic rules complicate underwriting model deployment for multinational portfolios spanning Asia-Pacific and European jurisdictions.
Report Scope
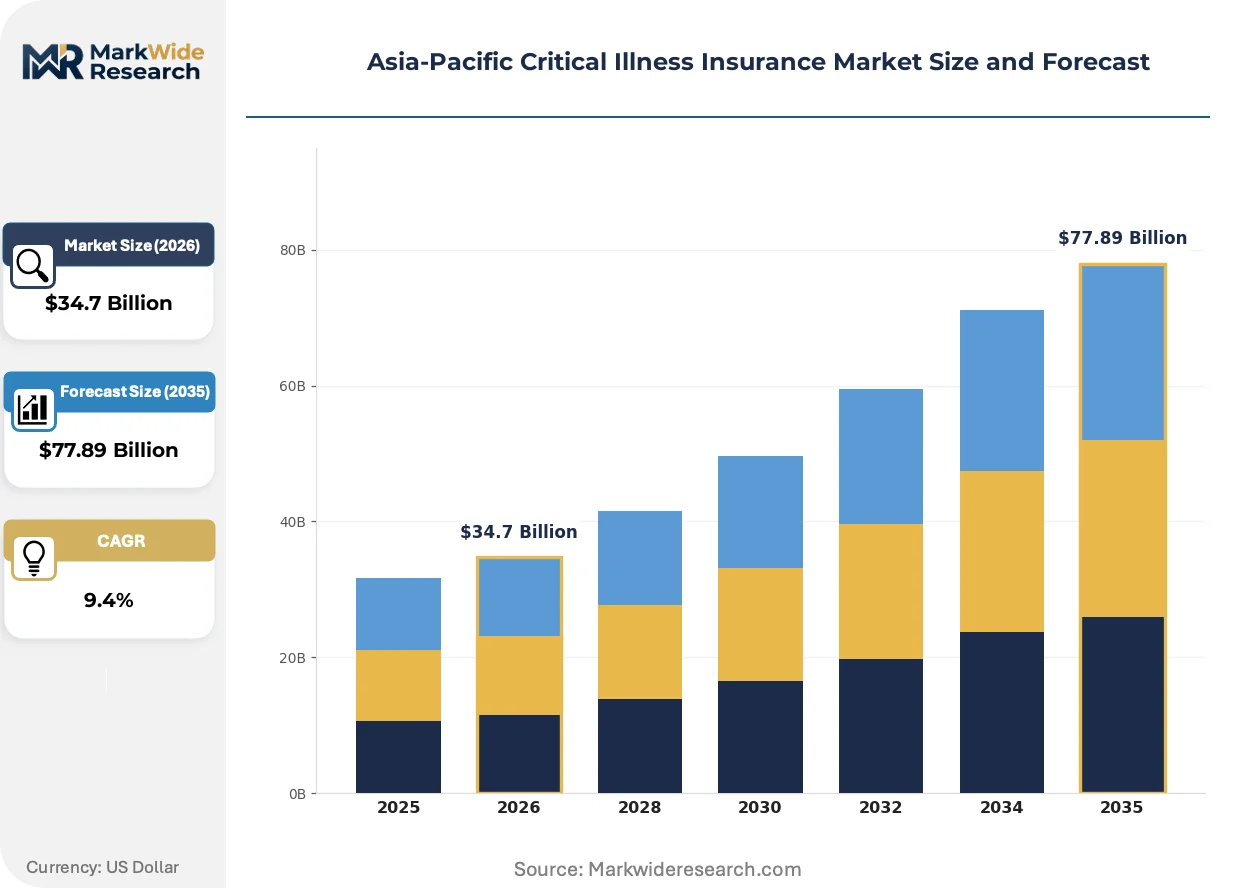
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Critical Illness Insurance Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $77.89 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Comprehensive, Basic, Major Disease, Terminal Illness Premium Payment Frequency: Monthly, Quarterly, Annually, Single Payment Distribution Channel: Direct Sales, Insurance Brokers, Financial Advisors, Online Platforms Customer Type: Individuals, Families, Corporates, Small Businesses |
| Companies Covered | Manulife Financial Corporation, Allianz SE, AIA Group Limited, Tokio Marine Holdings, Inc., China Pacific Insurance Company Limited, Ping An Insurance (Group) Company of China, Ltd., Prudential plc, Dai-ichi Life Holdings, Inc., China Life Insurance Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Critical Illness Insurance Market Trends and Innovations
Technology-enabled underwriting and shifting distribution economics are compressing traditional policy lifecycles while creating new competitive moats around data assets and direct channel control.
Algorithmic underwriting engines that score cardiovascular risk through continuous glucose monitoring and sleep pattern analysis are bifurcating the market between tech-integrated carriers and traditional mortality-table dependent insurers. Younger individual buyers in South Korea and Australia are adopting these models fastest, driving margin compression for standard products while enabling personalized premium tiers based on real-time behavioral data.
Japan's METI and Australia's TGA are tightening advertising disclosure requirements for survival period clauses and condition-specific exclusions, forcing product simplification and compressing differentiation strategies. Carriers must now standardize benefit trigger language across multi-jurisdiction portfolios, with direct-to-consumer platforms facing the steepest compliance recalibration.
Broker channel disintermediation is accelerating as embedded insurance partnerships with digital health platforms and neobanks capture policy origination. This shift concentrates distribution economics in Singapore and Hong Kong, where regulatory sandboxes permit experimental tie-ups between insurers and non-traditional financial service providers, sidelining traditional agency networks in Thailand and Malaysia.
Asia-Pacific Critical Illness Insurance Market Segmentation
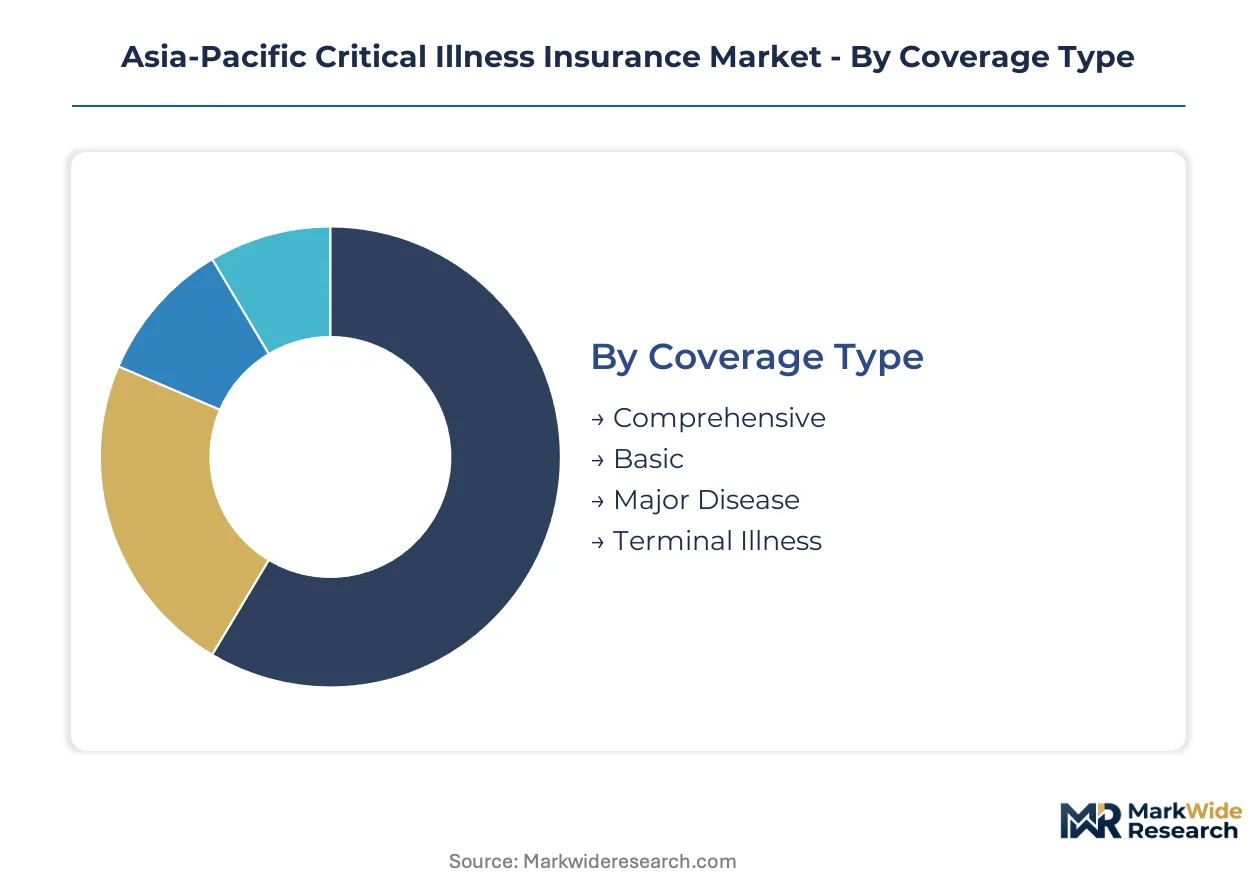
Critical illness insurance segments diverge sharply across Asia-Pacific based on regulatory maturity and distribution infrastructure. Coverage breadth and payment flexibility determine competitive positioning in markets with uneven broker penetration.
Coverage Type:
Geographic spread varies by condition complexity—comprehensive products concentrate in Australia's TGA-regulated environment while basic plans dominate price-sensitive emerging markets.
- Comprehensive:Bundles multiple condition triggers with survival period waivers. Demand clusters in China's tier-1 cities where households face substantial non-medical financial shocks from cancer diagnoses.
- Basic:Covers core conditions—cancer, stroke, myocardial infarction—at lower premium tiers. Indonesia and Vietnam show strongest uptake among first-time buyers seeking income protection without complexity.
- Major Disease:Targets specific high-incidence conditions prevalent in aging populations. Japan's METI framework shapes product design through mandated clinical definition standards.
- Terminal Illness:Accelerates death benefit payout upon life expectancy prognosis. Australia's TGA disclosure requirements influence how carriers communicate benefit triggers to policyholders.
Comprehensive holds the largest share; momentum sits with Basic plans penetrating underinsured Southeast Asian markets.
Premium Payment Frequency:
Cost tier alignment determines channel strategy—higher frequency payments reduce barrier to entry while single payments optimize for high-net-worth segments.
- Monthly:Preserves liquidity for gig-economy workers and younger individual buyers across India and South Korea. Australia's neobank partnerships embed this option into salary-linked deductions.
- Quarterly:Balances cash flow management with administrative efficiency. Mid-tier enterprises in Thailand prefer this rhythm for group policy administration.
- Annually:Carriers offer modest discounts for upfront commitment. Concentrated among established corporate benefit programs in Japan's aging employer market.
- Single Payment:Lump-sum premium eliminates ongoing obligation. Appeals to high-net-worth individuals in Singapore and Hong Kong seeking estate planning integration.
Monthly payment structures are expanding most quickly; annual arrangements retain margin advantage for established carriers.
Distribution Channel:
Application focus separates traditional relationship-driven sales from algorithmic direct-to-consumer platforms gaining traction in digitally mature markets.
- Direct Sales:AIA Group's pan-Asian agency network sustains penetration where broker infrastructure remains underdeveloped. Philippines and rural India depend heavily on this channel.
- Insurance Brokers:Independent intermediaries command premium placement in Australia's sophisticated retail market. Regulatory sandboxes in Singapore enable experimental broker-digital hybrid models.
- Financial Advisors:Embedded within wealth management relationships. Hong Kong's private banking channels integrate critical illness into comprehensive financial planning.
- Online Platforms:Embedded insurance partnerships with digital health apps capture younger demographics. South Korea's telemedicine convergence accelerates real-time policy activation post-diagnosis.
Direct sales maintains volume leadership; online platforms gain share fastest where smartphone penetration exceeds traditional banking access.
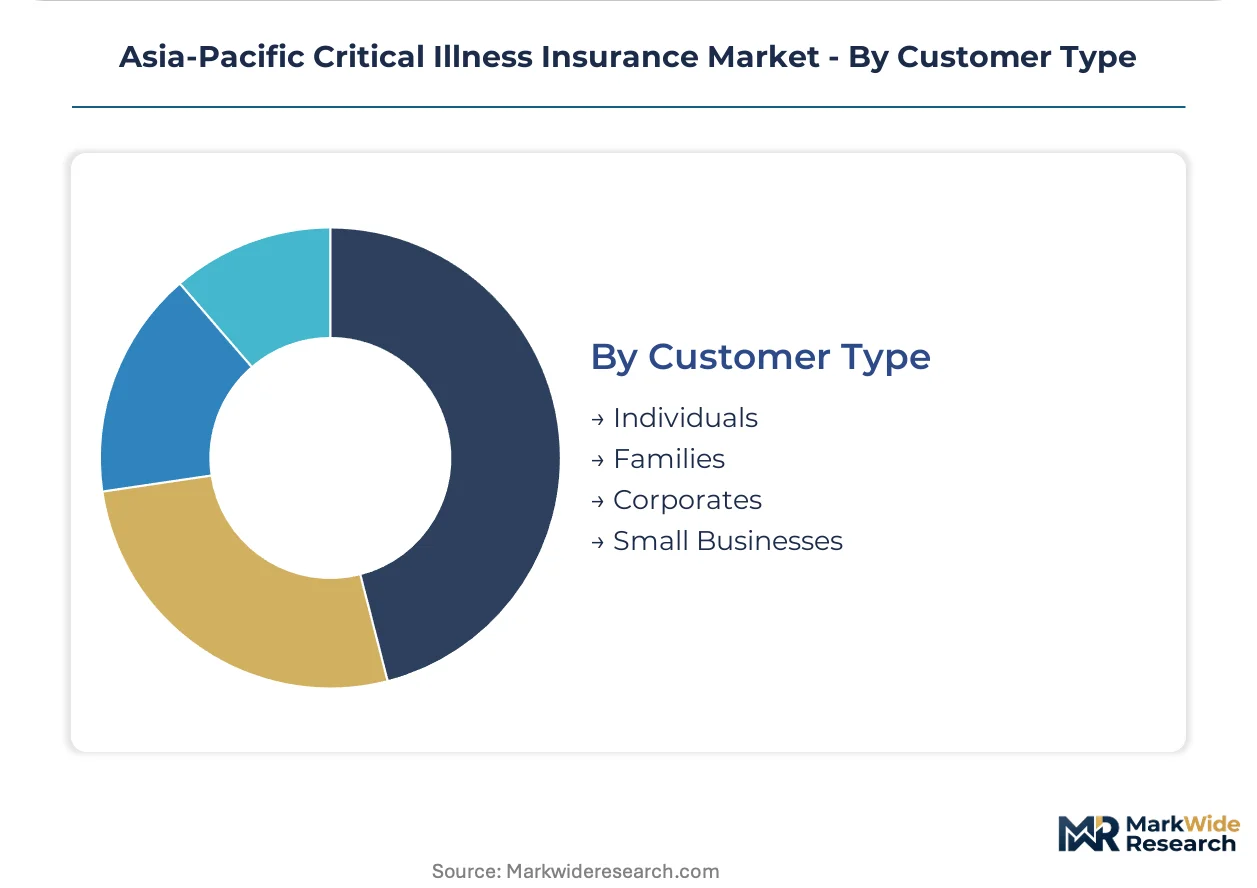
Customer Type:
Volume concentration reflects economic structure—corporate programs drive scale while individual segments demand customization.
- Individuals:Self-directed purchasers seeking income protection gaps. China's rising out-of-pocket healthcare costs accelerate adoption among urban professionals.
- Families:Multi-life policies covering household breadwinners and dependents. India's expanding middle-class shows strongest growth in family-tier products.
- Corporates:Employer-sponsored group policies dominate Japan's aging workforce market. Tokio Marine Holdings competes through segment specialization.
- Small Businesses:Micro-enterprise owners seeking portable coverage independent of employer. Vietnam's informal economy creates addressable pool for simplified direct products.
Corporate customer segments command premium volume; individual buyers represent the steepest expansion trajectory as gig-economy participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Asia-Pacific, with China and India driving volume through out-of-pocket cost pressures while Japan and Australia concentrate value in employer-sponsored and comprehensive individual products respectively.
China
Rising medical expenditure gaps in tier-2 cities accelerate household adoption of supplemental lump-sum indemnity products. The National Medical Products Administration (NMPA) shapes clinical definition requirements that determine which tumor staging criteria trigger payouts. Shanghai and Beijing host the densest concentrations of policy origination, where urban professionals seek income protection against non-medical financial shocks.
Japan
An aging employer market sustains corporate group policy dominance as workforce demographics shift. The Ministry of Economy, Trade and Industry (METI) mandates survival period clauses that compress policy attractiveness for acute-onset conditions like myocardial infarction. Tokyo anchors the national market, with Osaka-Kobe and Nagoya forming secondary clusters where insurance density reflects manufacturing employment concentration.
India
Expanding middle-class populations and gig-economy participation create dual demand vectors for both family-tier products and portable individual coverage. Regulatory frameworks from the Insurance Regulatory and Development Authority govern disclosure standards and product classification. Mumbai and Delhi-NCR concentrate distribution infrastructure, while Bangalore and Hyderabad emerge as digital policy origination hubs.
Australia
Sophisticated retail markets sustain independent broker channel dominance alongside embedded neobank partnerships. The Therapeutic Goods Administration (TGA) enforces tightening advertising disclosure requirements for survival period clauses and condition-specific exclusions. Sydney and Melbourne host relocated analytical centers from Southeast Asian carriers seeking actuarial talent concentration.
South Korea
Younger demographics adopt algorithmic underwriting models fastest, driving personalized premium tiers based on real-time behavioral data. The Ministry of Food and Drug Safety (MFDS) influences clinical definition standards that intersect with insurance product design. Seoul anchors telemedicine convergence with underwriting workflows, enabling real-time policy activation post-diagnosis.
Asia-Pacific Critical Illness Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale carriers commanding mortality data advantages and niche players occupying condition-specific or distribution-channel segments. The market structure bifurcates between pan-Asian agency networks and proprietary health data ecosystems. Three archetypes dominate: integrated multi-line insurers with captive distribution, technology-enabled carriers leveraging wearable underwriting, and corporate group policy specialists. Competitive moves concentrate on API-connected health data ecosystem integration and regulatory sandbox partnerships with digital health platforms.
Among integrated Asia-Pacific carriers, AIA Group Limited and Ping An Insurance occupy positions exemplifying divergent strategic vectors—agency network penetration versus data ecosystem anchoring—while Tokio Marine Holdings sits within the corporate specialization tier. These three represent how geographic origin and structural form shape competitive positioning: the Hong Kong-based pan-Asian network, the Chinese technology-integrated conglomerate, and the Japanese employer-market dominant each illustrate distinct archetype pathways without claiming specific tactical superiority.
| Leading Market Players |
|---|
| Manulife Financial Corporation |
| Allianz SE |
| AIA Group Limited |
| Tokio Marine Holdings, Inc. |
| China Pacific Insurance Company Limited |
| Ping An Insurance (Group) Company of China, Ltd. |
| Prudential plc |
| Dai-ichi Life Holdings, Inc. |
| China Life Insurance Company Limited |
| Others |
Pricing and Supply Chain Analysis
Dynamic underwriting algorithms replacing traditional mortality-table pricing are simultaneously relocating actuarial talent to Singapore and Sydney while compressing margin structures for standard products across Southeast Asia. This substitution dynamic concentrates pricing power among carriers with proprietary health data ecosystems and fragments it for those dependent on outsourced analytical functions.
Pricing Analysis
Long-term group offtake contracts dominate Japan's corporate benefit market, while spot-market individual policies proliferate through Australia's neobank partnerships and South Korea's telemedicine platforms. Price differentiation hinges on survival period waiver inclusion and real-time biometric integration depth, with wearable-enabled tiers commanding premium positioning against basic mortality-table products. Cost compression in standard comprehensive plans is intensifying as direct-to-consumer platforms in Indonesia and Vietnam strip out broker commissions. Gig-economy workers in India and South Korea exhibit highest price sensitivity; high-net-worth individuals in Singapore and Hong Kong show least, accepting single-payment structures for estate planning integration.
Supply Chain Analysis
Extended lead times for actuarial model validation are forcing carriers to hold larger reserves of analytical talent in Singapore, Sydney, and Tokyo. Product development capacity concentrates in Australia, Japan, and China, with clinical definition standardization efforts by China's SAMR and Japan's METI creating regulatory chokepoints. Raw material inputs for underwriting models draw from wearable device manufacturers, telemedicine platforms, and national mortality databases. Single-source vulnerability sits with cloud infrastructure providers hosting real-time biometric scoring engines. Distribution runs through embedded partnerships with digital health platforms in South Korea and Hong Kong's regulatory sandboxes, sidelining traditional agency networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific critical illness insurance operates as a defensive-moat market where regulatory entrenchment through divergent clinical definition requirements creates sticky policyholder relationships and high switching costs across multi-jurisdiction portfolios.
For Market Incumbents: Fortify proprietary health data ecosystems by deepening API integration with wearable manufacturers and telemedicine platforms before China's SAMR standardization compresses product differentiation. Anchor analytical capacity in Singapore and Sydney to offset Southeast Asian actuarial talent scarcity. Prioritize survival period waiver innovation to defend margin position against METI-mandated waiting period constraints in Japan's corporate group segment. For New Entrants and Emerging Players: Embedded insurance partnerships with neobanks and digital health apps represent the most penetrable service-layer gap, as incumbents under-serve gig-economy workers seeking monthly liquidity-preserving payment structures. Target Vietnam and Philippines direct-to-consumer origination where insurance density remains below 3% of GDP. Pursue regulatory sandbox authorization in Hong Kong or Singapore to validate algorithmic underwriting models before broader Asia-Pacific deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital health platforms possessing underwriting workflow integration capabilities and established biometric data partnerships. Long-term viability favors carriers with captive mortality data advantages spanning 5-10 year policy lifecycles. Watch for SAMR standardization announcements as inflection indicator that would redistribute competitive advantage toward scale players.| Strategic Initiative | Industry Significance |
|---|---|
| Wearable Data Partnership | Secures real-time biometric feeds from Samsung Health and Apple Watch ecosystems for dynamic premium scoring. |
| Regulatory Sandbox Authorization | Enables experimental algorithmic underwriting deployment under Hong Kong IA and MAS supervision frameworks. |
| Actuarial Center Relocation | Consolidates pricing functions in Sydney and Singapore to address Southeast Asian analytical talent scarcity. |
| Telemedicine Platform Integration | Accelerates real-time policy activation post-diagnosis through Seoul-based remote diagnostic workflows. |
| Corporate Group Policy Expansion | Captures Japan's aging employer market through METI-compliant survival period waiver products. |
Research Methodology
Operator-level perspectives from chief actuaries, underwriting technology leads, regulatory affairs directors at Asia-Pacific carriers, and digital health platform partnership managers anchored the qualitative base. Secondary validation drew from NMPA clinical definition filings, METI insurance guideline publications, TGA disclosure requirement updates, and SAMR standardization notices. Bottom-up policy origination data from tier-1 and tier-2 Chinese cities, top-down macroeconomic healthcare expenditure trends, and triangulation across these sources established market sizing.
Sensitivity analysis around biometric adoption rates, regulatory standardization timelines, and corporate benefit penetration depth shaped the analytical framework. Segmentation modeling covered coverage type, premium payment frequency, distribution channel, and customer archetype across the projection horizon. CAGRs were derived from fitted growth curves against historical policy origination velocity, with inputs including wearable device penetration data and out-of-pocket healthcare cost trajectories in China and India.
Underlying assumptions cover SAMR standardization pace, METI survival period clause stability, and TGA advertising disclosure enforcement continuity, with deviation risk concentrated in regulatory harmonization timing and biometric data governance rulings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Travel Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Small Business Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Disability Insurance Market
Insurance
Fire Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Engineering Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Cyber Liability Insurance Market