
 Sweet Potato Fries Market | 2026-2036
Sweet Potato Fries Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Potato Fries Market Insights
Subscription-based replenishment programs for frozen potato products is shifting how foodservice distributors manage inventory and pricing. Lamb Weston leverages its North American processing footprint to sustain consistent supply to chain restaurants. McCain Foods anchors its competitive stance through R&D intensity in batter and coating technologies for sweet potato variants.
Sweet potato fries consist of sliced and processed Ipomoea batatas tubers, typically par-fried in vegetable oil at 175–185°C and quick-frozen to preserve texture and reduce final preparation time to under four minutes in commercial or home fryers. Frozen product type dominates volume due to extended shelf life and operational convenience in foodservice kitchens, while seasoned variants capture expanding margin pools through flavor differentiation and premium positioning. Distribution through restaurants remains the highest-velocity channel, though online retail is accelerating as direct-to-consumer frozen delivery infrastructure matures.
FDA food safety modernization requirements and USDA organic certification standards shape ingredient sourcing and processing protocols for manufacturers serving the United States market. State-level trans-fat bans in California and New York have accelerated reformulation toward clean-label oils and reduced saturated fat profiles. Stakeholders must monitor evolving front-of-package labeling rules and air-fryer cooking claim validations as purchase criteria continue fragmenting across retail and foodservice buyers.
Market Dynamics
Air-fryer-ready formulations are restructuring formulation priorities across frozen sweet potato fry portfolios, compelling processors to reengineer oil absorption profiles and moisture retention systems for domestic cooking environments.
Growth Catalysts
- Clean-label mandates:FDA trans-fat restrictions and state-level bans in California and New York are accelerating reformulation toward high-oleic sunflower and avocado oil alternatives.
- Quick-service menu expansion:Fast-casual chains are deploying sweet potato fries as differentiated side offerings to capture health-conscious diner traffic.
- Air-fryer penetration:Household adoption of rapid-air circulation appliances is integrating freezer-to-table convenience expectations into retail product specifications.
Market Restraints
- Input cost volatility:Sweet potato harvest sensitivity to drought conditions in North Carolina and Louisiana creates raw material price instability.
- Supply concentration risk:Frozen processing capacity clusters in the Pacific Northwest and Midwest, exposing distribution networks to regional weather disruptions.
- Technical shelf-life limitations:Natural sugar caramelization during frozen storage degrades fry color consistency, constraining extended distribution timelines.
Strategic Opportunities
- Direct-to-consumer infrastructure:Cold-chain delivery platforms are opening subscription-based replenishment channels for premium frozen variants.
- USDA organic certification tailwinds:Federal procurement preferences and retailer slotting fee reductions for certified organic products create margin expansion potential.
- Seasoned flavor convergence:Fusion of regional spice profiles with traditional batters enables premium positioning in ethnic cuisine segments.
Industry Challenges
- Processing equipment capex intensity:Continuous fryer automation and optical sorting systems require seven-figure capital commitments for quality tier upgrades.
- Front-of-package compliance timelines:Evolving FDA labeling claim validations for air-fryer cooking instructions delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Potato Fries Market |
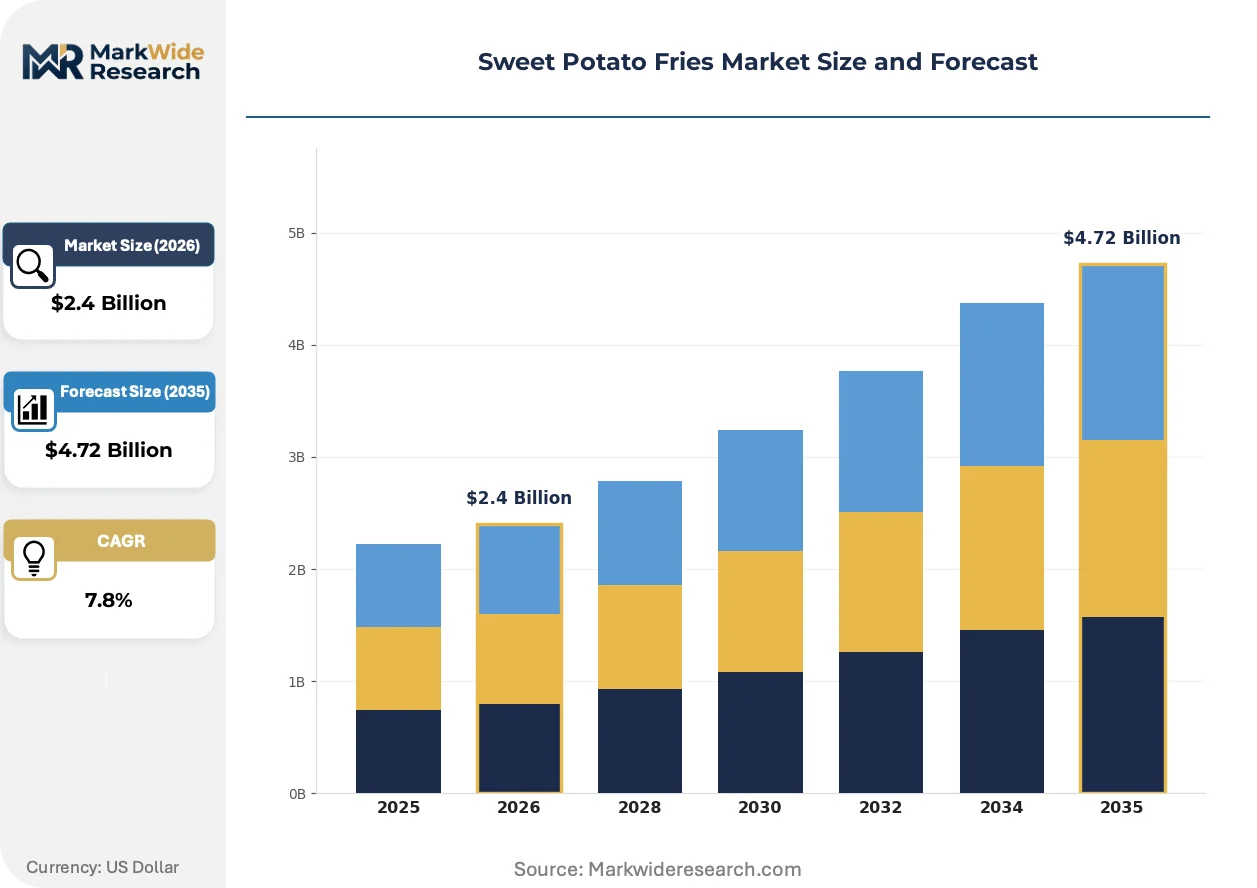
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Organic, Seasoned Packaging Type: Bag, Box, Bulk, Retail Pack Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Restaurants End User: Households, Food Service, Cafes, Catering |
| Companies Covered | Lamb Weston, McCain Foods, J.R. Simplot Company, Aviko, Ardo, Russet House Potatoes, Farm Frites, Cavendish Farms, Ore-Ida, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Potato Fries Market Trends and Innovations
Formulation science and cooking technology convergence are redefining quality benchmarks for frozen sweet potato products, with processor R&D pipelines prioritizing texture preservation across divergent preparation methods.
Advanced batter systems incorporating modified starch and rice flour blends are integrating into mainstream production lines. Quick-service operators and retail brands are adopting these formulations at accelerating rates to maintain crispness through holding periods. The technology is integrating hold-time performance into contract specifications, compressing competitive differentiation around finish quality rather than base ingredient sourcing.
USDA organic certification standards and FDA Food Safety Modernization Act traceability requirements are tightening ingredient documentation protocols. Manufacturers must now maintain chain-of-custody records from farm to freezer for audit readiness. Organic sweet potato fry lines face the steepest compliance burden, with certifying body inspections adding four to six weeks to production scheduling.
Foodservice distributors are unbundling frozen potato procurement from broadline contracts, creating specialized buying consortia for high-volume operators. Independent restaurant groups are consolidating purchasing through regional cooperatives, displacing traditional broadline middlemen. This pattern concentrates most visibly in the Southeast, where fast-casual expansion is outpacing national chain penetration.
Sweet Potato Fries Market Segmentation
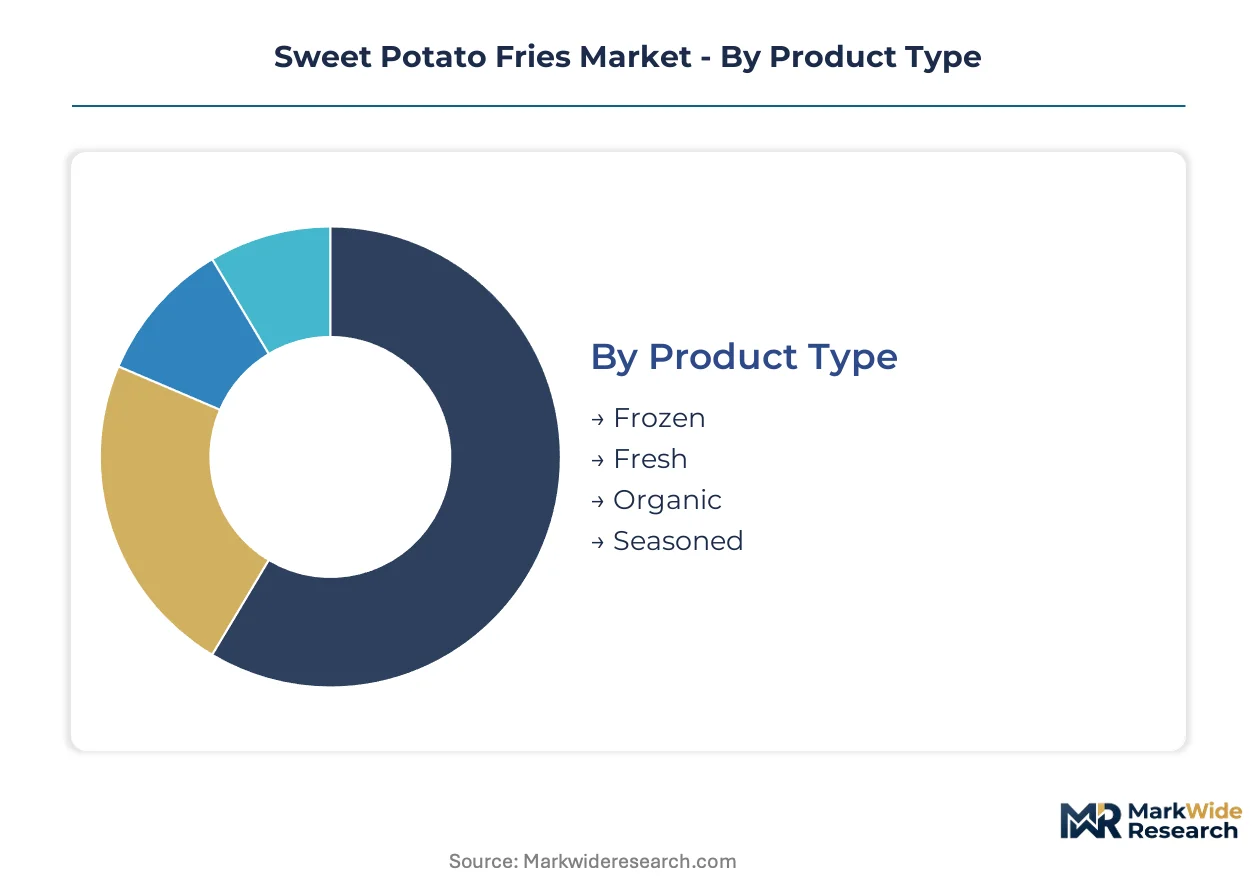
Sweet potato fry segmentation reveals how processing technology, packaging engineering, and channel logistics create distinct value tiers. Manufacturers configure production lines and cold-chain investments around specific segment requirements rather than pursuing universal coverage.
Product Type:
Par-frying temperature profiles and moisture retention specifications differentiate manufacturing investments across product categories.
- Frozen:Tubers undergo par-frying at 175–185°C followed by rapid freezing to preserve cellular structure. Quick-service restaurants in the United States concentrate procurement here for operational consistency and sub-four-minute finish times.
- Fresh:Refrigerated distribution with modified atmosphere packaging maintains enzymatic stability for 7–14 days. Fast-casual chains with high table turnover and visible prep kitchens favor this format despite shorter shelf life and higher spoilage rates.
- Organic:USDA certification mandates chain-of-custody documentation from farm through freezer, adding inspection delays to production scheduling.
- Seasoned:Batter and coating R&D intensity concentrates in regional spice fusion variants targeting ethnic cuisine segments.
Mature deployment sits with Frozen. Newer deployment is concentrated in Seasoned.
Packaging Type:
Unit economics and handling automation requirements shape packaging selection across retail and foodservice channels.
- Bag:Flexible film structures with high-barrier laminates dominate retail freezer sections, enabling vertical merchandising and consumer portion control.
- Box:Rigid corrugated formats with wax coatings protect product integrity through restaurant receiving docks and high-volume storage environments.
- Bulk:Foodservice distributors manage 20–40 pound poly-lined cases for chain restaurant replenishment, optimizing freight density over shelf appeal.
- Retail Pack:Printed film with air-fryer cooking instructions and nutritional callouts responds to direct-to-consumer delivery platform specifications.
Volume leadership belongs to Bulk. Margin expansion concentrates in Retail Pack.
Distribution Channel:
Cold-chain infrastructure maturity and buyer procurement patterns determine channel prioritization for processor sales teams.
- Supermarkets:Freezer section reset cycles and slotting fee negotiations govern placement economics, with air-fryer-ready variants gaining linear footage in the United States.
- Online Retail:Direct-to-consumer frozen delivery platforms are opening subscription replenishment channels, requiring last-mile temperature control investments.
- Convenience Stores:Limited freezer capacity favors smaller pack sizes and impulse-positioned grab-and-go formats.
- Restaurants:Broadline distributor relationships and contract specifications for hold-time performance dominate procurement workflows for quick-service operators.
Velocity concentration remains with Restaurants. Fastest channel expansion is occurring in Online Retail.
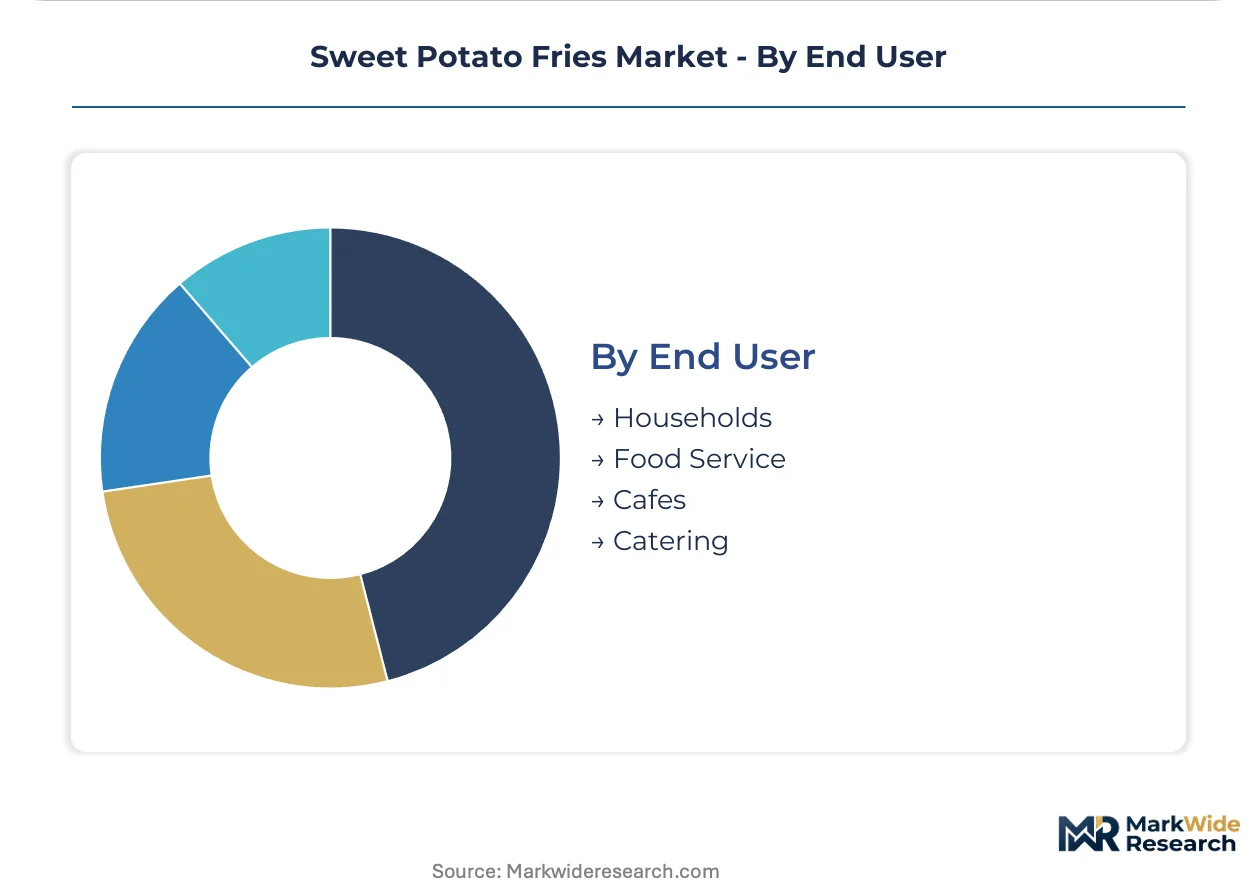
End User:
Preparation equipment availability and labor cost structures differentiate demand specifications across buyer categories.
- Households:Air-fryer penetration in domestic kitchens is restructuring retail product specifications toward reduced-oil absorption profiles and freezer-to-table convenience claims.
- Food Service:Commercial fryer infrastructure and holding cabinet workflows demand batter systems engineered for extended crispness retention during peak service periods.
- Cafes:Limited kitchen footprints favor pre-portioned formats with minimal prep labor and flexible menu integration.
- Catering:Transport logistics and off-site finishing requirements drive demand for par-fried products with stable color performance through extended holding.
Established demand concentration sits with Food Service. Emerging specification development is concentrated in Households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's Research Triangle corridor anchors sweet potato processing density in the United States, with Washington State's Columbia Basin and Idaho's Magic Valley forming the complementary frozen potato manufacturing belt.
United States
Quick-service restaurants and fast-casual chains drive procurement volumes through broadline distributor networks. FDA trans-fat restrictions and California's state-level ban accelerate reformulation toward high-oleic oil alternatives. North Carolina's coastal plain concentration of sweet potato farms supplies raw material to processing facilities in the Research Triangle region.
Canada
Retail freezer section expansion and air-fryer-ready product adoption reshape consumer purchasing patterns. Health Canada's front-of-package labeling regulations influence nutritional claim validations for frozen potato products. Manitoba's Red River Valley hosts processing infrastructure serving both domestic supermarkets and cross-border foodservice channels.
Netherlands
European distribution hubs leverage Rotterdam's port infrastructure for frozen product transshipment across the continent. EFSA nutritional labeling standards and EU Green Deal sustainability requirements shape ingredient sourcing protocols. The Flevoland polder region concentrates potato processing capacity with integrated cold-chain logistics serving German and French retail buyers.
Belgium
Specialized fry manufacturing expertise supports private-label production for European retail chains. REACH chemical safety regulations and EU organic certification standards govern batter and coating ingredient approvals. The Wallonia region's agri-food processing corridor maintains legacy fry production infrastructure with modernized automation investments.
China
Domestic quick-service restaurant expansion creates demand for standardized frozen potato products with localized flavor profiles. SAMR food safety modernization requirements and GB standards for frozen vegetables tighten processing documentation protocols. Shandong Province's vegetable processing belt hosts contract manufacturing facilities serving Asian fast-food chains.
Sweet Potato Fries Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sweet potato fry landscape, with integrated processors owning fryer automation and freezing infrastructure while branded marketers outsource manufacturing. The structure concentrates around three tiers: multinational frozen potato specialists with North American processing footprints, European cooperative-owned processors with regional distribution dominance, and private-label contractors serving retailer specifications. Strategic moves center on backward integration into sweet potato sourcing and R&D partnerships for batter technology licensing.
Within the multinational specialist tier, Lamb Weston and McCain Foods exemplify scale-driven positions, while J.R. Simplot Company occupies a distinct geography-anchored role. These entities represent divergent approaches to supply security—one through Pacific Northwest processing density, another through R&D intensity in coating formulations, the third through integrated agricultural operations.
| Leading Market Players |
|---|
| Lamb Weston |
| McCain Foods |
| J.R. Simplot Company |
| Aviko |
| Ardo |
| Russet House Potatoes |
| Farm Frites |
| Cavendish Farms |
| Ore-Ida |
| Others |
Pricing and Supply Chain Analysis
Quick-service restaurant chains concentrate procurement volumes through long-term distributor contracts, anchoring a contract-based pricing model where volume tiers and hold-time performance specifications determine unit economics. This buyer concentration grants chain operators leverage over batter technology premiums while exposing processors to margin compression when raw material costs fluctuate.
Pricing Analysis
Hold-time performance through peak service periods anchors value-based pricing premiums for quick-service operators, with batter systems engineered for extended crispness retention commanding tiered contract rates. USDA organic certification and high-oleic oil formulations differentiate price levels across conventional and clean-label tiers. Pricing pressure stems from drought-driven sweet potato harvest volatility in North Carolina and Louisiana, compressing margins for non-integrated processors. Independent restaurant groups exhibit highest price sensitivity due to limited volume scale, while national chains absorb premiums for supply security.
Supply Chain Analysis
Sweet potato supply rests on North Carolina coastal plain harvests and complementary Louisiana acreage, with frozen processing capacity clustering in Washington State's Columbia Basin and Idaho's Magic Valley. High-oleic sunflower and avocado oil alternatives, modified starch blends, and optical sorting equipment constitute critical input dependencies. Single-source vulnerability concentrates in Pacific Northwest freezing infrastructure exposed to regional weather disruptions. Distribution runs through broadline foodservice networks and specialized cold-chain platforms serving retail freezer sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Food Safety Modernization Act traceability requirements and state-level trans-fat bans construct a cost-of-compliance barrier that favors processors with established documentation infrastructure and reformulation capabilities. This regulatory moat disadvantages undercapitalized entrants lacking audit-ready chain-of-custody systems.
For Market Incumbents: Cement supply security through backward integration into North Carolina sweet potato sourcing and captive high-oleic oil refining capacity. Expand air-fryer-ready formulation R&D to defend against private-label erosion in retail channels. Processor consolidation in the Pacific Midwest freezing corridor presents acquisition opportunities to concentrate capacity. For New Entrants and Emerging Players: Direct-to-consumer cold-chain delivery platforms represent the most penetrable channel, with subscription replenishment models bypassing slotting fee barriers in conventional retail. Target USDA organic certification gaps in fast-casual supply chains where incumbent capacity constraints create replenishment vulnerabilities. Lead with air-fryer cooking claim validation as a differentiated entry proposition. For Investors and Strategic Acquirers: The window for entry favors processors with integrated agricultural operations and existing organic certification infrastructure. Long-term viability hinges on climate-adaptive sourcing strategies and batter technology licensing portfolios. Watch drought frequency indices for North Carolina growing regions as an inflection indicator for input cost trajectories and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sweet Potato Sourcing | Captive supply from North Carolina growing regions reduces harvest volatility exposure for processors. |
| Air-Fryer-Ready Formulation Development | FDA cooking claim validation enables premium positioning in retail freezer sections. |
| USDA Organic Certification Investment | Federal procurement preferences and retailer slotting fee reductions expand margin pools. |
| Direct-to-Consumer Cold-Chain Launch | Subscription replenishment platforms bypass conventional distributor margin stacking. |
| Batter Technology Licensing Agreement | Rice flour and modified starch blend patents generate royalty streams from private-label manufacturers. |
Research Methodology
Multi-period observation of quick-service menu placement cycles, air-fryer household penetration rates, and sweet potato acreage fluctuations anchored the trend analysis, supplemented by interviews with frozen potato category managers, foodservice procurement directors, agricultural extension specialists, and cold-chain logistics operators. Secondary validation drew from USDA crop reports, FDA labeling guidance documents, customs trade data, and SEC processor filings. Bottom-up volume estimates triangulated against top-down category spend analysis.
Input-output matrices modeled par-frying capacity utilization, oil absorption coefficients, and distribution cost structures across the projection horizon. Segmentation dimensions included product type, packaging format, distribution channel, and end-use preparation equipment. CAGRs derived from slope analysis of historical volume trajectories adjusted for regulatory phase-in schedules and technology adoption curves. Forecast inputs incorporated climate projection models for growing region precipitation patterns and air-fryer appliance shipment data.
Caveats apply where FDA front-of-package labeling rule finalization, state-level trans-fat ban expansion, or severe drought episodes in North Carolina could materially shift the outlook. A small set of named triggers—regulatory compliance timelines, harvest yield variance, and air-fryer penetration inflection—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Vegan Protein Balls Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Snack Food Packaging Market
Snacks
Dairy Protein Crisps Market
Snacks
France Energy Bar Market
Snacks
No-Fat Peanut Butter Market
Snacks
Europe Extruded Snack Food Market
Snacks
Roasted Corn Market
Snacks
Low Calorie Snack Foods Market
Snacks
Granola Market
Snacks
Germany Energy Bar Market
Snacks
Spain Energy Bar Market
Snacks
Protein Crisps Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
South Korea Snack Bar Market
Snacks
South America Cereal Bar Market