
 Frozen Potato Market | 2026-2036
Frozen Potato Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Potato Market Analysis
Food processing technician availability is bifurcating the competitive landscape between automated and labor-dependent facilities. McCain Foods Limited leverages its vertical integration from seed breeding through distribution to sustain cost leadership across multiple continents. Lamb Weston Holdings, Inc. anchors North American supply through its massive processing footprint in the Columbia Basin. J.R. Simplot Company differentiates via proprietary potato varieties optimized for specific fry textures and hold times.
Frozen potato products are par-fried or blanched potato items preserved at sub-zero temperatures, typically processed through cutting, blanching, drying, frying, and flash-freezing sequences to achieve specific moisture content and starch retrogradation profiles for consistent rethermalization. French fries command the largest revenue share within product type segmentation due to universal quick-service menu penetration and established consumer habituation. Quick service outlets represent the fastest-expanding end-user channel as chains standardize prep-minimal formats across emerging markets. Retail packaging formats are capturing margin pools as convenience-oriented consumers shift toward smaller-portion, resealable options for home preparation.
The EU Green Deal and FDA food safety modernization frameworks are elevating energy efficiency and traceability requirements throughout frozen potato value chains, compelling processors to retrofit facilities or risk market access restrictions. REACH compliance in Europe and evolving USDA organic certification pathways are reshaping ingredient sourcing protocols for value-added potato products. Stakeholders must monitor cold-chain decarbonization mandates and alternative freezing technology maturation to preserve competitive positioning as regulatory thresholds tighten.
Market Dynamics
Cold-chain energy mandates under the EU Green Deal are forcing processors to retrofit freezing tunnels or surrender market access, while Brazilian quick-service expansion pulls volume toward Latin America. This regulatory-demand tension is restructuring capital allocation across frozen potato value chains.
Growth Catalysts
- EU Green Deal cold-chain standards:Mandates for lower-GWP refrigerants and energy-efficient blast freezing are accelerating equipment replacement cycles among European processors seeking compliance certainty.
- Quick-service menu standardization:Chains in Brazil and Mexico are locking in frozen potato specifications to reduce kitchen labor and ensure fry texture consistency across locations.
- Air fryer penetration:Residential air fryer ownership in the United States is expanding addressable demand for par-fried products optimized for rapid rethermalization without oil immersion.
Market Restraints
- Input cost volatility:Natural gas and electricity price spikes in Germany and the Netherlands are compressing margins at freezing-intensive processing facilities.
- Supply concentration risk:Columbia Basin potato sourcing dominance creates weather and water-rights exposure for North American fry manufacturers.
- Fresh potato substitution:Food service operators in Italy and Spain retain partial fresh-cut preparation for premium positioning, limiting frozen penetration.
Strategic Opportunities
- Underpenetrated Indian food service:Quick-service infrastructure buildout in Mumbai and Bangalore offers volume expansion for processors establishing local cold-chain partnerships.
- USDA organic certification pathways:Evolving standards for processed potato products enable premium positioning in US retail channels seeking clean-label differentiation.
- Direct-to-foodservice distribution:Bypassing traditional wholesale layers through temperature-controlled last-mile networks is capturing margin pools in the United Kingdom.
Industry Challenges
- Food processing technician scarcity:Automated line maintenance and HACCP compliance expertise gaps are bifurcating operational reliability between capital-intensive and labor-dependent plants.
- Freezing tunnel capex intensity:Individual quick freezing (IQF) system upgrades require substantial capital outlays that strain mid-tier processor balance sheets.
- REACH chemical compliance timelines:European coating and processing aid re-authorization delays are forcing reformulation cycles that disrupt production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Potato Market |
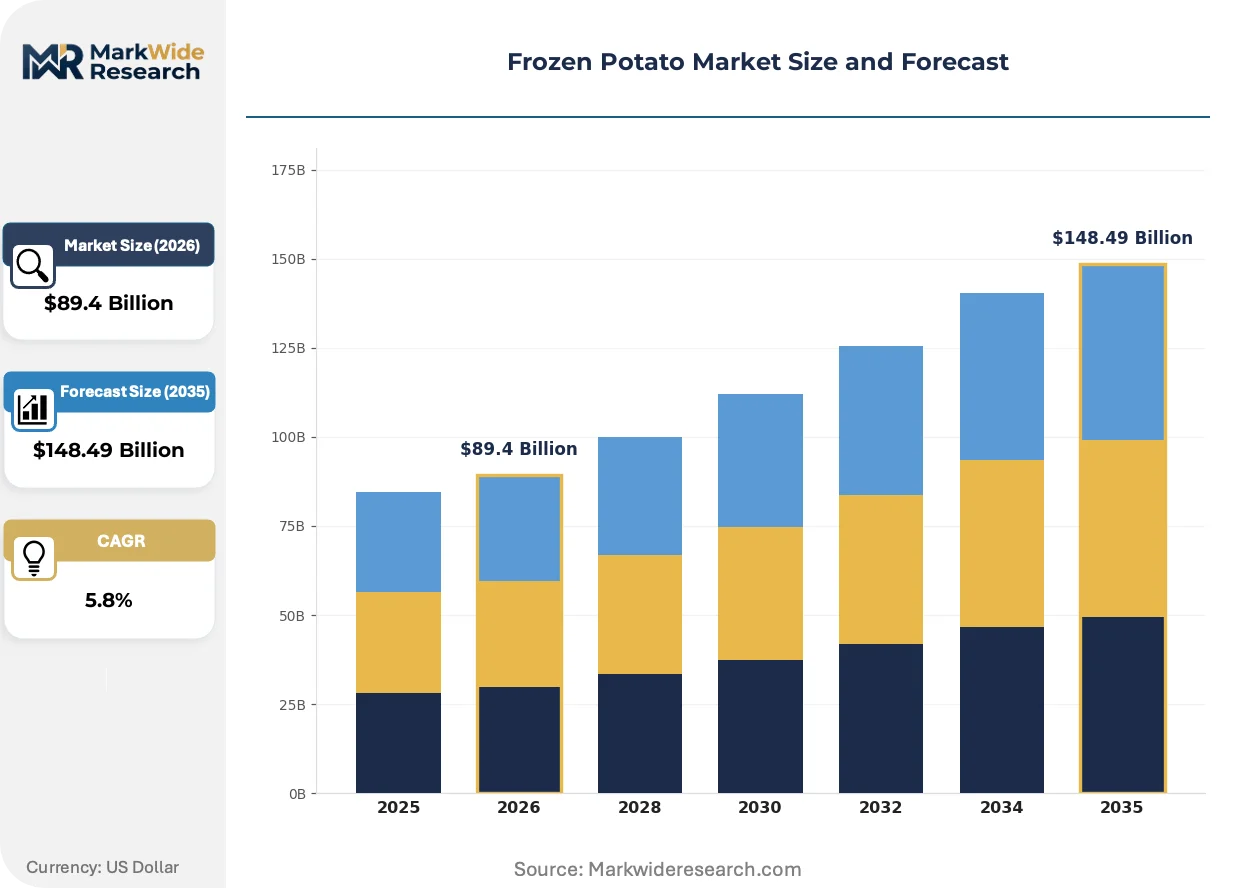
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $148.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: French Fries, Mashed Potatoes, Potato Wedges, Hash Browns End User: Restaurants, Quick Service Outlets, Grocery Stores, Food Service Providers Packaging Type: Bulk Packaging, Retail Packaging, Vacuum Packs, Stand-Up Pouches Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | McCain Foods Limited, Lamb Weston Holdings, Inc., J.R. Simplot Company, Aviko Holding BV, Farm Frites International B.V, Cavendish Farms, Agristo NV, Clarebout Potatoes, Agrarfrost Holding GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Potato Market Emerging Trajectories
Energy recovery systems and alternative freezing technologies are compressing the carbon intensity of frozen potato manufacturing. These shifts are reshaping facility design priorities and supplier selection criteria across major processing regions.
Mechanical vapor recompression (MVR) evaporators are capturing waste heat from blanching operations for reuse in pre-heating and drying stages. European processors in Belgium and the Netherlands are deploying MVR systems at scale to meet EU Green Deal energy benchmarks. This heat integration architecture is displacing conventional steam-based processing configurations that rely on external fuel inputs.
REACH chemical authorization protocols are restricting certain anti-oxidant coatings previously used to manage fry color consistency. Processors are reformulating surface treatments or accelerating enzymatic browning inhibition research to maintain product specifications. French fry and specialty potato product categories face the steepest compliance timelines, with German and French facilities leading substitution efforts.
Smaller-portion resealable retail formats are capturing convenience-oriented household demand previously served by bulk food service packs. Supermarket chains in the United States and United Kingdom are expanding private-label frozen potato offerings in 500-750 gram stand-up pouches. This channel migration is most visible in suburban markets where air fryer ownership and home meal preparation frequency are both rising.
Frozen Potato Market Segmentation
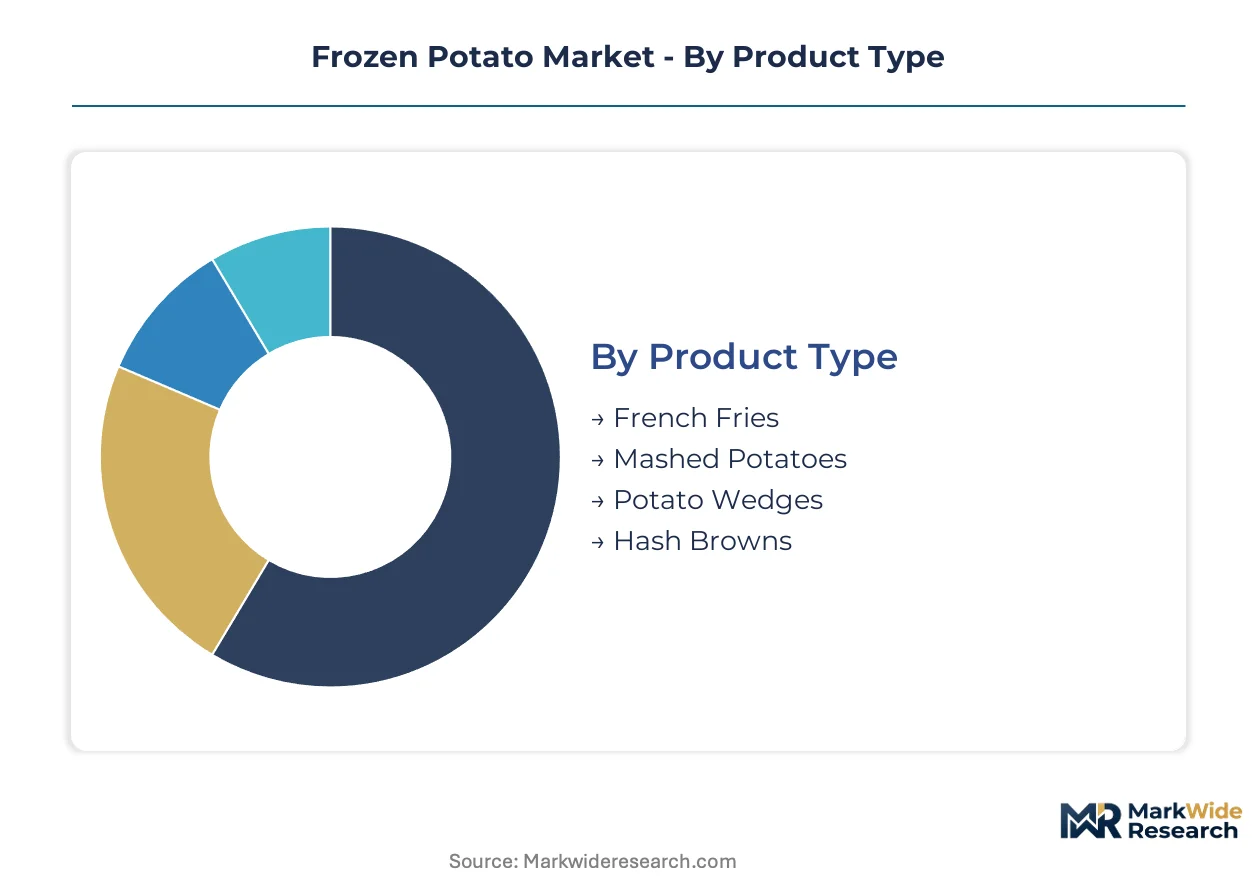
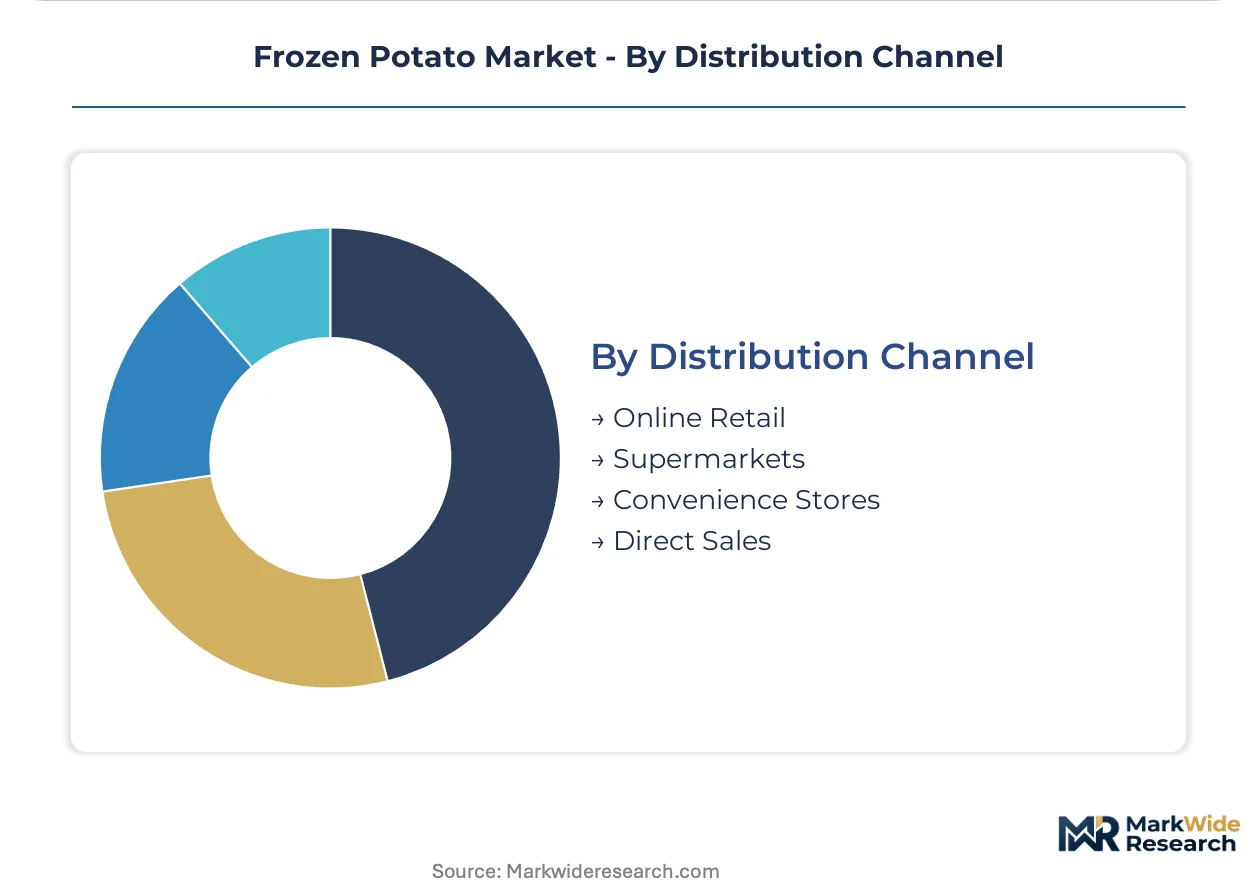
Frozen potato segmentation reveals how product form, channel access, and packaging economics determine margin capture. Substitution pressures from fresh preparation and alternative starches vary sharply across these dimensions, reshaping where processors allocate formulation and distribution resources.
Product Type:
Fresh-cut substitution pressure concentrates in formats where operators retain kitchen labor capacity, while par-fried segments defend share through rethermalization consistency.
- French Fries:Par-fried strips with defined moisture content and starch retrogradation profiles engineered for consistent crisping. Quick service outlets in Brazil and Mexico are locking in specifications to eliminate fryer variability across franchise locations.
- Mashed Potatoes:Dehydrated or frozen purees with butter and seasoning inclusions, reconstituted via steam-table or microwave. Institutional food service in Germany favors bulk formats for cafeteria throughput, though fresh mash retains share in premium Italian dining.
- Potato Wedges:Skin-on cut segments with thicker cross-sections than fries, blanched to partial cook. Demand clusters in UK pub chains and US casual dining where texture differentiation commands menu placement.
- Hash Browns:Shredded or formed potato cakes, par-fried for griddle finish. US breakfast-focused chains and home air fryer preparation are expanding addressable demand for rapid-cook formats.
French Fries anchors the volume base while Hash Browns gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive automated prep from labor-dependent fresh preparation, determining frozen penetration depth.
- Restaurants:Full-service establishments balancing labor costs against premium positioning through partial fresh-cut retention. Spanish and Italian operators source frozen for volume items while hand-cutting for signature dishes.
- Quick Service Outlets:Chains with standardized menu architectures and minimal kitchen footprints. Brazilian expansion is pulling procurement volume toward Latin America as infrastructure modernizes in São Paulo and Rio de Janeiro.
- Grocery Stores:Retail intermediaries stocking frozen aisles for home preparation. US suburban markets with high air fryer ownership are expanding resealable format placement.
- Food Service Providers:Institutional distributors serving schools, hospitals, and corporate cafeterias. EU Green Deal energy standards are forcing cold-chain upgrades for contract retention.
Quick Service Outlets command the largest procurement volumes while Grocery Stores expands most quickly through convenience-oriented format innovation.
Packaging Type:
Margin capture potential diverges between commodity bulk flows and value-added retail formats with branding opportunities.
- Bulk Packaging:Food service sacks and totes optimized for high-volume fryer loading. US and UK distributors favor 10-20kg formats for restaurant back-of-house efficiency.
- Retail Packaging:Branded cartons and bags for supermarket freezer placement. Stand-up pouches with resealable closures are displacing traditional boxes in US and UK suburban markets.
- Vacuum Packs:Oxygen-barrier films extending shelf life for premium specialty cuts. Belgian and Dutch processors deploy modified atmosphere packaging for export logistics.
- Stand-Up Pouches:Flexible format with zipper closure and high graphic surface area. UK supermarket private-label expansion is driving 500-750 gram SKU proliferation.
Bulk Packaging underpins food service economics while Stand-Up Pouches climbs fastest on convenience-premium positioning.
Distribution Channel:
Channel control determines margin retention versus wholesale layer capture, with temperature integrity as the critical operational variable.
- Online Retail:Direct-to-consumer frozen delivery requiring insulated packaging and rapid fulfillment. UK grocery platforms are expanding frozen potato SKUs with same-day delivery guarantees.
- Supermarkets:Branded and private-label placement in dedicated freezer infrastructure. US chains are reallocating aisle space toward air fryer-compatible formats.
- Convenience Stores:Limited assortment of high-velocity items for immediate consumption preparation. Urban grab-and-go demand in Brazilian cities is expanding frozen snack availability.
- Direct Sales:Processor-to-operator relationships bypassing distributor markups. UK temperature-controlled last-mile networks are enabling food service margin capture.
Supermarkets maintains the broadest reach while Direct Sales expands most quickly through cold-chain disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Brazil channels frozen potatoes predominantly through quick-service expansion, while European markets balance retail convenience formats against food service bulk procurement under tightening energy regulations.
United States
Air fryer penetration in suburban households is accelerating demand for par-fried retail formats optimized for rapid rethermalization. FDA food safety modernization frameworks are elevating traceability requirements throughout frozen potato value chains. The Columbia Basin processing cluster anchors North American supply, with massive freezing-intensive facilities concentrated in Washington and Oregon.
Germany
Institutional food service in cafeterias and hospitals favors bulk mashed potato formats for throughput efficiency. EU Green Deal cold-chain mandates are forcing processors to retrofit freezing tunnels with lower-GWP refrigerants. The Lower Saxony potato processing belt is leading equipment replacement cycles to secure compliance certainty ahead of enforcement deadlines.
Brazil
Quick-service infrastructure buildout in São Paulo and Rio de Janeiro is pulling procurement volume toward Latin America as chains standardize menu architectures. ANVISA food safety protocols are tightening import inspection regimes for frozen potato products. Modernized cold-chain partnerships in southeastern metro corridors are enabling processor market entry.
Netherlands
Export-oriented processors are deploying mechanical vapor recompression systems to meet EU Green Deal energy benchmarks for blanching and drying operations. REACH chemical authorization timelines are restricting certain anti-oxidant coatings used for fry color consistency. The Flevoland polder region concentrates large-scale freezing facilities serving continental European distribution networks.
United Kingdom
Supermarket private-label expansion is driving proliferation of 500-750 gram stand-up pouch formats for convenience-oriented household demand. Temperature-controlled last-mile networks are enabling direct-to-foodservice distribution that bypasses traditional wholesale markups. Processing activity clusters in eastern England near major port infrastructure for continental supply integration.
Frozen Potato Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in frozen potato manufacturing. The upper tier commands cost advantages through captive supply chains from seed breeding through distribution, while mid-scale competitors concentrate on regional market penetration or specialty texture formulations. Strategic archetypes include vertical integrators controlling agricultural inputs, regional specialists optimizing for local taste preferences, and private-label contractors serving retailer specifications. Dominant competitive moves center on freezing technology upgrades for regulatory compliance and direct distribution partnerships that disintermediate wholesale layers.
Among North American processors, McCain Foods Limited exemplifies the integrated archetype through upstream control over agricultural inputs, while Lamb Weston Holdings, Inc. anchors scale-driven supply security through massive processing footprints. J.R. Simplot Company occupies a differentiation position via proprietary variety development optimized for specific end-use applications. These three represent the structural poles around which competitive dynamics organize: cost leadership through integration, volume security through scale, and premium positioning through product-specific innovation.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Lamb Weston Holdings, Inc. |
| J.R. Simplot Company |
| Aviko Holding BV |
| Farm Frites International B.V |
| Cavendish Farms |
| Agristo NV |
| Clarebout Potatoes |
| Agrarfrost Holding GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal cold-chain certification gates both supplier qualification and price differentiation simultaneously, forcing processors to absorb retrofit costs or surrender premium positioning in continental European markets. Frozen potato pricing stratifies across organic-certified, energy-efficient, and conventional tiers as buyers weigh compliance certainty against procurement outlays.
Pricing Analysis
Long-term offtake contracts dominate procurement between quick-service chains and major processors, locking in volume commitments that insulate against spot-market potato price swings. Price differentiation rests on organic certification status and blast-freezing energy efficiency ratings, with EU-compliant facilities commanding premiums over legacy configurations. Pricing pressure intensifies in bulk food service tiers as natural gas and electricity cost spikes in Germany and the Netherlands compress freezing-intensive margins. Quick-service outlets exhibit highest price sensitivity due to standardized menu economics, while premium retail channels absorb modest premiums for resealable convenience formats.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container corridors and reefer availability constraints on trans-Atlantic lanes are elevating inbound logistics costs for European processors dependent on North American seed potato genetics. Supply concentrates in the United States, Belgium, and the Netherlands, with the Columbia Basin and Flevoland polder anchoring processing capacity. Raw material flows draw from specialized chipping potato varieties, lower-GWP refrigerant systems, and modified-atmosphere packaging films. Single-source vulnerability concentrates in Columbia Basin water-rights exposure, where drought stress threatens contract fulfillment. Distribution runs through temperature-controlled food service distributors and direct-to-operator last-mile networks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen potato markets reward service-attach strategies as temperature-controlled logistics partnerships and fryer equipment leasing expand faster than commodity product sales. Recurring revenue from cold-chain compliance monitoring and rethermalization training contracts deepens account stickiness beyond transactional procurement.
For Market Incumbents: Shield market position by accelerating mechanical vapor recompression deployment ahead of EU Green Deal enforcement deadlines, securing compliance premiums that stranded competitors forfeit. Deepen backward integration into proprietary potato breeding programs to reduce dependency on Columbia Basin water-rights volatility. Lock in multi-year quick-service contracts in Brazil before infrastructure buildout attracts new processor entry.
For New Entrants and Emerging Players: Anchor in Indian quick-service corridors around Mumbai and Bangalore where cold-chain partnerships remain underdeveloped and local processing capacity lags demand growth. Target stand-up pouch retail formats in UK suburban markets where air fryer penetration outpaces incumbent SKU proliferation. Pursue co-manufacturing arrangements with established European processors to bypass freezing tunnel capex barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blast-freezing equipment upgrades as EU Green Deal mandates force replacement cycles. Five-to-ten-year viability favors processors with demonstrated compliance execution and captive agricultural supply. Acquisition screening should prioritize mid-scale European operators with MVR installation progress and established quick-service contract books. The signal to watch is ANVISA import inspection regime tightening in Brazil, which would advantage local processing capacity over import-dependent distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Deployment | EU Green Deal energy benchmarks in Belgium and the Netherlands favor early adopters with compliance premiums. |
| Direct-to-Foodservice Distribution Buildout | Temperature-controlled last-mile networks in the United Kingdom capture wholesale margin pools. |
| Proprietary Variety Development | In-house breeding programs reduce Columbia Basin water-rights exposure for North American fry manufacturers. |
| Stand-Up Pouch Format Expansion | UK supermarket private-label proliferation drives 500-750 gram SKU growth in suburban markets. |
| Brazilian Cold-Chain Partnership Formation | São Paulo and Rio de Janeiro infrastructure modernization enables processor market entry ahead of ANVISA tightening. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with frozen potato processing executives, quick-service procurement directors, cold-chain logistics operators, and food service distribution managers; and secondary validation through EU customs trade databases, ECHA REACH authorization filings, USDA organic certification records, and SEC processor disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-user channel, packaging format, and regional regulatory clusters.
Across the projection horizon, the analytical framework segmented value and volume trajectories by French fry, mashed potato, wedge, and hash brown categories; by quick-service, restaurant, grocery, and institutional end users; and by bulk, retail, vacuum, and stand-up pouch packaging configurations. CAGRs derived from processor capacity expansion announcements, quick-service outlet buildout rates in Brazil and India, and air fryer household penetration curves in the United States. Energy cost elasticity and water-rights risk premiums informed margin compression scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and Brazilian quick-service infrastructure investment; material deviation in regulatory timelines or macroeconomic conditions would warrant model refresh. Practitioners should keep alternative scenarios live as REACH chemical re-authorization timelines and Columbia Basin hydrological stress indicators evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Europe Dehydrated Food Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market