
 Roasted Corn Market | 2026-2036
Roasted Corn Market Size, Share, and Industry Trends Forecast 2026-2036
Roasted Corn Market Analysis
The EU Green Deal is recalibrating sourcing standards across European roasted corn supply chains, pushing processors toward regenerative agriculture verification. Del Monte Food, Inc. leverages its integrated North American corn procurement network to secure consistent heirloom varietals. SunOpta Inc. anchors its competitive position through certified organic roasting facilities that meet stringent EU import criteria. Barberá Snacks SL dominates Iberian private-label production with specialized hot-air roasting technology that reduces acrylamide formation.
Roasted corn consists of mature maize kernels subjected to dry-heat treatment at temperatures between 150°C and 200°C until achieving moisture content below 10 percent, yielding a shelf-stable snack with enhanced Maillard-derived flavor compounds. The product serves commercial foodservice operators and retail channels seeking clean-label alternatives to fried snacks. Traditional flavor profiles occupy the largest volume share in Latin American and Mediterranean markets where unseasoned or lightly salted preparations align with established consumption habits. Spicy variants represent the fastest-expanding segment as chili-lime formulations gain traction among younger demographics in North American convenience stores. Online Retail distribution channels are capturing disproportionate growth in premium single-serve formats, though Supermarkets retain dominant throughput for family-sized bags.
FDA nutrition labeling requirements and USDA organic certification standards govern product composition and marketing claims in the United States, while EFSA acrylamide benchmarks shape European processing protocols and equipment investment decisions. India's FSSAI packaged food safety regulations mandate specific moisture and microbial limits that determine import eligibility for regional processors. Stakeholders must monitor evolving contaminant thresholds and origin-verification mandates to maintain cross-border market access and avoid supply disruption.
Market Dynamics
EU Green Deal compliance mandates are forcing roasted corn processors to reconfigure sourcing networks toward regenerative agriculture verification, creating asymmetric compliance burdens across European and non-European supply bases.
Growth Catalysts
- Clean-label snack migration:Foodservice operators in Mexico, India, and Thailand are replacing fried alternatives with dry-heat roasted formats to meet consumer demand for minimally processed options.
- EFSA acrylamide thresholds:European processors investing in hot-air roasting technology gain preferential access to EU retail channels with stricter contaminant benchmarks than competing imports.
- Night-market urbanization:Southeast Asian metropolitan clusters are concentrating volume through street vendor networks that favor single-serve roasted corn formats over packaged alternatives.
Market Restraints
- Heirloom varietal concentration:North American corn belt sourcing dominance creates vulnerability to climate-induced yield volatility in specific Midwestern counties.
- Organic certification lag:USDA organic and EU organic conversion timelines stretch 24-36 months, freezing new entrants out of premium private-label contracts.
- Maillard reaction inconsistency:Batch-to-batch flavor compound variation in traditional drum roasting limits standardization for multinational quick-service restaurant specifications.
Strategic Opportunities
- Online Retail premiumization:Direct-to-consumer channels in North America are capturing margin expansion through single-serve heritage varietal offerings unavailable in conventional supermarkets.
- Chili-lime flavor innovation:Younger demographics in US convenience stores are driving fastest-expanding segment growth for spicy variants with regional pepper sourcing stories.
- FSSAI import alignment:Indian packaged food safety regulations create first-mover advantage for processors achieving moisture and microbial compliance ahead of regional competitors.
Industry Challenges
- Regenerative verification talent scarcity:Agricultural auditors with EU-recognized regenerative credentials remain concentrated in limited geographies, creating certification bottlenecks.
- Hot-air roasting capex barriers:Acrylamide-reducing equipment upgrades demand capital allocations that mid-scale Iberian and Mediterranean processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roasted Corn Market |
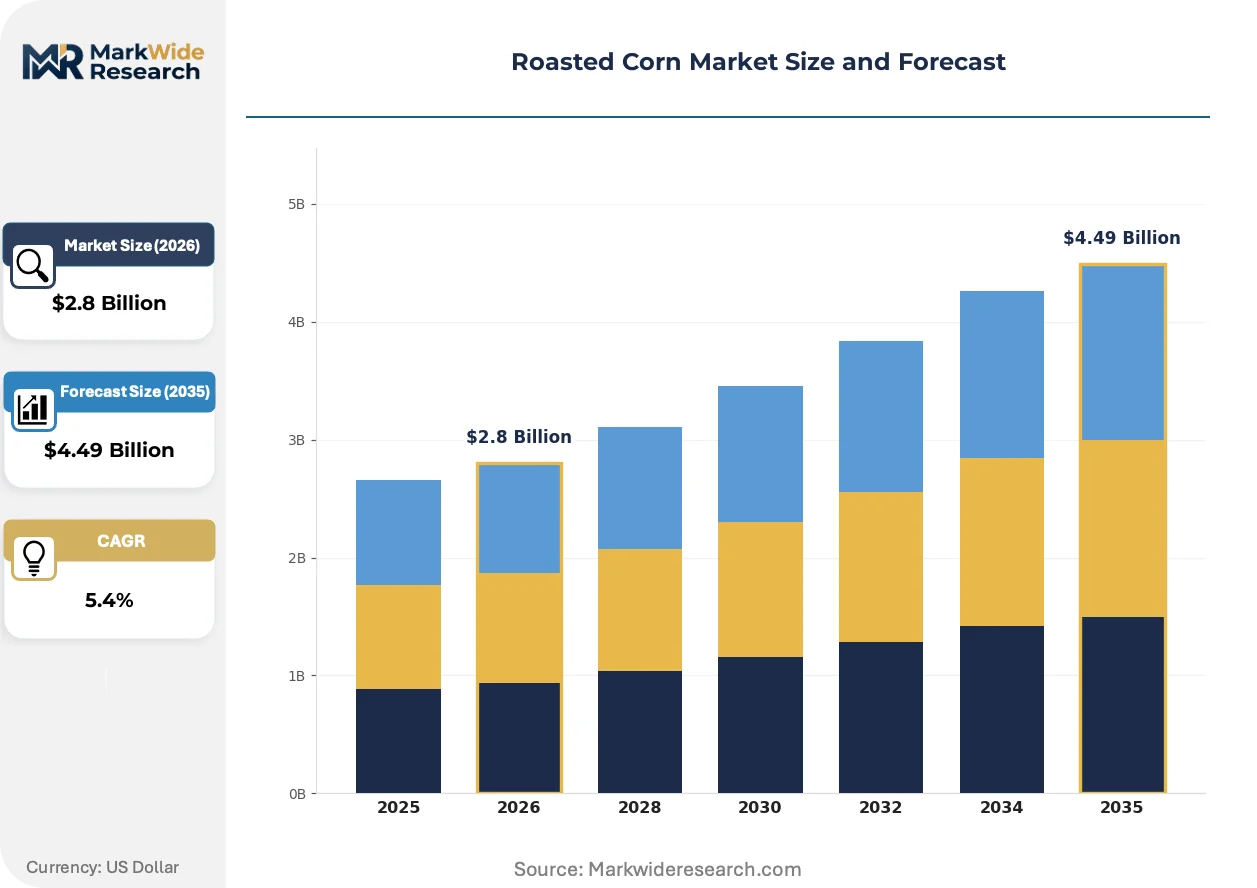
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Spicy, Sweet, Savory Packaging Type: Bags, Cups, Trays, Boxes Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Festivals End User: Households, Restaurants, Food Trucks, Caterers |
| Companies Covered | Del Monte Food, Inc., SunOpta Inc., H.J. Heinz Company Brands LLC, N.L. Food Industries, Barberá Snacks SL, Laxcorn, AIM Biscuits, Vaishnav Food Products, The Naked Nut Growers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roasted Corn Market Emerging Trajectories
Processing technology and verification protocols are restructuring competitive advantage in roasted corn, with equipment choices and compliance architectures now determining market access more than brand recognition or scale.
Infrared-hot air hybrid roasting systems are rewriting quality consistency benchmarks for Maillard-derived flavor formation. Quick-service restaurant chains in Thailand and Mexico are piloting these installations to reduce acrylamide variability while maintaining throughput. The technology is compressing the performance gap between artisanal drum methods and industrial-scale production.
REACH chemical safety registration and EU Green Deal sustainable agriculture provisions are reshaping European import eligibility for processed corn products. Processors must now document regenerative practices across upstream corn cultivation to maintain supermarket distribution contracts. Iberian private-label manufacturers face the steepest compliance curve given legacy reliance on conventional sourcing.
Certification-driven procurement now governs premium roasted corn purchasing decisions in North American and European retail channels. Buyers are unbundling organic, non-GMO, and regenerative claims into separate specification tiers with distinct pricing bands. This pattern concentrates volume with processors holding multiple verified credentials rather than single-certification competitors.
Roasted Corn Market Segmentation
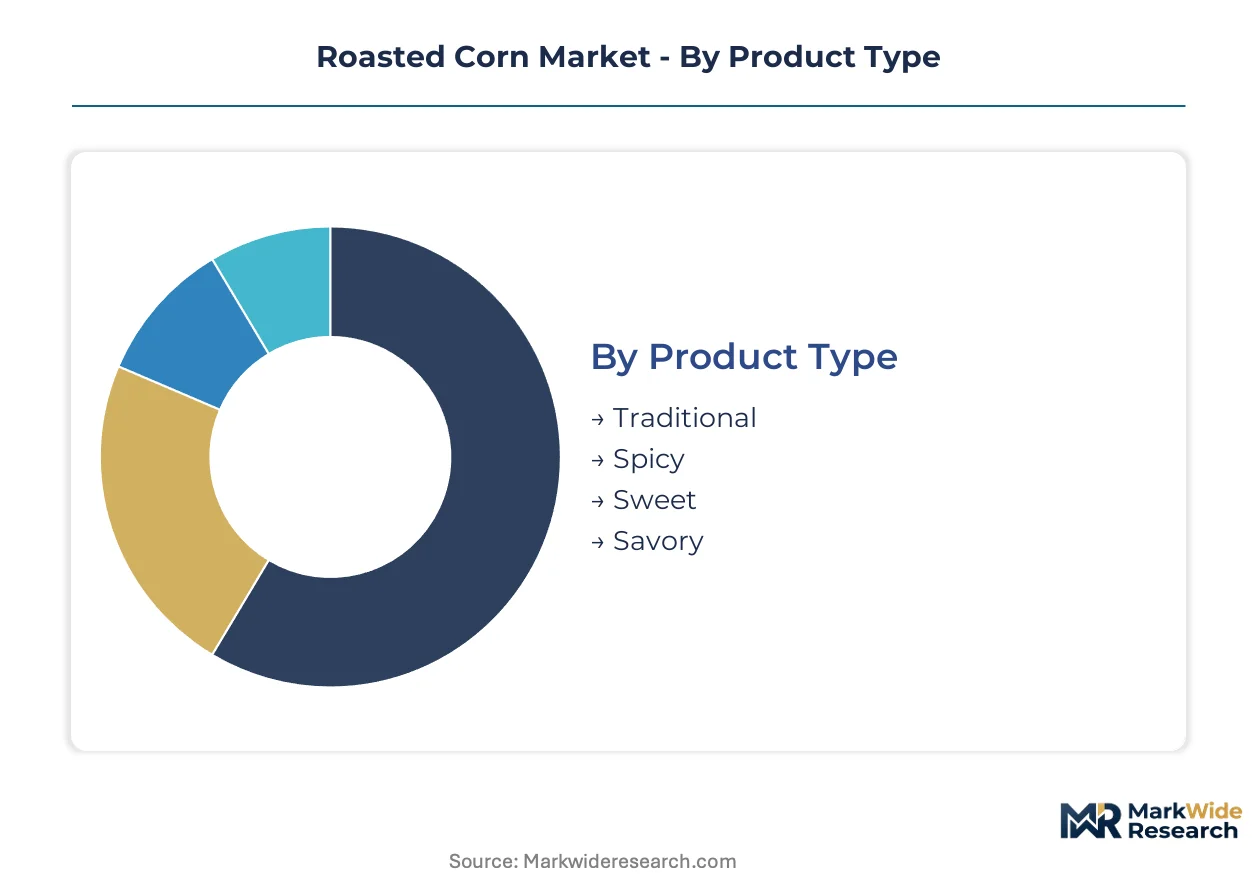
Segmentation in roasted corn reveals how flavor innovation, packaging convenience, and channel access determine margin capture. Each dimension exposes different competitive moats between artisanal producers and industrial processors.
Product Type:
Customization intensity varies sharply across this spectrum, from heritage recipes requiring minimal adaptation to formulations demanding continuous R&D iteration.
- Traditional:Unseasoned or lightly salted preparations dominate Latin American and Mediterranean retail shelves. Mexican street vendors and Spanish tapas bars anchor volume for this segment, where consumers reject flavor complexity as inauthentic.
- Spicy:Chili-lime and regional pepper formulations are climbing the fastest among North American convenience store shoppers. Younger demographics in US urban centers drive disproportionate growth for single-serve spicy SKUs with transparent sourcing narratives.
- Sweet:Honey-glazed and caramelized variants target Asian metropolitan night markets where dessert-snack hybrid positioning commands premium pricing.
- Savory:Cheese-dusted and herb-infused recipes serve European private-label contracts requiring clean-label ingredient decks without artificial flavor enhancers.
Most installed capacity flows through Traditional. Expansion is steepest in Spicy.
Packaging Type:
Cost-to-convenience ratios segment this category, with premium single-serve formats commanding 3-4x unit economics against bulk family packs.
- Bags:Flexible film and paper-based pouches dominate supermarket throughput for family-sized roasted corn offerings. Multi-layer barrier constructions extend shelf life for organic variants requiring oxygen exclusion.
- Cups:Single-serve rigid containers capture food truck and stadium vendor demand where consumption immediacy outweighs material cost premiums.
- Trays:Thermoformed bases with lidding film serve catering and hospitality channels requiring portion-controlled presentation for buffet-style service.
- Boxes:Corrugated and folding carton formats support gift-oriented premium positioning in direct-to-online retail channels.
Volume concentrates in Bags. Margin expansion is strongest in Cups.
Distribution Channel:
Customer acquisition economics diverge dramatically between high-frequency impulse channels and relationship-driven institutional sales.
- Supermarkets:Multi-brand shelf sets and promotional slotting fees govern access for heritage and organic roasted corn lines. Iberian and Mexican retail chains concentrate procurement with processors holding EU organic and regenerative certifications.
- Convenience Stores:Chili-lime and spicy single-serve formats are gaining share fastest among US c-store operators replacing fried snack facings with clean-label alternatives.
- Online Retail:Direct-to-consumer platforms enable heritage varietal storytelling and subscription pricing unavailable in conventional grocery.
- Food Festivals:Seasonal event circuits in Southeast Asian urban clusters drive trial volume for artisanal producers testing flavor innovations before retail scaling.
Throughput dominance sits with Supermarkets. Channel mix is shifting fastest toward Online Retail.
End User:
Specification complexity escalates from household impulse purchase to institutional procurement with documented provenance requirements.
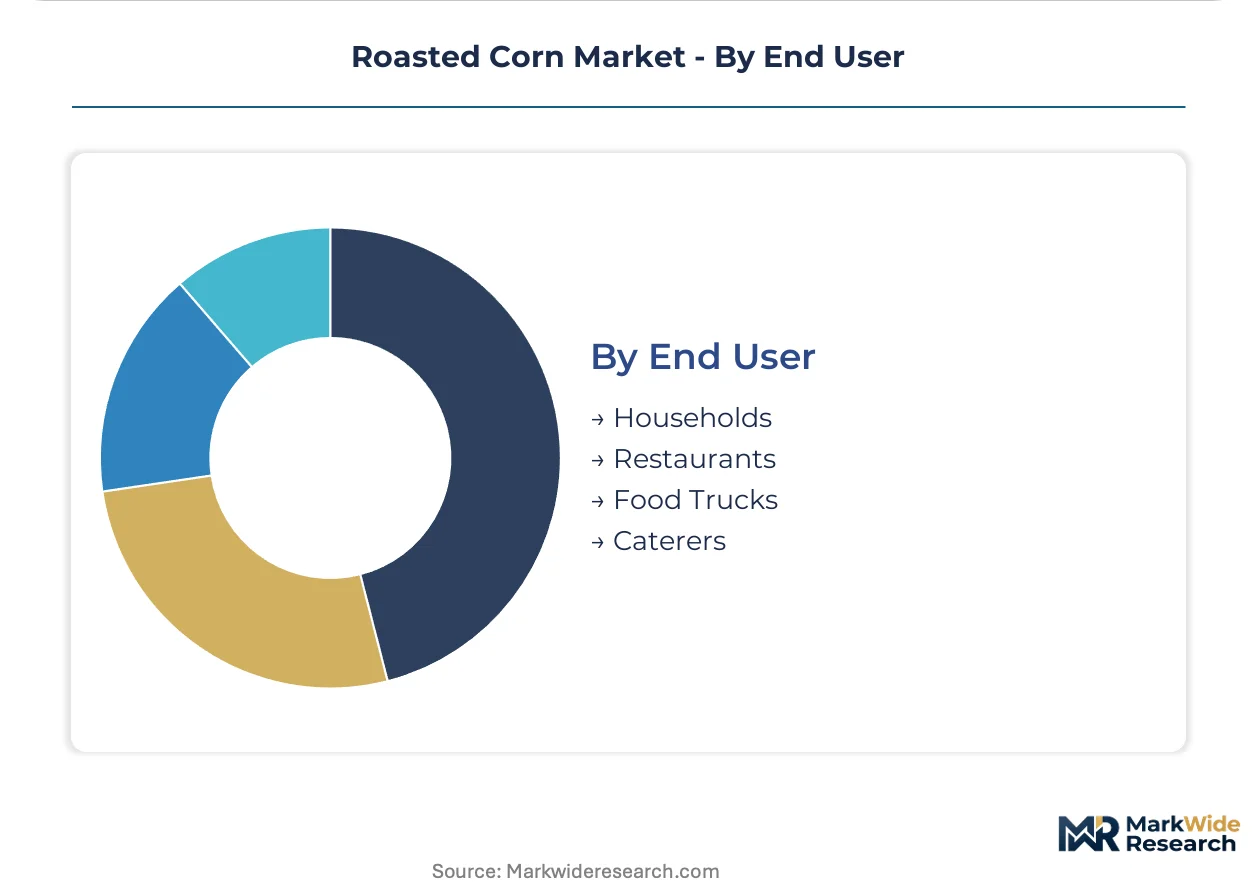
- Households:Retail-packaged consumption across Latin American and Mediterranean markets favors traditional unseasoned formats in family-sized bags.
- Restaurants:Quick-service chains in Thailand and Mexico specify infrared-hot air hybrid roasted corn to meet acrylamide thresholds while maintaining throughput consistency.
- Food Trucks:Mobile operators in Indian metropolitan centers favor cup-packaged spicy variants for night-market service with minimal preparation infrastructure.
- Caterers:Event-service providers in European markets require tray-based portion control and batch-level traceability for allergen management.
Volume flows predominantly through Households. Procurement sophistication is advancing most quickly in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roasted corn production traces its industrial lineage to Mexican street food traditions, where open-flame preparation methods established quality benchmarks later adopted by commercial processors. These artisanal roots continue shaping equipment design and flavor standards across export markets. Contemporary demand clusters reflect both heritage consumption patterns and emerging clean-label preferences.
Mexico
Street vendors in Mexico City and Oaxaca anchor traditional unseasoned roasted corn volume, with night-market operators driving single-serve cup format adoption. The Secretariat of Economy's NOM standards for processed corn products establish moisture and labeling requirements that govern domestic manufacturing. Jalisco's Guadalajara metropolitan cluster concentrates industrial roasting capacity serving both domestic retail and US export channels.
United States
Convenience store operators in Texas and California are replacing fried snack facings with chili-lime roasted corn variants targeting younger demographics. FDA nutrition labeling requirements and USDA organic certification standards govern product composition and interstate commerce. The Midwest corn belt counties in Iowa and Illinois supply heirloom varietals to processors seeking heritage provenance claims for premium positioning.
Spain
Iberian private-label manufacturers face steep compliance curves as EU Green Deal regenerative agriculture verification reshapes sourcing contracts for supermarket distribution. EFSA acrylamide thresholds drive hot-air roasting equipment investments among Barcelona and Valencia processors. Catalonia's industrial corridor concentrates specialized roasting technology providers serving Mediterranean export markets.
India
Food trucks in Mumbai and Delhi metropolitan centers favor spicy cup-packaged formats for night-market service with minimal preparation infrastructure. FSSAI packaged food safety regulations mandate specific moisture and microbial limits that determine import eligibility for regional processors. Maharashtra's Pune-Ahmednagar belt hosts emerging roasting facilities targeting compliance ahead of regional competitors.
Thailand
Quick-service restaurant chains in Bangkok are piloting infrared-hot air hybrid roasting installations to reduce acrylamide variability while maintaining throughput consistency. The country's national food and drug administration oversees processed snack safety standards aligned with ASEAN harmonization initiatives. Chiang Mai's food processing zone attracts equipment providers serving Southeast Asian urban night-market networks.
Roasted Corn Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the roasted corn value chain, with integrated agricultural operations facing nimble private-label specialists. The market exhibits moderate consolidation, where three to five vertically integrated processors control bulk commodity supply while dozens of regional artisans capture premium heritage positioning. Strategic archetypes separate regenerative-certified organic operators from conventional scale players and equipment-technology licensors. Competitive moves concentrate on hot-air roasting capacity expansion and regenerative agriculture certification partnerships that secure EU retail access.
Within the integrated-processor tier, Del Monte Food, Inc. and SunOpta Inc. exemplify divergent geographic and certification strategies, with the former representing North American supply chain integration and the latter anchoring certified organic roasting infrastructure. Barberá Snacks SL occupies a specialized position among Iberian private-label manufacturers, reflecting the regional concentration of hot-air roasting technology adoption. These three entities collectively illustrate how equipment choices and compliance architectures now determine market access more than brand recognition or scale.
| Leading Market Players |
|---|
| Del Monte Food, Inc. |
| SunOpta Inc. |
| H.J. Heinz Company Brands LLC |
| N.L. Food Industries |
| Barberá Snacks SL |
| Laxcorn |
| AIM Biscuits |
| Vaishnav Food Products |
| The Naked Nut Growers |
| Others |
Supply Flow & Price Mechanics
Chicago Board of Trade corn futures volatility cascades through roasted corn supply chains into three distinct pricing tiers anchored by certification status and volume commitment levels. Premium organic and regenerative-certified SKUs command substantial uplifts over conventional bulk offerings, while spot-market processors absorb margin compression from input cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs roasted corn transactions, with EU organic and regenerative certifications driving the widest spreads. Price differentiation rests on verification tier and heirloom varietal provenance rather than brand equity alone. Cost compression in economy-grade bulk segments is intensifying as Midwestern climate volatility squeezes conventional corn belt yields. Quick-service restaurant chains exhibit lowest price sensitivity due to specification lock-in, while private-label supermarket buyers negotiate hardest on unit economics.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale quick-service restaurant demand through contracted volume commitments with specified acrylamide thresholds. Raw material sourcing concentrates in Iowa, Illinois, and Jalisco state, with heirloom varietal propagation tethered to specific Midwestern counties and Mexican highland microclimates. Processing equipment, specialized roasting drums, and infrared-hot air hybrid systems constitute critical capital dependencies. Single-source vulnerability runs through concentrated heirloom seed stock maintained by limited germplasm repositories. Distribution runs through Iberian private-label manufacturers for EU retail access and North American integrated processors for domestic foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance premiums and North American scale economies, with regenerative certification costs in Europe running substantially above Midwestern organic conversion timelines.
For Market Incumbents: Lock in regenerative agriculture partnerships across Jalisco and Guadalajara metropolitan clusters before auditor capacity constraints tighten further. Secure captive supply of heirloom seed varieties through germplasm licensing agreements to defend against climate-induced yield volatility in specific Midwestern counties. Hot-air roasting capacity expansion in Barcelona and Valencia industrial corridors will preserve EU supermarket access as EFSA acrylamide thresholds tighten. For New Entrants and Emerging Players: FSSAI packaged food safety regulations in India open a window for moisture-compliant processors to capture import share ahead of regional competitors lagging on microbial limit certification. Target Maharashtra's Pune-Ahmednagar belt for greenfield roasting facilities serving Mumbai and Delhi night-market networks. Lead with single-serve cup formats for food truck operators requiring minimal preparation infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale Iberian and Mediterranean processors face hot-air roasting capex barriers that integrated North American operators can finance through captive cash flow. Acquisition candidates include certified organic roasting facilities with EU import eligibility and established quick-service restaurant specifications. Watch infrared-hot air hybrid technology adoption rates among Thai quick-service chains as inflection indicator for equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | EU Green Deal verification unlocks premium supermarket shelf placement across Iberian retail chains. |
| Hot-Air Roasting Technology Deployment | Acrylamide-reducing equipment investments preserve EFSA-compliant market access for European processors. |
| Heirloom Varietal Supply Agreements | Captive seed stock agreements with Midwestern germplasm repositories mitigate climate yield volatility exposure. |
| Direct-to-Online Retail Channel Buildout | Subscription pricing for heritage varietal storytelling captures margin unavailable in conventional grocery. |
| FSSAI Compliance-First Market Entry | Moisture and microbial certification ahead of Indian competitors secures import eligibility for regional processors. |
Methodological Framework
Multiple input streams — primary interviews with roasting equipment manufacturers, procurement leads at quick-service restaurant chains, and regulatory affairs specialists at FSSAI and EFSA — were reconciled against secondary validation from customs trade records, SEC 10-K filings of integrated food processors, and EU Green Deal implementation documentation. Conversations with category buyers at Iberian supermarket chains and street vendor network operators in Mexico City and Bangkok supplied channel-level demand signals. Bottom-up volume triangulation across product type, packaging format, and distribution channel was cross-checked against top-down value estimates from trade flow analysis.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation modeling spanning flavor profile, packaging convenience tier, and end-user specification complexity. CAGRs were derived from trend extrapolation of clean-label snack migration patterns and night-market urbanization trajectories, stress-tested against organic certification conversion timelines and hot-air roasting equipment penetration curves.
Revisions become necessary when EU Green Deal regenerative verification mandates accelerate, EFSA acrylamide thresholds tighten beyond current hot-air technology capabilities, or Midwestern heirloom corn yields experience sustained climate disruption. Forecasts reflect assumptions about auditor capacity expansion and equipment financing availability that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Protein Bar Market
Snacks
North America Potato Chips Market
Snacks
North America Pretzel Market
Snacks
Snack Bar Market
Snacks
Trail Mix Market
Snacks
Crackers Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Sweet Potato Chips Market
Snacks
Vegan Snacks Market
Snacks
South America Snack Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Argentina Snack Bar Market
Snacks
United States Energy Bar Market
Snacks
Low Calorie Snacks Market
Snacks
Saudi Arabia Snack Bar Market