
 Vegan Protein Balls Market | 2026-2036
Vegan Protein Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Balls Market Analytics
Pea protein is expanding its share of formulations as manufacturers reduce dependence on soy and whey isolates. Bounce Foods Ltd leverages vertical integration from ingredient sourcing to co-manufacturing, sustaining cost advantages across European distribution. The Protein Ball Co anchors its portfolio in clean-label positioning, competing through transparent supply chain storytelling that resonates with allergen-sensitive buyers.
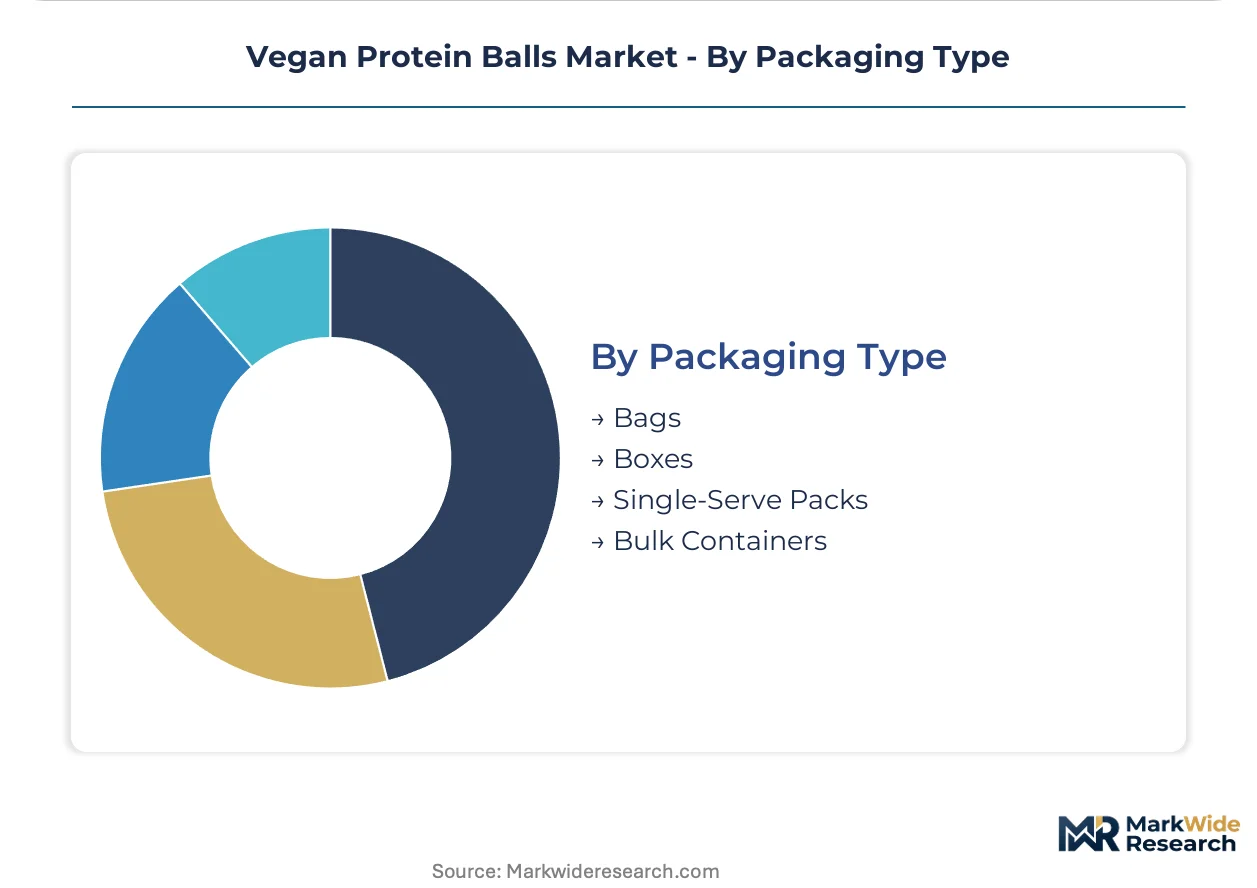
Vegan protein balls are shelf-stable, minimally processed spherical snacks typically comprising plant protein isolates, nut or seed binders, and natural sweeteners, formed through cold-pressing or extrusion and designed to deliver 8–15 grams of protein per serving for on-the-go nutrition. Energy bites occupy the dominant volume position due to lower price points and broader retail penetration, while meal replacement balls command premium margins through higher protein density and fortified micronutrient profiles. Single-serve packs lead packaging innovation as convenience retailers prioritize grab-and-go formats over bulk containers.
The FDA regulates nutrition labeling and allergen declarations for plant-based snacks sold in the United States, while the USDA oversees organic certification pathways that many vegan protein ball brands pursue for differentiation. The EFSA and EMA frameworks in Europe shape novel food approvals and health claim substantiation, directly influencing which functional benefits companies can communicate across member states. Stakeholders must monitor evolving protein content thresholds and clean-label enforcement intensity as regulators tighten scrutiny on plant-based marketing claims.
Market Dynamics
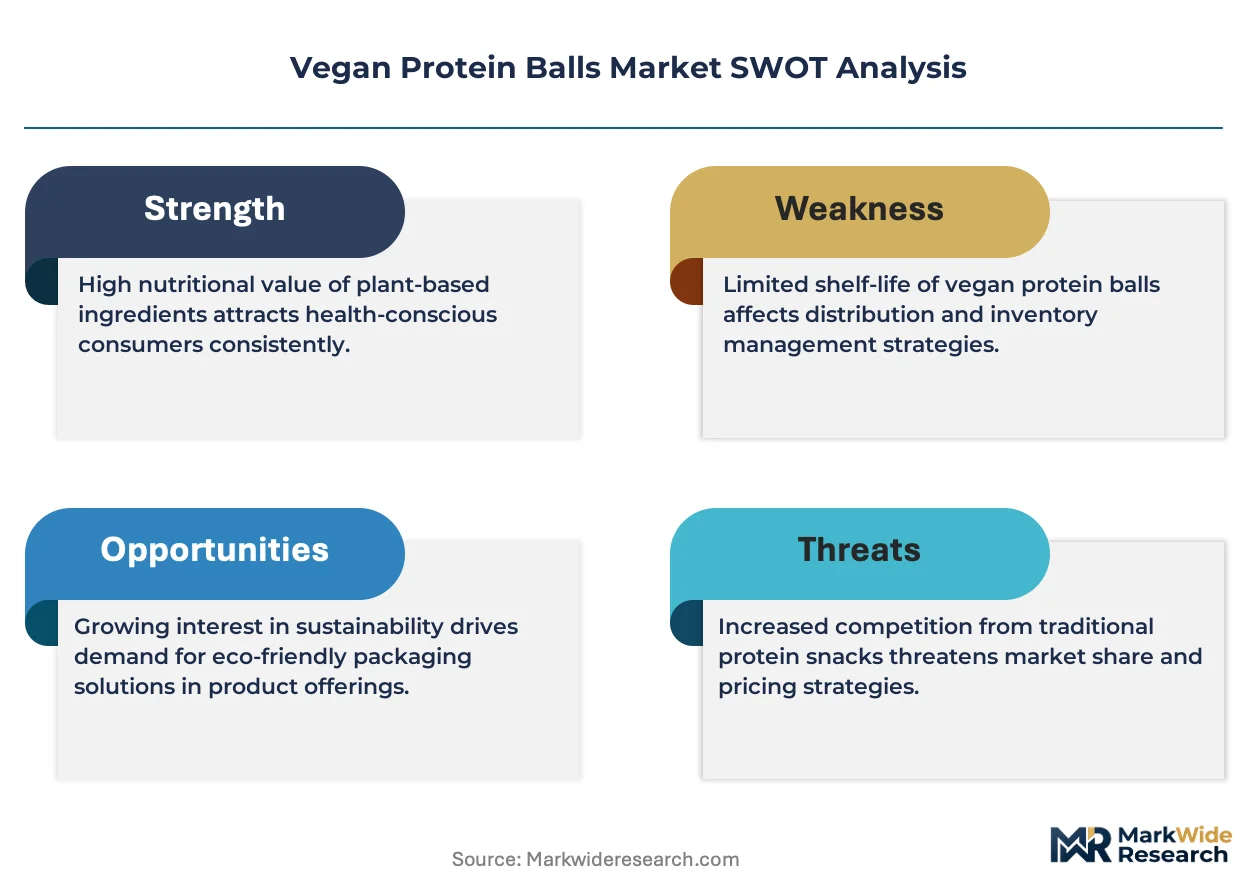
Clean-label enforcement by the FDA is compressing formulation timelines as brands reformulate to meet updated allergen declaration thresholds and protein content substantiation requirements. This regulatory pressure cascades through co-manufacturing networks, forcing ingredient qualification protocols that favor vertically integrated suppliers.
Growth Catalysts
- Fitness community penetration:Boutique gyms and CrossFit boxes in coastal metropolitan clusters are normalizing vegan protein balls as pre-workout standard fare, creating repeat purchase velocity through subscription locker programs.
- Pea protein substitution:Manufacturers are displacing soy isolates with pea protein concentrates to reduce allergen risk profiles and unlock EU novel food approvals under EFSA guidelines.
- Single-serve packaging mandate:Convenience retailers are prioritizing grab-and-go formats over bulk containers, aligning shelf space allocation with commuter traffic patterns in dense urban cores.
Market Restraints
- Input cost volatility:Organic nut butter and cold-pressed oil prices fluctuate with California almond harvest yields and Argentine peanut crop cycles, squeezing margin stability.
- Supply concentration risk:North American pea protein isolate production clusters in Manitoba and Saskatchewan, exposing brands to regional drought and rail logistics disruptions.
- Technical limitation:Cold-pressing equipment throughput caps at 2,500 units per hour for spherical formats, constraining scale economics versus extruded bar alternatives.
Strategic Opportunities
- Underpenetrated geography:German pharmacy chains (Apotheken) remain unserved by dedicated vegan protein ball sets, presenting first-mover shelf access before dm-drogerie market entry.
- Regulatory tailwind:USDA organic certification pathways offer premium price realization as retailers implement segregated planogram tiers for certified plant-based snacks.
- Distribution innovation:Direct-to-locker delivery partnerships with corporate wellness programs bypass traditional grocery slotting fees and capture worksite consumption occasions.
Industry Challenges
- Clean-label formulation expertise gap:R&D talent capable of binding 8–15g protein per serving without synthetic stabilizers commands premium compensation and extended recruitment cycles.
- Co-manufacturing certification timelines:BRC and SQF audits for allergen-free lines require 14–18 month qualification periods, delaying new product velocity.
- Legacy ERP integration friction:Lot traceability systems for organic ingredient chains conflict with standard food manufacturing software modules, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Balls Market |
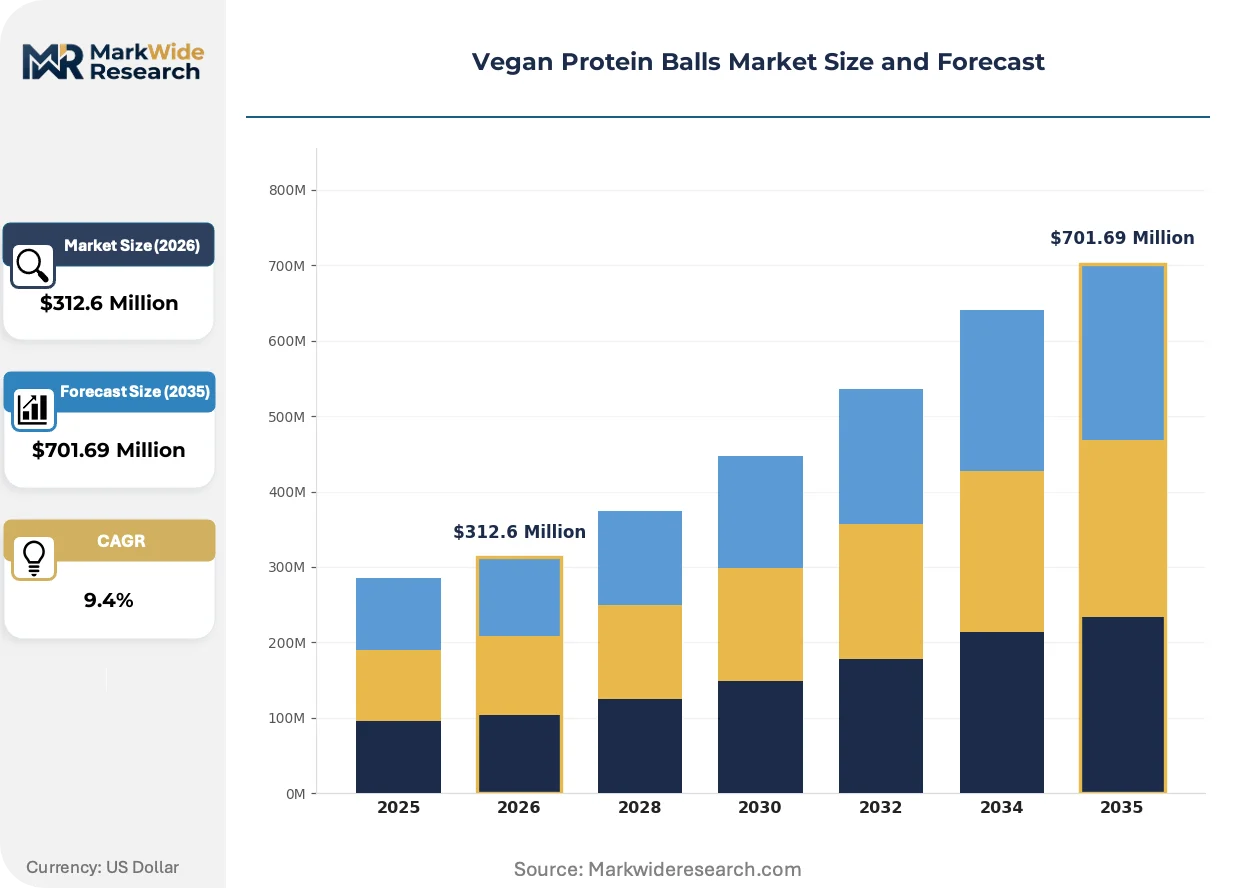
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $701.69 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Bites, Snack Balls, Meal Replacement Balls, Dessert Balls Main Ingredient: Pea Protein, Almond Flour, Chia Seeds, Oats Flavor Profile: Chocolate, Vanilla, Berry, Coconut Packaging Type: Bags, Boxes, Single-Serve Packs, Bulk Containers |
| Companies Covered | The Protein Ball Co, Bounce Foods Ltd, The Daily Nourish Co., Nibble Group Ltd, Tom & Luke Ltd, Creation Nation, Boostball, Health Lab, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Balls Market Evolving Landscape
Extrusion technology is fragmenting production economics as cold-pressing equipment becomes accessible to mid-scale entrants. Three forces are compressing the innovation cycle: equipment modularity, regulatory harmonization pressures, and channel-specific format requirements.
High-moisture extrusion is modularizing protein ball manufacturing by enabling continuous production runs that switch between base formulations without full line sanitation. Regional co-manufacturers in the Netherlands and California are adopting these systems to service multiple brand clients on shared shifts. The technology is modularizing capital deployment, allowing entrants to scale throughput in 40% increments rather than committing to dedicated lines.
REACH compliance deadlines for food-contact materials are forcing European brands to qualify alternative barrier films for oxygen-sensitive nut bases. The regulation is compressing packaging innovation timelines as suppliers race to validate compostable structures before 2026 enforcement windows. Brands targeting German and French retail are responding by dual-sourcing film inventories and accelerating shelf-life testing protocols.
Boutique fitness operators are consolidating procurement through centralized purchasing cooperatives that displace individual gym owner decision-making. These buying groups negotiate exclusive flavor rotations and white-label supply agreements, capturing margin that previously flowed to distributors. The shift is most visible in London and Sydney, where CrossFit affiliate networks have established dedicated snack procurement committees with quarterly vendor reviews.
Vegan Protein Balls Market Segmentation
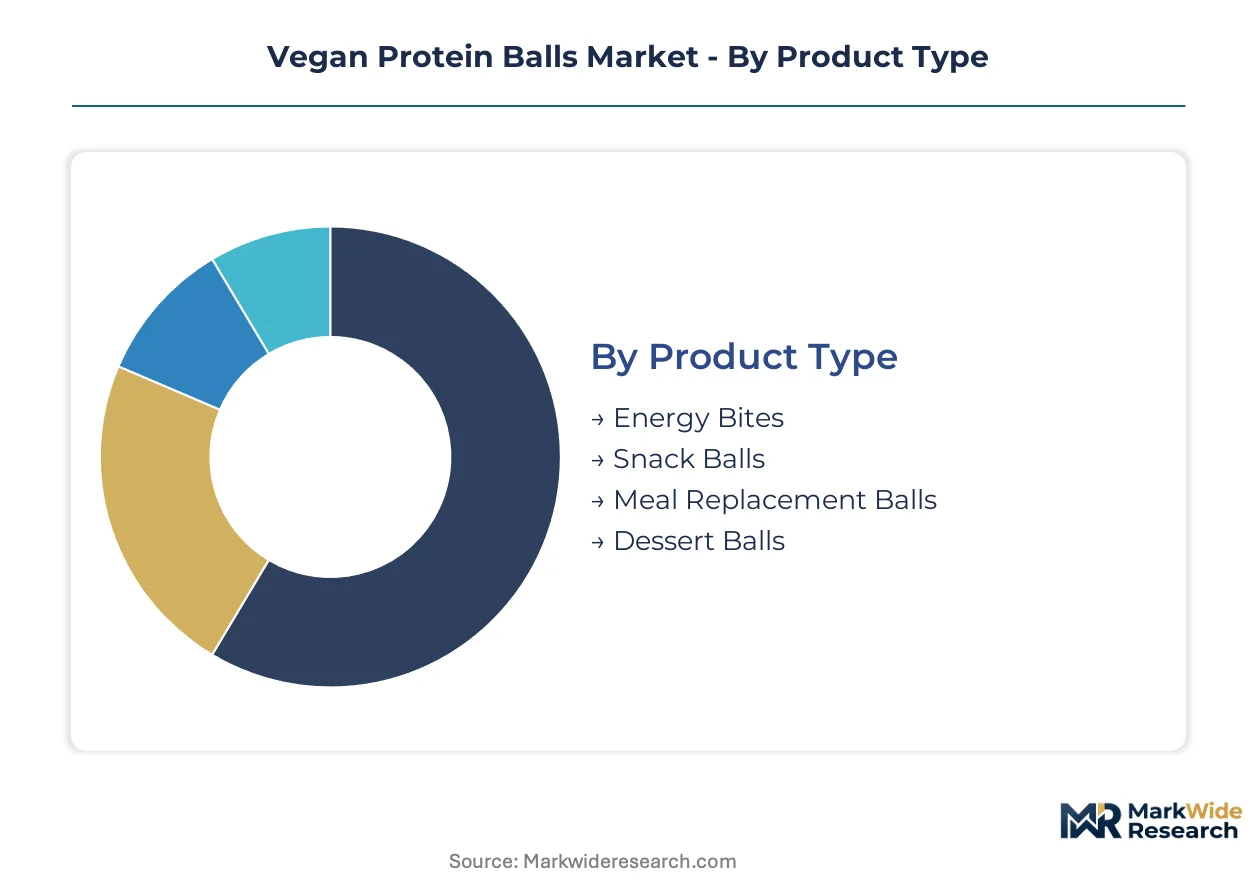
Segmentation in vegan protein balls reveals how supply chain configuration shapes competitive access. Manufacturers prioritize segments where ingredient qualification and co-manufacturing certification create defendable positions.
Product Type:
Supply concentration in cold-pressing equipment favors formats that maximize throughput per production hour.
- Energy Bites:Lower protein density (8–10g) with nut-date bases dominates unit economics. Demand concentrates in United States boutique fitness channels where subscription locker programs normalize pre-workout consumption.
- Snack Balls:Mid-range positioning (10–12g protein) balances portability with satiety. Coastal metropolitan clusters in California and New York drive velocity through convenience retail grab-and-go placement.
- Meal Replacement Balls:Fortified micronutrient profiles command premium shelf positioning.
- Dessert Balls:Indulgence-positioned variants with cocoa coatings target evening consumption occasions.
Today's leader: Energy Bites. Tomorrow's challenger: Meal Replacement Balls.
Main Ingredient:
Cost tier differentiation separates premium organic inputs from commodity-grade alternatives.
- Pea Protein:Isolate and concentrate forms displace soy across allergen-sensitive formulations. EFSA novel food approvals unlock European expansion for brands qualifying under EU regulatory frameworks.
- Almond Flour:California harvest volatility exposes margin pressure. United States organic certification pathways command 15–20% price premiums at retail.
- Chia Seeds:Omega-3 positioning targets functional nutrition buyers.
- Oats:Gluten-free certification requirements add qualification complexity.
Pea protein anchors current formulation share. Almond flour faces substitution pressure from sunflower seed alternatives.
Flavor Profile:
Application context dictates whether familiarity or novelty drives purchase.
- Chocolate:Cocoa-based coatings mask protein aftertaste in high-density formulations. German pharmacy retail channels favor chocolate variants for shelf-stable snacking sets.
- Vanilla:Neutral base enables clean-label positioning with minimal additive load.
- Berry:Acai and blueberry concentrates target antioxidant claims in sports nutrition.
- Coconut:MCT oil integration supports ketogenic diet positioning.
Chocolate maintains volume leadership. Berry flavors gain fastest in functional positioning segments.
Packaging Type:
Customer type separation between individual convenience buyers and household stock-up purchasers.
- Single-Serve Packs:Individual wrappers optimize commuter traffic patterns in dense urban cores. United States convenience retailers mandate this format for planogram access.
- Bags:Multi-count pouches serve pantry-stocking households.
- Boxes:Gift-oriented presentation targets corporate wellness program procurement.
- Bulk Containers:Food-service and gym dispensary channels require portion-control protocols.
Single-serve packs dominate retail velocity. Bulk containers serve institutional channels with different margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metropolitan clusters in the United States concentrate the highest velocity vegan protein ball consumption, with boutique fitness channels and convenience retail driving repeat purchase patterns. Regulatory frameworks in multiple jurisdictions are reshaping formulation standards and market access conditions.
United States
FDA nutrition labeling updates for plant-based claims are compressing reformulation timelines as brands adjust protein content substantiation protocols. California and New York metro areas anchor demand through CrossFit affiliate networks and commuter-focused convenience retail. The USDA organic certification pathway enables premium price realization in segregated retail planograms.
Germany
Apotheken pharmacy chains remain unserved by dedicated vegan protein ball sets, creating first-mover shelf access opportunities before mass-market entry. REACH compliance deadlines for food-contact materials force accelerated validation of compostable barrier films. Berlin and Munich fitness communities normalize pre-workout consumption through subscription procurement models.
United Kingdom
CrossFit affiliate networks in London and Sydney have established dedicated snack procurement committees with quarterly vendor reviews. EFSA novel food approval frameworks shape which functional benefits companies can communicate across member states. Manchester and Birmingham co-manufacturing clusters service multiple brand clients through shared high-moisture extrusion shifts.
Australia
Boutique fitness operators consolidate procurement through centralized purchasing cooperatives that displace individual gym owner decision-making. TGA regulations influence sports nutrition positioning and health claim substantiation requirements. Sydney and Melbourne urban cores prioritize single-serve grab-and-go formats aligned with commuter traffic patterns.
Netherlands
Regional co-manufacturers adopt modular extrusion systems to service multiple brand clients without full line sanitation between runs. EFSA guidelines on pea protein concentrates unlock European expansion for allergen-sensitive formulations. Rotterdam and Amsterdam distribution hubs facilitate cold-pressed equipment access for mid-scale market entrants.
Vegan Protein Balls Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and co-manufacturing certification capabilities. The vendor base separates into three tiers: multinational CPG conglomerates with shelf-space leverage, vertically integrated mid-scale specialists controlling ingredient sourcing, and niche craft producers emphasizing clean-label storytelling. Strategic archetypes include the supply-chain-integrated operator, the regulatory-compliance specialist, and the channel-exclusive partner. Dominant competitive moves involve co-manufacturing certification acceleration and direct-to-locker distribution partnerships bypassing traditional grocery slotting fees.
Within the vertically integrated tier, Bounce Foods Ltd and The Protein Ball Co exemplify contrasting approaches to market positioning. Bounce Foods Ltd occupies a supply-chain-control archetype through captive ingredient sourcing and European distribution networks. The Protein Ball Co anchors clean-label positioning with transparent supply chain storytelling that resonates with allergen-sensitive buyers. General Mills, Inc. represents multinational CPG leverage with existing retail relationships and scale economics. These three entities illustrate how formulation expertise, regulatory navigation, and channel access separate competitive outcomes.
| Leading Market Players |
|---|
| The Protein Ball Co |
| Bounce Foods Ltd |
| The Daily Nourish Co. |
| Nibble Group Ltd |
| Tom & Luke Ltd |
| Creation Nation |
| Boostball |
| Health Lab |
| General Mills, Inc. |
| Others |
Value Network & Pricing Analysis
Cold-pressing equipment technicians in the Netherlands and California command wage premiums that widen spreads between artisanal and mass-market price tiers. Labor-cost differentials in specialized protein-ball manufacturing regions directly feed into three-tier pricing stratification across premium organic, standard clean-label, and economy private-label offerings.
Pricing Analysis
Input-cost pass-through from volatile organic nut butter and cold-pressed oil markets compresses margins at the economy tier while supporting premium-tier price integrity. Pricing stratifies across USDA-certified organic, clean-label conventional, and private-label economy levels, with certification grade and volume scale as primary differentiation drivers. Cost compression in the mid-tier is intensifying as Argentine peanut crop cycles squeeze almond flour alternatives. Boutique fitness channels show least price sensitivity, while convenience retail stock-up purchasers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Amsterdam, and California's Central Valley anchor hub-and-spoke patterns that feed coastal metropolitan clusters. Pea protein isolate production concentrates in Manitoba and Saskatchewan, while organic almond sourcing draws from California harvests and European organic cooperatives. Single-source vulnerability in North American pea protein exposes brands to regional drought and rail logistics disruptions. Distribution runs through co-manufacturing networks with shared high-moisture extrusion shifts rather than captive production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vegan protein balls rests on pea protein cost curves flattening as processing scale accumulates, alongside premium-tier velocity accelerating through pharmacy and corporate wellness channels.
For Market Incumbents: Anticipate displacement pressure from modular extrusion entrants by accelerating BRC and SQF certification timelines for allergen-free lines. Lock in captive supply of organic pea protein concentrates through backward integration into Manitoba processing partnerships. Defend shelf position by securing exclusive flavor rotations with consolidated CrossFit purchasing cooperatives before white-label supply agreements proliferate. For New Entrants and Emerging Players: German pharmacy chain buyers remain unserved by dedicated vegan protein ball sets, presenting first-mover access before dm-drogerie market entry. Target corporate wellness program procurement committees with direct-to-locker delivery partnerships that bypass traditional grocery slotting fees. Lead with compostable barrier film validation to capture REACH compliance-driven packaging transitions ahead of enforcement windows. For Investors and Strategic Acquirers: Multinational CPG conglomerates with existing snack distribution networks are the most active acquirer in this space, seeking clean-label capability through bolt-on targets. Five-to-ten year viability hinges on brands demonstrating defendable co-manufacturing certification velocity and organic ingredient traceability systems. Watch for inflection when EFSA novel food approvals for emerging protein isolates unlock European expansion for mid-scale specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Locker Distribution Partnership | Bypasses grocery slotting fees by capturing worksite consumption through corporate wellness procurement. |
| Pea Protein Concentrate Backward Integration | Secures Manitoba supply against drought-driven price spikes and rail logistics disruptions. |
| Compostable Barrier Film Validation | Accelerates shelf-life testing to meet REACH compliance deadlines for oxygen-sensitive nut bases. |
| BRC/SQF Allergen-Free Line Certification | Compresses 14-18 month qualification periods to defend against modular extrusion entrants. |
| Pharmacy Channel First-Mover Entry | Captures Apotheken shelf access in Germany before mass-market competitors establish presence. |
Research Methodology
Direct dialogue with co-manufacturing operations managers, protein ingredient procurement leads, boutique fitness channel buyers, and regulatory affairs specialists at plant-based snack brands grounded qualitative insights. Secondary validation drew from FDA nutrition labeling guidance documents, EFSA novel food approval registers, USDA organic certification databases, and Nielsen retail audit data for convenience channel velocity. Bottom-up production capacity modeling and top-down consumption pattern analysis were triangulated to cross-verify segment-level outputs.
Bottom-up volume builds aggregated installed cold-pressing and extrusion equipment capacity across Netherlands, California, and UK co-manufacturing clusters, while top-down approaches calibrated against retail scan data and fitness channel procurement volumes. Segmentation modeling spanned product type, main ingredient, flavor profile, and packaging format dimensions across the projection horizon. CAGRs were derived from equipment throughput expansion curves, protein isolate supply forecasts, and channel penetration rate assumptions for pharmacy and corporate wellness segments.
Inputs from EFSA approval timelines and California almond harvest yield projections were available through the study window; gaps in real-time co-manufacturing capacity utilization data introduce uncertainty bands around near-term production estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Seafood Snacks Market
Snacks
South Africa Savory Snacks Market
Snacks
Italy Snack Bar Market
Snacks
Pretzel Salts Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Europe Snack Bar Market
Snacks
Snack Food Packaging Market
Snacks
Baked Savoury Snacks Market
Snacks
Nachos Market
Snacks
United Kingdom Snack Bar Market
Snacks
Kale Chips Market
Snacks
United States Children's Snack Bar Market
Snacks
Austria Snack Bar Market
Snacks
Seaweed Snacks Market
Snacks
Specialty Snacks Market