
 Germany Energy Bar Market | 2026-2036
Germany Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Energy Bar Market Foresight
Plant-based protein isolates is repositioning cost structures across German energy bar portfolios. Layenberger Nutrition Group leverages its domestic manufacturing base to anchor supply reliability for functional nutrition lines. Clif Bar & Company competes through organic certification depth, while Nestlé S.A. extends its refrigerated distribution network into convenience channels nationwide.
Germany energy bars are shelf-stable, nutrient-dense food products typically formulated with proteins, carbohydrates, fibers, and micronutrients, compressed through cold extrusion or baking processes to deliver portable caloric delivery for athletic or meal-gap scenarios. Protein bars dominate value contribution due to premium positioning, while vegan and organic nutrition focus segments outpace conventional formats in velocity growth. E-commerce channels capture disproportionate trial volume, though supermarkets retain the largest absolute transaction base.
BfR (German Federal Institute for Risk Assessment) evaluates novel ingredient safety, while EU REACH governs packaging material compliance and EU organic regulations certify label claims for the German market. Stakeholders must monitor evolving Nutri-Score thresholds and incoming EU packaging waste directives that will reshape material specifications and on-label communication requirements.
Market Dynamics
Germany's Nutri-Score labeling mandate and EU organic certification requirements are forcing reformulation across energy bar portfolios, compressing margins for conventional products while rewarding certified alternatives with shelf placement advantages.
Growth Catalysts
- Bavaria fitness culture density:Munich's concentration of climbing gyms, CrossFit boxes, and trail running clubs generates concentrated demand for high-protein formats.
- EU organic regulation tailwinds:Certified organic claims unlock premium positioning in REWE and Edeka chains, where shelf-facing rules favor labeled products.
- Cold extrusion technology maturation:Domestic equipment suppliers enable smaller brands to achieve industrial texture profiles without capital-intensive baking infrastructure.
Market Restraints
- Pea protein isolate cost volatility:German manufacturers face margin compression when Canadian and Chinese crop yields fluctuate.
- North Rhine-Westphalia retail concentration:Metro AG and Aldi Süd control disproportionate shelf access, extracting listing fees that disadvantage mid-tier entrants.
- EU packaging waste directive friction:BfR compliance timelines for recyclable multilayer films extend new product development cycles.
Strategic Opportunities
- Baden-Württemberg underpenetration:Stuttgart's corporate wellness programs lack dedicated energy bar suppliers compared to Bavaria's density.
- Direct-to-subscription channel innovation:Monthly personalized nutrition boxes bypass conventional retail slotting constraints.
- CSRD-aligned carbon labeling:Early adopters of lifecycle transparency capture institutional procurement from Bundeswehr and federal ministry canteens.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise combining protein chemistry with clean-label requirements concentrates at Layenberger and a few contract manufacturers.
- EU organic certification timeline:Conversion periods lock suppliers into multi-year commitments before label claims become viable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Energy Bar Market |
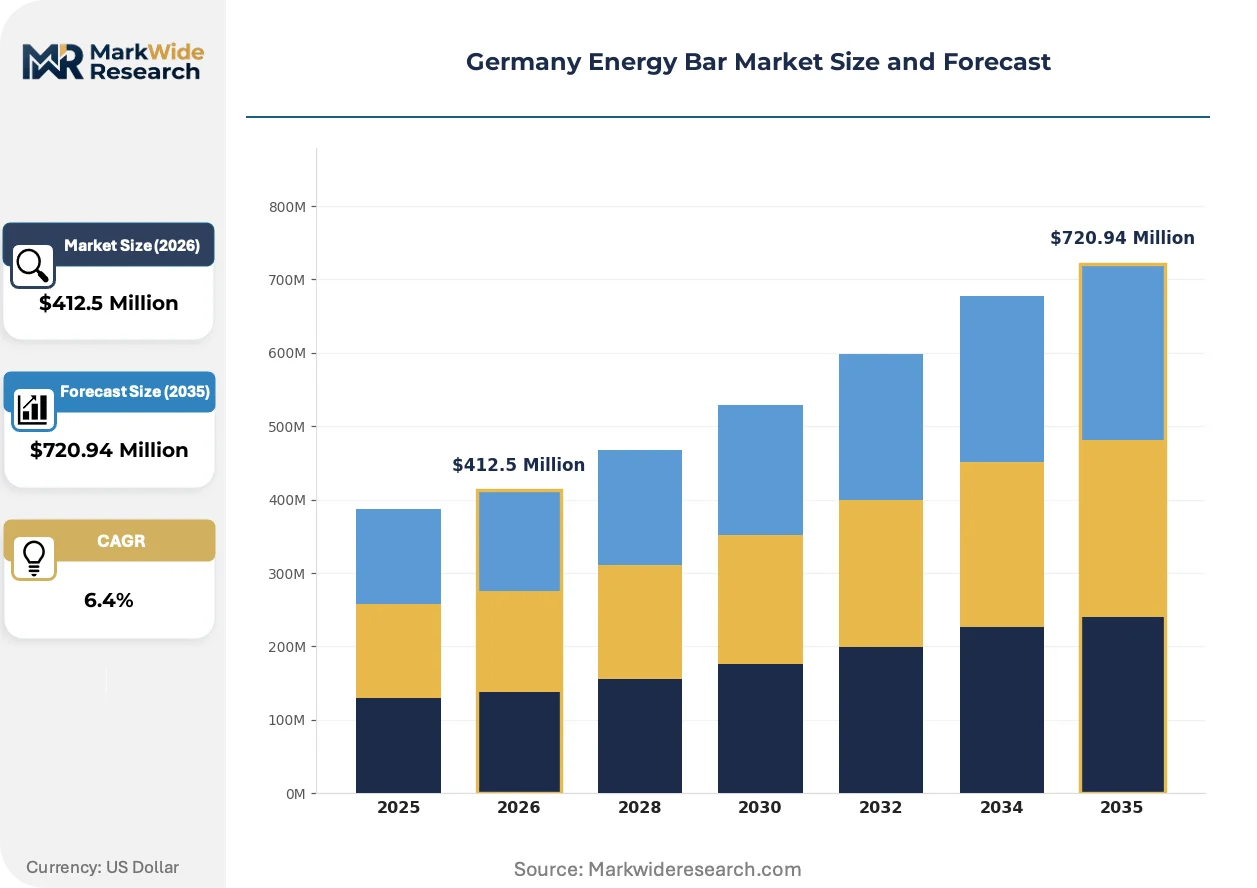
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Cereal Bars, Nut Bars, Fruit Bars, Meal Replacement Bars Consumer Age Group: Children, Adolescents, Adults, Seniors Sales Channel: Specialty Stores, Pharmacies, E-commerce, Supermarkets, Convenience Stores Nutrition Focus: High Protein, Low Sugar, Gluten Free, Vegan, Organic |
| Companies Covered | Nestlé S.A., Clif Bar & Company, General Mills Inc., Simply Good Foods Company, BellRing Brands, Inc., Mondelez International, Glanbia plc, Layenberger Nutrition Group, Mars, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Energy Bar Market Shifts & Advancements
Reformulation priorities in German energy bars center on protein source diversification, label transparency, and packaging material transitions that satisfy both regulatory mandates and athlete performance expectations.
Fermented protein isolates from German biotech suppliers is consolidating supply chains for mid-tier brands previously dependent on imported soy and pea concentrates. Specialty sports nutrition retailers in Hamburg and Berlin are accelerating trial orders of fava bean and sunflower protein formats. This ingredient shift is consolidating cost advantages for domestic bioprocessing facilities against Asian commodity suppliers.
EU Nutri-Score threshold tightening is forcing sodium and saturated fat reductions across conventional chocolate-coated formats. BfR guidance on novel sweetener safety is extending formulation review timelines. Protein bar segments targeting children's sports leagues face the steepest reformulation costs, with several Bavarian manufacturers pivoting toward uncoated fruit-nut bases to maintain B and C ratings.
Corporate wellness procurement is fragmenting away from single-supplier contracts toward multi-brand curated portals. Siemens and BMW works councils now administer allowance-based selections where employees choose from certified organic, vegan, and allergen-free alternatives. This purchasing pattern is most visible in Baden-Württemberg automotive clusters, where sustainability procurement officers prioritize transparent supply chain documentation over volume discounts.
Germany Energy Bar Market Segmentation
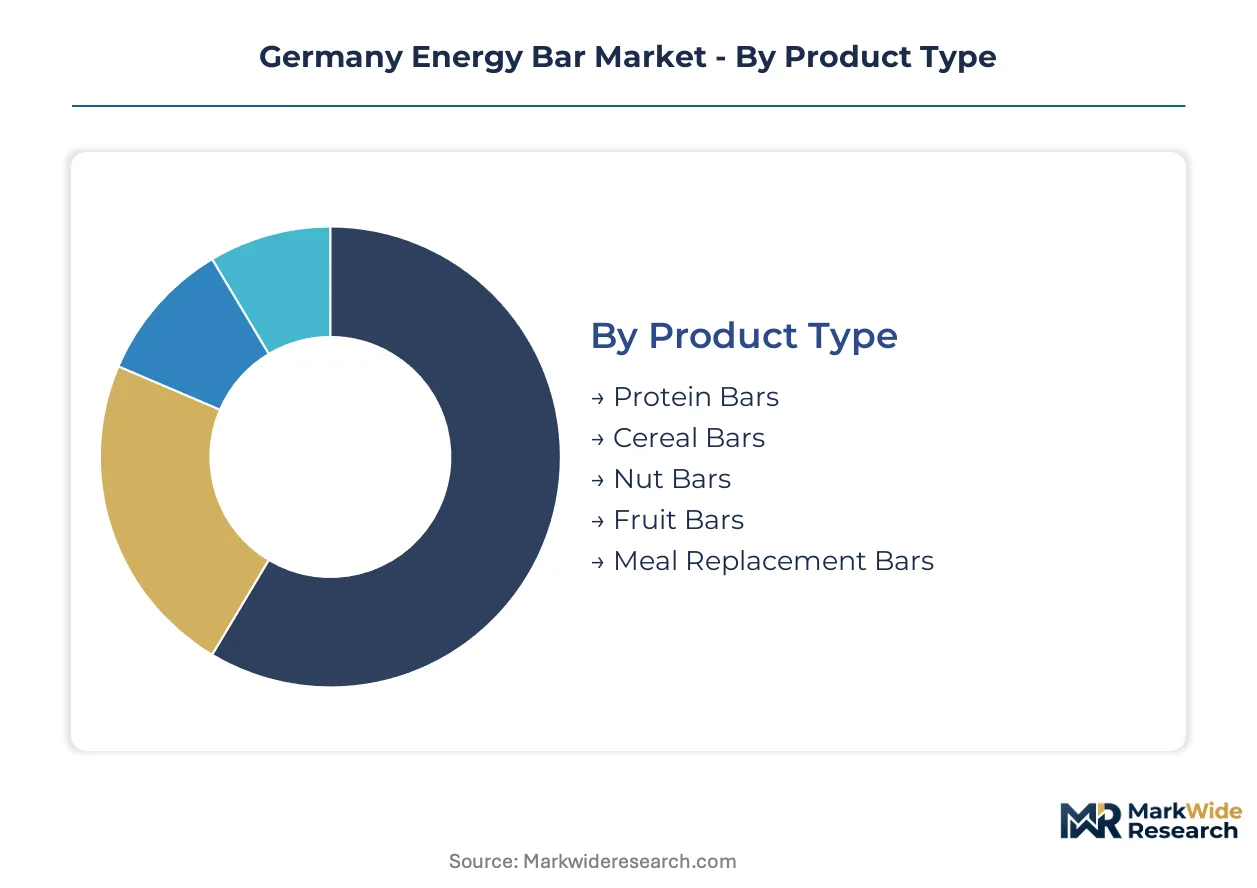
German energy bar portfolios fragment across four critical dimensions. Product type determines manufacturing complexity and margin structure. Consumer age and nutrition focus dictate formulation priorities under BfR and EU organic frameworks. Channel selection shapes brand positioning and trial economics.
Product Type:
Volume concentrates in mass-market formats while premium positioning clusters around performance-oriented specifications.
- Protein Bars:Cold-extruded or baked matrices delivering 15-25g protein per serving from whey, casein, or plant isolates. Bavarian CrossFit affiliates and Munich climbing gyms drive concentrated demand for 20g+ formats with BfR-compliant novel sweetener profiles.
- Cereal Bars:Oat, rice, or mixed grain bases bound with glucose syrups or date pastes. REWE and Edeka chains in North Rhine-Westphalia move the highest absolute volumes, though Nutri-Score C and D ratings compress shelf placement for conventional formulations.
- Nut Bars:Almond, cashew, or hazelnut-dominant compositions with minimal processing.
- Fruit Bars:Compressed dried fruit matrices, often single-ingredient or dual-component.
- Meal Replacement Bars:Complete micronutrient profiles targeting 400+ kcal per unit.
Today's leader: Protein Bars. Tomorrow's challenger: Meal Replacement Bars.
Consumer Age Group:
Formulation constraints tighten as age segments descend, with BfR novel ingredient scrutiny most intensive for pediatric applications.
- Children:Sodium and saturated fat ceilings under tightening Nutri-Score thresholds force Bavarian manufacturers toward uncoated fruit-nut bases. Youth sports leagues in Hamburg and Berlin generate institutional procurement volume.
- Adolescents:Price-sensitive trial behavior concentrates in convenience channels and e-commerce flash promotions.
- Adults:Corporate wellness allowances at Siemens and BMW works councils drive curated multi-brand portal adoption in Baden-Württemberg.
- Seniors:Texture-modified formats with enhanced micronutrient density for sarcopenia prevention.
Adults command current revenue concentration. Adolescents are expanding most quickly through digital-native trial patterns.
Sales Channel:
Physical retail retains absolute transaction dominance while digital channels capture disproportionate new brand discovery.
- Supermarkets:REWE, Edeka, and Aldi Süd control shelf-facing rules that favor EU organic certification. Metro AG extracts listing fees that disadvantage mid-tier entrants in North Rhine-Westphalia.
- E-commerce:Direct-to-subscription models bypass slotting constraints through monthly personalized nutrition boxes.
- Specialty Stores:Hamburg and Berlin sports nutrition retailers accelerate trial orders of fermented protein and fava bean formats.
- Pharmacies:Medical positioning for meal replacement and clinical nutrition applications.
- Convenience Stores:Impulse-oriented single-unit purchases with compressed margin structures.
Supermarkets anchor absolute volume. E-commerce is gaining share fastest through subscription innovation.
Nutrition Focus:
Certification depth separates premium positioning from commodity competition under EU regulatory frameworks.
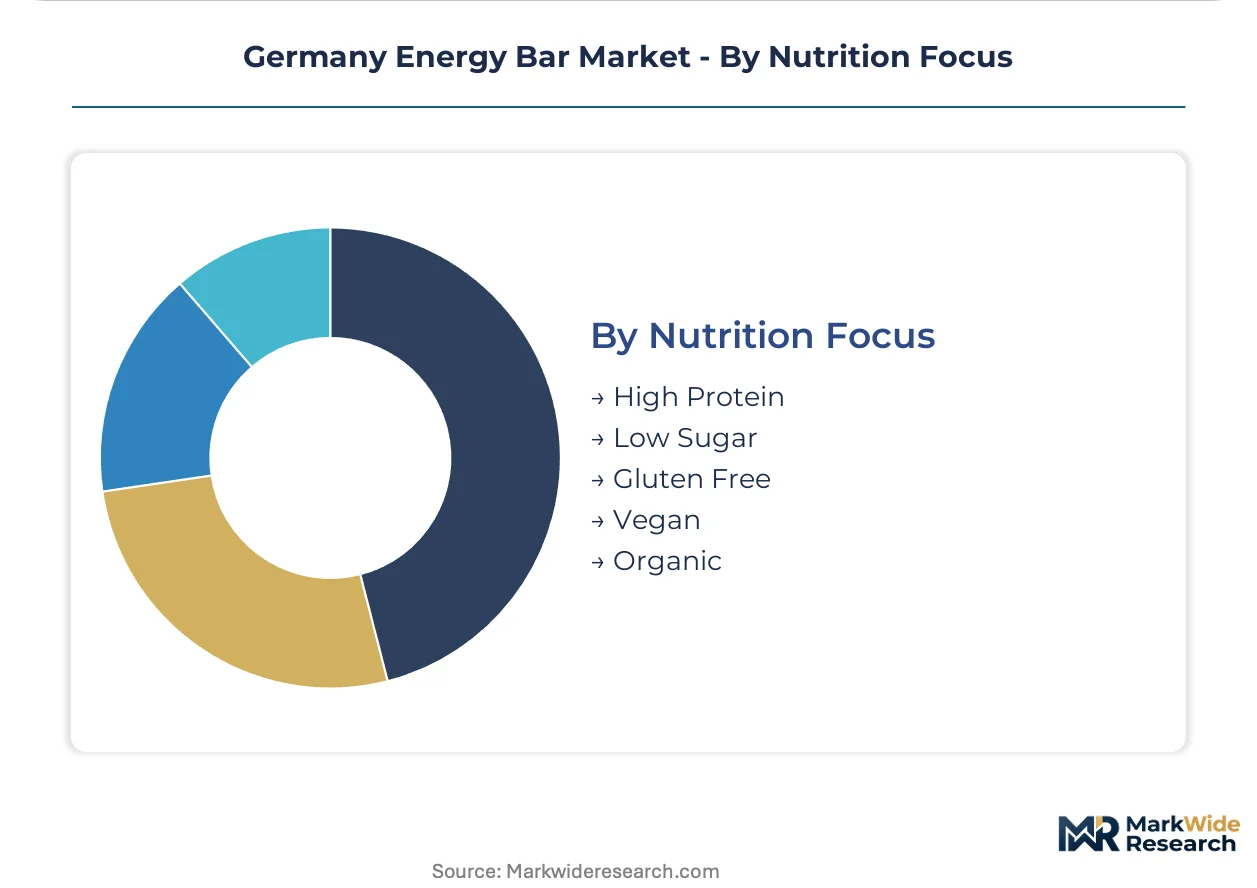
- Organic:EU organic regulation compliance unlocks shelf placement advantages and works with REWE and Edeka chain-facing rules. Conversion periods lock suppliers into multi-year commitments before label claims become viable.
- High Protein:20g+ per serving targets athletic performance segments with cold extrusion texture requirements.
- Vegan:Plant protein isolates from German biotech suppliers consolidate supply chains against Asian commodity dependence.
- Low Sugar:BfR guidance on novel sweetener safety extends formulation review timelines.
- Gluten Free:Oat-based matrices with certified gluten-free sourcing for celiac and preference-driven demand.
Organic commands premium shelf access. Vegan shows steepest expansion trajectory through domestic bioprocessing cost advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's fitness infrastructure density anchors Germany's energy bar demand geography, with Munich's climbing gyms and CrossFit affiliates generating concentrated high-protein format consumption. Regional specialization across German states reflects divergent retail structures, regulatory enforcement intensity, and industrial clustering patterns that reshape local competitive dynamics.
Bavaria
Munich's concentration of bouldering halls, trail running clubs, and functional fitness boxes drives 20g+ protein bar adoption. BfR novel sweetener guidance extends formulation review timelines for local manufacturers targeting youth sports leagues. Augsburg and Nuremberg specialty retailers accelerate trial orders of fermented protein formats from domestic biotech suppliers.
North Rhine-Westphalia
Metro AG and Aldi Süd control disproportionate shelf access in Cologne and Düsseldorf, extracting listing fees that compress mid-tier entrant margins. EU organic certification unlocks premium positioning in REWE and Edeka chains where shelf-facing rules favor labeled products. Dortmund's corporate wellness procurement officers prioritize transparent supply chain documentation over volume discounts.
Baden-Württemberg
Stuttgart's automotive clusters lack dedicated energy bar supplier density relative to Bavaria's fitness culture penetration. Siemens and BMW works councils administer allowance-based curated portals where employees select certified organic and vegan alternatives. Karlsruhe's sustainability procurement officers drive CSRD-aligned carbon labeling adoption for federal ministry canteen contracts.
Hamburg
Specialty sports nutrition retailers in Hamburg accelerate fava bean and sunflower protein format trials ahead of national distribution. BfR evaluates novel ingredient safety for plant-based isolates entering children's sports league formulations. The port city's logistics infrastructure enables cold extrusion equipment imports for smaller brands achieving industrial texture profiles.
Berlin-Brandenburg
E-commerce subscription models bypass conventional retail slotting constraints through monthly personalized nutrition boxes. Berlin's digital-native consumer base drives disproportionate new brand discovery velocity relative to physical transaction volume. Potsdam's federal administrative presence shapes early procurement patterns for Bundeswehr and ministry canteen institutional contracts.
Germany Energy Bar Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel access dimensions, producing a tiered structure where organic compliance separates premium positioning from commodity competition. Nestlé S.A. and Mondelez International leverage refrigerated distribution networks and convenience channel penetration, while domestic specialists anchor supply reliability through captive manufacturing. Three archetypes dominate: multinational CPG conglomerates with portfolio breadth, domestic nutrition specialists with formulation expertise, and private-label contractors serving Aldi Süd and Metro AG. Competitive moves concentrate on EU organic certification acquisition and direct-to-subscription channel innovation.
Within the domestic specialist tier, Layenberger Nutrition Group exemplifies manufacturing-anchored supply reliability for functional nutrition lines, while Clif Bar & Company occupies a position defined by organic certification depth. Nestlé S.A. sits within the multinational CPG archetype, extending refrigerated infrastructure into convenience channels nationwide. These three represent divergent strategic postures: captive production, certification-first positioning, and distribution scale.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Clif Bar & Company |
| General Mills Inc. |
| Simply Good Foods Company |
| BellRing Brands, Inc. |
| Mondelez International |
| Glanbia plc |
| Layenberger Nutrition Group |
| Mars, Incorporated |
| Others |
Supply & Pricing Matrix
EU organic certification procurement mandates from REWE and Edeka chains force German manufacturers toward multi-year supplier conversion commitments, compressing near-term margin flexibility while locking in premium shelf access that justifies higher price points.
Pricing Analysis
Pea protein isolate cost pass-through from Canadian and Chinese crop volatility dominates German energy bar pricing dynamics. Three-tier pricing structure across EU organic premium, conventional mid-market, and private-label economy levels separates certified products with Nutri-Score advantages from commodity competition. Pricing pressure stems from Aldi Süd and Metro AG listing fee extraction in North Rhine-Westphalia, where mid-tier entrants face the steepest compression. Corporate wellness buyers at Siemens and BMW works councils show lowest price sensitivity, prioritizing transparent supply chain documentation over volume discounts.
Supply Chain Analysis
EU organic certification gating locks German brands into multi-year conversion timelines before label claims become viable, tethering supply reliability to domestic bioprocessing infrastructure. Raw material sourcing draws from Canadian pea protein, Chinese soy isolates, and German fermented protein biotech suppliers. Cold extrusion equipment imports concentrate through Hamburg's port logistics, creating single-source vulnerability for smaller brands achieving industrial texture profiles. Distribution runs through REWE and Edeka refrigerated networks for premium formats, with direct-to-subscription models bypassing conventional slotting constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in German energy bars rests on domestic bioprocessing cost advantages displacing Asian commodity dependence, alongside CSRD-aligned carbon labeling capturing institutional procurement premiums.
For Market Incumbents: Hedge against pea protein isolate volatility through backward integration into German fermented protein biotech suppliers. Secure multi-year EU organic certification pipelines before Nutri-Score threshold tightening accelerates. Deepen captive manufacturing at Bavaria facilities to anchor supply reliability against cold extrusion equipment import delays. For New Entrants and Emerging Players: Capture Baden-Württemberg's underpenetrated corporate wellness segment, where Stuttgart automotive clusters lack dedicated supplier density relative to Bavaria. Target direct-to-subscription channel innovation with monthly personalized nutrition boxes bypassing Metro AG and Aldi Süd listing fee structures. Lead with CSRD-aligned carbon transparency to differentiate from incumbent certification-only positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic bioprocessing specialists combining EU organic certification depth with fermented protein isolate capabilities. Long-term viability favors manufacturers with captive cold extrusion infrastructure and Bundeswehr institutional procurement relationships. Watch BfR novel sweetener guidance timelines as inflection indicator for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU Organic Certification Acquisition | Unlocks REWE and Edeka shelf-facing advantages under tightening Nutri-Score rules. |
| Domestic Bioprocessing Scale-Up | Consolidates cost advantages against Canadian and Chinese pea protein volatility. |
| Direct-to-Subscription Launch | Bypasses Metro AG listing fees through personalized nutrition box models. |
| CSRD Carbon Labeling Adoption | Captures Siemens and BMW works council procurement with lifecycle transparency. |
| Cold Extrusion Equipment Integration | Achieves industrial texture profiles without capital-intensive baking infrastructure. |
Research Methodology
Bottom-up fitness enthusiast and corporate wellness procurement modeling reconciled against top-down German bioprocessing capacity tracking forms the analytical core of this study. Primary interviews with category buyers at REWE and Edeka, supply planners at Layenberger Nutrition Group, formulation directors at domestic contract manufacturers, and sustainability procurement officers at Baden-Württemberg automotive clusters combined with secondary validation from BfR guidance documents, EU organic regulation filings, Nielsen retail audit data, and German customs trade records.
Input-output matrix framing connects protein isolate cost structures, cold extrusion technology adoption curves, and certification conversion timelines to volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, consumer age group, sales channel, and nutrition focus certification depth. CAGRs derive from regression analysis against historical protein bar velocity patterns and EU organic label penetration rates, with BfR novel ingredient review timelines and EU packaging waste directive compliance costs as industry-specific forecast inputs.
Underlying measurement precision varies by segment; protein bar and organic certification segments carry tighter precision than conventional cereal bar categories due to concentrated retail data availability. Forecasts reflect documented assumptions about Nutri-Score threshold evolution and EU organic conversion timeline stability. Deviation in BfR sweetener safety guidance or Canadian pea protein crop yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Baked Savory Snacks Market
Snacks
Savory Snack Products Market
Snacks
Indonesia Snack Bar Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Better for You Snacks Market
Snacks
North America Snack Food Market
Snacks
Germany Snack Bar Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Snack Pellets Market
Snacks
Cereal Bars Market
Snacks
Europe Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Protein Crisps Market
Snacks
Qatar Potato Chips Market
Snacks
UK Snack Market
Snacks
Grass-Fed Jerkies Market