
 Low Calorie Snack Foods Market | 2026-2036
Low Calorie Snack Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Snack Foods Market Foresight
The EU Green Deal's farm-to-fork sustainability targets are expanding scrutiny of snack supply chains across European retail channels. Nestle S.A. leverages its R&D infrastructure to reformulate legacy portfolios with reduced caloric density. PepsiCo anchors its North American position through direct-store-delivery networks that control shelf placement. Mondelez International differentiates via portion-packaging innovations that align with front-of-pack labeling requirements.
Low calorie snack foods are formulated products containing reduced energy density per serving, typically achieved through modified carbohydrate profiles, fiber enrichment, or controlled fat content below 3 grams per serving, designed to deliver satiety without exceeding 150 kilocalories per portion. Protein bars occupy the highest-margin tier within product type segmentation due to ingredient costs and sports-nutrition positioning. Baked chips compete on volume scale through supermarket distribution, while veggie snacks lead growth velocity among plant-forward ingredient categories. Sweeteners within the ingredients dimension face structural pressure as WHO guidelines and FDA labeling rules accelerate substitution toward natural alternatives.
The FDA enforces Nutrition Facts panel requirements and health claim substantiation that directly shape permissible marketing language and reformulation targets. EFSA and EMA coordinate on novel food ingredient approvals that govern market access for alternative proteins and fiber additives in European formulations. Health Canada and PMRA administer additive safety assessments that influence cross-border product standardization. Stakeholders must monitor evolving front-of-pack warning label mandates and sugar taxation proposals that will determine competitive viability across priority markets.
Market Dynamics
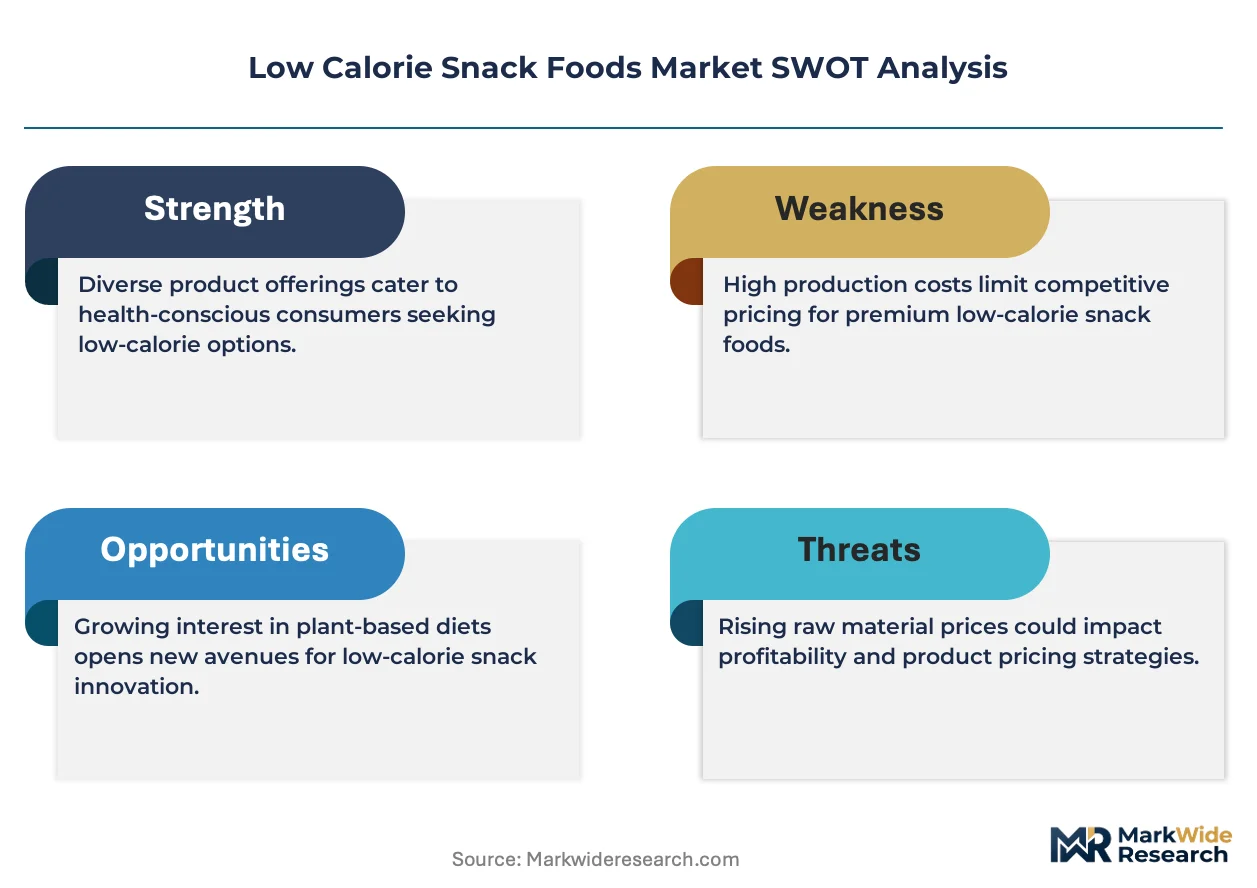
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing systematic reformulation across legacy portfolios, compressing timelines for alternative sweetener integration and reshaping competitive viability for brands dependent on conventional formulations.
Growth Catalysts
- Corporate Wellness Programs:Health-conscious employers in the United States are expanding subsidized purchases of portion-controlled items through on-site vending and cafeteria contracts, creating institutional demand channels.
- EU Green Deal:The farm-to-fork sustainability targets are expanding scrutiny of snack supply chains across European retail channels, rewarding brands with verified carbon accounting and regenerative sourcing credentials.
- Protein-Forward Positioning:Urban professionals are prioritizing portable nutrition with elevated protein content, pulling formulation investments toward isolate-enriched bars and extruded meat alternatives.
Market Restraints
- Alternative Sweetener Input Costs:Stevia and monk fruit extract prices exhibit volatility tied to agricultural yields in China and Southeast Asia, compressing margin structures for reformulated products.
- Supply Concentration Risk:Soluble fiber additive production concentrates among a limited set of European chemical processors, creating vulnerability to REACH compliance disruptions.
- Technical Limitation:Fat replacement technologies fail to replicate mouthfeel in baked applications below 3 grams per serving, constraining product-category expansion.
Strategic Opportunities
- Underpenetrated Geography:India's tier-two cities present white space for portion-packaged snacks as FSSAI front-of-pack labeling mandates create first-mover advantages for compliant entrants.
- Regulatory Tailwind:Health Canada's proposed sugar taxation framework will accelerate demand for sub-5% sugar formulations, rewarding early reformulation investments.
- Technology Convergence:Precision fermentation-derived proteins are converging with extrusion processing to enable next-generation meat analogs at cost parity with conventional snacks.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists with dual expertise in sensory optimization and regulatory navigation command premium compensation, constraining mid-tier manufacturer capabilities.
- Certification Timeline Compression:EFSA novel food ingredient approvals for alternative fibers and proteins extend 18-24 months, delaying product launches against competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Snack Foods Market |
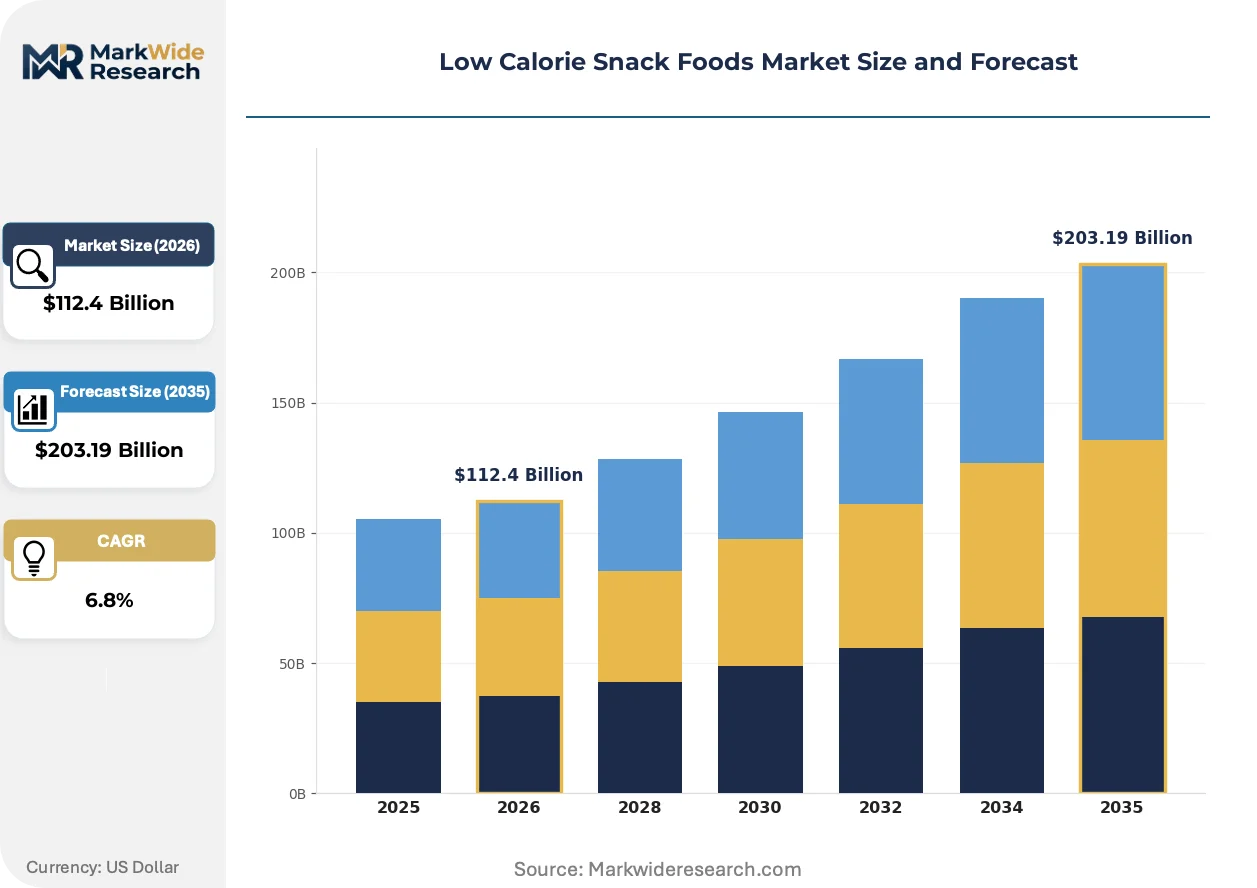
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Baked Chips, Rice Cakes, Veggie Snacks Ingredients: Whole Grains, Nuts, Seeds, Sweeteners End User: Health-Conscious Consumers, Athletes, Weight Watchers, Busy Professionals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores |
| Companies Covered | General Mills, Inc, Nestle S.A., Mondelez International, The Kraft Heinz Company, Conagra Brands, Inc, Archer Daniels Midland Company, Cargill, Incorporated, Danone, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Snack Foods Market Shifts & Advancements
Active reformulation is reshaping ingredient sourcing and manufacturing infrastructure as brands respond to labeling mandates and shifting palatability expectations across protein-forward and plant-based categories.
Precision fermentation-derived proteins are converging with high-moisture extrusion to produce fibrous meat analogs that replicate chew and satiety signals. Sports-nutrition buyers and flexitarian households are adopting these formats at accelerating velocity. The technology is converging with conventional snack manufacturing lines, enabling co-packing networks to absorb production without dedicated capex.
REACH regulations governing novel food-contact substances are tightening scrutiny of recycled packaging polymers in European markets. Industrial consequence includes mandatory migration testing for mineral oil saturated hydrocarbons in paper-based flexible packaging. Baked chip and cracker segments are most affected, with manufacturers accelerating shift to virgin fiber or bio-based barrier coatings to maintain shelf-life claims.
Subscription-based replenishment models are displacing conventional supermarket stock-up behavior among urban professionals with predictable consumption patterns. Direct-to-consumer channels capture recurring revenue with customized flavor rotations and portion sizing. This shift concentrates in United States coastal metropolitan areas where delivery density supports unit-economics viability.
Low Calorie Snack Foods Market Segmentation
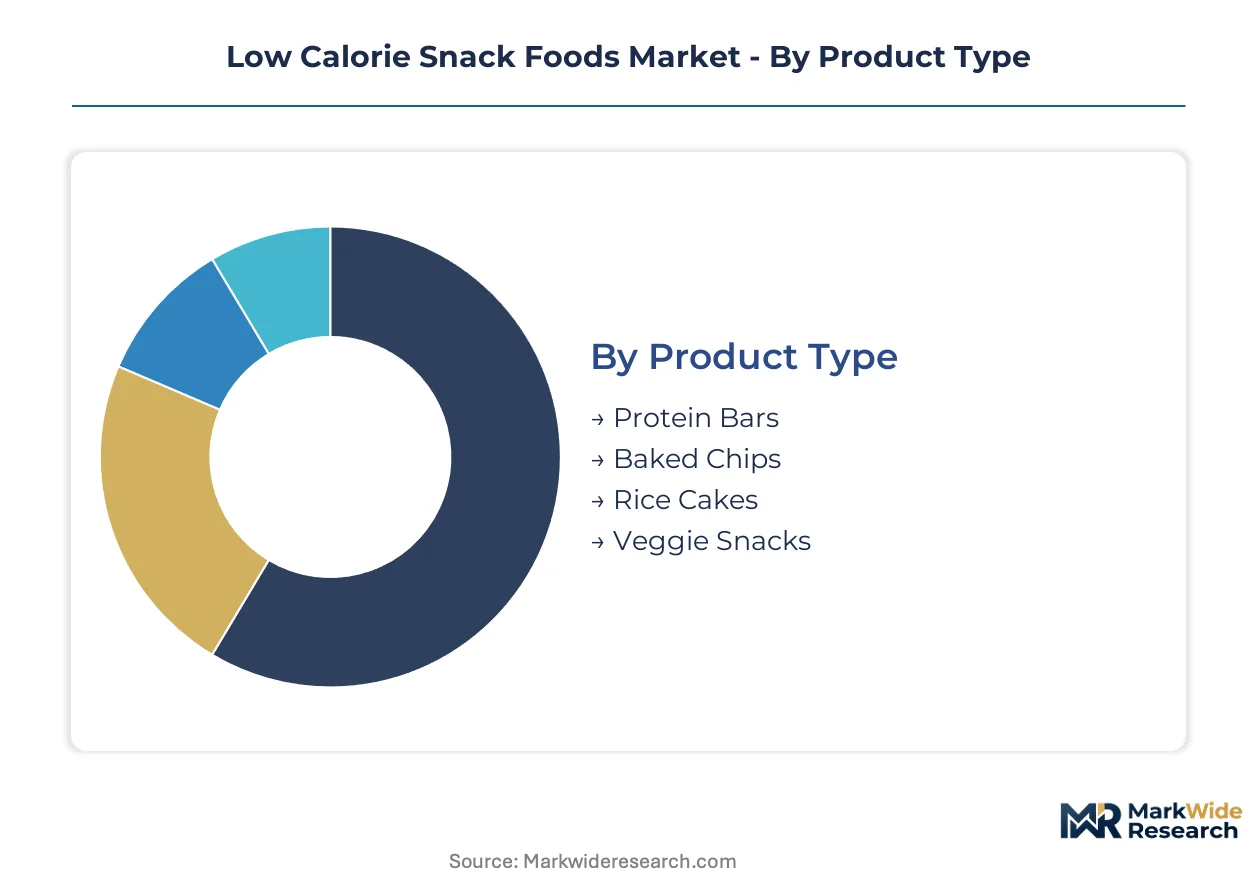
Segmentation in low calorie snack foods reveals how formulation choices, ingredient sourcing, and channel access create divergent margin structures. Each dimension carries distinct regulatory exposure and competitive intensity that shapes viable positioning strategies.
Product Type:
Standalone snack formats dominate shelf-stable retail, while embedded nutrition systems integrate into broader meal-replacement protocols across corporate wellness contracts.
- Protein Bars:Isolate-enriched formulations deliver 15-20 grams protein per serving through extruded matrices with controlled moisture content. Demand concentrates among athletes and urban professionals in United States metropolitan corridors where sports-nutrition positioning commands premium shelf placement. FDA health claim substantiation requirements constrain permissible performance marketing language.
- Veggie Snacks:Dehydrated or extruded vegetable-based products achieve caloric density below 100 kilocalories per portion through fiber enrichment and minimal oil coating. European retail channels under EU Green Deal farm-to-fork mandates reward verified regenerative sourcing credentials for these plant-forward formats. EFSA novel food approvals govern alternative protein fortification in these products.
- Baked Chips:Thin-sheet potato or grain substrates processed at reduced oil absorption compared to fried alternatives.
- Rice Cakes:Puffed whole-grain discs with minimal ingredient complexity, competing on price accessibility in mass-market channels.
Baked chips lead volumes today; veggie snacks are gaining share fastest.
Ingredients:
Cost tier differentiation separates commodity inputs from specialty additives facing agricultural yield volatility and regulatory scrutiny on novel substance approvals.
- Sweeteners:Natural alternatives including stevia and monk fruit extract displace conventional sucrose under FDA added-sugar labeling mandates. Input costs fluctuate with harvest conditions in China and Southeast Asia, compressing margins for reformulated portfolios dependent on these botanical extracts.
- Whole Grains:Oat, quinoa, and ancient grain flours provide soluble fiber enrichment and structural integrity in extruded bars and baked formats. Health Canada front-of-pack labeling proposals accelerate demand for sub-5% sugar whole-grain formulations across North American retail.
- Nuts:Almond, cashew, and peanut bases deliver protein density and satiety signaling in bar applications.
- Seeds:Chia, flax, and hemp additions contribute omega fatty acid positioning and textural contrast.
Whole grains anchor volume scale; sweeteners attract the steepest reformulation investment.
End User:
Customer type determines packaging format, portion sizing, and channel prioritization with divergent price elasticity and loyalty patterns.
- Health-Conscious Consumers:Broad demographic segment prioritizing clean-label ingredient transparency and front-of-pack nutritional clarity. United States urban professionals in coastal metropolitan areas drive subscription-based replenishment through direct-to-consumer channels with customized flavor rotations.
- Busy Professionals:Time-constrained buyers seeking portable nutrition with minimal preparation requirements and predictable portion control. Corporate wellness programs in United States technology and financial services sectors subsidize on-site vending and cafeteria contracts for this cohort.
- Athletes:Performance-oriented buyers requiring macronutrient precision and rapid glycemic response management.
- Weight Watchers:Calorie-tracking consumers prioritizing explicit portion boundaries and satiety-per-kilocalorie optimization.
Health-conscious consumers represent the largest addressable base; busy professionals show the fastest channel shift toward institutional procurement.
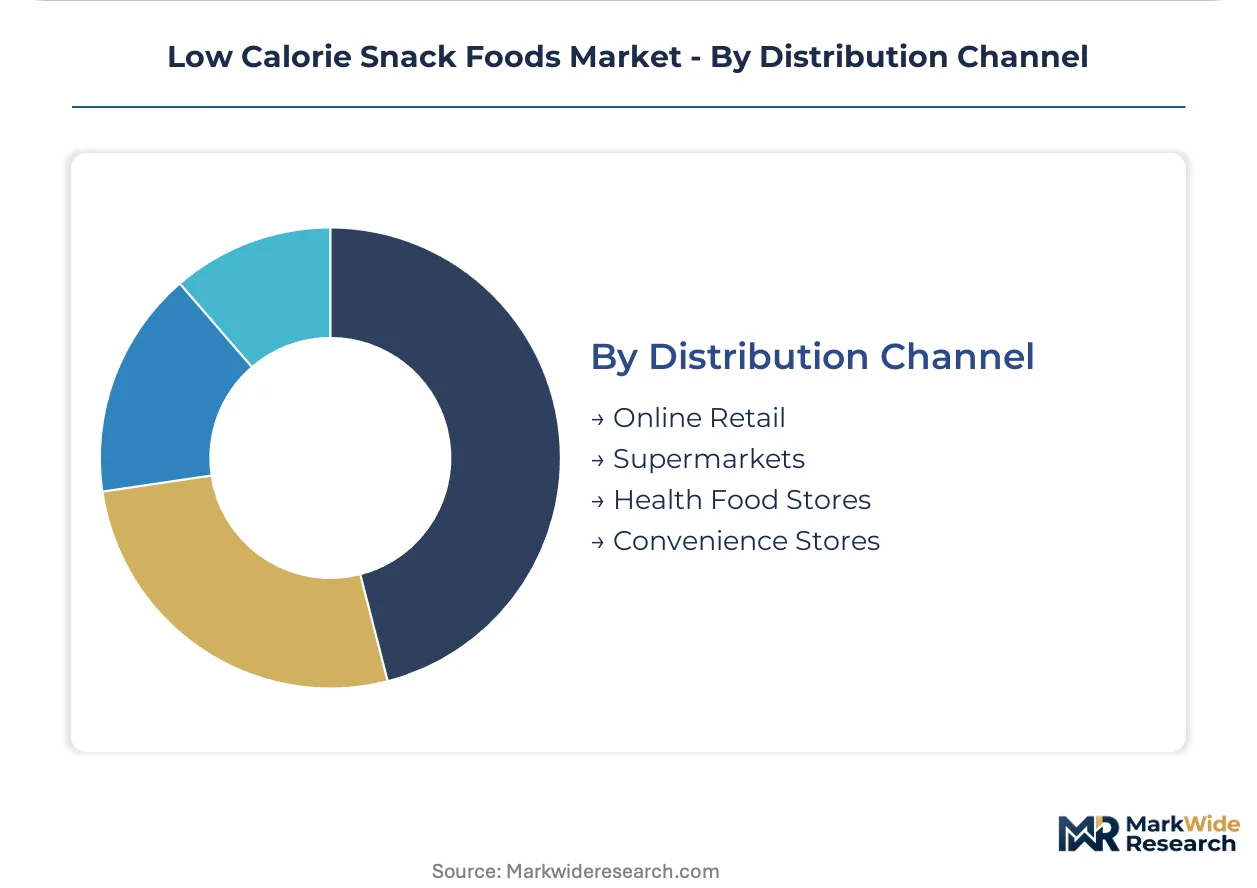
Distribution Channel:
Supply concentration varies dramatically between capital-intensive retail networks and asset-light digital fulfillment systems with divergent working capital requirements.
- Supermarkets:High-volume conventional retail commanding shelf placement fees and promotional slotting investments. Direct-store-delivery networks control prime positioning in United States mass-market channels, creating barriers for emerging brands without established distributor relationships.
- Online Retail:Digital-native fulfillment capturing recurring revenue through subscription models with data-driven personalization. Urban professionals in United States coastal cities concentrate here, where delivery density supports viable unit economics for customized portion sizing and flavor rotation.
- Health Food Stores:Specialty retail emphasizing certified organic, non-GMO, and allergen-free positioning with educated staff consultation.
- Convenience Stores:Impulse-oriented channels prioritizing single-serve packaging and immediate consumption occasions.
Supermarkets maintain volume dominance; online retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The low calorie snack foods industry traces its modern origins to post-war American food science laboratories, where caloric reduction technologies first achieved commercial scale before diffusing to European and Asian manufacturing centers.
United States
Urban professionals in coastal metropolitan corridors drive subscription-based replenishment through direct-to-consumer channels with customized flavor rotations. FDA updated Nutrition Facts labeling requirements for added sugars are compressing timelines for alternative sweetener integration across legacy portfolios. Chicago and Minneapolis anchor North American R&D clusters where reformulation expertise concentrates among food scientists commanding premium compensation.
Germany
Retail channels under EU Green Deal farm-to-fork mandates reward verified carbon accounting and regenerative sourcing credentials for plant-forward snack formats. EFSA novel food ingredient approvals govern alternative protein fortification in European formulations. Bavaria and Baden-Württemberg host soluble fiber additive processors whose REACH compliance status determines supply security for extruded bar manufacturers.
India
Tier-two cities present white space for portion-packaged snacks as FSSAI front-of-pack labeling mandates create first-mover advantages for compliant entrants. Health-conscious employers in technology and financial services sectors are expanding subsidized purchases through on-site vending contracts. Maharashtra and Karnataka concentrate manufacturing infrastructure for dehydrated vegetable-based products with caloric density below 100 kilocalories per portion.
Japan
Precision fermentation-derived proteins are converging with high-moisture extrusion to enable next-generation meat analogs at cost parity with conventional snacks. METI standards on food-contact substances govern migration testing requirements for bio-based barrier coatings in flexible packaging. Tokyo-Osaka industrial corridors anchor sports-nutrition demand for isolate-enriched bars delivering 15-20 grams protein per serving.
United Kingdom
Specialty retail channels emphasizing certified organic and non-GMO positioning capture educated consumer segments with staff consultation services. Health Canada and PMRA additive safety assessments influence cross-border product standardization with North American markets. London and Southeast England concentrate direct-store-delivery networks controlling prime supermarket shelf placement for baked chip and cracker segments.
Low Calorie Snack Foods Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protein-forward and plant-based formulation tiers, with isolate-enriched bars and precision fermentation-derived analogs commanding superior returns against conventional baked formats. The vendor base stratifies between multinational conglomerates with captive R&D infrastructure and mid-tier specialists dependent on external co-packing networks. Three archetypes dominate: science-forward reformulators, scale-driven commodity producers, and subscription-native digital brands. Competitive moves concentrate on strategic partnerships for novel ingredient access and geographic expansion into underpenetrated tier-two cities.
Within the multinational conglomerate tier, Nestle S.A. and PepsiCo occupy positions exemplifying divergent channel strategies—Swiss-incorporated science-forward reformulation against American scale-driven direct-store-delivery dominance. Mondelez International represents the portfolio diversification archetype, with Illinois-based operations spanning portion-packaging innovations. These three entities anchor the competitive structure without exhausting its variation, as Archer Daniels Midland Company and Cargill, Incorporated supply upstream inputs that constrain downstream formulation possibilities.
| Leading Market Players |
|---|
| General Mills, Inc |
| Nestle S.A. |
| Mondelez International |
| The Kraft Heinz Company |
| Conagra Brands, Inc |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Danone |
| PepsiCo |
| Others |
Supply & Pricing Matrix
Precision fermentation-derived protein integration is compressing unit economics for isolate-enriched bars while simultaneously concentrating production capabilities among biotech-equipped co-packers in Japan and the United States. This technology shift feeds back into pricing power dynamics, as brands with captive fermentation partnerships capture margin expansion unavailable to commodity-reliant competitors dependent on volatile botanical sweetener markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolate-enriched protein bars with sports-nutrition positioning from baked chips competing on supermarket volume and rice cakes anchored in mass-market accessibility. Price differentiation rests on certification grade for regenerative sourcing and brand premium for direct-to-consumer subscription loyalty. Cost compression in the premium tier is intensifying because stevia and monk fruit extract harvest volatility in China and Southeast Asia squeezes reformulated product margins. Health-conscious consumers in United States coastal metropolitan areas show lowest price sensitivity, while convenience store impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Direct-store-delivery networks handle hyperscale supermarket demand through PepsiCo-controlled shelf placement infrastructure in the United States and United Kingdom. Raw material sourcing draws from soluble fiber additive processors in Germany and Switzerland, precision fermentation facilities in Japan, and botanical extract harvests in China and Southeast Asia. Single-source vulnerability concentrates in European REACH-compliant fiber processors, where approval disruptions cascade through extruded bar manufacturing. Distribution runs through institutional procurement channels for corporate wellness contracts and subscription-based digital fulfillment for urban professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in low calorie snack foods rests on reformulation-driven cost-down trajectories as precision fermentation proteins achieve cost parity with conventional inputs, alongside premium-tier pull from sports-nutrition positioning and regenerative sourcing credentials.
For Market Incumbents: Deepen backward integration into precision fermentation protein supply through strategic partnerships with Japanese and United States biotech facilities, defending against emerging science-forward reformulators. Fortify direct-store-delivery network control in North American mass-market channels to maintain shelf placement barriers against digital-native subscription brands. Prioritize EFSA novel food ingredient approval pipelines for alternative fiber additives to compress certification timelines against competitor windows. For New Entrants and Emerging Players: Enter via India's tier-two cities where FSSAI front-of-pack labeling mandates create first-mover structural advantages for compliant portion-packaged snacks. Target corporate wellness procurement channels in United States technology and financial services sectors with institutional vending contracts that bypass supermarket slotting fee barriers. Lead with precision fermentation-derived meat analog positioning to capture flexitarian household adoption at premium price points. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier co-packing-dependent specialists lacking captive R&D infrastructure or alternative sweetener supply hedges. Long-term viability concentrates in science-forward reformulators with dual expertise in sensory optimization and regulatory navigation, alongside subscription-native digital brands with recurring revenue density in coastal metropolitan corridors. Monitor EFSA approval velocity for novel fiber and protein ingredients as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures cost-parity protein supply from Japanese METI-regulated facilities for meat analog production. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from United States urban professionals with data-driven flavor rotation personalization. |
| Regenerative Sourcing Certification | Unlocks EU Green Deal farm-to-fork compliance premiums in German and United Kingdom retail channels. |
| Alternative Sweetener Supply Hedge | Mitigates agricultural yield volatility in China and Southeast Asia through multi-source botanical extract contracts. |
| Corporate Wellness Channel Expansion | Penetrates institutional procurement in United States technology and financial services sector on-site vending contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food science R&D directors, brand managers at multinational conglomerates, category buyers at United States supermarket chains, and supply planners at European soluble fiber processors with secondary validation from FDA Nutrition Facts labeling guidance documents, EFSA novel food approval databases, EU Green Deal farm-to-fork policy releases, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across product type, ingredient category, end-user archetype, and distribution channel dimensions anchored volume and value projections over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating reformulation cost trajectories, regulatory timeline compression effects, and channel shift velocity among urban professional demographics. Industry-specific forecast inputs included precision fermentation capacity buildout schedules and FSSAI front-of-pack labeling implementation phases.
Inputs from EFSA approval databases and Chinese botanical extract harvest reports were available through the study window; gaps in real-time corporate wellness contract disclosure introduce uncertainty bands around institutional channel sizing. Forecasts reflect documented assumptions regarding alternative sweetener cost stabilization and REACH compliance continuity for European fiber processors. Periodic stress-testing of base assumptions is recommended against regulatory acceleration scenarios and precision fermentation technology cost-breakthrough timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fiber Bars Market
Snacks
Veggie Chips Market
Snacks
No-Fat Peanut Butter Market
Snacks
Super Low Calorie Snacks Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Snack Food Packaging Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
South Korea Snack Bar Market
Snacks
Seaweed Snacks Market
Snacks
Middle East Snack Bar Market
Snacks
United Kingdom Energy Bar Market
Snacks
Global Snack Food Market
Snacks
South America Protein Bar Market
Snacks
Packaged Rice Snacks Market
Snacks
Extruded Cereals Market