
 Snack Food Packaging Market | 2026-2036
Snack Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Food Packaging Market Intelligence
The shift toward high-barrier, multi-layer flexible films with advanced resealable features is redrawing the competitive landscape for premium snack products. Amcor Plc leverages its extensive global manufacturing footprint to supply major food conglomerates with these solutions. Berry Global Group Inc. specializes in a wide array of rigid and flexible solutions for diverse snack applications. Mondi Plc competes effectively with a strong portfolio in both paper-based packaging and flexible plastic alternatives.
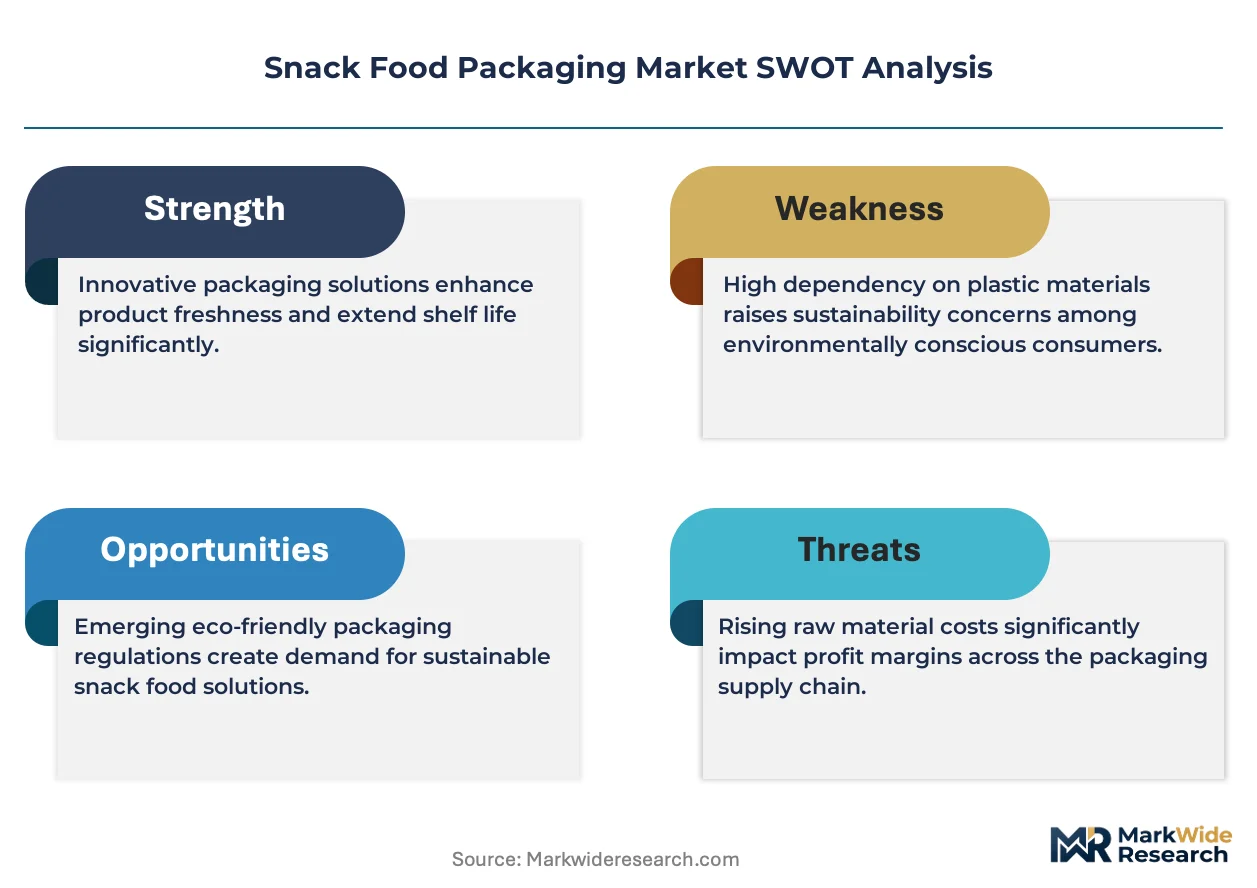
Snack food packaging encompasses materials and formats engineered to protect products like chips, nuts, and confectionery from moisture, oxygen, and physical breakage. These solutions must meet specific oxygen transmission rates (OTR) and moisture vapor transmission rates (MVTR) to maintain product freshness and extend shelf life. Flexible pouches continue to dominate the packaging format segment due to their light weight and superior branding surface area. While plastic remains the prevalent material type, biodegradable polymers are gaining significant market share, driven by sustainability mandates.
Packaging composition and food contact safety are strictly governed by regulations like the US FDA's Title 21 CFR and the EU's Framework Regulation (EC) No 1935/2004. China's GB standards for food contact materials also impose stringent requirements on producers and importers. These frameworks dictate permissible materials and require extensive migration testing to ensure consumer safety. Navigating the evolving landscape of single-use plastic regulations and circular economy initiatives remains the central strategic challenge.
Market Dynamics
The central tension shaping the snack food packaging market is the conflict between stringent food preservation requirements and mounting regulatory pressure for sustainable, circular materials. This dynamic forces innovation in polymer science and package design to meet both high-barrier performance and end-of-life recyclability mandates.
Growth Catalysts
- Convenience-Driven Formats:Demand from India's urban consumers for single-serving and on-the-go snack options accelerates the adoption of flexible pouches and portion-controlled packs, expanding volume for packaging converters.
- Regulatory Mandates for Recyclability:Circular economy frameworks, including the EU Green Deal, create a powerful incentive for brands to adopt mono-material films and other easily recyclable packaging solutions to meet legislative targets and avoid penalties.
- Advanced Biodegradable Polymers:The commercialization of high-barrier biodegradable polymers, such as advanced PLA grades, allows brands to market sustainable packaging without compromising the shelf life required for products like nuts and dried fruits.
Market Restraints
- Polymer Price Volatility:Fluctuations in the price of petroleum-based resins, a primary raw material for plastic films, introduce significant cost instability and margin pressure for packaging manufacturers.
- Performance Gaps in Green Materials:Certain compostable and biodegradable materials still exhibit lower moisture and oxygen barrier properties (MVTR/OTR) compared to conventional multi-layer laminates, limiting their use for sensitive snack products.
- Fragmented Regulatory Compliance:Navigating disparate food contact safety regulations, such as the US FDA's Title 21 CFR versus China's GB standards, increases testing costs and time-to-market for companies operating globally.
Strategic Opportunities
- Emerging Market Penetration:Rapid urbanization and rising disposable incomes in Southeast Asian countries present significant white-space opportunities for packaged snack brands and their packaging suppliers.
- Smart and Interactive Packaging:Integrating QR codes or NFC technology into packaging for premium snacks offers a new channel for brand storytelling, traceability, and direct consumer engagement.
- Plant-Based Snack Category:The expansion of plant-based and alternative protein snacks creates demand for specialized packaging that addresses unique requirements for freshness, moisture control, and brand positioning in a high-growth segment.
Industry Challenges
- High Capital Investment:Re-tooling manufacturing lines to process new mono-material structures or biodegradable polymers requires significant capital expenditure, creating a barrier for smaller converters.
- Food-Grade Certification Delays:Achieving food contact approvals from bodies like the European Food Safety Authority (EFSA) for novel recycled or bio-based materials is a time-consuming and expensive process.
- PCR Supply Chain Constraints:Sourcing a consistent, high-quality supply of food-grade post-consumer recycled (PCR) plastic remains a major operational hurdle for converters aiming to meet brand sustainability goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Food Packaging Market |
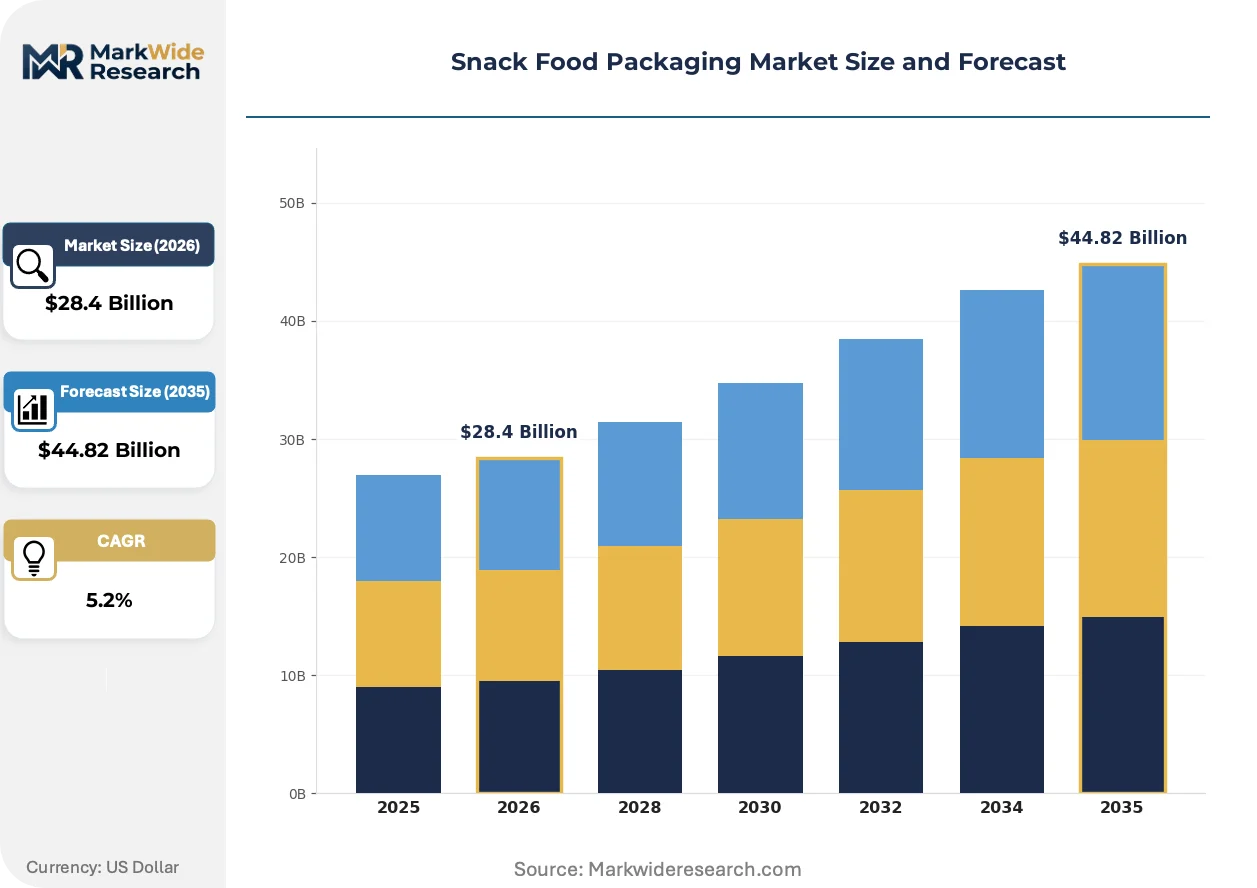
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paperboard, Aluminum Foil, Biodegradable Polymers, Composite Materials Packaging Format: Pouches, Boxes, Trays, Wraps, Cups, Tubes Closure Type: Resealable Zipper, Heat Seal, Snap Lid, Tear Notch, Adhesive Tape End User Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Food Stores |
| Companies Covered | Huhtamaki Oyj, Berry Global Group Inc., Amcor Plc, ProAmpac LLC, Mondi Plc, Smurfit Kappa Group plc, Sealed Air Corporation, Constantia Flexibles Group GmbH, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Food Packaging Market Strategic Shifts & Innovations
The industry's pivot toward circularity is the dominant theme, compelling a fundamental redesign of materials to balance product protection with end-of-life viability. This shift prioritizes innovations that enable recycling within existing infrastructure, moving beyond theoretical biodegradability.
Mono-material flexible films, particularly those based on all-polyethylene (PE) or all-polypropylene (PP) structures, are designed specifically for recyclability. Major consumer packaged goods companies are rapidly adopting these solutions for products like potato chips and confectionery to meet public sustainability commitments. This technology is supplanting traditional, unrecyclable mixed-polymer laminates that have long dominated the flexible packaging sector.
Extended Producer Responsibility (EPR) schemes, gaining legislative force across the European Union and other jurisdictions, are altering packaging economics. These regulations place the financial burden of collection, sorting, and recycling directly on brand owners and packaging producers. The policy most directly affects producers of hard-to-recycle formats like multi-layer pouches, forcing them to redesign for circularity or face escalating fees.
Consumers are increasingly using on-pack digital triggers like QR codes to verify sustainability claims and product origins before purchase. This behavior disrupts traditional marketing channels by prioritizing transparent, data-backed supply chain information over brand messaging alone. This trend is most pronounced among health-conscious buyers in North American and European markets, particularly within the organic and premium snack segments.
Snack Food Packaging Market Segmentation
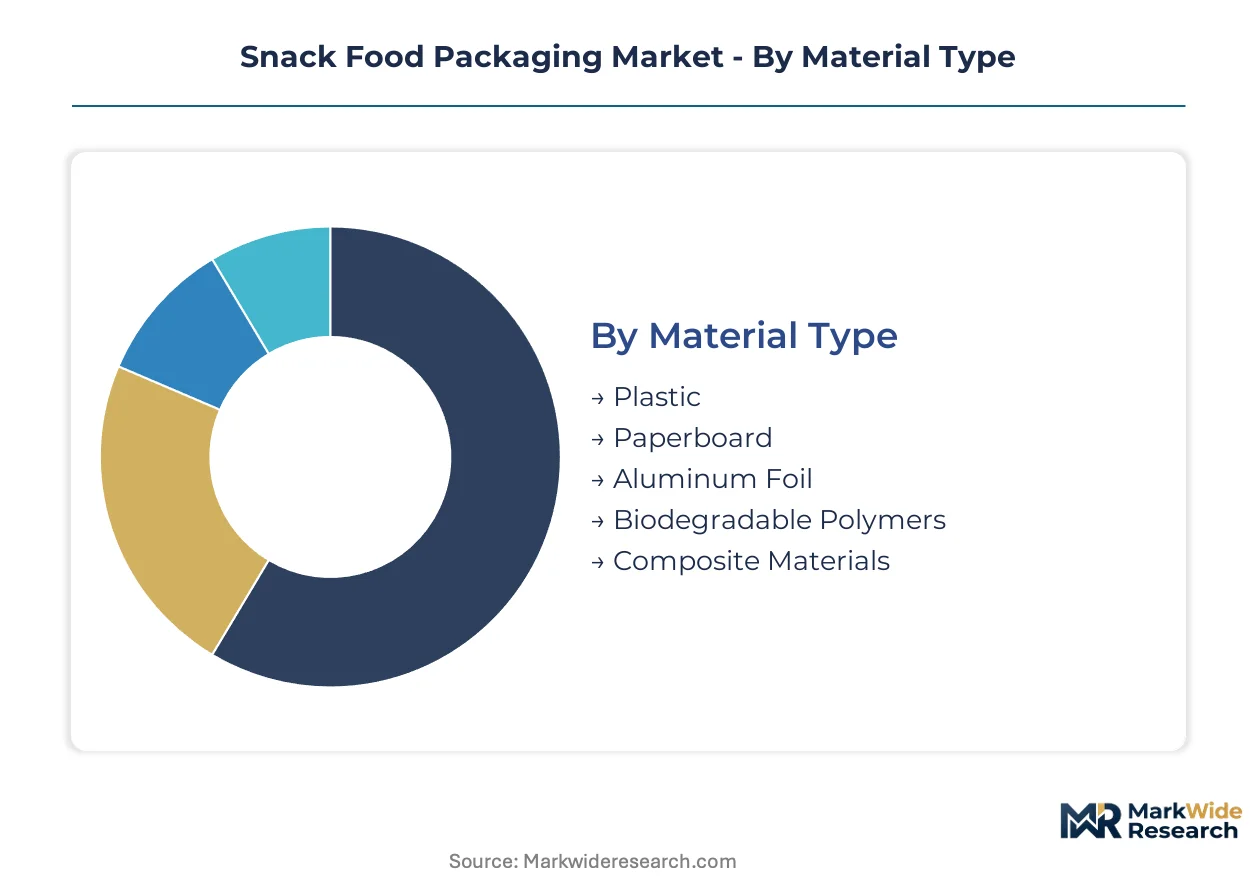
Understanding the distinct segments within the snack food packaging market is critical for identifying specific demand drivers and technological shifts. Packaging solutions must align with product characteristics, consumer preferences, and channel-specific logistics to ensure both product integrity and market success.
Material Type:
The choice of packaging material often dictates the distribution channel, influencing shelf stability and aesthetic appeal for snack products.
- Plastic:High barrier properties protect sensitive snacks from oxygen and moisture, making plastic ubiquitous across supermarket and convenience store channels. Demand from global food conglomerates drives significant volume.
- Biodegradable Polymers:These materials, including advanced PLA grades, offer a sustainable alternative without compromising shelf life for premium snacks sold in specialty food stores and online. Sustainability mandates from the EU Green Deal accelerate their adoption.
- Paperboard:Provides structural integrity and branding surface for snack boxes and trays, often found in multi-packs sold in supermarkets.
- Aluminum Foil:Offers superior barrier protection against light, oxygen, and moisture, essential for extending the shelf life of delicate snack items.
- Composite Materials:Multi-layer structures combine different material properties to achieve specific barrier and strength requirements for diverse snack applications.
By volume, Plastic leads. By growth pace, Biodegradable Polymers are ahead.
Packaging Format:
Snack product characteristics and consumption occasions primarily determine the optimal packaging format.
- Pouches:Lightweight and flexible, pouches offer excellent branding surface area and are ideal for single-serving, on-the-go snack formats. Their dominance is notable in India's urban consumer market for chips and nuts.
- Boxes:Provide robust protection and stackability for confectionery and multi-pack snack offerings, frequently utilized in supermarket aisles. Their rigid structure supports premium branding.
- Trays:Often used for delicate baked goods or snack assortments, providing product visibility and protection during transport.
- Wraps:Commonly employed for confectionery bars and individual snack portions, offering basic protection and branding space.
- Cups:Suited for yogurt, fruit, and other semi-liquid snack varieties, providing convenient portion control and portability.
- Tubes:Specialty format for stackable snacks like potato crisps, offering structural integrity and brand recognition.
Pouches demonstrate the broadest market reach across diverse snack categories, while Boxes secure substantial share in multi-pack offerings.
Closure Type:
Consumer convenience and product freshness mandates heavily influence the selection of closure mechanisms for snack packaging.
- Resealable Zipper:Extends product freshness and offers convenience for multi-serving snack packs, appealing to consumers seeking portion control and waste reduction. This feature is particularly valued in premium snack products.
- Heat Seal:Provides a tamper-evident, air-tight barrier crucial for maintaining the shelf life of sensitive snack items like chips and nuts. It remains the most common primary seal for flexible packaging.
- Snap Lid:Offers easy reclosure for rigid containers such as snack cups and tubs, ensuring product integrity after initial opening.
- Tear Notch:Facilitates easy opening for single-serving flexible pouches, enhancing consumer accessibility for on-the-go snacks.
- Adhesive Tape:Used for reclosing snack bags or securing box flaps, providing a simple and cost-effective closure solution.
Resealable Zipper closures hold strategic importance for premiumization, while Heat Seal remains foundational for product protection across all snack segments.
End User Channel:
The distribution dynamics of snack products are fundamentally shaped by the specific end-user channel, impacting packaging requirements.
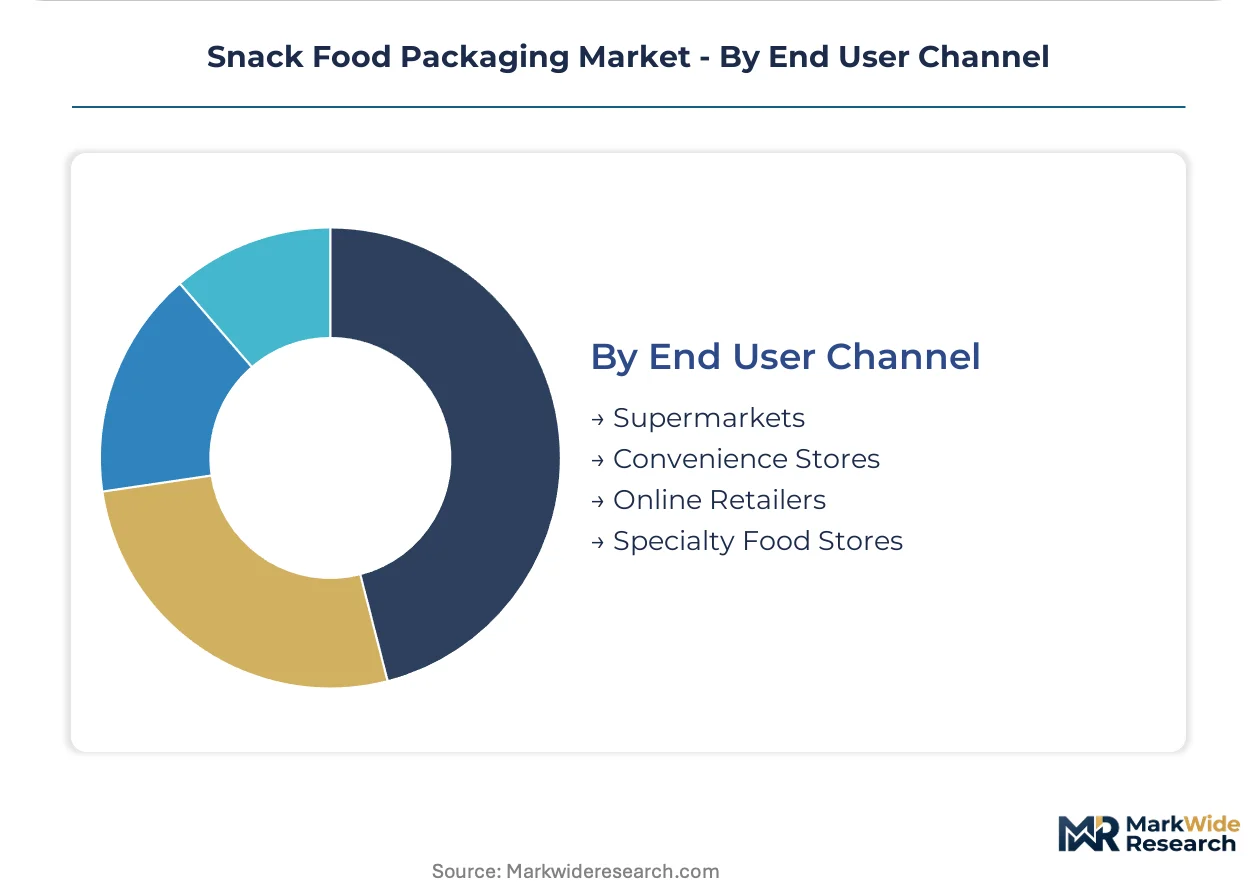
- Supermarkets:Represent the dominant channel for snack food sales, requiring packaging designed for shelf appeal, bulk purchasing, and efficient logistics. High-volume sales in this channel drive demand for cost-effective, yet protective, packaging solutions.
- Online Retailers:Demand packaging optimized for shipping resilience, minimal weight, and often unique branding opportunities suitable for direct-to-consumer delivery. Traceability features like QR codes are increasingly important for this channel.
- Convenience Stores:Focus on single-serving, on-the-go snack formats that prioritize portability and immediate consumption.
- Specialty Food Stores:Cater to niche markets, often requiring premium, aesthetically pleasing, and sustainable packaging for artisanal or organic snack offerings.
Supermarkets continue to drive the largest packaging volumes, while Online Retailers are expanding most quickly, necessitating innovation in e-commerce friendly designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The movement of sustainable packaging technologies from European innovators to North American consumer brands is reshaping material specifications across key markets. This dynamic influences investment in advanced polymer science and package design globally. Emerging economies, particularly in Asia, are also driving demand for packaging solutions tailored to rapid urbanization and shifting consumer preferences.
United States
Health-conscious consumers and the demand for convenience-driven formats propel packaging innovation in the United States. The US FDA's Title 21 CFR dictates stringent food contact safety regulations for all packaging materials. California's food tech hubs, particularly around San Francisco, are driving innovation in plant-based snack packaging solutions.
China
China's expanding middle class and the rapid growth of e-commerce for snacks demand resilient and aesthetically pleasing packaging. China's GB standards for food contact materials impose strict requirements on both domestic and imported packaging. Cities within the Yangtze River Delta, such as Shanghai, are witnessing significant investment in high-barrier film production capabilities.
India
India's urban consumer base, with its preference for single-serving and on-the-go snack options, significantly boosts demand for flexible packaging. FSSAI guidelines influence packaging material choices and labeling requirements for local producers. Mumbai and Delhi's organized retail sectors are increasing demand for flexible pouches and portion-controlled packs.
Germany
Strong sustainability mandates and a preference for recyclable packaging drive material innovation in Germany. The EU Green Deal policies accelerate the adoption of mono-material films and other circular packaging solutions. The Rhine-Ruhr region is a significant center for advanced polymer research and packaging manufacturing.
Brazil
Rapid urbanization and rising disposable incomes for packaged goods are key drivers for snack food packaging in Brazil. ANVISA regulations govern food packaging safety and material composition, influencing market entry for international players. São Paulo's robust food processing industry is a major consumer of flexible and rigid snack packaging formats.
Snack Food Packaging Market Key Industry Players
Listed leaders compete with private specialists across material innovation and geographic reach within the snack food packaging market. The market exhibits a tiered structure, encompassing large multinational corporations and specialized regional manufacturers. Global packaging conglomerates, flexible packaging specialists, and sustainable material innovators represent key strategic archetypes. Strategic partnerships for material development and geographic expansion into emerging markets represent dominant competitive moves.
At the global scale end of the market, Amcor Plc leverages its extensive manufacturing footprint to serve major food conglomerates with advanced packaging solutions. Berry Global Group Inc. occupies a position as a provider of a wide array of rigid and flexible solutions for diverse snack applications. Mondi Plc exemplifies a strong portfolio across both paper-based packaging and flexible plastic alternatives, particularly for premium snack products.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Berry Global Group Inc. |
| Amcor Plc |
| ProAmpac LLC |
| Mondi Plc |
| Smurfit Kappa Group plc |
| Sealed Air Corporation |
| Constantia Flexibles Group GmbH |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
High-volume flexible packaging conversion lines demand consistent raw material supply, concentrating production among a few major polymer producers. This scale also establishes competitive price floors for standard snack packaging formats.
Pricing Analysis
The pricing gap between conventional multi-layer laminates and advanced mono-material films for snack packaging reflects ongoing material innovation. Contract-based long-term offtake agreements dominate, influenced by material barrier properties and sustainability certifications. Pricing pressure stems from volatile petroleum-based resin costs, impacting manufacturers' margins. Large food conglomerates are less price-sensitive for premium, high-barrier solutions, while smaller brands prioritize cost-effectiveness for standard applications.
Supply Chain Analysis
China and India anchor significant flexible packaging conversion capacity, supplying a vast consumer market. The supply chain draws from petroleum-based resins, specialized barrier coatings, and advanced biodegradable polymers. Polymer price volatility introduces significant cost instability for packaging manufacturers. Distribution runs through a mix of direct sales to large CPGs and regional distributors serving smaller brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snack food packaging market presents a fragmentation opportunity, driven by the rise of specialized plant-based and alternative protein snacks. This shift creates distinct packaging niches requiring tailored material and format solutions.
For Market Incumbents: Shield market share by rapidly retooling manufacturing lines for mono-material flexible films. This addresses mounting regulatory pressure from EU Green Deal policies. Invest in advanced barrier technologies for biodegradable polymers to close performance gaps against conventional plastics. Capacity addition in key European and North American manufacturing hubs can secure long-term supply. For New Entrants and Emerging Players: Niche packaging design for plant-based snack brands represents a significant white-space opportunity. Target e-commerce-optimized formats for direct-to-consumer brands, particularly within specialty food stores in North American and European markets. Emphasize rapid prototyping capabilities and verifiable sustainability certifications. This approach bypasses the high capital investment required for large-scale conventional production. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among packaging converters specializing in high-barrier mono-material films. The market offers sustained growth over the next decade due to non-discretionary consumer demand for snacks. Target vertically integrated specialists with strong R&D in biodegradable polymers or food-grade PCR processing. The commercialization success of advanced PLA grades in large-scale snack applications serves as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material Production Lines | Enables compliance with EU Green Deal and other EPR schemes, reducing financial penalties for brand owners. |
| Develop Advanced Biodegradable Barrier Coatings | Closes performance gaps for sensitive snack products, expanding the addressable market for sustainable materials. |
| Expand Food-Grade PCR Sourcing Networks | Secures consistent supply of post-consumer recycled content, meeting brand sustainability goals and consumer demand. |
| Integrate Smart Packaging Technologies | Enhances brand storytelling and traceability for premium snacks, fostering direct consumer engagement in North America. |
| Target Southeast Asian Market Expansion | Capitalizes on rapid urbanization and rising disposable incomes, capturing new consumer segments for flexible pouches. |
Research Approach
Initial hypotheses were tested against primary input from packaging engineers, brand managers, and raw material suppliers. Regulatory affairs specialists also provided critical insights. This primary data was validated through extensive secondary research, including US FDA filings, EU Framework Regulation documents, and China's GB standards. Bottom-up data collection was triangulated with top-down market sizing to ensure robust analysis.
Variance decomposition identified key drivers impacting snack food packaging market growth across the analysis window. A multi-factor analytical framework modeled segmentation dimensions including material type, packaging format, and end-user channel. Compound Annual Growth Rates were derived from an iterative process of supply-side capacity modeling and demand-side consumption patterns. Polymer price forecasts and evolving single-use plastic regulations served as critical inputs.
Forecasts assume regulatory continuity in the US FDA, EU EFSA, and China GB standards regimes; material policy shifts would require re-modeling. The analysis reflects current market dynamics, acknowledging that significant shifts in global trade policies or unforeseen technological breakthroughs could alter projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Vegan Protein Balls Market
Snacks
Low Fat Protein Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
Plant-Based Snacks Market
Snacks
Europe Extruded Snack Food Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
North America Energy Bar Market
Snacks
Asia Pacific Snack Food Market
Snacks
Savoury Biscuits Market
Snacks
Fried Potato Chips Market
Snacks
Better for You Snacks Market
Snacks
Snack Products Market
Snacks
Organic Snack Food Market
Snacks
Crispy Fruit Chips Market
Snacks
United Kingdom Snack Bar Market
Snacks
Dairy Snacks Market