
 Sweet Potato Flour Market | 2026-2036
Sweet Potato Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Potato Flour Market Outlook
Specialty health food store distribution is reshaping how sweet potato flour reaches end consumers. Ingredion Incorporated leverages its ingredient science infrastructure to supply formulated blends to commercial bakeries. Carolina Innovative Food Ingredients Inc. anchors its position through direct relationships with southeastern US sweet potato growers. FutureCeuticals, Inc. differentiates by concentrating on spray-dried and micronized particle specifications for nutritional applications.
Sweet potato flour consists of dehydrated, milled tuber flesh, typically exhibiting 8-12% residual moisture and amylopectin-dominant starch structures that yield viscous pastes upon hydration. Manufacturers employ drum-drying or flash-drying processes to preserve carotenoid content and achieve consistent granulation for industrial use. Organic flour commands premium positioning as certified acreage contracts tighten supply availability. Gluten-free flour competes aggressively in baking applications where wheat substitution requires precise rheological matching. Snack foods represent the fastest-growing end use as extruded chip and puff manufacturers reformulate for allergen-free claims.
The FDA enforces Current Good Manufacturing Practice regulations for allergen controls that sweet potato flour processors must document through hazard analysis protocols. USDA organic certification requirements govern labeling integrity for products entering natural retail channels. FSMA traceability mandates will intensify record-keeping burdens across root-to-package supply chains. Stakeholders must monitor how evolving clean-label definitions and gluten-free threshold standards influence formulation decisions and procurement specifications.
Market Dynamics
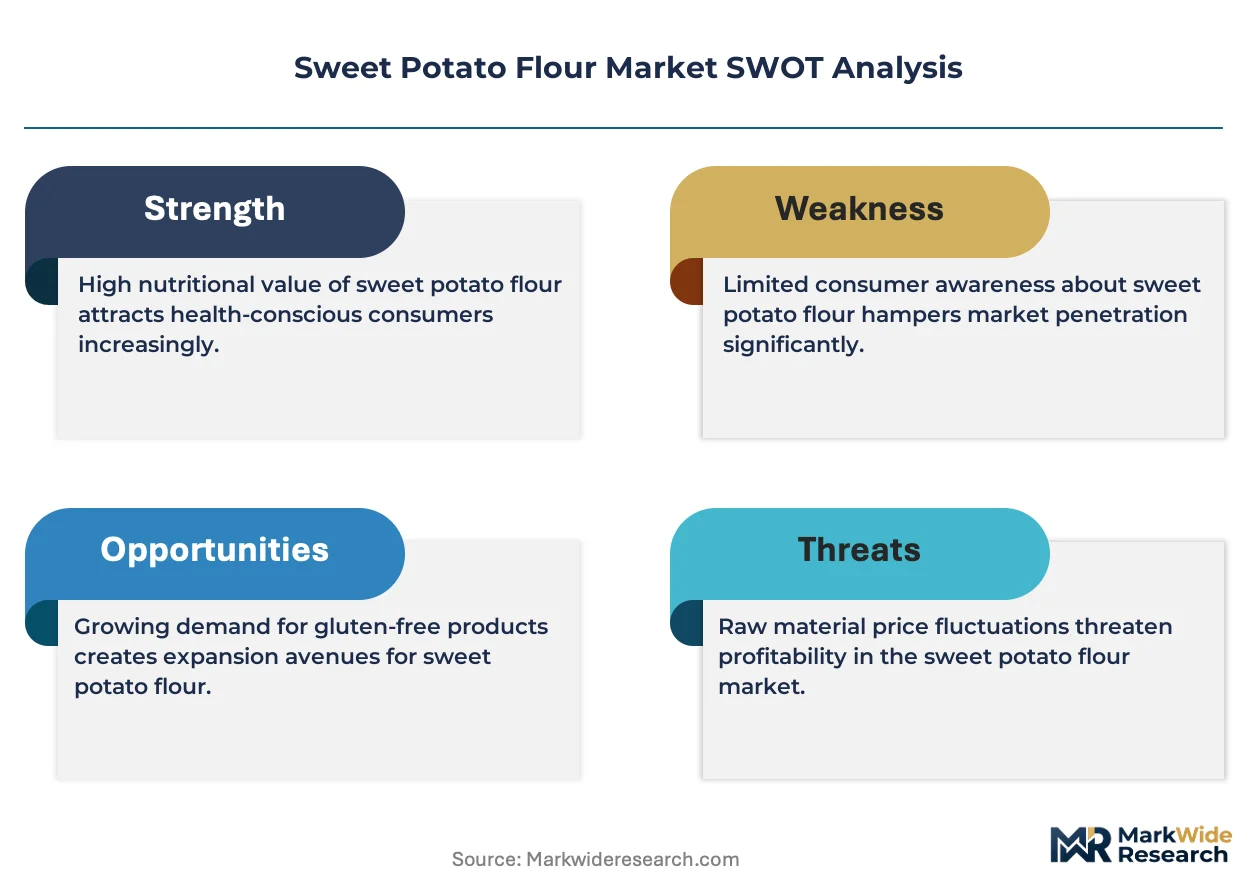
Clean-label reformulation mandates from major retailers are compressing formulation cycles for sweet potato flour suppliers, forcing processors to validate allergen-free claims through accelerated third-party certification timelines.
Growth Catalysts
- FDA Food Safety Modernization Act traceability rules:Processors investing in lot-tracking infrastructure capture shelf space from non-compliant competitors as retailers enforce documentation standards.
- Extruded snack manufacturing:Allergen-free puff and chip producers absorb volume as reformulation pipelines accelerate to meet retailer clean-label requirements.
- Organic certified acreage contracts:Tight supply availability for certified organic flour creates premium positioning and margin expansion for contracted growers.
Market Restraints
- Input cost volatility:Southeastern US sweet potato harvest variability exposes processors to raw material price swings that compress operating margins.
- Technical limitation in wheat substitution:Amylopectin-dominant starch structures require rheological modifiers that increase formulation complexity and cost.
- Substitution threat from cassava flour:Neutral-flavor alternatives compete aggressively in gluten-free baking applications where taste masking is critical.
Strategic Opportunities
- Micronized particle specifications:Nutritional applications in functional foods absorb spray-dried flour at premium price points.
- Specialty health food retail channels:Direct-to-consumer distribution bypasses conventional grocery slotting fees and builds brand equity.
- USDA organic certification pipeline:Early investment in certifier relationships secures supply allocation before competitor capacity comes online.
Industry Challenges
- FSMA compliance timeline compression:Hazard analysis documentation requirements strain quality assurance staffing at mid-scale processors.
- Carotenoid preservation expertise gap:Drum-drying optimization requires process engineering talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Potato Flour Market |
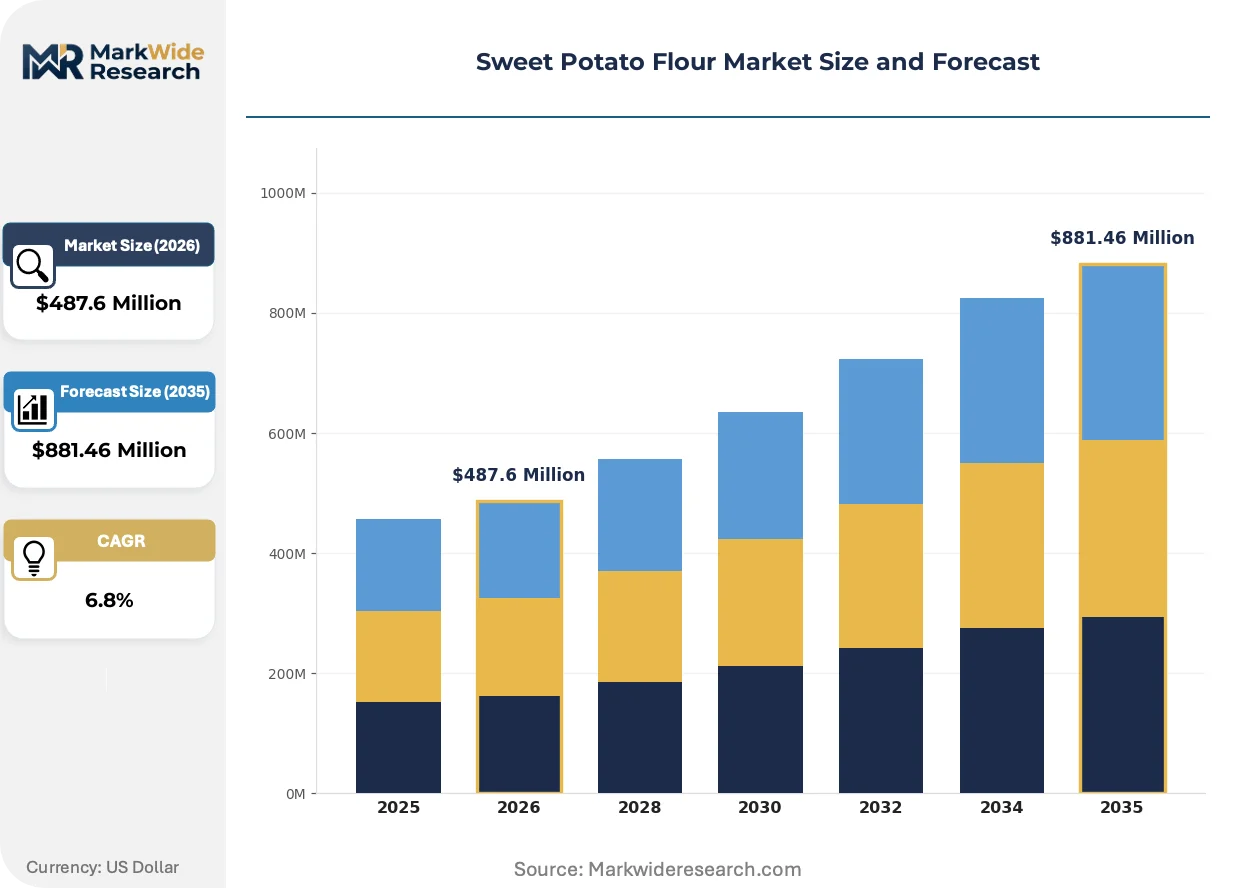
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Flour, Gluten-Free Flour, Instant Flour, All-Purpose Flour End Use: Baking, Snack Foods, Sauces, Nutritional Supplements Packaging Type: Bags, Boxes, Bulk Containers, Sachets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Saipro Biotech Private Limited, Live Glean, Barry Farm Foods, FutureCeuticals, Inc., SACOMA, Hearth Foods, Milne MicroDried, Ingredion Incorporated, Carolina Innovative Food Ingredients Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Potato Flour Market Strategic Shifts
Processing technology and regulatory documentation requirements are reshaping competitive differentiation, with particle engineering and traceability infrastructure becoming primary value levers rather than commodity volume.
Flash-drying technology is migrating from conventional drum-drying configurations as processors seek higher carotenoid retention rates and tighter moisture control. Commercial bakeries adopting these specifications report improved shelf stability in finished goods. The capital intensity of this transition is consolidating supplier tiers around scaled operators with technical service capabilities.
REACH substance registration requirements in Europe are tightening purity documentation for root-derived ingredients entering cosmetic and nutraceutical channels. Exporters to EU markets now face expanded testing protocols for heavy metals and pesticide residues. Natural retail channels in Germany and France absorb this compliance cost through certified supply premiums.
Direct sourcing relationships between flour processors and regional grower cooperatives are displacing spot-market procurement. Southeastern US sweet potato farming clusters now contract directly with ingredient manufacturers, bypassing agricultural commodity traders. This channel shift concentrates in snack food manufacturing where lot consistency and origin claims support clean-label marketing.
Sweet Potato Flour Market Segmentation
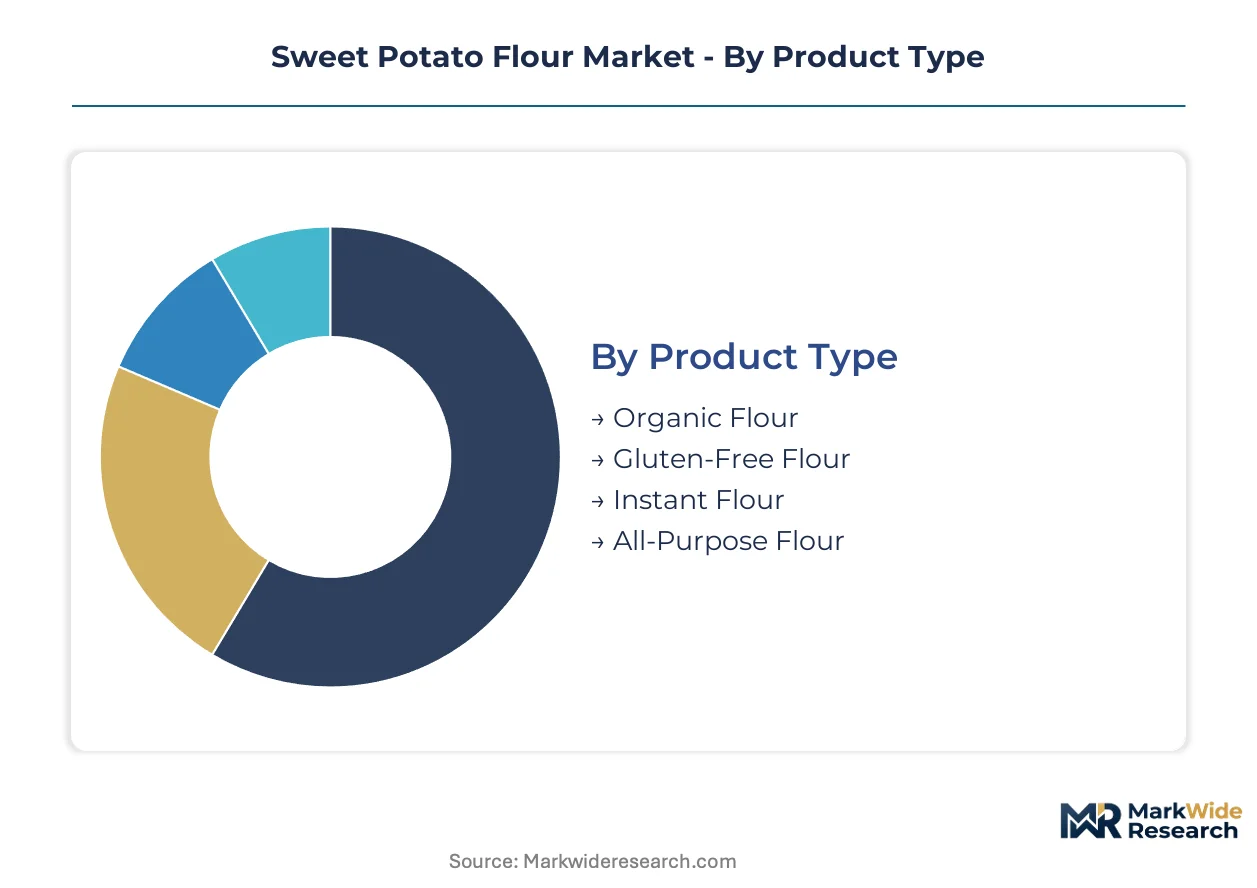
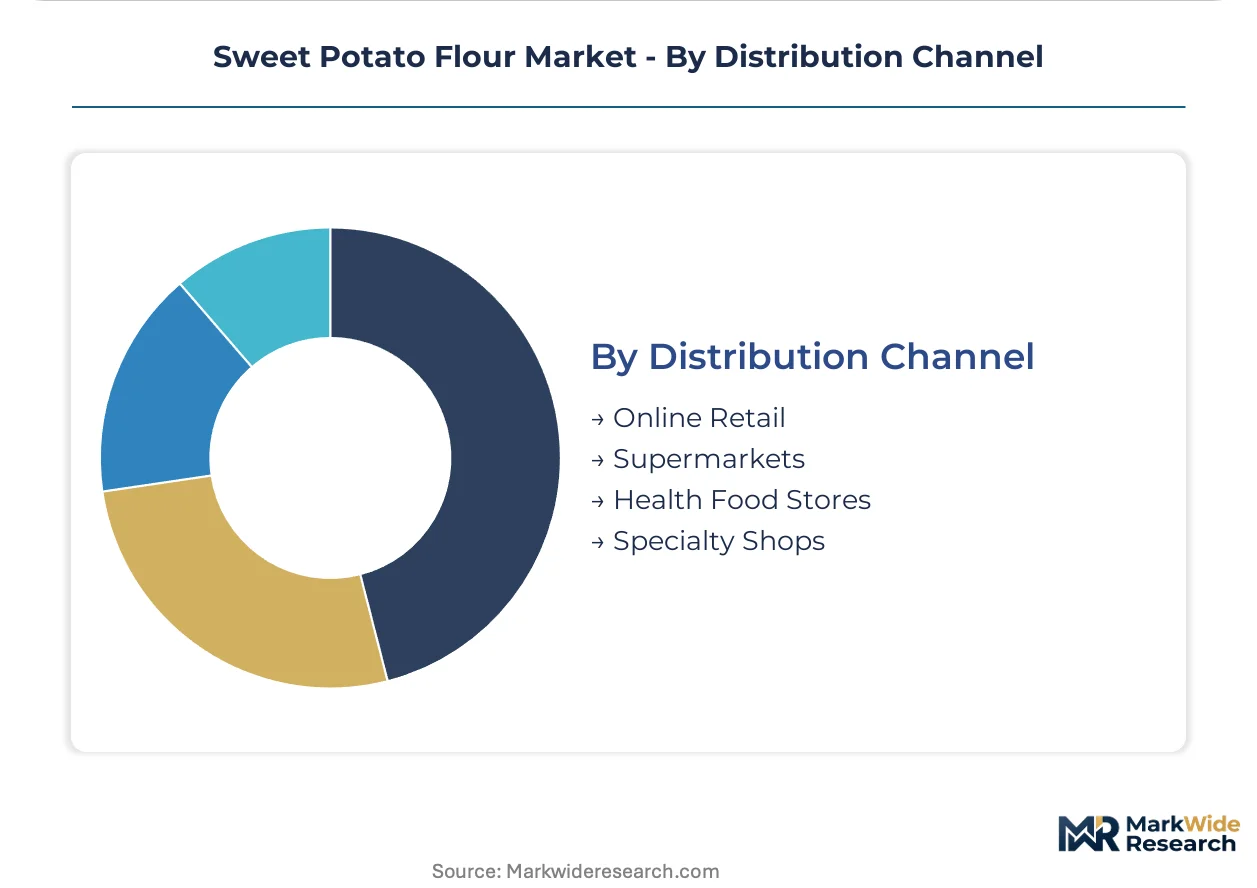
Sweet potato flour segmentation reflects divergent technical specifications across food manufacturing, nutritional formulations, and retail distribution. Each category carries distinct margin profiles and regulatory documentation burdens that reshape supplier priorities.
Product Type:
The use-case spectrum spans certified organic baking applications to instant reconstitution products requiring precise hydration kinetics.
- Organic Flour:Certified acreage contracts with USDA-accredited bodies command premium positioning in natural retail channels. Demand concentrates in clean-label snack manufacturing across the United States as retailers enforce documentation standards for allergen-free claims.
- Gluten-Free Flour:Amylopectin-dominant starch structures require rheological modifiers for wheat substitution in commercial bakeries. North American celiac-safe formulations absorb larger volumes as FDA traceability mandates tighten lot-tracking requirements.
- Instant Flour:Pre-gelatinized specifications enable rapid hydration for beverage and convenience food applications.
- All-Purpose Flour:Standard granulation serves cost-sensitive industrial baking with minimal processing overhead.
The dominant share belongs to Gluten-Free Flour, while Organic Flour is closing the gap fastest.
End Use:
Application concentration varies sharply by formulation complexity and carotenoid preservation requirements.
- Snack Foods:Extruded chip and puff manufacturers reformulate for allergen-free claims using flash-dried specifications. Clean-label mandates from major retailers accelerate volume absorption as reformulation pipelines compress.
- Baking:Commercial bakeries demand consistent granulation for shelf stability in finished goods. Viscous paste characteristics from amylopectin structures necessitate precise hydration control in gluten-free bread applications.
- Sauces:Thickening applications leverage the flour's natural binding properties in prepared foods.
- Nutritional Supplements:Micronized particle specifications serve functional food formulations at premium price points.
Snack Foods generates the steepest expansion trajectory, with Nutritional Supplements climbing fastest in value terms.
Packaging Type:
Packaging selection tracks customer scale and shelf-life requirements from bulk industrial procurement to single-serve retail.
- Bulk Containers:Food manufacturers with captive extrusion lines purchase multi-ton quantities under direct contracts with southeastern US processors. Lot consistency requirements favor this format for snack food production.
- Bags:Standard 5-25 lb formats serve commercial bakeries and mid-scale foodservice operations.
- Boxes:Retail-ready packaging supports natural channel distribution with origin claims and certification logos.
- Sachets:Single-serve portions target direct-to-consumer sampling and travel-size nutritional products.
Bulk Containers anchor procurement volume, though Bags gain share through specialty health food store expansion.
Distribution Channel:
Channel structure determines margin capture and brand equity accumulation for flour processors.
- Health Food Stores:Direct relationships with regional cooperatives bypass conventional grocery slotting fees. Certified organic flour achieves premium positioning through staff education and origin storytelling.
- Online Retail:E-commerce platforms enable micronized and spray-dried specifications to reach nutritional supplement formulators nationwide.
- Supermarkets:Mass retail placement requires FSMA-compliant documentation and third-party allergen certification.
- Specialty Shops:Ethnic and gourmet retailers serve niche baking applications with imported or heritage varietal flours.
Health Food Stores command the highest margin per unit, while Online Retail expands most quickly through subscription and bulk purchase models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA traceability mandates under the Food Safety Modernization Act are reshaping procurement patterns across the largest consuming geography. Processors investing in lot-tracking infrastructure capture shelf space from non-compliant competitors as retailers enforce documentation standards.
United States
Clean-label snack manufacturers in the Southeast absorb larger volumes as reformulation pipelines accelerate. USDA organic certification requirements govern labeling integrity for products entering natural retail channels. North Carolina's sweet potato farming clusters contract directly with ingredient processors, bypassing agricultural commodity traders.
China
Domestic food manufacturers demand flash-dried specifications for carotenoid retention in extruded products. SAMR enforces GB standards for food additive usage in root-derived ingredients. Shandong Province processors expand drum-drying capacity to serve export markets.
Germany
Natural retail channels absorb certified organic flour at premium price points through staff education and origin storytelling. REACH substance registration requirements tighten purity documentation for cosmetic and nutraceutical applications. Bavaria-based distributors consolidate procurement from southeastern US growers.
Japan
Functional food formulators source micronized particle specifications for nutritional supplement applications. METI guidelines influence import documentation for allergen-free claims. Osaka-area trading houses specialize in spray-dried flour for beverage manufacturers.
India
Commercial bakeries experiment with gluten-free formulations as celiac awareness expands in urban centers. FSSAI labeling requirements govern allergen declarations for imported root-derived ingredients. Maharashtra's food processing parks attract contract manufacturing for export-oriented snack producers.
Sweet Potato Flour Market Competitive Environment
Ingredient science specialists and direct-sourcing regional processors split the market between formulated blend supply and grower-integrated production. The structure concentrates around scaled operators with technical service capabilities and mid-scale processors with captive agricultural relationships. Two strategic archetypes dominate: multinational ingredient platforms leveraging R&D infrastructure, and southeastern US-based processors controlling raw material access through acreage contracts. Competitive moves center on flash-drying technology licensing and accelerated third-party certification timelines for allergen-free claims.
Within the multinational platform tier, Ingredion Incorporated and FutureCeuticals, Inc. represent contrasting approaches to value capture. Among regional direct-sourcing specialists, Carolina Innovative Food Ingredients Inc. exemplifies grower-integrated production models. Saipro Biotech Private Limited occupies a position serving nutritional applications with specialized particle specifications. These three anchors demonstrate how scale, agricultural integration, and technical differentiation create defensible positions under tightening FDA documentation requirements.
| Leading Market Players |
|---|
| Saipro Biotech Private Limited |
| Live Glean |
| Barry Farm Foods |
| FutureCeuticals, Inc. |
| SACOMA |
| Hearth Foods |
| Milne MicroDried |
| Ingredion Incorporated |
| Carolina Innovative Food Ingredients Inc. |
| Others |
Value Chain & Pricing Dynamics
Southeastern US sweet potato farming clusters concentrate upstream supply, anchoring margin pools with processors holding direct acreage contracts and bypassing commodity traders. Retailer clean-label mandates downstream compress formulation cycles, transferring documentation compliance costs into supplier pricing power.
Pricing Analysis
Geographic price spreads widen between certified organic flour from contracted southeastern growers and spot-market conventional grades from international origins. Pricing stratifies across premium certified organic, mid-tier gluten-free, and economy all-purpose tiers driven by certification level and volume scale. Cost compression in economy grades intensifies because cassava flour substitution erodes price floors. Commercial bakeries exhibit highest price sensitivity due to formulation complexity costs, while nutritional supplement formulators show lowest sensitivity for micronized specifications.
Supply Chain Analysis
Upstream feedstock draws from North Carolina, Mississippi, and Louisiana farming clusters with concentrated harvest seasons. Raw material dependencies rest on sweet potato varietal selection, drum-drying or flash-drying equipment capacity, and third-party organic certification infrastructure. Single-source vulnerability runs through southeastern weather exposure and harvest variability. Distribution feeds from processor direct contracts to snack food manufacturers, with health food store channels bypassing conventional grocery warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as FDA Food Safety Modernization Act traceability mandates force retailer procurement shifts toward documented supply chains, accelerating volume concentration with compliant processors.
For Market Incumbents: Harden FSMA-compliant lot-tracking infrastructure to capture shelf space from non-compliant competitors as retailers enforce documentation standards. Deepen backward integration into certified organic acreage contracts before competitor capacity secures limited supply. Flash-drying technology licensing represents a priority defensive lever against substitution threats from cassava flour processors.
For New Entrants and Emerging Players: Build out micronized particle specification capabilities for nutritional supplement applications where premium pricing tolerates new supplier qualification timelines. Direct-to-consumer health food store distribution offers the most penetrable channel, bypassing slotting fee barriers that protect incumbent grocery placement. Origin storytelling and staff education partnerships with regional cooperatives provide differentiation against commodity-positioned rivals.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ingredient platforms lacking direct grower relationships, presenting rollup opportunities for agricultural integration. Long-term viability centers on processors controlling certified acreage contracts through the projection horizon. Watch for FDA enforcement actions against non-compliant processors as the inflection signal for market share redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash-Drying Technology Licensing | Carotenoid retention rates differentiate suppliers for clean-label snack manufacturers. |
| USDA Organic Certification Pipeline Investment | Early certifier relationships secure supply allocation before competitor capacity enters. |
| Direct Grower Cooperative Contracts | Bypassing agricultural commodity traders captures margin and origin claim credibility. |
| Micronized Particle Specification Development | Spray-dried flour commands premium positioning in functional food formulations. |
| FSMA Traceability Infrastructure Buildout | Lot-tracking documentation satisfies retailer enforcement and displaces non-compliant rivals. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement managers, quality assurance directors at snack food manufacturers, organic certifier executives, and health food store category buyers; alongside secondary validation through FDA FSMA guidance documents, USDA organic certification records, customs trade data for root-derived ingredients, and SEC filings from publicly traded ingredient processors. Bottom-up volume modeling from processor capacity and grower acreage contracts triangulated against top-down demand estimation from end-use consumption patterns.
Forecast inputs considered product type segmentation across organic, gluten-free, instant, and all-purpose grades; end-use concentration in snack foods, baking, sauces, and nutritional supplements; packaging format differentiation between bulk containers and retail-ready formats; and distribution channel structure spanning health food stores, online retail, supermarkets, and specialty shops. CAGRs were derived from regression analysis against historical volume trajectories, incorporating input cost volatility assumptions and regulatory compliance timeline acceleration.
Stress conditions across southeastern US harvest variability, cassava flour substitution elasticity, and FDA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label mandate adoption curves and organic certification pipeline constraints. Cross-checking against USDA National Agricultural Statistics Service acreage reports and FDA inspection citation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Corn Co-Products Market