
 Global Guayusa Market | 2026-2036
Global Guayusa Market Size, Share, and Industry Trends Forecast 2026-2036
Global Guayusa Market Analysis
EU Novel Food Regulation is pivoting the cost-of-entry calculus for Amazonian botanical suppliers seeking European market access. RUNA leverages direct-trade relationships with Ecuadorian indigenous cooperatives to anchor its raw material security. Waykana Tea Company competes through specialized single-origin sourcing that sustains premium positioning in specialty retail channels.
Guayusa is a caffeinated holly leaf native to the upper Amazon basin, typically dried and processed into cut leaves or extracts containing approximately 20-50 mg caffeine per cup alongside theobromine and L-theanine. Its primary commercial purpose centers on delivering sustained mental clarity without the jitter effects common to synthetic caffeine sources. Extract forms currently command the strongest margin pools within product type segmentation, reflecting pharmaceutical and functional food manufacturer demand for standardized actives. Health Enthusiasts represent the fastest-expanding end user category, though Beverage Manufacturers still dominate absolute volume procurement.
FDA GRAS self-affirmation pathways and EFSA Novel Food consultations jointly determine which guayusa formats achieve commercial scale in North America and Europe respectively. Ecuador's national biosafety authority and the Convention on Biological Diversity Nagoya Protocol compliance requirements further shape export licensing for wild-harvested genetic resources. Stakeholders must monitor evolving alkaloid standardization mandates across multiple jurisdictions to anticipate which supply chain investments will retain regulatory validity.
Market Dynamics
Clean-label beverage manufacturers are consolidating procurement around direct-trade supply networks with Ecuadorian indigenous cooperatives, bypassing commodity auction channels that previously dominated Amazonian botanical sourcing.
Growth Catalysts
- EU Novel Food Regulation pathway completion:EFSA consultations for dried leaf and extract formats are unlocking formulation access for European functional beverage brands previously blocked by regulatory uncertainty.
- Sustained-release caffeine demand:Beverage formulators are substituting guayusa for synthetic caffeine in ready-to-drink portfolios targeting jitter-sensitive professional demographics.
- Ecuadorian export infrastructure:Guayaquil port cold-chain investments and Nagoya Protocol compliance offices are reducing shipment spoilage rates for wild-harvested leaf consignments.
Market Restraints
- Wild-harvest supply concentration:Over 80% of commercial leaf originates from Ecuadorian Amazonian provinces, creating climate and political risk exposure without cultivated acreage diversification.
- Novel Food consultation costs:EFSA safety dossier preparation and toxicology studies impose six-figure euro expenditures that exclude smaller Amazonian cooperative exporters from European market access.
- Standardized extract input volatility:Pharmaceutical-grade alkaloid standardization requires laboratory verification that fluctuates with Ecuadorian laboratory capacity constraints.
Strategic Opportunities
- Japanese regulatory opening:PMDA consultation pathways for caffeine-containing botanicals remain underdeveloped, creating first-mover positioning for compliant suppliers in Asia-Pacific's third-largest functional beverage market.
- Pharmaceutical adaptogen convergence:L-theanine and theobromine co-extraction is attracting nutraceutical manufacturers seeking multi-compound cognitive support formulations.
- Direct-to-specialty-retail channels:E-commerce subscription models for single-origin loose leaf are bypassing traditional tea importer markups in North American urban markets.
Industry Challenges
- Indigenous knowledge documentation:Nagoya Protocol compliance requires formal benefit-sharing agreements with Kichwa and Shuar communities that lack standardized contract templates.
- Alkaloid batch consistency:Wild-harvested leaf exhibits natural caffeine variation that complicates finished product label claim verification for beverage manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Guayusa Market |
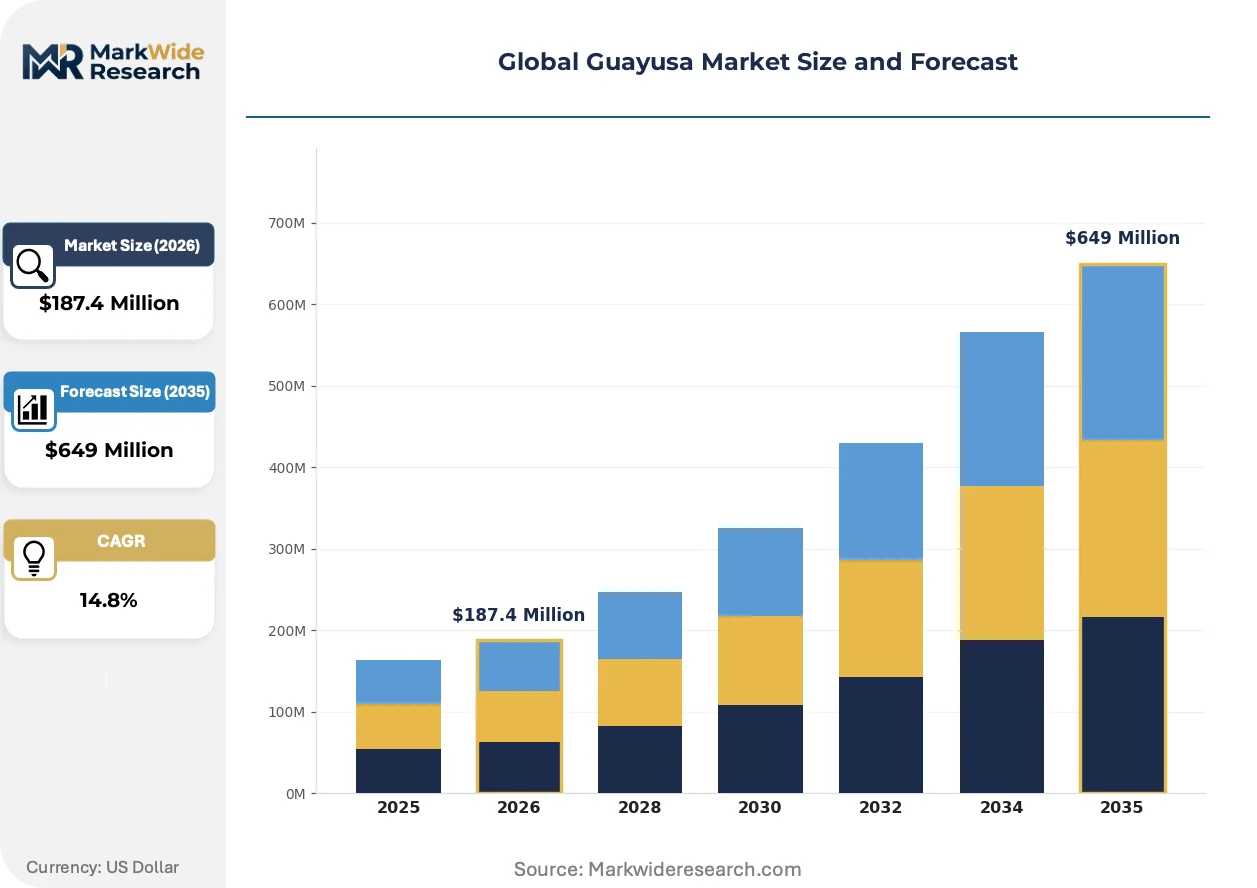
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $649 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Powder, Extract End User: Retail Consumers, Food Services, Health Enthusiasts, Beverage Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Application: Beverages, Health Supplements, Functional Foods, Natural Remedies |
| Companies Covered | Stash Tea Company, Waykana Tea Company, RUNA, Harney & Sons, BI Nutraceuticals, Applied Food Sciences, Wa-yusa, Mountain Rose Herbs, Doehler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Guayusa Market Emerging Trajectories
Processing technology and regulatory clarity are converging to reshape competitive positioning between raw leaf traders and vertically integrated extract producers.
Supercritical CO2 extraction is consolidating margin capture toward pharmaceutical and nutraceutical contract manufacturers. Beverage formulators in the United States are adopting standardized guayusa extract at accelerating rates to achieve precise caffeine dosing in multi-ingredient energy blends. This technology compression is marginalizing traditional cut-leaf suppliers in commodity-grade procurement channels.
EFSA Novel Food consultation completion for additional guayusa formats is reshaping European market entry economics. Industrial consequence includes accelerated safety dossier investment by Ecuadorian export consortiums seeking preemptive regulatory positioning. Specialty tea distributors in Germany and France are responding by building direct-import relationships that bypass legacy botanical trading houses.
Specialty coffee retail channels are integrating guayusa as a non-coffee caffeine alternative on shared brewing equipment. Independent cafés in Pacific Coast US cities are displacing traditional yerba mate offerings with single-origin Ecuadorian leaf programs. This consumption-pattern rotation is most visible in Portland, Seattle, and Los Angeles metro markets where equipment interoperability reduces menu expansion capital requirements.
Global Guayusa Market Segmentation
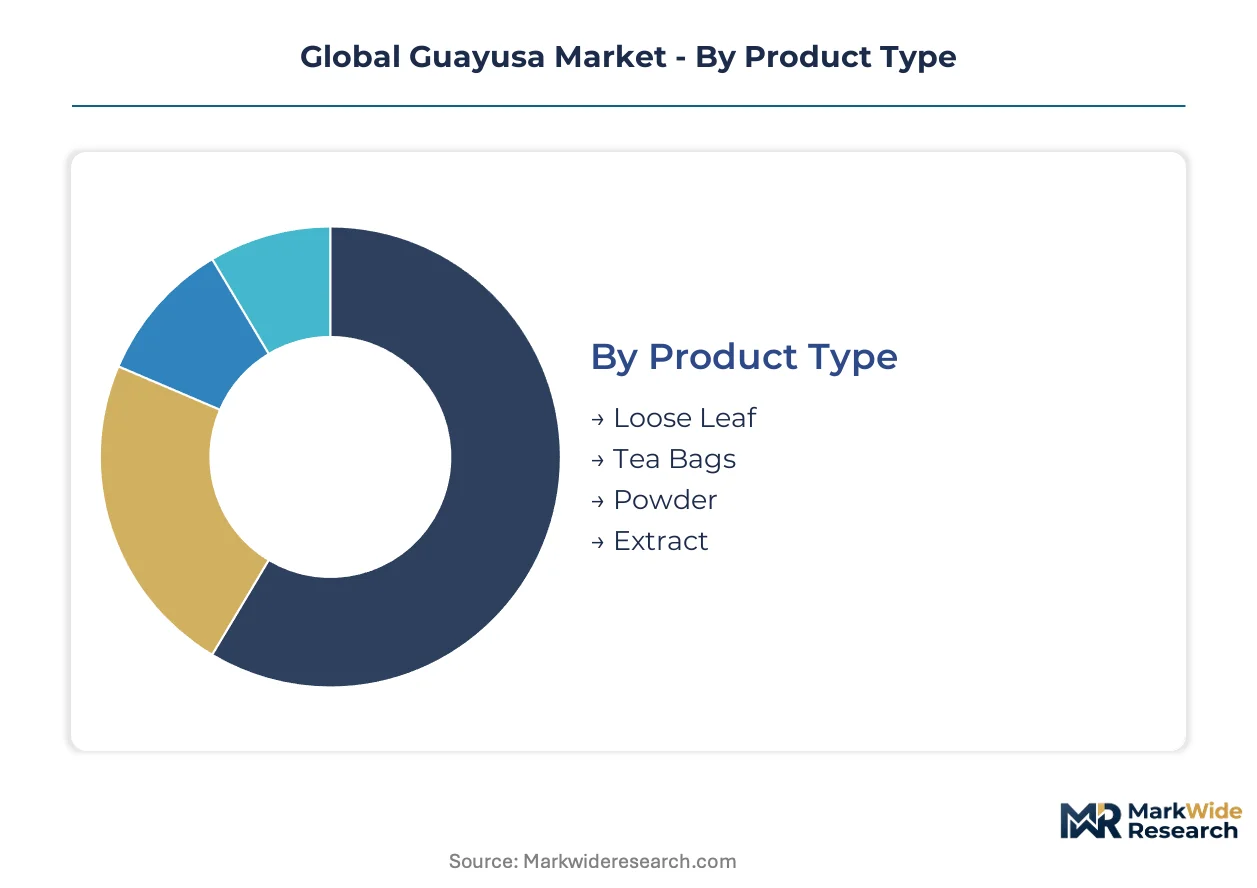
Guayusa's commercial trajectory splits across four distinct classification axes. Each axis carries divergent certification burdens that determine which suppliers can access which customer tiers.
Product Type:
EFSA Novel Food consultations and FDA GRAS self-affirmation requirements fall unevenly across these formats, with concentrated alkaloid products facing the steepest regulatory scrutiny.
- Extract:Standardized caffeine and L-theanine concentrates undergo pharmaceutical-grade laboratory verification. Beverage manufacturers in the United States procure this format for precise dosing in multi-ingredient energy formulations, though Ecuadorian laboratory capacity constraints create input volatility.
- Loose Leaf:Dried whole leaves retain the broadest regulatory approval footprint across jurisdictions. Direct-trade networks with Ecuadorian indigenous cooperatives concentrate procurement here for specialty retail channels in North American urban markets.
- Tea Bags:Cut-leaf sachets bridge convenience and single-origin positioning. German and French specialty distributors are building direct-import relationships that bypass legacy botanical trading houses for this format.
- Powder:Micronized leaf enables instant beverage applications. Functional food manufacturers favor this format for blending into smoothie bases and protein formulations.
Loose Leaf sits at the top of the volume ranking, with Extract climbing the fastest.
End User:
Margin capture potential stratifies sharply across these customer tiers, with institutional buyers commanding price leverage that individual consumers cannot replicate.
- Beverage Manufacturers:Ready-to-drink and multi-ingredient energy blend formulators drive absolute procurement tonnage. These buyers substitute guayusa for synthetic caffeine to target jitter-sensitive professional demographics in the United States.
- Health Enthusiasts:Individuals seeking sustained mental clarity without synthetic stimulant side effects. This cohort expands most quickly through e-commerce subscription models for single-origin loose leaf in Pacific Coast urban markets.
- Retail Consumers:Mainstream grocery and mass-market purchasers. Supermarket shelf placement remains limited outside specialty beverage aisles.
- Food Services:Independent cafés in Portland, Seattle, and Los Angeles integrate guayusa as a non-coffee caffeine alternative on shared brewing equipment, displacing traditional yerba mate offerings.
Beverage Manufacturers dominate absolute procurement, with Health Enthusiasts gaining share fastest.
Distribution Channel:
Channel selection determines whether suppliers capture premium positioning or compete as commodity inputs.
- Online Retail:Subscription models and direct-to-consumer platforms enable single-origin storytelling that justifies price premiums. This channel bypasses traditional tea importer markups most effectively.
- Specialty Stores:Curated urban retailers in Germany and France build direct-import relationships with Ecuadorian export consortiums. These outlets prioritize Nagoya Protocol compliance documentation and indigenous cooperative provenance.
- Health Food Shops:Natural products retailers stock guayusa alongside adaptogen and nootropic assortments. FDA GRAS status supports shelf placement confidence.
- Supermarkets:Mass-market grocery chains require scale and standardized supply that wild-harvested sourcing struggles to guarantee consistently.
Specialty Stores anchor premium positioning, with Online Retail expanding most quickly.
Application:
Formulation complexity and regulatory pathway length vary substantially across these use cases.
- Beverages:Ready-to-drink, brewed, and instant formats constitute the primary commercial outlet. Clean-label energy positioning drives substitution away from synthetic caffeine across United States functional beverage portfolios.
- Health Supplements:Capsule and tablet applications require pharmaceutical-grade alkaloid standardization. Supercritical CO2 extraction technology concentrates margin capture toward contract manufacturers serving this segment.
- Functional Foods:Powder integration into bars, snacks, and meal replacements. L-theanine and theobromine co-extraction attracts nutraceutical manufacturers seeking multi-compound cognitive support formulations.
- Natural Remedies:Traditional indigenous use cases documented for Nagoya Protocol compliance. Formal benefit-sharing agreements with Kichwa and Shuar communities remain essential for wild-harvested sourcing legitimacy.
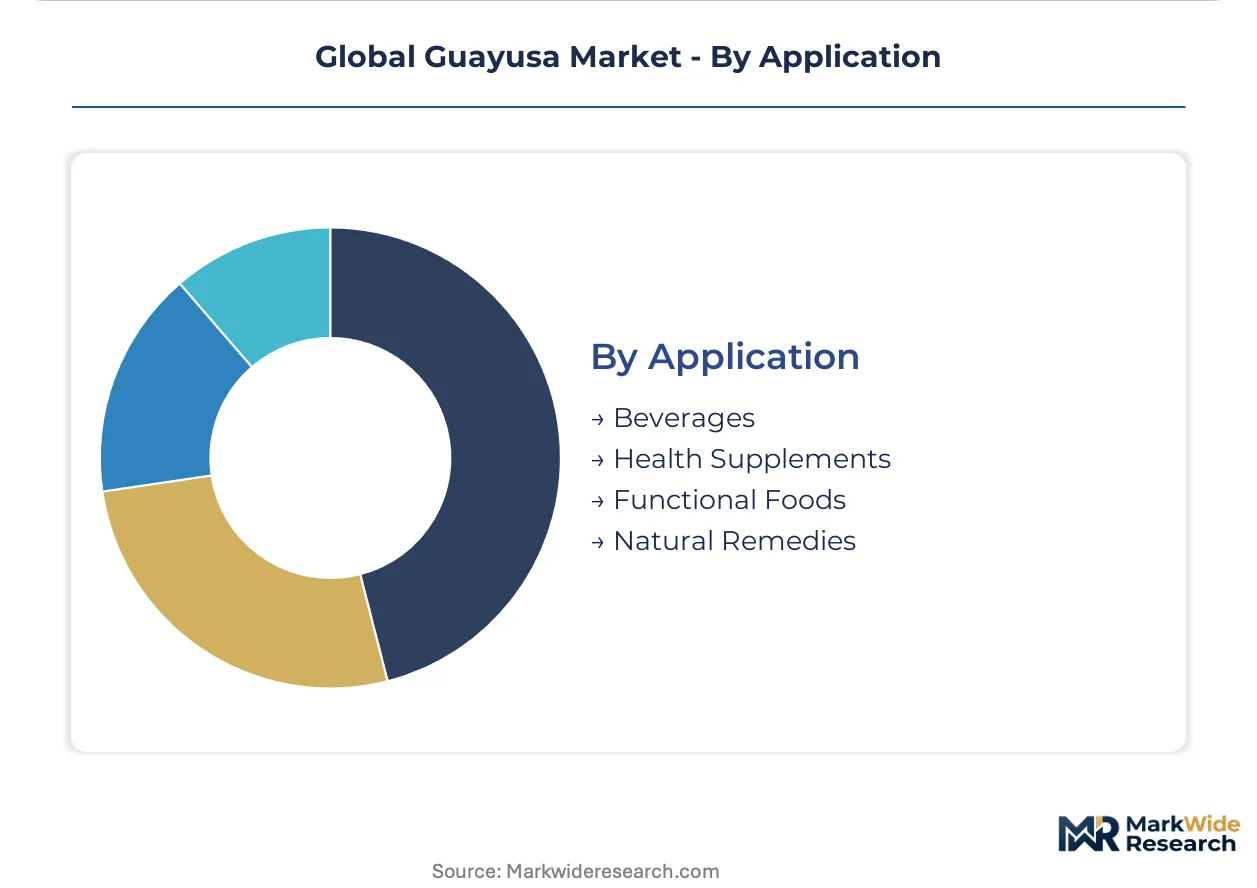
Beverages command the largest absolute volume, with Health Supplements following the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guayusa cultivation and commercialization trace their modern lineage to Ecuador's Amazonian provinces, where Kichwa and Shuar communities developed wild-harvesting traditions centuries before functional beverage industrialization. This Ecuadorian heritage now anchors supply networks that extend across three continents through distinct regulatory and demand environments.
United States
Functional beverage startups in Portland, Seattle, and Los Angeles drive procurement innovation through direct-trade relationships with Ecuadorian cooperatives. FDA GRAS self-affirmation pathways enable rapid formulation iteration for clean-label energy products. Pacific Coast urban clusters concentrate specialty café integration where guayusa displaces yerba mate on shared brewing equipment.
Germany
Specialty tea distributors in Berlin and Hamburg build direct-import relationships that bypass legacy botanical trading houses. EFSA Novel Food consultations for dried leaf formats unlock formulation access previously blocked by regulatory uncertainty. Bavarian natural products retailers anchor Nagoya Protocol compliance documentation requirements for indigenous cooperative provenance.
France
Parisian curated retailers prioritize single-origin storytelling that justifies price premiums in specialty channels. ANSM oversight of novel food ingredients shapes import documentation standards for Amazonian botanicals. Île-de-France functional food manufacturers explore L-theanine and theobromine co-extraction for cognitive support formulations.
Japan
PMDA consultation pathways for caffeine-containing botanicals remain underdeveloped, creating first-mover positioning opportunities in Asia-Pacific's third-largest functional beverage market. Tokyo metropolitan health enthusiasts drive subscription model experimentation for sustained-release caffeine alternatives. Kansai region import distributors evaluate Ecuadorian export consortium partnerships ahead of regulatory clarity.
Canada
Health Canada Natural Health Product regulations govern guayusa extract approval timelines for nutraceutical applications. Vancouver and Toronto natural products retailers stock guayusa alongside adaptogen assortments through cross-border supply relationships with US distributors. British Columbia e-commerce platforms enable single-origin loose leaf subscription models that bypass traditional importer markups.
Global Guayusa Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists controlling upstream Ecuadorian sourcing relationships. Market concentration remains moderate, with distinct tiers separating indigenous cooperative-linked brands from commodity botanical traders. Two strategic archetypes dominate: direct-trade originators leveraging Nagoya Protocol compliance for premium positioning, and extract specialists capturing pharmaceutical-grade margin pools through supercritical CO2 technology. Capacity expansion into standardized alkaloid production and strategic partnerships with Ecuadorian export consortiums constitute the dominant competitive moves.
Within the direct-trade originator tier, RUNA and Waykana Tea Company exemplify supply chain architectures built around Ecuadorian indigenous cooperative relationships. RUNA anchors raw material security through formal benefit-sharing agreements with Kichwa communities, while Waykana occupies a position emphasizing specialized single-origin sourcing. Among established beverage houses, Stash Tea Company and Harney & Sons represent legacy tea industry incumbents integrating guayusa into diversified botanical portfolios. BI Nutraceuticals and Applied Food Sciences sit within the extract specialist archetype, targeting pharmaceutical and functional food manufacturer demand for standardized actives.
| Leading Market Players |
|---|
| Stash Tea Company |
| Waykana Tea Company |
| RUNA |
| Harney & Sons |
| BI Nutraceuticals |
| Applied Food Sciences |
| Wa-yusa |
| Mountain Rose Herbs |
| Doehler |
| Others |
Supply Flow & Price Mechanics
Kichwa harvester cooperatives in Ecuador's Napo and Pastaza provinces anchor labor-cost structures that widen spreads between premium single-origin and commodity-grade guayusa. Wild-harvesting skill concentration in these Amazonian regions ties pricing tiers directly to indigenous knowledge premiums and Nagoya Protocol compliance documentation costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic single-origin loose leaf from conventionally harvested cut leaf and bulk extract commodities. Price differentiation rests on EFSA Novel Food consultation completion and indigenous cooperative provenance certification. Pricing pressure stems from Ecuadorian laboratory capacity constraints affecting pharmaceutical-grade alkaloid standardization. Beverage manufacturers exhibit highest price sensitivity due to volume procurement scale, while health enthusiasts tolerate premium positioning for subscription-model single-origin access.
Supply Chain Analysis
Dual-sourcing mandates from FDA-regulated beverage manufacturers and EFSA-compliant European formulators require qualification of multiple Ecuadorian export consortiums. Supply concentrates in Ecuador's Amazonian provinces, with secondary sourcing emerging from Peruvian border regions and Colombian Putumayo. Raw material flows draw from wild-harvested leaf, supercritical CO2 extraction inputs, and dried processing infrastructure. Single-source vulnerability persists around Guayaquil port cold-chain chokepoints. Distribution runs through direct-trade networks with indigenous cooperatives, specialty tea importers in Germany and France, and North American e-commerce subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in extract standardization capabilities and Japanese regulatory first-mover positioning as cost-down drivers from supercritical CO2 technology adoption reshape competitive economics.
For Market Incumbents: Deploy Nagoya Protocol compliance documentation as a defensive moat against emerging commodity traders lacking indigenous cooperative relationships. Deepen backward integration into Ecuadorian export consortium partnerships to secure captive supply of wild-harvested leaf amid climate risk exposure. Counter threat from synthetic caffeine substitution by accelerating EFSA Novel Food pathway completion for additional extract formats. For New Entrants and Emerging Players: E-commerce subscription platforms offer the most penetrable channel entry for single-origin storytelling that bypasses legacy importer markups. Target Japanese PMDA consultation preparation ahead of regulatory clarity in Asia-Pacific's third-largest functional beverage market. Pursue white-space in pharmaceutical-grade L-theanine and theobromine co-extraction for nutraceutical contract manufacturing partnerships. For Investors and Strategic Acquirers: Functional beverage houses seeking clean-label caffeine alternatives represent the most active acquirer in this space. Long-term viability hinges on cultivated acreage diversification reducing wild-harvest concentration risk. Acquisition target archetype: vertically integrated extract specialists with supercritical CO2 capacity and Ecuadorian cooperative relationships. Signal to monitor: EFSA consultation completion timelines for additional guayusa formats as inflection indicator for European market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Pathway Completion | Unlocks formulation access for European beverage manufacturers previously blocked by regulatory uncertainty. |
| Supercritical CO2 Extraction Scale-Up | Captures pharmaceutical-grade margin pools through standardized alkaloid production for nutraceutical applications. |
| Direct-Trade Cooperative Partnerships | Secures raw material access with Nagoya Protocol compliance documentation for premium channel positioning. |
| PMDA Consultation Preparation | Establishes first-mover positioning in Japanese functional beverage market ahead of regulatory clarity. |
| E-Commerce Subscription Launch | Bypasses traditional tea importer markups through single-origin storytelling in Pacific Coast urban markets. |
Methodological Framework
Coverage spans Ecuador, the United States, Germany, France, and Japan, with primary inputs from each market cluster. Primary interviews combined beverage formulation executives at functional drink manufacturers, regulatory affairs specialists navigating EFSA and FDA pathways, indigenous cooperative export managers in Napo province, specialty tea buyers at German and French distributors, and pharmaceutical contract manufacturing procurement leads. Secondary validation drew from FDA GRAS notification filings, EFSA novel food consultation registers, Ecuadorian biosafety authority export licensing records, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type and end-user segments.
Rate-of-change decomposition anchored projections across the analysis window through segmented CAGRs derived from pricing elasticity modeling and regulatory pathway timeline assumptions. Forecast framework modeled product type segmentation (extract, loose leaf, tea bags, powder), end-user tiers (beverage manufacturers, health enthusiasts, retail consumers, food services), distribution channels (online retail, specialty stores, health food shops, supermarkets), and application categories (beverages, health supplements, functional foods, natural remedies). Industry-specific inputs included wild-harvest yield variability coefficients and EFSA consultation completion probability weightings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ecuadorian climate patterns affecting wild-harvest volumes and PMDA regulatory clarity timing in Japan. Deviation in EFSA consultation approval timelines or Nagoya Protocol enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market