
 Prunus Africana Market | 2026-2036
Prunus Africana Market Size, Share, and Industry Trends Forecast 2026-2036
Prunus Africana Market Analytics
The nutraceutical sector is recalibrating its raw material priorities as prostate health supplements gain shelf space in North American and European retail channels. Nature's Way Products leverages direct-to-consumer distribution to sustain brand visibility in this category. Indena S.p.A. anchors European supply through its phytochemical extraction infrastructure. Sabinsa Corporation differentiates via its vertically controlled supply relationships with African collectors.
Prunus africana denotes the bark of an evergreen tree native to montane forests of sub-Saharan Africa, containing phytosterols and pentacyclic triterpenes including beta-sitosterol that manufacturers standardize to specific marker compound concentrations for therapeutic applications. The extract segment dominates value capture due to pharmaceutical-grade purification requirements, while the capsule format registers the fastest trajectory as consumer compliance preferences shift toward unit-dose delivery. Powder forms occupy stable demand from herbal product manufacturers blending multi-ingredient formulations. Dietary supplements channel the largest volume, though pharmaceutical applications concentrate margin pools where prescribers influence reimbursement outcomes.
CITES enforcement through national management authorities in range states governs export quotas and sustainable harvesting certification, while the European Medicines Agency's herbal monograph framework establishes quality benchmarks for marketed extracts in EU member states. The U.S. FDA's dietary supplement current good manufacturing practice regulations compel identity testing and contaminant screening for imported botanical materials. Stakeholders must monitor CITES quota negotiations and emerging synthetic alternatives that could displace wild-harvested bark volumes.
Market Dynamics
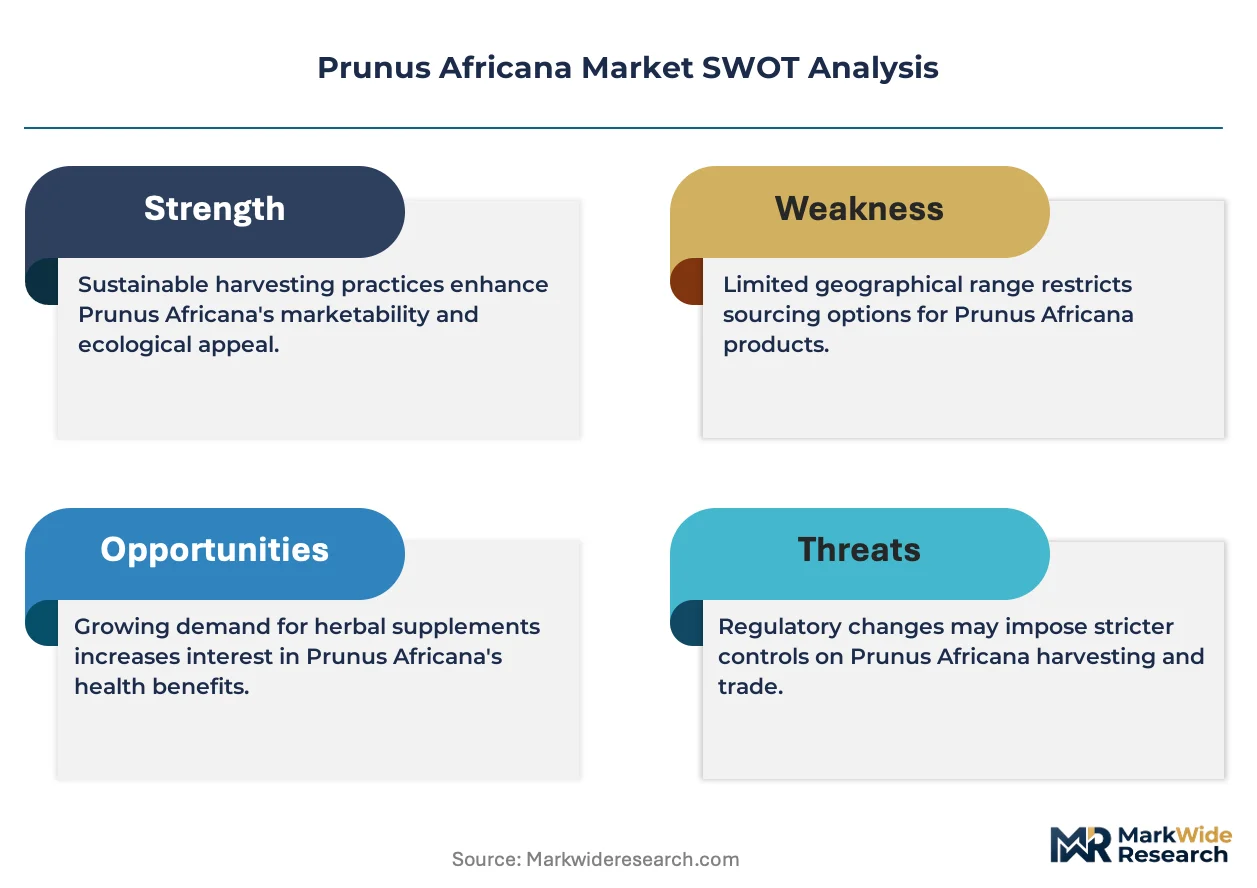
CITES Appendix II listing enforcement is compressing wild-harvested bark volumes while nutraceutical manufacturers scramble to secure certified sustainable supply chains before quota negotiations reset annual export ceilings.
Growth Catalysts
- EMA Herbal Monograph Framework:The European Medicines Agency's quality benchmarks for marketed extracts create regulatory clarity that accelerates pharmacy channel penetration across EU member states.
- Prostate Health Formulation Demand:North American retail channels are expanding shelf space for beta-sitosterol standardized supplements as male aging demographics drive repeat purchase behavior.
- Madagascar Wild Population Harvesting:Export-oriented supply chains in this range state benefit from established collector networks and national management authority quota allocations.
Market Restraints
- Wild Population Depletion Risk:Montane forest habitat fragmentation in Cameroon threatens long-term bark yield sustainability and collector livelihood security.
- Synthetic Beta-Sitosterol Substitution:Laboratory-derived phytosterol production from soy and pine sources offers price-competitive alternatives with simpler supply chain documentation.
- CITES Export Quota Volatility:Annual quota negotiations between range state management authorities and the CITES Secretariat create procurement planning uncertainty for extract manufacturers.
Strategic Opportunities
- Cultivation Program Expansion:Kenya and Tanzania present underdeveloped montane agroforestry potential for domesticated Prunus africana planting outside natural forest ecosystems.
- Unit-Dose Capsule Format Growth:Consumer compliance preferences in German and French pharmacy channels favor pre-measured delivery systems over bulk powder purchases.
- Dual Carbon Goals Alignment:China's SAMR sustainable sourcing incentives for botanical imports reward certified wild-harvest operations with expedited customs clearance protocols.
Industry Challenges
- Marker Compound Standardization:Batch-to-batch beta-sitosterol concentration variability in wild-harvested bark complicates pharmaceutical-grade purification and label claim compliance.
- Collector Certification Timeline:Range state sustainable harvesting training programs and chain-of-custody documentation requirements delay new supplier onboarding by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prunus Africana Market |
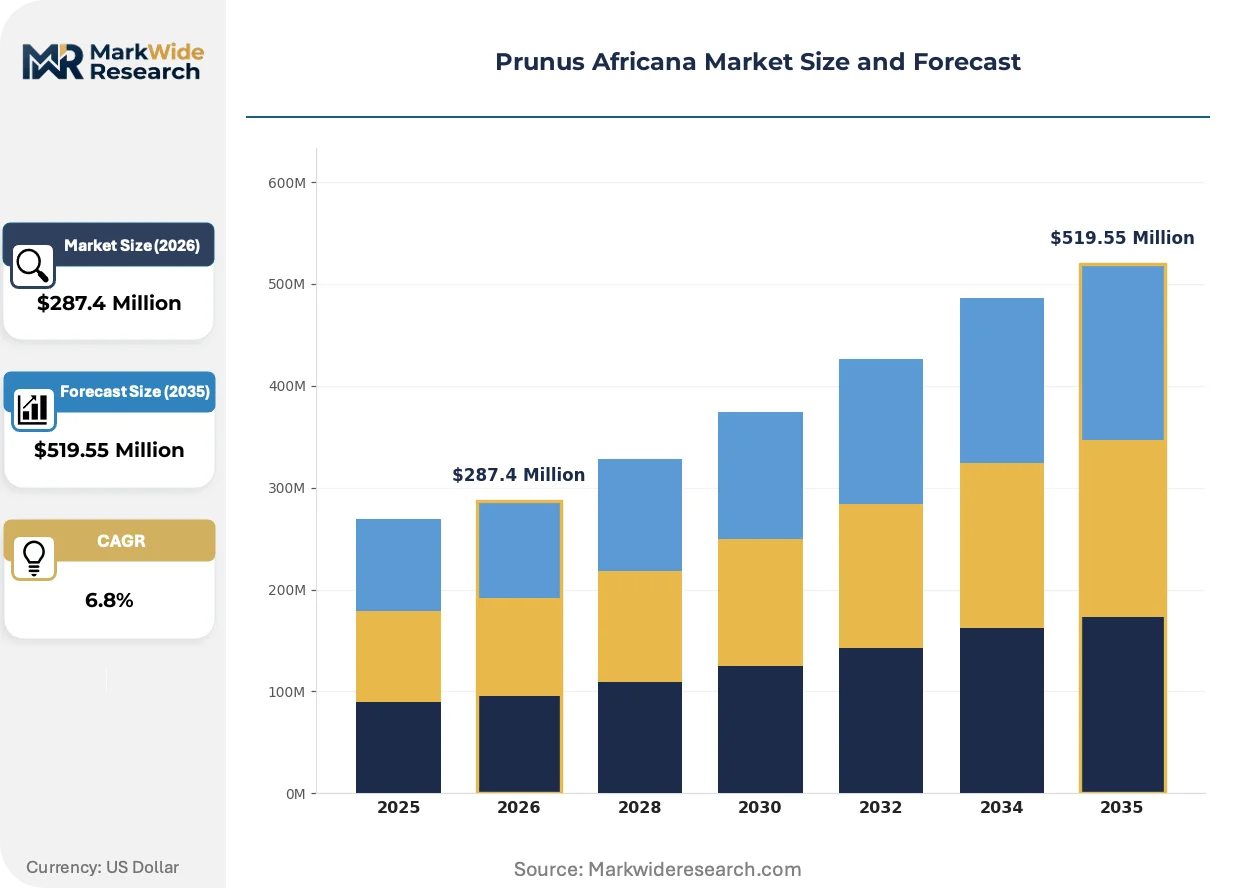
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $519.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract, Powder, Capsule, Tincture End User: Pharmaceutical Companies, Nutraceutical Firms, Research Institutions, Herbal Product Manufacturers Application: Antiinflammatory, Prostate Health, Herbal Remedies, Dietary Supplements Distribution Channel: Online Retail, Specialty Store, Direct Sales, Wholesale |
| Companies Covered | Nature’s Way Products, Sabinsa Corporation, Indena S.p.A., Parchem Fine & Specialty Chemicals, Groupe Fournier, Naturex, Euromed S.A., Nexira, Frutarom Health BU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prunus Africana Market Evolving Landscape
Pharmaceutical-grade extraction infrastructure is bifurcating between centralized European processing hubs and emerging African value-add facilities, while digital traceability platforms reshape how CITES compliance is demonstrated to customs authorities.
Supercritical CO2 extraction technology is modularizing downstream purification capacity for mid-scale nutraceutical manufacturers who previously relied on third-party toll processors in Italy and Germany. Indena S.p.A. and comparable European extract houses are deploying containerized extraction units closer to bark collection points in Cameroon and Madagascar. This distributed model compresses logistics costs and reduces degradation of heat-sensitive triterpene compounds during extended transport.
REACH registration requirements for imported botanical substances are tightening contaminant screening protocols for bark extracts entering EU cosmetic and pharmaceutical applications. The European Chemicals Agency's updated guidance on pesticide residue limits forces extractors to expand analytical testing capacity or risk border rejection. German and French importers are consolidating supplier bases to reduce audit burden, favoring vertically integrated African operations with in-house laboratories.
Direct-to-consumer subscription models are displacing traditional wholesale distributor relationships for prostate health supplements in US and Canadian markets. Nature's Way Products and comparable brands bypass pharmacy retail markups through automated replenishment programs. This channel compression concentrates margin capture with formulation owners while reducing working capital tied to inventory float through distributor warehouses.
Prunus Africana Market Segmentation
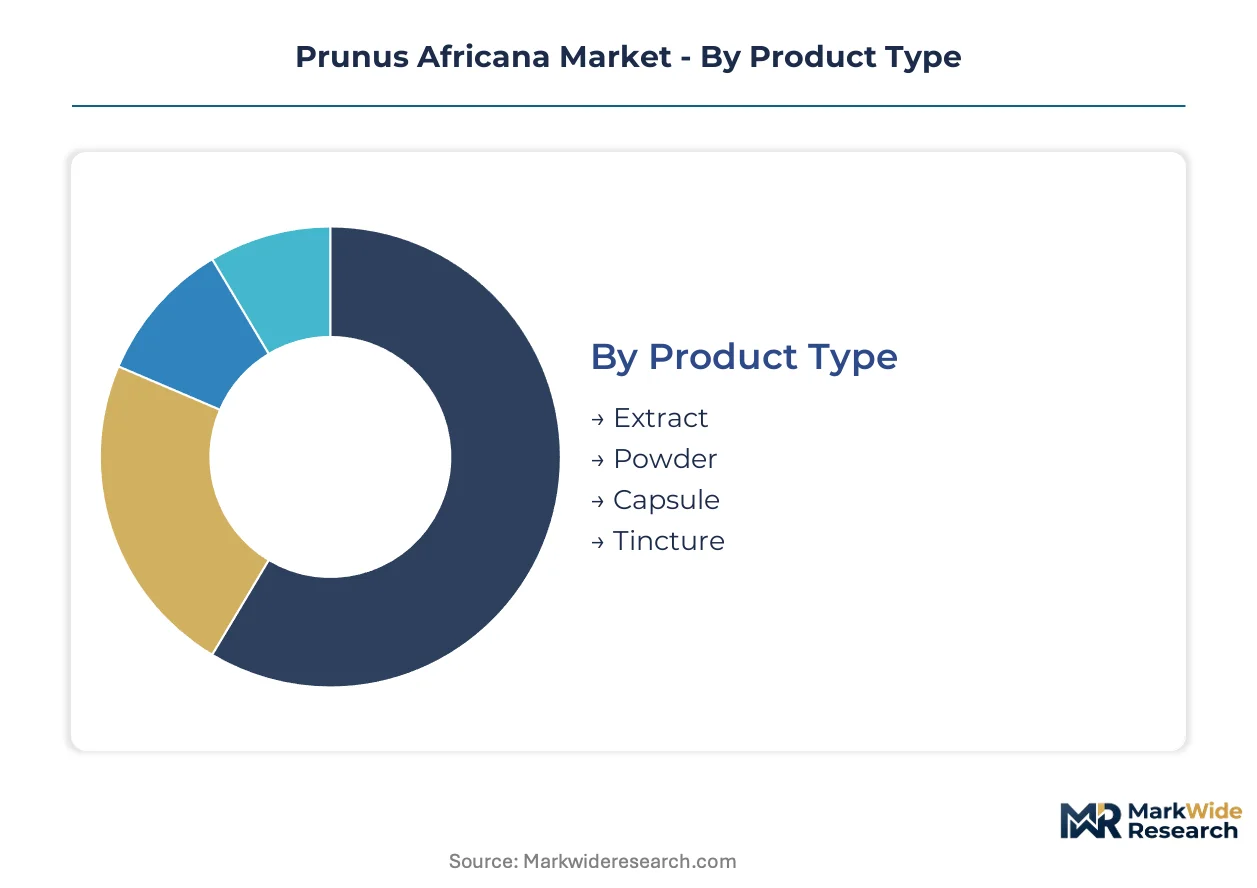
Prunus africana supply chains fragment across four distinct dimensions that reshape procurement economics. Product form determines purification investment and margin capture, while end-user concentration in nutraceutical channels concentrates volume purchasing power.
Product Type:
Buyers in this category differentiate by therapeutic grade requirements and formulation flexibility needs.
- Extract:Pharmaceutical-grade purification concentrates beta-sitosterol and pentacyclic triterpenes to standardized marker compound specifications. EMA herbal monograph compliance in Germany and France drives pharmacy channel procurement of certified extracts with chain-of-custody documentation.
- Capsule:Pre-measured unit-dose delivery systems align with consumer compliance preferences in North American direct-to-consumer channels. Automated replenishment programs from subscription-based brands accelerate format adoption over bulk alternatives.
- Powder:Multi-ingredient blenders in herbal product manufacturing favor bulk powder for formulation flexibility. Stable demand persists from traditional medicine compounders requiring non-standardized material inputs.
- Tincture:Ethanol-based preparations serve specialized herbalist channels with shorter shelf-life requirements. Limited commercial scale restricts volume penetration outside artisanal production networks.
Extract leads volumes today; capsule is gaining share fastest.
End User:
Procurement scale and regulatory sophistication separate institutional buyers from commercial blenders.
- Nutraceutical Firms:Direct-to-consumer brands dominate bark extract procurement for prostate health formulations with repeat purchase subscription models. CITES quota volatility compresses their supply security planning horizons to annual negotiation cycles.
- Pharmaceutical Companies:Prescription-grade applications require EMA-compliant extracts with validated analytical methods for reimbursement eligibility. German and French pharmacy channels concentrate margin pools where prescriber influence shapes procurement.
- Herbal Product Manufacturers:Traditional medicine compounders blend Prunus africana into multi-botanical preparations for non-standardized retail segments. Powder format preference reflects cost-driven formulation economics over therapeutic standardization.
- Research Institutions:Clinical trial material sourcing for mechanism-of-studies on benign prostatic hyperplasia drives small-batch extract procurement with full phytochemical characterization.
Nutraceutical firms lead volumes today; pharmaceutical companies are expanding procurement fastest.
Application:
Therapeutic positioning determines regulatory pathway and pricing tier access.
- Prostate Health:Beta-sitosterol standardized supplements target male aging demographics through pharmacy and direct-to-consumer channels. FDA dietary supplement regulations govern label claims while EMA herbal monographs enable pharmacy positioning in EU member states.
- Dietary Supplements:General wellness positioning avoids disease claim restrictions under US FDA and Health Canada frameworks. Volume concentration in North American retail channels drives procurement scale for extract manufacturers.
- Antiinflammatory:Traditional use applications in African and European herbal medicine markets persist outside standardized therapeutic frameworks. Limited clinical validation restricts pharmacy channel penetration.
- Herbal Remedies:Traditional medicine systems in range states consume bark through informal collector networks with minimal export orientation. Local consumption patterns differ from international commercial specifications.
Dietary supplements lead volumes today; prostate health is climbing the fastest.
Distribution Channel:
Channel selection determines margin retention and customer relationship control.
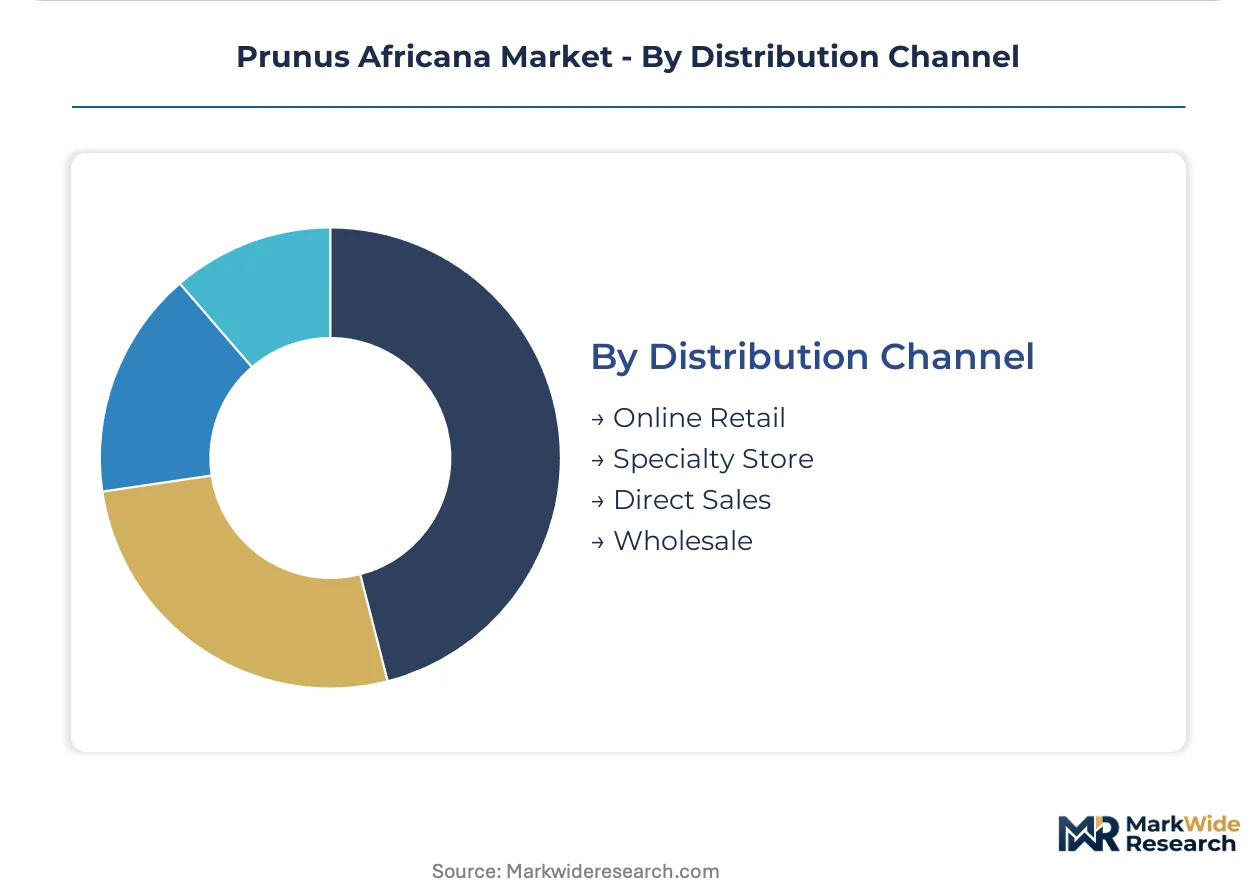
- Online Retail:Direct-to-consumer subscription models bypass wholesale markups and concentrate customer data ownership with formulation brands. Automated replenishment programs in US and Canadian markets reduce working capital tied to distributor inventory float.
- Wholesale:Traditional pharmacy and health food store distribution in European markets requires EMA-compliant documentation and batch certification. German and French importers consolidate supplier bases to reduce audit burden from REACH registration requirements.
- Specialty Store:Herbalist and natural product retailers serve consumers seeking practitioner guidance on traditional preparation methods. Limited scale restricts volume concentration relative to mass retail channels.
- Direct Sales:Collector-to-manufacturer relationships in Cameroon and Madagascar bypass intermediary margins for vertically integrated extractors. CITES chain-of-custody documentation requirements favor established direct procurement networks.
Wholesale leads volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cameroon anchors Prunus africana supply chains through its montane forest collector networks and CITES-managed export quotas. Range states across sub-Saharan Africa face divergent regulatory pressures and infrastructure constraints that reshape regional competitive positioning.
Cameroon
Wild bark harvesting in the Bamenda Highlands and Mount Cameroon regions supplies extract manufacturers in Italy and Germany. The country's Ministry of Forestry and Wildlife administers CITES export permits under annual quota negotiations with the Secretariat. Yaoundé-based collector cooperatives are consolidating chain-of-custody documentation to meet EMA herbal monograph requirements for EU-bound shipments.
Madagascar
Export-oriented supply chains in the central highlands benefit from established collector networks and national management authority quota allocations. The Madagascar National Parks authority governs sustainable harvesting protocols in protected montane forest zones. Antananarivo processing facilities are expanding bark drying capacity to reduce pre-export degradation of heat-sensitive triterpene compounds.
Kenya
Montane agroforestry initiatives in the Aberdare Range and Mount Kenya foothills present underdeveloped cultivation potential outside natural forest ecosystems. The Kenya Forest Service regulates wild harvesting permits while agricultural extension services pilot domesticated planting programs. Nairobi-based exporters are developing CITES-compliant documentation systems to access German and French pharmacy channels.
Italy
Pharmaceutical-grade extraction infrastructure in Milan and Bologna concentrates European downstream purification capacity for bark-derived beta-sitosterol. The Italian Medicines Agency enforces EMA herbal monograph quality benchmarks for extracts entering pharmacy distribution. Milan-headquartered extract houses are deploying containerized processing units closer to African collection points to compress logistics costs.
Germany
Pharmacy channel penetration in Bavaria and North Rhine-Westphalia drives EMA-compliant extract procurement for prostate health formulations. The Federal Institute for Drugs and Medical Devices oversees REACH registration requirements for imported botanical substances. Frankfurt and Hamburg importers are consolidating supplier bases to reduce audit burden from updated pesticide residue screening protocols.
Prunus Africana Market Competitive Landscape
Strategic partnerships dominate the current landscape as extract manufacturers secure CITES-compliant supply chains ahead of quota renegotiations. The vendor base fragments across European purification specialists, North American direct-to-consumer brands, and African collector networks. Three archetypes define competitive positioning: vertically integrated extract houses with African sourcing operations, subscription-based nutraceutical brands bypassing wholesale channels, and toll processors offering modular supercritical CO2 capacity. Capacity expansion and backward integration into collector certification represent the dominant competitive moves.
Among European extraction specialists, Indena S.p.A. and Euromed S.A. exemplify the integrated archetype with documented African supply relationships. Nature's Way Products occupies a position within the direct-to-consumer tier, leveraging automated replenishment programs to concentrate margin capture. These three companies represent distinct strategic postures without implying specific market share or operational scale.
| Leading Market Players |
|---|
| Nature's Way Products |
| Sabinsa Corporation |
| Indena S.p.A. |
| Parchem Fine & Specialty Chemicals |
| Groupe Fournier |
| Naturex |
| Euromed S.A. |
| Nexira |
| Frutarom Health BU |
| Others |
Value Network & Pricing Analysis
EMA herbal monograph compliance requirements in Germany and France are forcing extract manufacturers to absorb certification and documentation costs that compress margins at the pharmacy channel entry tier. This procurement specification shift rewards collector cooperatives in Cameroon and Madagascar that pre-invest in chain-of-custody systems, while marginalizing uncertified suppliers through price exclusion.
Pricing Analysis
Input-cost pass-through from CITES quota volatility and collector certification timelines shapes contract structures across the value chain. Three-tier pricing structure across pharmaceutical-grade, dietary supplement-grade, and traditional medicine-grade levels separates EMA-compliant extracts from standard dietary supplement materials and unstandardized bulk powder. Pricing pressure stems from synthetic beta-sitosterol substitution from soy and pine sources in cost-sensitive nutraceutical formulations. Pharmaceutical companies exhibit lowest price sensitivity due to reimbursement eligibility requirements, while herbal product manufacturers face acute margin compression from raw material variability.
Supply Chain Analysis
Workforce availability constraints in Cameroon's Bamenda Highlands and Madagascar's central highlands limit collector network expansion despite quota allocations. Geographic supply concentration centers on Cameroon, Madagascar, and emerging cultivation zones in Kenya and Tanzania. Raw material dependencies include wild-harvested bark, ethanol for tincture processing, and supercritical CO2 for pharmaceutical-grade extraction. Single-source vulnerability runs through Madagascar's collector cooperative infrastructure. Distribution runs through Antananarivo and Yaoundé processing hubs to Milan and Bologna extraction facilities, with direct-to-consumer brands bypassing wholesale channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European pharmacy channel premiums and African sourcing cost bases, with CITES regulatory differentials creating entry barriers that protect certified operators.
For Market Incumbents: Deepen backward integration into collector certification programs in Cameroon and Madagascar to lock in quota allocations before renegotiation cycles. Secure containerized extraction unit deployment closer to collection points to compress logistics degradation of heat-sensitive triterpenes. Synthetic beta-sitosterol substitution from laboratory-derived sources threatens long-term pricing power for wild-harvested materials.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel entry in North American prostate health formulations, bypassing wholesale markups and distributor inventory float. Target underdeveloped cultivation programs in Kenya and Tanzania for domesticated planting outside natural forest ecosystems. Partner with established collector cooperatives for expedited CITES documentation rather than building certification infrastructure from origin.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated extract houses with documented African supply relationships and EMA-compliant laboratory infrastructure. Long-term viability hinges on cultivation program maturation and synthetic substitution timelines. Watch CITES quota negotiation outcomes as the primary inflection indicator for supply security premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Collector Certification Investment | Secures CITES export quota allocations through Yaoundé and Antananarivo management authorities. |
| Containerized Extraction Deployment | Compresses triterpene degradation risks during extended transport from Bamenda Highlands. |
| Cultivation Program Development | Reduces wild population depletion exposure in Kenya's Aberdare Range agroforestry zones. |
| Direct-to-Consumer Channel Launch | Bypasses wholesale markups and concentrates customer data ownership with formulation brands. |
| Synthetic Substitution Monitoring | Tracks laboratory-derived beta-sitosterol cost curves from soy and pine feedstocks. |
Research Methodology
Direct dialogue with CITES management authority officials, collector cooperative leaders, extract manufacturer procurement directors, and EMA regulatory affairs specialists anchored qualitative findings. Secondary validation drew from CITES trade database records, EMA herbal monograph documentation, EU REACH registration filings, and national export permit registries in Cameroon and Madagascar. Bottom-up volume estimates from collector network capacity and top-down demand calibration from nutraceutical procurement patterns were triangulated for convergence.
Bottom-up modeling tracked bark harvest volumes by range state against extraction yield rates and standardized marker compound specifications. Segmentation dimensions included product form, end-user concentration, therapeutic application, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and supply-constrained quota trajectories. Industry-specific forecast inputs incorporated CITES annual negotiation cycles and EMA herbal monograph revision timelines.
Revisions become necessary when CITES quota renegotiations produce material allocation shifts, synthetic beta-sitosterol production achieves cost parity with wild-harvested sources, or EMA contaminant screening protocols tighten beyond current analytical capacity. Forecasts reflect documented assumptions about collector network stability and cultivation program maturation rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Sorghum by-Products Market