
 Sugar Cane Market | 2026-2036
Sugar Cane Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Cane Market Intelligence
A capital-intensity divergence between integrated plantation-to-mill operators and standalone processors is reorganizing competitive dynamics in sugar cane. Raízen leverages its biomass cogeneration assets to sustain energy cost advantages across Brazilian operations. Louis Dreyfus Company B.V. anchors its position through origination networks that span multiple cane-growing basins. Südzucker AG competes via beet-cane diversification that buffers against single-crop price swings.
Sugar cane is a perennial C4 grass, Saccharum officinarum, containing sucrose concentrations of 12-15% by weight in harvested stalks, processed through crushing, juice extraction, and crystallization to yield raw and refined sugar for industrial and consumer use. The product type dimension shows sugar commanding the largest revenue pool while ethanol is displacing molasses as the fastest-growing output stream from cane crush. End use segmentation reveals food and beverage maintaining volume dominance even as biofuel offtake tightens linkage between cane pricing and energy markets.
The EPA's Renewable Fuel Standard and Brazil's RenovaBio program shape ethanol demand pull from cane processors, while India's FSSAI and BIS enforce refined sugar purity benchmarks that filter export eligibility. ISO 22000 and HACCP protocols govern food-grade sugar access into regulated import markets. Stakeholders must track how carbon intensity scoring in fuel regulations revalues bagasse-powered mills against fossil-dependent competitors.
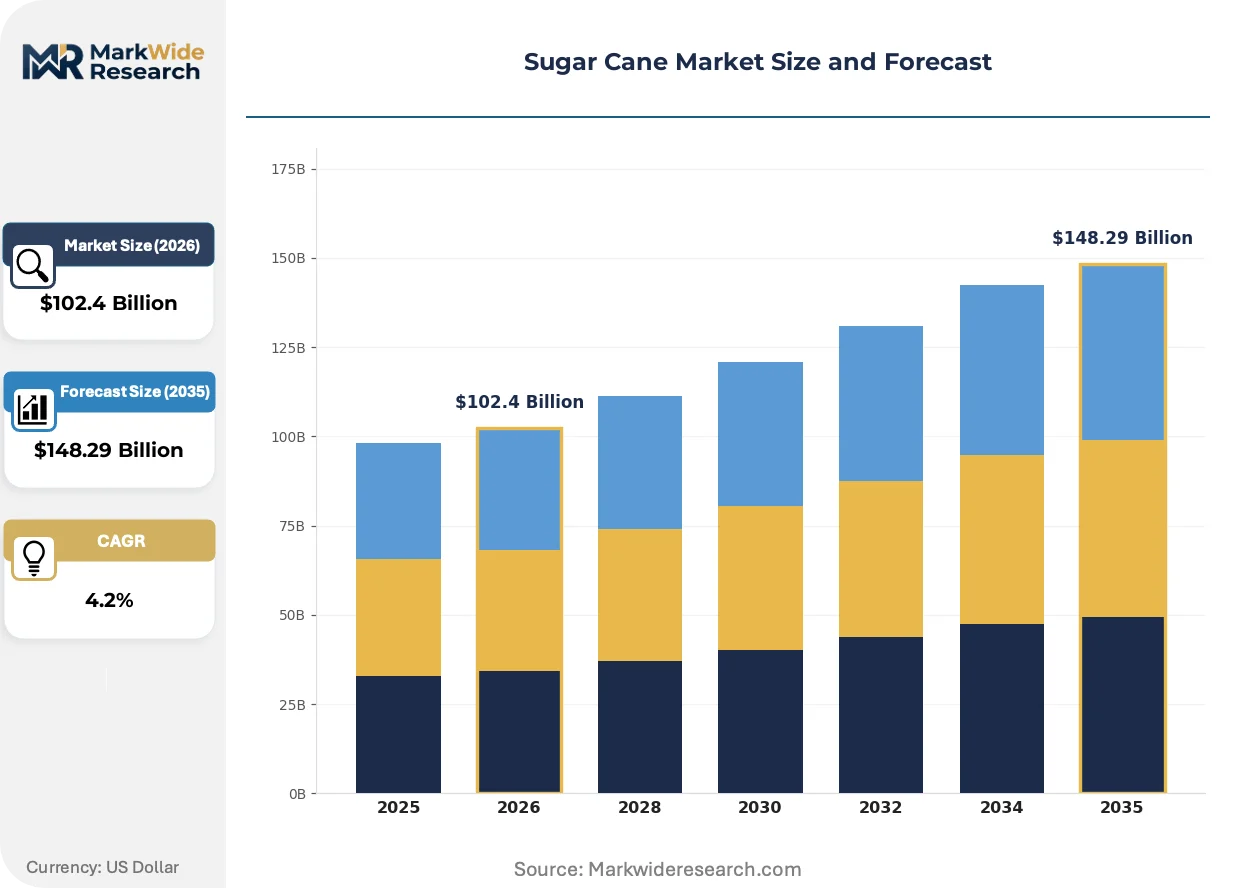
Market Dynamics
The sugar cane sector is undergoing a structural reorganization as energy market linkage revalues crush economics, with biofuel mandates and carbon intensity scoring now determining which mills capture margin and which face stranded asset risk.
Growth Catalysts
- RenovaBio carbon credit mechanism:Brazil's biofuel certification program rewards low-carbon ethanol output from bagasse-powered facilities, redirecting capital toward cogeneration retrofits.
- Bagasse-to-power integration:Cogeneration systems burning residual fiber now supply grid electricity during harvest windows, diversifying revenue beyond sugar and ethanol sales.
- India:FSSAI enforcement of refined sugar purity benchmarks is filtering export eligibility and consolidating processing capacity toward compliant mills.
Market Restraints
- Input cost volatility:Fertilizer price swings tied to natural gas markets squeeze plantation margins, particularly for smallholder-dependent supply bases in Southeast Asia.
- Supply concentration risk:Crush capacity clusters in Brazil's Center-South region expose buyers to single-basin weather disruption and port logistics bottlenecks.
- Substitution threat:Corn-based ethanol expansion in the US Midwest competes for biofuel blending mandates, capping cane ethanol premium capture in Atlantic markets.
Strategic Opportunities
- Thailand:Underutilized crushing capacity in the Northeast region offers origination expansion as EU renewable energy directive compliance tightens import standards.
- Cellulosic ethanol convergence:Second-generation fermentation technology unlocking bagasse and straw residues is opening feedstock pools beyond sucrose extraction.
- Carbon border adjustment mechanism:EU CBAM phase-in creates compliance service demand for lifecycle emissions verification across cane supply chains.
Industry Challenges
- Agronomy skill scarcity:Precision agriculture deployment for yield optimization requires data science capabilities that legacy plantation management structures lack.
- ISO 22000 certification timelines:Food-grade sugar access into regulated import markets demands 12-18 month compliance windows that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Cane Market |
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $148.29 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar, Molasses, Bagasse, Ethanol End Use: Food & Beverage, Biofuel, Pharmaceuticals, Animal Feed Processing Technique: Crystallization, Fermentation, Filtration, Distillation Distribution Channel: Wholesale, Retail, Direct Sales, E-commerce |
| Companies Covered | Florida Crystals Corporation, Raízen, Louis Dreyfus Company B.V., Südzucker AG, Tereos, Wilmar International Limited, Biosev SA, Mitr Phol Group, Cosan S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Cane Market Strategic Shifts & Innovations
Digital plantation management and precision harvest scheduling are compressing the gap between field operations and mill optimization, while regulatory carbon accounting is embedding emissions measurement into procurement contracts.
Mechanical harvesting automation with real-time cane quality sensors is fragmenting the traditional supply relationship between growers and mills. Large plantation operators in São Paulo state are deploying near-infrared spectroscopy on harvesters to measure sucrose content at cutting, enabling dynamic routing to mills by payout tier. This capability is fragmenting long-term supply contracts into spot-price-indexed transactions based on verified quality at field edge.
The EPA's Renewable Fuel Standard updates are tightening lifecycle emissions thresholds for imported ethanol, compressing market access for mills without bagasse power or methane capture systems. Brazilian exporters must now submit certified carbon intensity scores to maintain blending credit eligibility in US markets. Facilities with fossil fuel-dependent process heat face margin compression against biomass-powered competitors.
Food and beverage manufacturers are embedding sustainability criteria into procurement specifications, displacing traditional commodity spot purchasing with multi-year offtake agreements tied to traceability and emissions disclosure. Nestlé and Unilever procurement teams in Europe now require chain-of-custody documentation from cane field to refinery. This shift is most visible in Germany and the Netherlands, where retail-facing brands face CSRD supply chain disclosure obligations.
Sugar Cane Market Segmentation
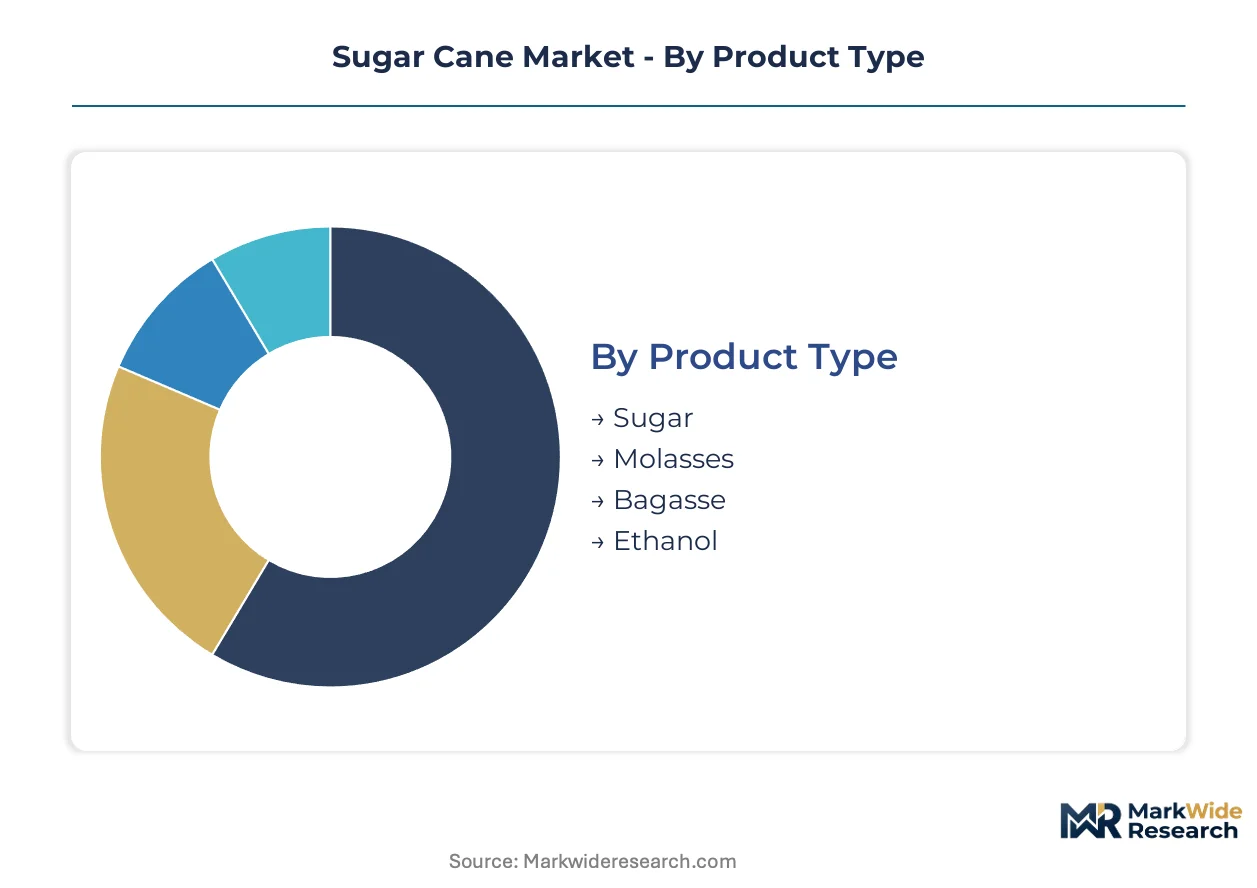
Sugar cane segmentation reveals how crush economics are splitting between traditional sweetener markets and energy-linked commodity streams. Product and end-use dimensions now determine which processors capture margin from biofuel mandates versus those stranded in oversupplied refined sugar channels.
Product Type:
Substitution pressure from corn-based ethanol and beet sugar is fragmenting revenue stability across cane-derived outputs, with energy-linked products facing the most volatile demand trajectories.
- Sugar:Crystalline sucrose extracted through juice clarification and evaporation yields raw and refined grades for industrial and consumer applications. Food manufacturers in India and Brazil anchor procurement volumes, though FSSAI and BIS purity benchmarks are filtering export eligibility toward compliant mills.
- Ethanol:Fermentation of sucrose and subsequent distillation produces hydrous and anhydrous fuel grades. Brazilian RenovaBio carbon credit mechanisms reward low-carbon output from bagasse-powered facilities, redirecting capital toward cogeneration retrofits in São Paulo state.
- Molasses:Viscous byproduct of sugar crystallization containing residual sucrose and minerals, historically routed to animal feed and alcohol production. Demand is softening as ethanol fermentation economics favor direct sucrose processing over molasses-based routes.
- Bagasse:Fibrous residue post-crushing, combusted in cogeneration boilers to generate process heat and grid electricity. Grid access tariffs in Thailand and Brazil determine project returns for power-exporting mills.
Sugar anchors the volume base while ethanol gains share at the steepest rate.
End Use:
Cost-tier differentiation separates commodity-scale biofuel offtake from premium-priced food-grade and pharmaceutical specifications.
- Food & Beverage:Refined sugar for confectionery, soft drinks, and processed foods represents the foundational demand pool. Nestlé and Unilever procurement teams in Germany and the Netherlands now require chain-of-custody documentation from cane field to refinery under CSRD supply chain disclosure obligations.
- Biofuel:Ethanol blending into gasoline mandates across Brazil, the US, and EU markets. EPA Renewable Fuel Standard updates tightening lifecycle emissions thresholds compress market access for mills without bagasse power or methane capture systems.
- Pharmaceuticals:High-purity sucrose for excipient and intravenous applications demanding USP and EP compliance. ISO 22000 and HACCP protocols govern food-grade sugar access into regulated import markets with 12-18 month certification timelines.
- Animal Feed:Molasses and pressed bagasse as ruminant feed supplements, competing with soy and corn byproducts. Price sensitivity limits margin expansion in this channel.
Food & Beverage maintains the largest revenue footprint while Biofuel demonstrates the most rapid demand acceleration.
Processing Technique:
Application-specific purity requirements dictate capital intensity and energy integration strategies across mill configurations.
- Crystallization:Evaporation and seeding processes producing raw and refined sugar crystals. Brazilian mills in the Center-South region optimize energy recovery through multi-effect evaporators tied to bagasse boilers.
- Fermentation:Yeast-mediated conversion of sucrose to ethanol, with cellulosic variants unlocking bagasse and straw residues. Second-generation technology is opening feedstock pools beyond sucrose extraction in Thai and Brazilian pilot facilities.
- Filtration:Juice clarification using carbonatation or phosphatation methods to remove impurities. Process selection determines final sugar color and pharmaceutical eligibility.
- Distillation:Separation of ethanol from fermentation broth to reach fuel-grade purity. Energy integration with bagasse cogeneration lowers carbon intensity scores for export markets.
Crystallization commands the installed capacity base while Fermentation attracts the steepest capital deployment trajectory.
Distribution Channel:
Customer-type concentration separates bulk commodity flows from specification-driven direct relationships.
- Wholesale:Bulk sugar and ethanol sales to refiners, blenders, and industrial processors. Louis Dreyfus Company B.V. and comparable traders anchor origination networks spanning multiple cane-growing basins.
- Direct Sales:Long-term offtake agreements between mills and end-users with traceability requirements. Food and beverage manufacturers are embedding sustainability criteria into procurement specifications, displacing traditional commodity spot purchasing.
- Retail:Packaged sugar for consumer markets through supermarket and convenience store channels. Brand differentiation remains limited in this commoditized segment.
- E-commerce:Emerging channel for specialty and organic cane products targeting direct-to-consumer segments. Volume contribution remains marginal relative to industrial channels.
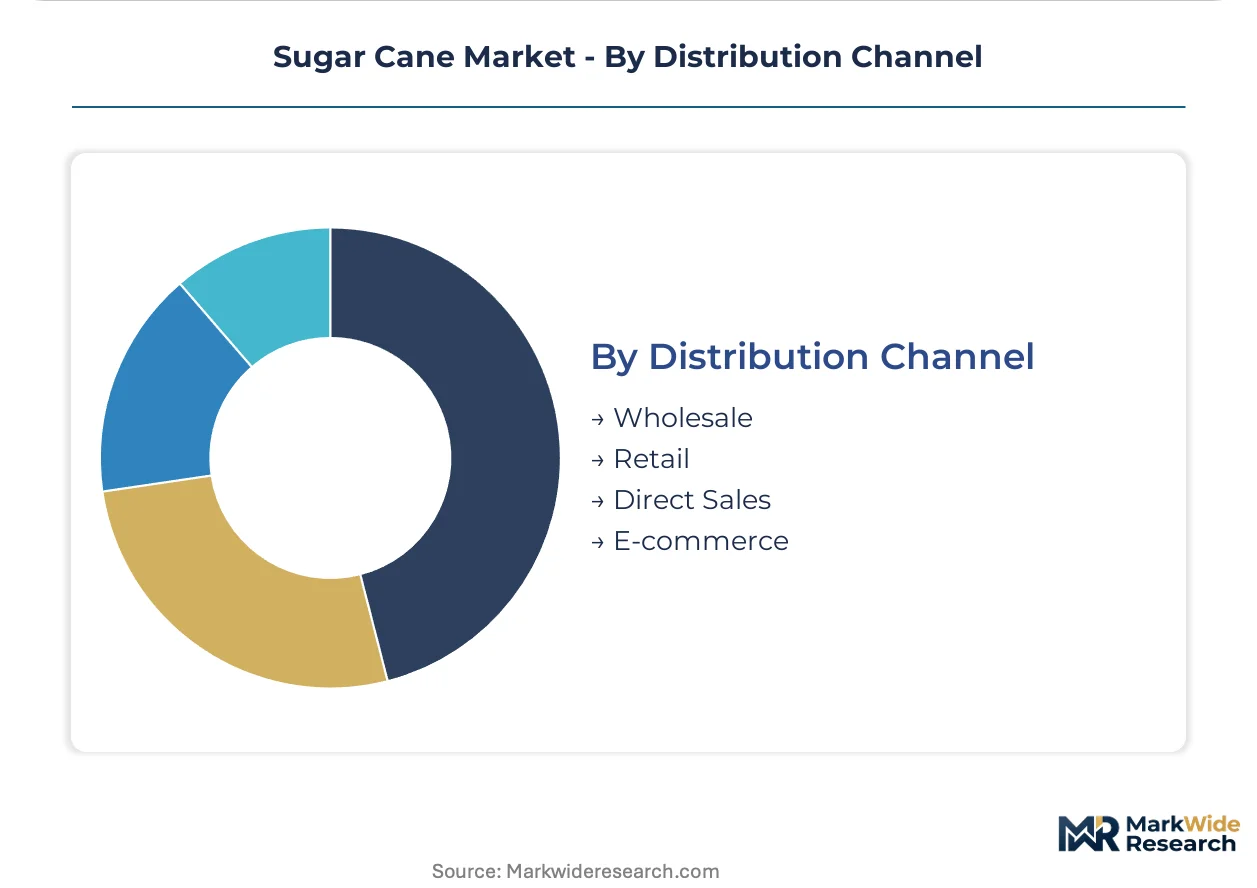
Wholesale handles the dominant volume flows while Direct Sales is expanding most quickly as procurement specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage through RenovaBio carbon credits while Indian mills absorb cost pressure from BIS compliance mandates. Crush capacity clusters in São Paulo state and Maharashtra define supply-side gravity for biofuel and refined sugar channels respectively.
Brazil
RenovaBio certification drives ethanol premiums toward bagasse-powered mills in São Paulo's Center-South cluster. ANVISA and the national biofuel regulator enforce carbon intensity scoring that filters export eligibility. Raízen and Cosan operations in Ribeirão Preto anchor the world's densest cane processing corridor.
India
FSSAI sugar purity benchmarks and BIS processing standards consolidate export capacity toward compliant mills in Maharashtra and Uttar Pradesh. The central regulator mandates refined sugar specifications that strain smallholder-dependent supply bases. Milling clusters in Kolhapur and Muzaffarnagar dominate volume throughput for food-grade export channels.
Thailand
Underutilized crush capacity in the Northeast region attracts EU renewable energy directive compliance demand. The national agricultural ministry oversees grid access tariffs for bagasse-to-power exports that determine mill project returns. Mitr Phol Group facilities in Khon Kaen province exemplify origination expansion toward carbon-verified supply chains.
United States
EPA Renewable Fuel Standard updates tighten lifecycle emissions thresholds for imported ethanol from Brazilian suppliers. Corn-based ethanol expansion in the Midwest competes for blending mandates that cap cane ethanol premium capture. Gulf Coast refiners in Texas and Louisiana dominate Atlantic basin offtake for hydrous fuel grades.
China
Dual carbon goals and provincial emissions targets redirect state-owned processor investment toward bagasse cogeneration retrofits. MIIT and national standardization authorities govern industrial sugar purity benchmarks for pharmaceutical and food manufacturing. Guangxi Zhuang Autonomous Region mills near Nanning concentrate domestic crush capacity for southern industrial demand.
Sugar Cane Market Key Industry Players
Concentration sits with integrated plantation-to-mill operators who control origination through captive cane supply. The vendor base splits between Brazilian energy-integrated processors, European beet-cane diversified refiners, and Southeast Asian origination specialists. Three archetypes dominate: biomass-cogeneration operators, multi-basin trading houses, and plantation-scale millers. Competitive moves center on cogeneration retrofit capital deployment and sustainability certification acquisition for EU and US biofuel market access.
Among the integrated processor tier, Raízen exemplifies the biomass-cogeneration archetype through its São Paulo state energy asset base. Louis Dreyfus Company B.V. occupies the multi-basin trading position with origination networks spanning Brazilian and Southeast Asian supply corridors. Südzucker AG represents beet-cane diversification strategy that buffers margin volatility across crop cycles.
| Leading Market Players |
|---|
| Florida Crystals Corporation |
| Raízen |
| Louis Dreyfus Company B.V. |
| Südzucker AG |
| Tereos |
| Wilmar International Limited |
| Biosev SA |
| Mitr Phol Group |
| Cosan S.A. |
| Others |
Cost & Logistics Intelligence
Corn-based ethanol displacement in US biofuel blending is simultaneously fragmenting cane ethanol's Atlantic basin premium geography and compressing crush economics for mills without bagasse power integration. This substitution dynamic redirects pricing power toward Brazilian RenovaBio-certified facilities while stranding fossil-dependent processors in commodity sugar channels.
Pricing Analysis
The customization-premium spread in sugar cane separates bagasse-cogeneration ethanol commanding RenovaBio carbon credits from standard molasses-route output facing commodity pricing. Contract-based long-term offtake dominates biofuel channels while spot-indexed transactions govern food-grade sugar. Price differentiation hinges on ISO 22000 certification tier and carbon intensity scoring for EU and US market access. Margins are tightening for mills without methane capture systems due to EPA lifecycle emissions thresholds. Smallholder-dependent processors in Southeast Asia exhibit highest price sensitivity; integrated plantation-to-mill operators in São Paulo state show least.
Supply Chain Analysis
Just-in-time harvest scheduling with real-time sucrose sensors is displacing strategic stockpile preferences among large plantation operators in São Paulo state. Geographic supply concentration centers on Brazil, India, and Thailand, with crush capacity clustering in Center-South Brazil and Maharashtra state. Raw material dependencies include fertilizer inputs tied to natural gas markets, agricultural labor availability, and irrigation water access. Single-basin weather disruption poses structural supply chain risk for buyers dependent on Center-South Brazil. Distribution runs through Louis Dreyfus Company B.V. and comparable multi-basin trading houses anchoring origination networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sugar cane markets reward defensive moats built on regulatory entrenchment, where RenovaBio certification and EPA compliance create switching costs that lock in biofuel offtake relationships.
For Market Incumbents: Fortify bagasse cogeneration assets to sustain carbon intensity advantages against corn-based ethanol substitution pressure. Expand capacity in Thailand's Northeast region to capture EU renewable energy directive compliance demand. Prioritize ISO 22000 certification investment to secure Nestlé and Unilever procurement specifications requiring chain-of-custody documentation. For New Entrants and Emerging Players: Differentiate on cellulosic ethanol technology unlocking bagasse and straw residues beyond sucrose extraction. Target underutilized crush capacity in Thailand's Northeast region as the most penetrable geography. Pursue direct sales channel entry with sustainability-verified offtake agreements displacing commodity spot purchasing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed plantation-scale millers lacking cogeneration retrofit capital. Long-term viability favors biomass-integrated operators with captive cane supply and regulatory certification moats. Watch RenovaBio carbon credit pricing as the inflection indicator for ethanol margin expansion versus sugar-channel stranding.| Strategic Initiative | Industry Significance |
|---|---|
| Bagasse Cogeneration Retrofit | RenovaBio certification unlocks carbon credit premiums for São Paulo state mills. |
| ISO 22000 Certification Investment | FSSAI and BIS compliance filters export eligibility toward certified processors. |
| Cellulosic Ethanol Technology Deployment | Second-generation fermentation opens feedstock pools beyond sucrose extraction. |
| Direct Sales Channel Expansion | CSRD disclosure obligations in Germany and Netherlands favor traceability-verified offtake. |
| Northeast Thailand Capacity Utilization | EU renewable energy directive compliance tightens import standards for carbon-verified supply. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, FSSAI purity benchmark documentation, and RenovaBio program disclosures. Primary interviews engaged biofuel procurement officers at European refiners, plantation operations managers in São Paulo state, and sustainability compliance leads at food manufacturers. Secondary validation drew from EPA Renewable Fuel Standard updates, EU renewable energy directive texts, and customs trade data for ethanol and sugar flows. Bottom-up crush capacity modeling triangulated against top-down consumption estimates across the analysis window.
Segmentation dimensions modeled include product type, end use, processing technique, and distribution channel across regional production clusters. Crystallization and fermentation capacity forecasts reflect capital deployment trajectories and regulatory carbon intensity scoring evolution. CAGRs derive from volume-throughput projections tied to biofuel mandate expansion and food-grade export eligibility filtering. Industry-specific inputs incorporate bagasse-to-power grid access tariffs and precision agriculture adoption rates for yield optimization.
The analysis sits within stated boundaries; outcomes outside sustained RenovaBio carbon credit pricing and EPA emissions threshold enforcement would require recalibration. Forecasts reflect assumptions regarding fertilizer cost stabilization and EU CBAM phase-in timing for lifecycle emissions verification. Revision becomes warranted when corn-based ethanol blending economics cross thresholds that displace cane ethanol Atlantic basin market share.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
United States Floriculture Market