
 Cambodia Agriculture Market | 2026-2036
Cambodia Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Agriculture Market Insights
Post-harvest processing and branded rice exports is rewriting margin distribution across the Cambodian agricultural value chain. Kubota Corporation leverages its mechanized equipment footprint to anchor premium positioning among commercial farming cooperatives. Deere & Company competes through precision agriculture technology adapted for Southeast Asian paddy conditions. Amru Rice Co., Ltd. dominates Cambodia's fragrant rice export segment with vertically integrated milling and packaging operations.
Cambodia agriculture encompasses crop cultivation, livestock management, aquaculture, and forestry activities across tropical lowland and upland ecosystems, with rice paddies covering approximately three-quarters of cultivated land area and requiring specific water management infrastructure for controlled flooding cycles. The sector serves domestic food security, regional commodity trade, and emerging biofuel feedstock supply. Rice commands the largest product type volume pool, though fruits and vegetables are capturing faster value growth from urban retail channel expansion. Mechanized harvest methods are displacing traditional labor-intensive practices as labor costs rise, while sustainable and organic certification segments attract premium pricing from export buyers in neighboring Asian markets.
Cambodia's Ministry of Agriculture, Forestry and Fisheries sets national crop standards and export phytosanitary requirements that determine market access for rice and processed agricultural goods. The country's national agricultural regulator enforces pesticide residue limits aligned with ASEAN harmonized standards to maintain trade eligibility with Thailand and Vietnam. Stakeholders must monitor irrigation infrastructure completion timelines and regional trade agreement negotiations that will determine competitive positioning against established Mekong Delta suppliers.
Market Dynamics
Post-harvest mechanization and irrigation infrastructure expansion are compressing traditional cultivation cycles across Cambodia's rice-dominated agricultural economy. Commercial farming cooperatives in Battambang and Pursat provinces are absorbing precision planting equipment at accelerating rates.
Growth Catalysts
- ASEAN Phytosanitary Harmonization:Aligned pesticide residue standards with Thailand and Vietnam are unlocking cross-border rice trade corridors for Cambodian millers.
- Commercial Farming Cooperatives:Consolidated land management units in Kampong Thom and Siem Reap are deploying mechanized harvest fleets to replace seasonal labor pools.
- Mekong River Irrigation Upgrades:National water management infrastructure investments are extending controlled flooding capacity into previously rain-fed upland districts.
Market Restraints
- Fertilizer Import Dependency:Cambodia sources the majority of nitrogen and phosphate inputs through Vietnamese and Thai intermediaries, exposing margins to regional price volatility.
- Fragmented Land Tenure:Smallholder plots averaging under two hectares limit economies of scale for mechanized equipment deployment outside cooperative structures.
- Storage Infrastructure Gap:Inadequate cold chain and silo capacity in Prey Veng and Takeo provinces forces accelerated post-harvest sales at suppressed spot prices.
Strategic Opportunities
- Organic Certification Segments:EU organic import quotas and premium pricing for chemical-free fragrant rice create margin expansion potential for Battambang exporters.
- Aquaculture Integration:Rice-fish farming systems in Tonle Sap floodplains offer dual-revenue streams with lower input intensity than monoculture paddies.
- Urban Retail Channel Expansion:Phnom Penh supermarket chains and e-grocery platforms are establishing direct procurement relationships with provincial farming associations.
Industry Challenges
- Equipment Maintenance Skill Shortage:Provincial technician training programs lag behind imported machinery complexity, extending downtime for precision planting and harvest systems.
- Phytosanitary Compliance Timelines:Cambodian Ministry of Agriculture export certification processes create shipment delays that conflict with just-in-time delivery contracts from Thai and Vietnamese buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Agriculture Market |
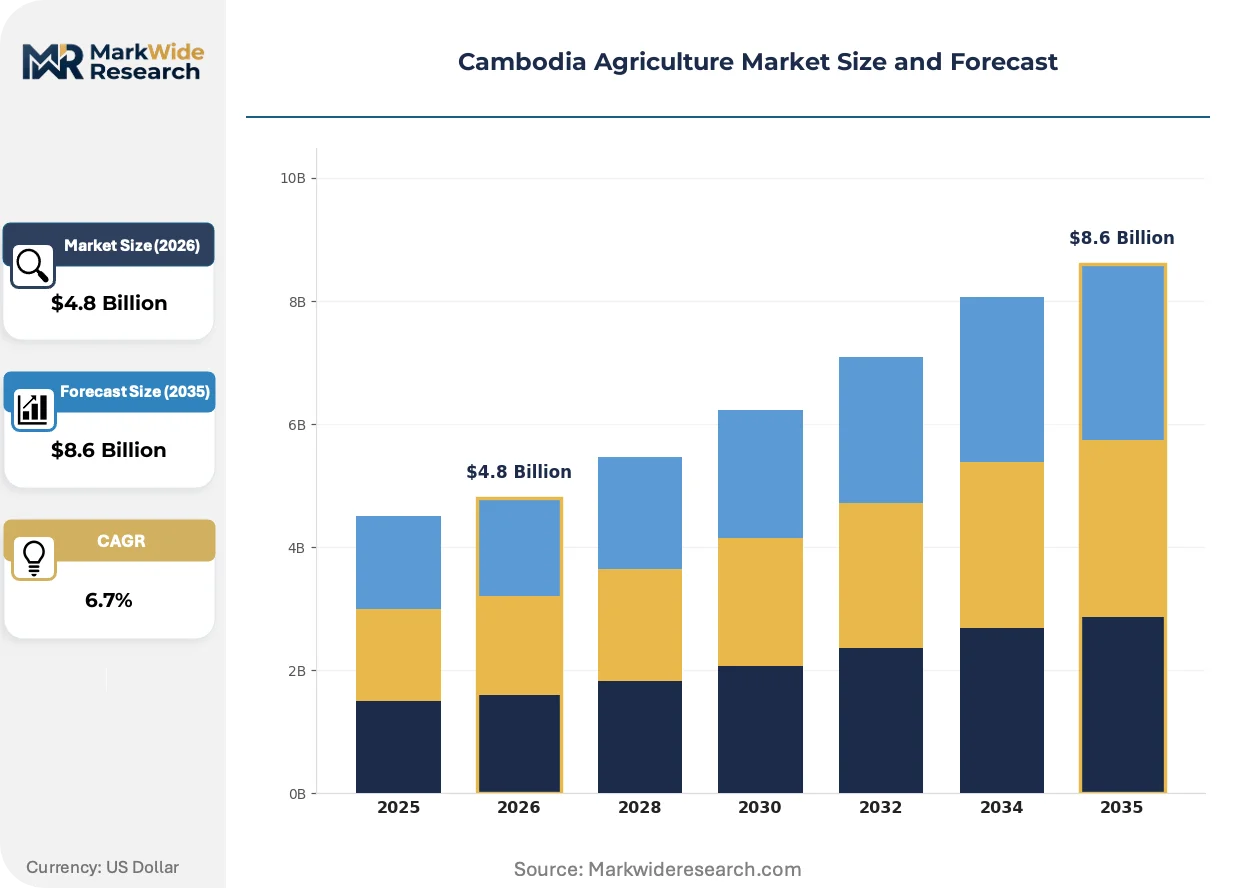
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice, Vegetables, Fruits, Pulses End Use Industry: Food Processing, Export, Local Consumption, Biofuel Distribution Channel: Wholesale, Retail, Direct Sales, Online Harvest Method: Traditional, Mechanized, Organic, Sustainable |
| Companies Covered | Kubota Corporation, Deere & Company, Mahindra & Mahindra Ltd, Yanmar Holdings Co., Ltd., Tractors and Farm Equipment Limited, New Holland Agriculture, AGCO Corporation, Escorts Limited, Amru Rice Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Agriculture Market Trends and Innovations
Digital soil mapping and variable-rate input application are compressing yield variance across Cambodia's heterogeneous paddy soils. These precision technologies are redistributing competitive advantage toward capitalized farming cooperatives with technical advisory partnerships.
Drone-based aerial seeding and pesticide application is rendering obsolete manual broadcast methods in Cambodia's commercial rice zones. Battambang province farming cooperatives are deploying unmanned aerial systems for flood-season crop establishment. This shift is compressing labor windows and reducing input waste in marginal soil conditions.
Cambodia's Ministry of Agriculture, Forestry and Fisheries enforcement of ASEAN-harmonized pesticide residue limits is tightening market access requirements for rice exports. Millers in Phnom Penh corridor provinces are investing in laboratory testing capacity to pre-certify shipments. The regulatory pressure falls most heavily on small independent processors lacking in-house quality assurance infrastructure.
Direct contracting between urban retail chains and provincial farming associations is displacing traditional auction-based wholesale channels for fresh produce. Phnom Penh supermarket operators are specifying varietal and harvest-timing requirements in advance purchase agreements. This procurement consolidation concentrates price-setting power with retail buyers while transferring crop planning risk to farming units.
Cambodia Agriculture Market Segmentation
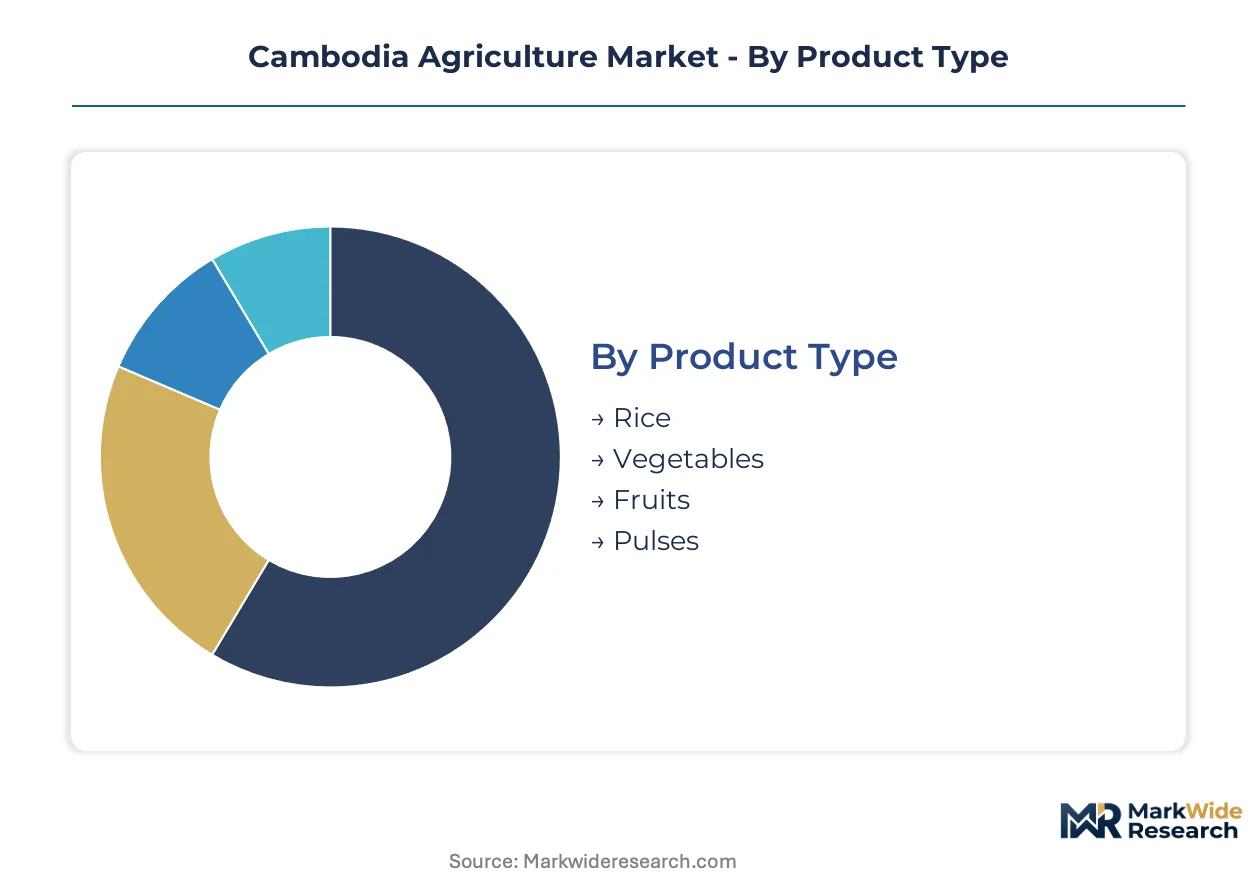
Segmentation reveals how Cambodian agricultural output splits across distinct commercial pathways, each with unique margin structures and infrastructure requirements. Rice paddies dominate land use but command divergent price points depending on harvest method and distribution channel. Understanding these splits exposes where capital deployment yields differential returns.
Product Type:
Mature staples anchor volume while emerging specialty crops capture expanding value pools across Cambodia's cultivation landscape.
- Rice:Fragrant jasmine and white long-grain varieties occupy roughly three-quarters of cultivated land area, with controlled flooding infrastructure determining yield consistency in Battambang and Pursat provinces. Mekong River corridor millers concentrate procurement around Phnom Penh for export-grade processing, though EU organic certification requirements are tightening quality thresholds for premium consignments.
- Vegetables:Leafy greens, gourds, and alliums supply urban retail channels with shorter cultivation cycles than cereal crops, enabling multiple harvests annually. Phnom Penh supermarket chains now contract directly with Siem Reap and Kampong Thom farming associations for specified varietals and harvest windows, compressing traditional wholesale auction margins.
- Fruits:Mango, longan, and durian orchards in Kampot and Battambang provinces serve regional export markets with growing cold chain investment.
- Pulses:Mung bean and soybean cultivation expands in rotation with rice paddies, fixing soil nitrogen for subsequent cereal cycles.
Rice retains volume leadership; vegetables hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity bulk sales from premium-branded channels with divergent input requirements.
- Food Processing:Rice milling operations in Phnom Penh and Battambang provinces absorb increasing value-added capacity, with fragrant rice exports commanding price premiums over commodity white rice. Amru Rice Co. and comparable integrated millers control branded packaging and phytosanitary certification for EU and ASEAN destination markets.
- Export:Cross-border trade to Thailand and Vietnam depends on ASEAN-harmonized pesticide residue standards enforced by Cambodia's Ministry of Agriculture, Forestry and Fisheries. Millers investing in laboratory testing capacity pre-certify shipments to avoid just-in-time delivery conflicts with regional buyers.
- Local Consumption:Domestic rice demand centers on lower-grade white rice through traditional wholesale channels in Phnom Penh and provincial capitals.
- Biofuel:Cassava and palm oil feedstock cultivation expands in northeastern provinces for regional biodiesel supply chains.
Local consumption retains volume leadership; export holds the steepest expansion curve.
Distribution Channel:
Customer type fragmentation distinguishes institutional procurement from household purchasing with opposing logistics requirements.
- Wholesale:Traditional auction-based channels in Phnom Penh's Dey Krahorm market and provincial assembly points still handle majority rice and vegetable volume, though spot price volatility disadvantages smallholders lacking storage infrastructure. Cooperative aggregation in Battambang and Takeo provinces is gradually consolidating bargaining position.
- Retail:Supermarket chains including Lucky and Aeon are establishing direct procurement relationships with farming associations, specifying harvest timing and varietal requirements that transfer crop planning risk to suppliers while concentrating price-setting power.
- Direct Sales:Contract farming arrangements between processors and cultivation units eliminate intermediary margins for large-volume transactions.
- Online:E-grocery platforms in Phnom Penh pilot last-mile delivery for fresh produce with limited penetration beyond capital region.
Wholesale retains volume leadership; retail holds the steepest expansion curve.
Harvest Method:
Supply concentration varies sharply between labor-intensive traditional systems and capital-intensive mechanized operations.
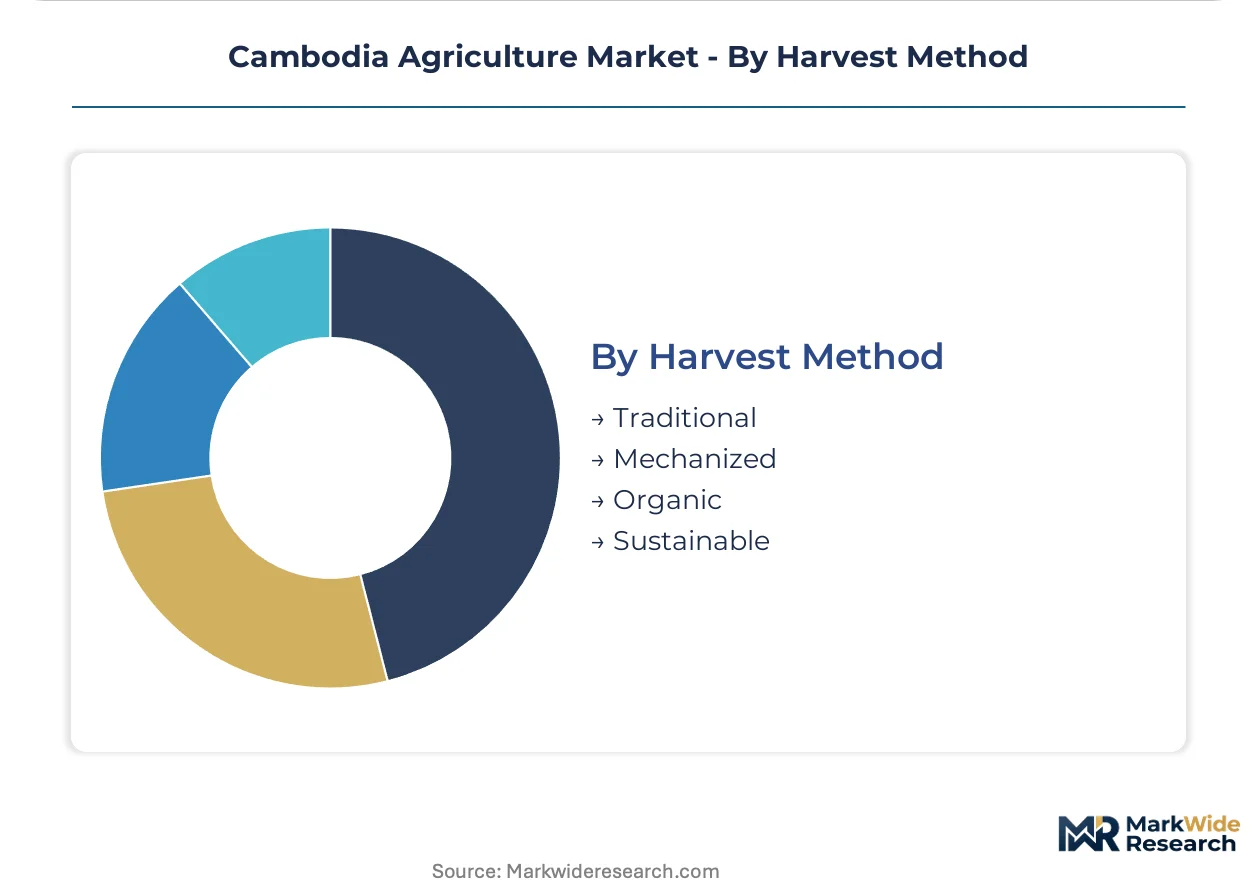
- Traditional:Manual transplanting and sickle harvesting persist across smallholder plots averaging under two hectares, particularly in Prey Veng and Takeo provinces where fragmented land tenure limits equipment deployment economics. Seasonal labor pools are contracting as rural wages rise and youth migration accelerates.
- Mechanized:Kubota and Deere precision planting and combine harvester fleets concentrate in Battambang and Pursat commercial cooperatives, compressing cultivation cycles and reducing post-harvest losses. Equipment maintenance skill shortages in provincial technician training programs extend downtime for complex systems.
- Organic:Chemical-free certification for fragrant rice attracts EU import quota premiums, with Battambang exporters leading laboratory testing investment.
- Sustainable:Rice-fish integrated systems in Tonle Sap floodplains offer dual-revenue streams with lower synthetic input dependence.
Traditional retains volume leadership; mechanized holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cultivation intensity concentrates in the Mekong River corridor where irrigation infrastructure and milling capacity cluster around provincial hubs. Battambang and Pursat provinces anchor commercial rice production through cooperative mechanization programs. Phnom Penh corridor provinces absorb the majority of value-added processing investment.
Battambang Province
Fragrant rice exports and organic certification programs drive commercial farming cooperative formation. Cambodia's Ministry of Agriculture enforces ASEAN-harmonized pesticide residue limits for EU-bound consignments. Battambang city millers invest in laboratory testing capacity to pre-certify shipments before export processing.
Pursat Province
Mechanized harvest fleets and precision planting equipment deployment accelerate as seasonal labor pools contract. National agricultural extension programs redirect cultivation patterns toward standardized commercial output. Pursat farming cooperatives absorb Kubota and Deere machinery through equipment financing schemes.
Kampong Thom Province
Consolidated land management units enable economies of scale previously fragmented across smallholder plots. The Ministry of Agriculture, Forestry and Fisheries directs irrigation infrastructure investments into previously rain-fed districts. Kampong Thom cooperative aggregation points consolidate bargaining position against wholesale buyers.
Siem Reap Province
Urban retail channel expansion from Phnom Penh supermarket chains establishes direct procurement relationships with provincial farming associations. Cambodia's national regulator mandates phytosanitary certification for cross-border vegetable trade. Siem Reap vegetable cultivation supplies specified varietals and harvest windows under advance purchase agreements.
Takeo Province
Storage infrastructure gaps force accelerated post-harvest sales at suppressed spot prices despite proximity to Phnom Penh demand centers. The Ministry of Agriculture coordinates cold chain investment timelines with provincial development plans. Takeo smallholders remain dependent on traditional auction-based wholesale channels lacking cooperative aggregation structures.
Cambodia Agriculture Market Competitive Landscape
Integrated rice millers and agricultural equipment suppliers split the market along value-chain position rather than direct competition. The vendor base concentrates around three strategic archetypes: machinery manufacturers with Southeast Asian distribution networks, vertically integrated processors controlling export certification, and cooperative aggregators consolidating smallholder output. Dominant competitive moves include precision technology localization for paddy conditions and laboratory testing capacity investment for phytosanitary pre-certification.
Within the machinery tier, Kubota Corporation and Deere & Company exemplify equipment suppliers adapting mechanized systems for tropical rice cultivation. Amru Rice Co., Ltd. occupies a position among integrated processors commanding branded export channels. These three entities represent distinct competitive positions without direct product overlap.
| Leading Market Players |
|---|
| Kubota Corporation |
| Deere & Company |
| Mahindra & Mahindra Ltd |
| Yanmar Holdings Co., Ltd. |
| Tractors and Farm Equipment Limited |
| New Holland Agriculture |
| AGCO Corporation |
| Escorts Limited |
| Amru Rice Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Battambang rice milling operations compresses margins across Cambodia's agricultural value chain while forcing suppliers toward export-grade certification investments and premium channel development.
Pricing Analysis
Cambodia's Ministry of Agriculture, Forestry and Fisheries enforcement of ASEAN-harmonized pesticide residue limits dictates the pricing tier structure across rice export segments. Three-tier pricing separates EU organic fragrant rice from ASEAN-standard white rice from domestic consumption grades, with certification investment creating margin expansion at the premium tier. Price differentiation rests on laboratory testing capacity and phytosanitary pre-certification timelines. Margins are tightening in commodity white rice due to Vietnamese and Thai supply competition, while smallholder cooperatives show highest price sensitivity due to fragmented land tenure limiting scale economies.
Supply Chain Analysis
ASEAN phytosanitary harmonization protocols function as de facto export-control mechanisms limiting rice flows to compliant millers with laboratory infrastructure. Geographic supply concentration centers on Battambang, Pursat, and Kampong Thom provinces for fragrant rice cultivation. Raw material dependencies include Vietnamese nitrogen fertilizer, Thai phosphate inputs, and Chinese equipment components. Supply chain risk manifests in fertilizer import exposure through regional intermediary pricing volatility. Distribution runs through Phnom Penh corridor millers for export processing, with cooperative aggregation gradually displacing traditional auction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment maintenance technician scarcity across provincial Cambodia creates a binding constraint on mechanized harvest fleet utilization, amplifying returns to stakeholders who close this capability gap through training infrastructure or predictive service models.
For Market Incumbents: Entrench cooperative relationships in Battambang and Pursat through captive equipment service networks that lock in precision planting fleet contracts. Invest in laboratory testing capacity ahead of EU organic quota expansion. Defend against Vietnamese miller price competition by securing advance purchase agreements with Phnom Penh supermarket chains. For New Entrants and Emerging Players: Mid-tier mechanized cooperatives in Kampong Thom and Siem Reap represent the most penetrable entry point, as these provinces lack incumbent equipment financing depth. Rice-fish integrated systems in Tonle Sap floodplains offer lower capital intensity entry with dual-revenue stream differentiation. Go-to-market through Ministry of Agriculture extension program partnerships accelerates land consolidation access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated millers with branded export channels and laboratory pre-certification infrastructure. Long-term viability favors vertically integrated processors controlling phytosanitary compliance rather than commodity traders exposed to spot price volatility. Monitor EU organic import quota utilization rates as inflection signal for premium segment capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Testing Capacity Investment | Amru Rice Co. and comparable millers pre-certify shipments to avoid just-in-time delivery conflicts with Thai buyers. |
| Equipment Financing Scheme Expansion | Kubota and Deere distributors in Pursat enable cooperative machinery absorption through localized credit structures. |
| Cooperative Aggregation Infrastructure | Battambang farming associations consolidate bargaining position against traditional wholesale auction channels. |
| Organic Certification Program Development | Battambang exporters capture EU quota premiums through chemical-free fragrant rice laboratory validation. |
| Direct Procurement Relationship Establishment | Phnom Penh supermarket chains transfer crop planning risk to farming associations while concentrating price-setting power. |
Research Methodology
Operator-level perspectives from cooperative managers, provincial equipment distributors, Ministry of Agriculture extension officers, and Phnom Penh supermarket procurement heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through Cambodia's Ministry of Agriculture, Forestry and Fisheries export statistics, ASEAN trade harmonization documentation, and customs records for fertilizer import flows. Bottom-up cultivation area estimates triangulated against top-down milling capacity assessments across Battambang and Phnom Penh corridor provinces.
Scenario-bracketing around irrigation infrastructure completion timelines and EU organic quota expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, harvest method, distribution channel, and end-use industry, with provincial cultivation intensity serving as a geographic overlay. CAGRs were derived from trend extrapolation of mechanization adoption curves and export certification penetration rates, incorporating input cost volatility assumptions for fertilizer import dependencies.
Practitioners should monitor ASEAN trade agreement negotiations and Mekong River irrigation upgrade completion schedules for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding labor migration patterns and equipment financing availability that could revise trajectory if rural wage acceleration outpaces mechanization economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Livestock and Meat Market