
 North America Animal Protein Market | 2026-2036
North America Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Animal Protein Market Analytics
The USDA's updated cell-cultured meat labeling framework is consolidating compliance costs around smaller producers who lack in-house legal and quality assurance teams. Tyson Foods leverages its vertically integrated feed-to-retail network to absorb these regulatory burdens without margin erosion. Cargill sustains competitive advantage through its dominant position in grain origination and protein processing across the U.S. Plains. JBS anchors its North American footprint with massive beef and pork processing scale that few rivals can replicate.
North America animal protein encompasses muscle tissue, organ meats, and derived collagen fractions from cattle, swine, poultry, and aquatic species, typically processed under HACCP protocols with specified pH, temperature, and moisture parameters to ensure shelf stability and pathogen control. These proteins serve as primary nitrogen sources in human diets, pet nutrition formulations, and specialized hydrolysates for clinical applications. Poultry leads volume throughput due to faster flock cycles and lower feed conversion ratios, while beef commands premium positioning in retail and food service channels where marbling scores and breed certifications drive price separation. Seafood represents the fastest-growing product type as aquaculture expansion and import sourcing diversify supply beyond traditional wild-catch limitations.
The USDA Food Safety and Inspection Service and FDA share jurisdiction over cell-cultured and conventional proteins, creating overlapping inspection regimes that shape facility design and operational cadence. Canada's Canadian Food Inspection Agency maintains parallel standards that facilitate cross-border trade but require dual certification for integrated suppliers. Mexico's Federal Commission for Protection from Sanitary Risks adds a third compliance layer for exporters serving integrated North American customers. Stakeholders must monitor how these regulatory boundaries evolve as novel production technologies challenge existing statutory definitions and inspection protocols.
Market Dynamics
The USDA's cell-cultured meat labeling mandate is forcing suppliers to rebuild compliance infrastructure around novel protein categories while conventional packers defend scale advantages in feedlot corridors.
Growth Catalysts
- Cell-Cultured Labeling Framework:The USDA's updated disclosure requirements create first-mover advantages for suppliers with existing FSIS inspection protocols and in-house regulatory teams.
- Midwest Feedlot Concentration:Integrated packing plants clustered near Interstate corridors in Nebraska, Kansas, and Iowa compress logistics costs and accelerate cold-chain velocity to coastal markets.
- Aquaculture Expansion:Recirculating aquaculture systems in the U.S. Southeast and Baja California are diversifying seafood supply beyond wild-catch quotas and seasonal variability.
Market Restraints
- Feed Grain Volatility:Corn and soybean meal prices swing with drought cycles in the U.S. Plains, compressing processor margins during El Niño periods.
- Dual-Jurisdiction Inspection Overlap:The FDA and USDA FSIS share authority over cell-cultured facilities, creating redundant audit protocols that extend facility commissioning timelines.
- Plant-Based Substitution:Pea and soy protein isolates in food service formulations displace conventional poultry in institutional contracts where cost-per-protein-gram dominates procurement.
Strategic Opportunities
- Canadian Cross-Border Integration:The Canadian Food Inspection Agency's harmonized meat inspection protocols enable consolidated production runs serving both U.S. and Canadian retail banners from single facilities.
- Pet Nutrition Hydrolysates:Specialized collagen fractions and organ meat meals command premium positioning in veterinary therapeutic diets and premium kibble formulations.
- IRA Biofuel Co-Product Streams:Renewable diesel tax credits in California and Oregon redirect rendered fats and tallow toward fuel feedstock, creating parallel revenue channels for packers.
Industry Challenges
- HACCP Specialist Scarcity:Qualified food safety plan developers and preventive controls qualified individuals command salary premiums that strain mid-sized processor operating budgets.
- Legacy Equipment Retrofit Costs:Conventional slaughter lines require seven-figure capital outlays to accommodate cell-cultured protein handling and segregated processing zones.
- Cross-Border Certification Timing:Mexico's Federal Commission for Protection from Sanitary Risks maintains independent approval queues that delay integrated North American product launches by 90-120 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Animal Protein Market |
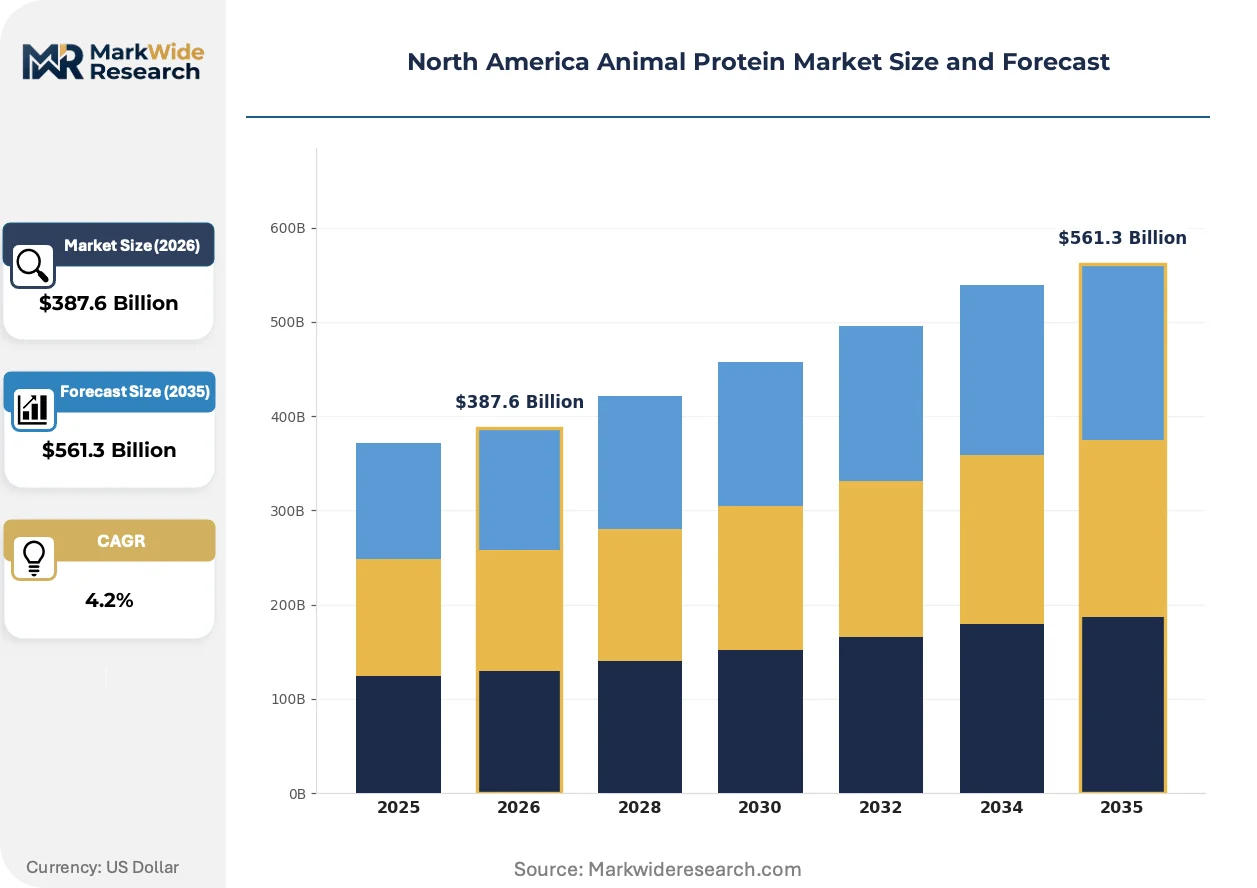
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Seafood End User: Retail, Food Service, Processing, Export Distribution Channel: Direct Sales, Wholesalers, Supermarkets, Online Application: Food Products, Pet Food, Nutritional Supplements, Culinary |
| Companies Covered | Agropur Dairy Cooperative, Dairy Farmers of America, Tyson Foods, Cargill, JBS, Arla Foods amba, Glanbia PLC, Groupe Lactalis, Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Animal Protein Market Evolving Landscape
Automation and alternative protein processing are compressing labor dependency while regulatory frameworks scramble to keep pace with production technology. These shifts favor capital-rich incumbents with compliance infrastructure.
Precision fermentation for collagen and gelatin alternatives is integrating into cosmetic and clinical-grade protein supply chains. Pharmaceutical buyers in New Jersey and Massachusetts are qualifying microbial-derived collagen for wound-healing applications. This technology is integrating upstream into existing bioreactor networks without requiring new fermentation capacity.
The USDA's updated HACCP validation requirements for mechanically separated poultry impose stricter pathogen monitoring frequencies on high-volume facilities. Small and mid-sized processors in the U.S. Southeast face disproportionate compliance cost burdens relative to throughput. Integrated operators with centralized laboratory services absorb these requirements through scale economies.
Food service distributors are consolidating protein procurement into category-management contracts that bundle conventional, alternative, and blended proteins under single-source agreements. Broadline operators in Texas and Florida are replacing spot-market purchasing with annual volume commitments that lock in price ceilings. This concentration is visible most acutely in K-12 and healthcare institutional channels where cost predictability outweighs product flexibility.
North America Animal Protein Market Segmentation
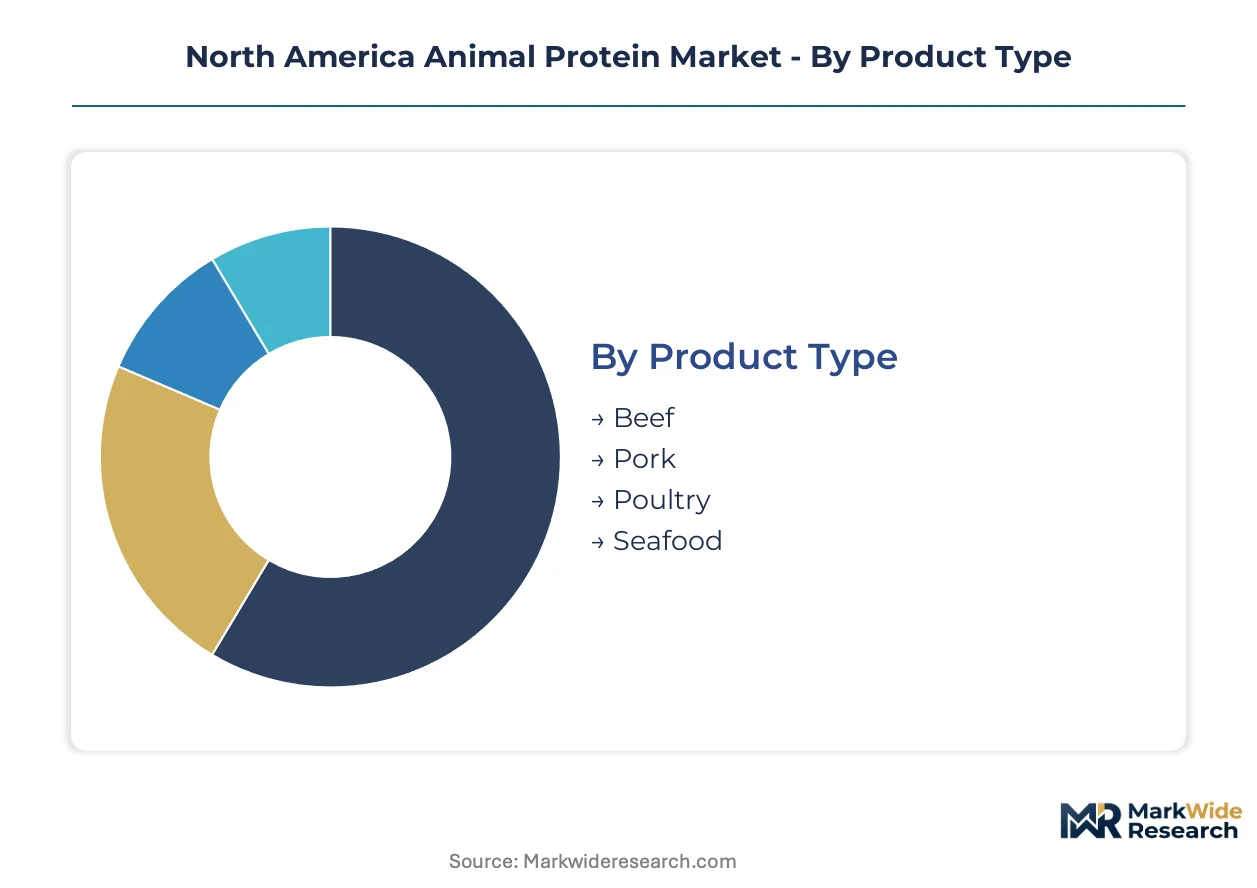
Segmentation in North American animal protein markets reveals how regulatory frameworks, channel economics, and protein functionality reshape supplier priorities. Understanding these divisions exposes where capital concentrates and where compliance burdens diverge.
Product Type:
Protein source selection dictates feed conversion efficiency, processing infrastructure requirements, and regulatory inspection protocols across the value chain.
- Beef:Carcass grading by USDA marbling scores and breed certifications creates price separation in retail and food service channels. Demand concentrates in the U.S. Midwest feedlot corridor where integrated packing plants compress logistics costs to coastal markets.
- Poultry:Faster flock cycles and superior feed conversion ratios drive volume throughput leadership. USDA FSIS mechanically separated poultry regulations impose stricter pathogen monitoring that favors high-volume facilities with centralized laboratory services.
- Pork:Swine production clusters near grain origination points in Iowa and Minnesota, with processing scale concentrated in Nebraska and North Carolina facilities.
- Seafood:Recirculating aquaculture systems in the U.S. Southeast and Baja California diversify supply beyond wild-catch quotas.
Poultry leads on scale; seafood leads on momentum.
End User:
Customer procurement patterns determine contract structures, price volatility exposure, and product specification complexity.
- Food Service:Broadline distributors in Texas and Florida consolidate procurement into annual volume commitments with price ceilings, replacing spot-market purchasing. K-12 and healthcare institutional channels prioritize cost predictability over product flexibility.
- Retail:Supermarket banners demand breed certifications and marbling score transparency to support premium positioning in meat cases.
- Processing:Further processors require consistent specification tolerances for sausage, deli, and prepared food manufacturing.
- Export:Canadian Food Inspection Agency harmonized protocols enable consolidated production runs serving both U.S. and Canadian markets from single facilities.
Food service leads on contract concentration; retail leads on specification intensity.
Distribution Channel:
Channel selection shapes cold-chain velocity, inventory carrying costs, and direct customer relationship depth.
- Direct Sales:Large protein processors bypass intermediaries to serve national restaurant chains and institutional buyers with dedicated logistics networks.
- Wholesalers:Independent distributors aggregate mixed-protein orders for mid-sized food service accounts lacking volume for direct procurement.
- Supermarkets:Retail banners control case-ready packaging specifications and private label development for protein categories.
- Online:E-commerce fulfillment requires modified atmospheric packaging and last-mile cold-chain infrastructure that diverges from conventional wholesale distribution.
Direct sales leads on margin capture; online leads on infrastructure investment requirements.
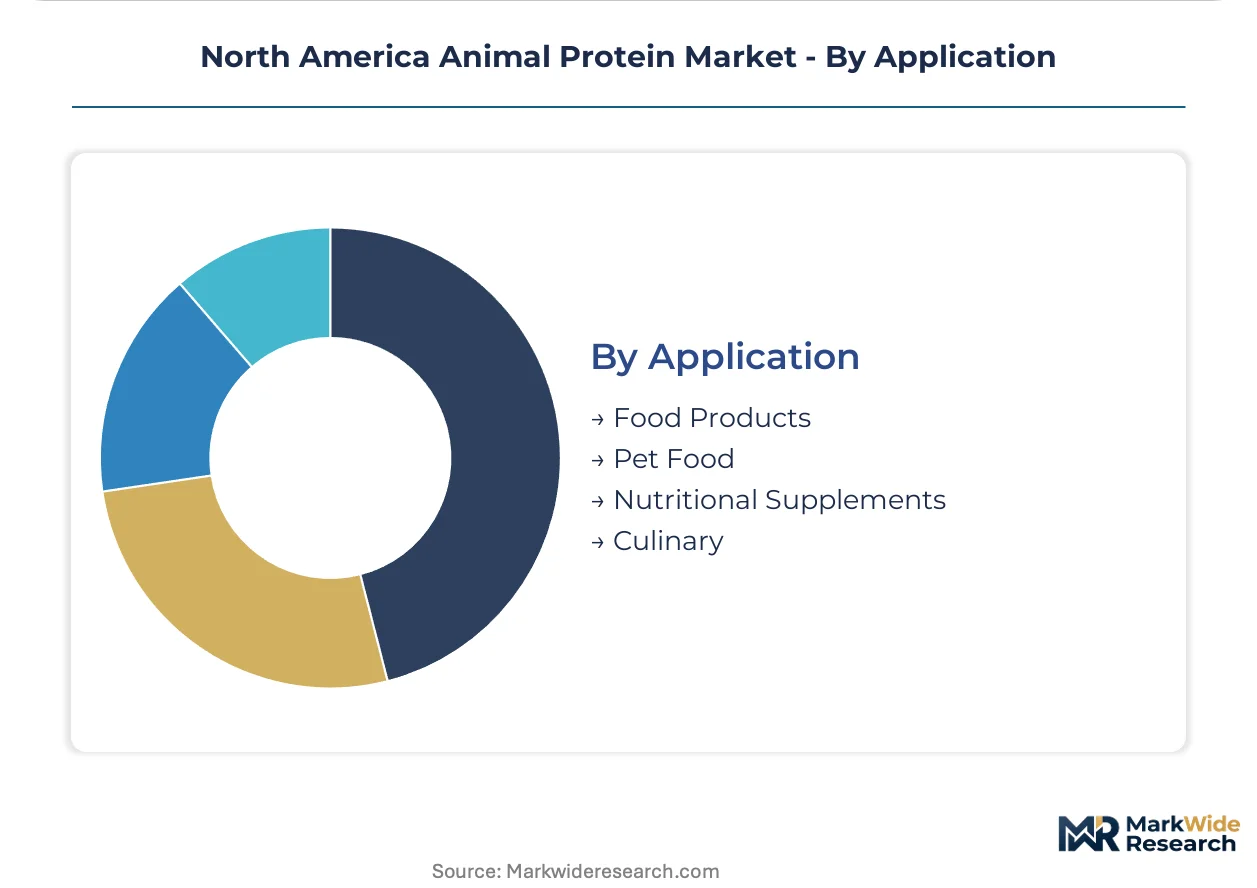
Application:
End-use functionality determines protein specification, processing intensity, and regulatory jurisdiction overlap.
- Food Products:Human consumption applications dominate volume, with HACCP protocols and FSIS inspection governing facility design and operational cadence.
- Pet Food:Specialized collagen fractions and organ meat meals command premium positioning in veterinary therapeutic diets.
- Nutritional Supplements:Hydrolyzed protein isolates for clinical applications require pharmaceutical-grade manufacturing qualifications.
- Culinary:Chef-driven demand for specific cuts and alternative protein blends expands menu development in premium food service segments.
Food products leads on volume throughput; nutritional supplements leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled meat processing labor pools and HACCP-certified technicians concentrate in the U.S. Midwest feedlot corridor, southern Ontario dairy belts, and northern Mexico cattle ranching zones. These workforce clusters anchor production capacity and inspection compliance infrastructure across the tri-national market.
United States
Integrated packing plants in Nebraska, Kansas, and Iowa process the majority of North American beef and pork volume. The USDA FSIS maintains parallel inspection protocols for conventional and cell-cultured protein facilities, creating compliance complexity near Omaha and Sioux Falls processing hubs. Tyson Foods and Cargill operate massive facilities along Interstate 80 corridors that compress cold-chain logistics to East and West Coast markets.
Canada
Dairy protein processing dominates in Quebec and Ontario, where Agropur and Dairy Farmers of America affiliate plants convert fluid milk into specialized ingredients. The Canadian Food Inspection Agency harmonizes meat inspection standards with U.S. protocols, enabling cross-border production runs from single facilities. Calgary and Edmonton serve as western protein logistics nodes connecting Prairie grain supplies to Pacific export terminals.
Mexico
Cattle ranching and pork production concentrate in northern states bordering Texas, with processing plants in Sonora and Chihuahua feeding U.S. supply chains. The Federal Commission for Protection from Sanitary Risks maintains independent certification queues that delay integrated North American product launches. Guadalajara and Monterrey host growing further-processing capacity for domestic retail and food service channels.
North America Animal Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North American animal protein landscape. The market structure concentrates around vertically integrated packers with captive feedlot and grain origination networks, while mid-sized processors occupy regional niches. Three archetypes dominate: scale-driven integrated giants, cooperative-owned dairy processors, and specialized ingredient suppliers. Competitive intensity manifests through capacity consolidation in Midwest packing corridors and strategic partnerships between protein processors and food service distributors.
Within the integrated packer tier, Tyson Foods, Cargill, and JBS exemplify scale-driven operators with feed-to-retail network control. Among cooperative structures, Agropur Dairy Cooperative and Dairy Farmers of America represent farmer-owned models with concentrated dairy protein processing capacity. Kerry Group PLC and Glanbia PLC occupy positions as specialized ingredient suppliers serving nutritional and clinical applications. These named entities anchor competitive dynamics without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Agropur Dairy Cooperative |
| Dairy Farmers of America |
| Tyson Foods |
| Cargill |
| JBS |
| Arla Foods amba |
| Glanbia PLC |
| Groupe Lactalis |
| Kerry Group PLC |
| Others |
Value Network & Pricing Analysis
Family-owned feedlot operators in the U.S. Plains and Midwest maintain pricing discipline through captive grain origination and long-term packing contracts, insulating their operations from spot-market volatility that erodes margins at merchant-dependent competitors. This ownership structure concentrates supply-side bargaining power in the hands of vertically integrated incumbents who control both input costs and output pricing.
Pricing Analysis
The bundled-versus-unbundled service split separates commodity protein transactions from value-added processing arrangements. Spot-market cattle purchases dominate the unbundled tier, while formula pricing tied to USDA grading standards anchors bundled contracts with national restaurant chains. Price differentiation rests on marbling scores and breed certifications in retail channels, with food service buyers showing highest sensitivity to cost-per-protein-gram in institutional contracts. Pricing pressure intensifies in poultry segments as plant-based isolates displace conventional volume in K-12 procurement.
Supply Chain Analysis
USDA FSIS and Canadian Food Inspection Agency certification gating restricts facility commissioning to operators with proven HACCP infrastructure and preventive controls qualified individuals. Geographic supply concentrates in the United States, Canada, and Mexico, with the Midwest feedlot corridor anchoring beef and pork processing and Baja California supporting aquaculture expansion. The supply chain draws from corn and soybean meal inputs tethered to drought-cycle volatility in the U.S. Plains. Single-source vulnerability in rendering and tallow recovery creates bottleneck risk. Distribution runs through broadline operators consolidating procurement into annual volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Animal Protein Market functions as a geographic-arbitrage play where Canadian cross-border integration yields compliance efficiencies unavailable to U.S.-only operators facing dual FDA-USDA jurisdiction.
For Market Incumbents: To counter plant-based substitution in institutional channels, Tyson Foods and JBS should deepen backward integration into alternative protein blending capacity while locking exclusive supply agreements with K-12 distributors. Securing in-house regulatory teams for cell-cultured labeling compliance provides defensive moats against smaller competitors lacking FSIS inspection protocols. For New Entrants and Emerging Players: Mid-sized food service accounts lacking volume for direct procurement represent the most penetrable buyer archetype. These operators seek consolidated protein sourcing across conventional, alternative, and blended categories. White-space targets include veterinary therapeutic diet formulations and precision fermentation collagen for pharmaceutical buyers in New Jersey and Massachusetts. A contract manufacturing angle serving branded pet nutrition lines offers lowest barriers to entry. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mid-cap processors with underutilized HACCP-certified capacity and established CFIA cross-border credentials. Long-term viability over the five-to-ten year horizon favors targets with demonstrated compliance infrastructure for novel protein categories. The signal to watch is USDA acceleration of cell-cultured facility approvals, which would re-rate first-mover packers with existing bioreactor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Protein Blending | Defends market share against pea and soy isolate displacement in institutional contracts. |
| Cross-Border Facility Certification | CFIA-USDA harmonization enables consolidated production runs serving both markets from single plants. |
| Pet Nutrition Hydrolysate Development | Veterinary therapeutic diet demand commands premium positioning for collagen fraction suppliers. |
| Cell-Cultured Regulatory Team Buildout | USDA labeling mandates favor incumbents with in-house compliance infrastructure and FSIS relationships. |
| Recirculating Aquaculture System Expansion | U.S. Southeast and Baja California RAS capacity diversifies seafood supply beyond wild-catch quotas. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feedlot operators, USDA FSIS inspection coordinators, broadline distributor procurement heads, and pet nutrition formulators with secondary validation from FDA guidance documents, CFIA meat inspection protocols, SEC 10-K protein segment disclosures, and customs trade flow data. Bottom-up volume modeling and top-down market sizing triangulated across these sources to constrain estimate variance.
Segment-weighting approaches applied differential growth assumptions across beef, poultry, pork, and seafood categories while modeling end-user splits between food service, retail, processing, and export channels. CAGRs were derived from trajectory fitting to historical throughput data and elasticity-adjusted demand projections across the analysis window. Industry-specific forecast inputs included feed conversion ratio trends and El Niño drought probability weightings for grain input cost modeling.
Underlying measurement precision varies by segment; poultry volume throughput carries tighter precision than emerging aquaculture RAS production. Forecasts reflect documented assumptions regarding regulatory approval timelines and cross-border certification harmonization. Deviation in USDA cell-cultured labeling enforcement intensity or feed grain price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Saudi Arabia Eggs Market