
 Spain Compound Feed Market | 2026-2036
Spain Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Compound Feed Market Analytics
Consolidation among large livestock cooperatives in Castile and León is recalibrating procurement power across northern Spain. Trouw Nutrition España SA leverages its premix technology leadership to secure long-term supply contracts with integrated pork operations. Cargill Inc. anchors its position through direct-to-farm distribution networks that bypass traditional wholesale layers. Nutreco NV competes by specializing in precision nutrition systems for high-performance dairy herds.
Compound feed comprises blended formulations of cereals, protein meals, minerals, and additives manufactured through grinding, mixing, pelleting, and extrusion processes to deliver standardized nutritional density for targeted animal species. Poultry feed occupies the largest volume share due to Spain's extensive broiler and layer operations concentrated in Murcia and Catalonia. Swine feed registers the fastest structural expansion as Aragon's pork sector scales finishing capacity. Ruminant feed retains stable margin pools tied to dairy farm consolidation in Galicia and the Basque Country.
Spain's Ministry of Agriculture enforces EU Green Deal targets through national CAP strategic plans that condition subsidies on sustainable feed sourcing. The country's food safety agency applies EU REACH and EFSA standards to regulate additive approvals and mycotoxin thresholds. Stakeholders must monitor how EU F-Gas Regulation phase-downs affect cooling costs in feed milling and whether BSE-era traceability mandates tighten further for cross-border raw material flows.
Market Dynamics
Spain's compound feed sector is restructuring around EU Green Deal compliance requirements that mandate carbon intensity reductions in agricultural inputs, forcing millers to reformulate protein sourcing and energy consumption patterns across Extremadura and Catalonia production clusters.
Growth Catalysts
- EU CAP Strategic Plans:Spain's Ministry of Agriculture channels subsidies toward sustainable feed sourcing, conditioning payments on verified low-carbon ingredient procurement from domestic oilseed crushers.
- Aragon Pork Cluster Expansion:Finishing capacity additions across northeastern Spain generate concentrated pull for high-performance swine formulations with optimized feed conversion ratios.
- Precision Nutrition Systems:Dairy cooperatives in Galicia deploy sensor-based ration optimization, creating demand for real-time formulated premix adjustments tied to milk yield monitoring.
Market Restraints
- Soybean Meal Import Dependency:Spain sources over seventy percent of protein meal from South American suppliers, exposing compounders to Atlantic shipping volatility and currency fluctuation.
- F-Gas Regulation Phase-Down:EU-mandated hydrofluorocarbon reductions elevate cooling costs for pelleting operations, compressing margins at midsize mills in Murcia.
- Traceability Mandate Complexity:BSE-era cross-border documentation requirements for rendered fats and animal proteins create administrative friction for importers at Barcelona and Valencia ports.
Strategic Opportunities
- Andalusian Olive Cake Integration:Underutilized pomace from Jaén oil mills offers locally sourced fiber and fat for ruminant rations, reducing import dependency.
- On-Farm Mixing Technology:Mobile blending units enable pig producers in Castile-La Mancha to customize finishing diets at the barn level, bypassing centralized mill distribution.
- Organic Feed Certification Growth:EU organic farming targets create premium positioning for certified compounders serving Catalonia's expanding free-range poultry operations.
Industry Challenges
- Feed Formulation Expertise Gap:Spanish agricultural universities produce insufficient nutritionists trained in amino acid optimization software, forcing cooperatives to recruit from Portuguese and French programs.
- Legacy Mill Retrofit Costs:Aging grinding and pelleting infrastructure in Castile and León requires capital deployment for energy efficiency compliance with national climate plans.
- Additive Approval Timelines:EFSA novel feed additive evaluations extend eighteen to thirty months, delaying Spanish innovators' access to enzyme and probiotic categories already commercialized in North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Compound Feed Market |
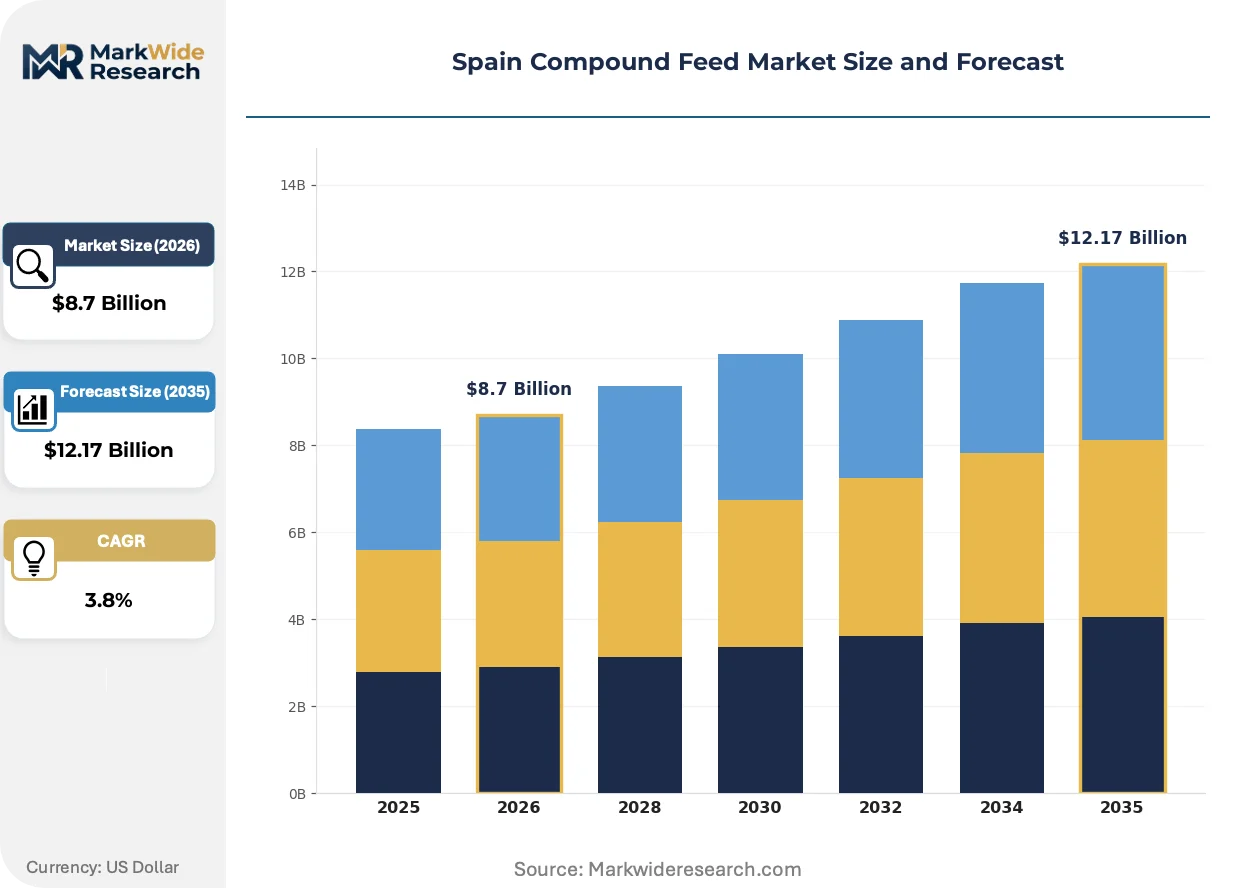
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Raw Material: Corn, Soybean Meal, Wheat, Barley End User: Farmers, Livestock Producers, Aquaculture Facilities, Feed Manufacturers Distribution Channel: Online Sales, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | ForFarmers, Trouw Nutrition España SA, Cargill Inc., ADM Animal Nutrition, Alltech Inc., Nutreco NV, Royal Agrifirm Group, Biomin, Koninklijke De Heus BV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Compound Feed Market Evolving Landscape
Digitalization and decarbonization mandates are converging to reshape how Spanish compounders source ingredients, manufacture formulations, and distribute finished feed to livestock operations across the peninsula.
Blockchain-enabled ingredient provenance tracking is decentralizing supply chain verification for Spanish swine and poultry integrators. Aragon-based pork producers now demand batch-level documentation linking soybean origin to specific Brazilian farms. This transparency infrastructure is compressing the role of traditional commodity brokers who previously obscured sourcing layers.
EU F-Gas Regulation phase-down timelines are accelerating refrigeration retrofit cycles across Spanish feed milling operations. Mills in Murcia and Catalonia face compressed timelines to replace hydrofluorocarbon cooling systems with ammonia or CO2 alternatives. Pelleting-intensive ruminant feed production bears disproportionate capital burden given higher thermal processing requirements.
Direct-to-farm distribution models are displacing wholesale intermediaries in northern Spain's dairy corridors. Galician cooperatives now contract volume commitments directly with premix suppliers, consolidating procurement decisions at the herd level rather than through regional distributors. This channel compression is most visible in the Basque Country where logistics platforms coordinate just-in-time delivery to automated feeding systems.
Spain Compound Feed Market Segmentation
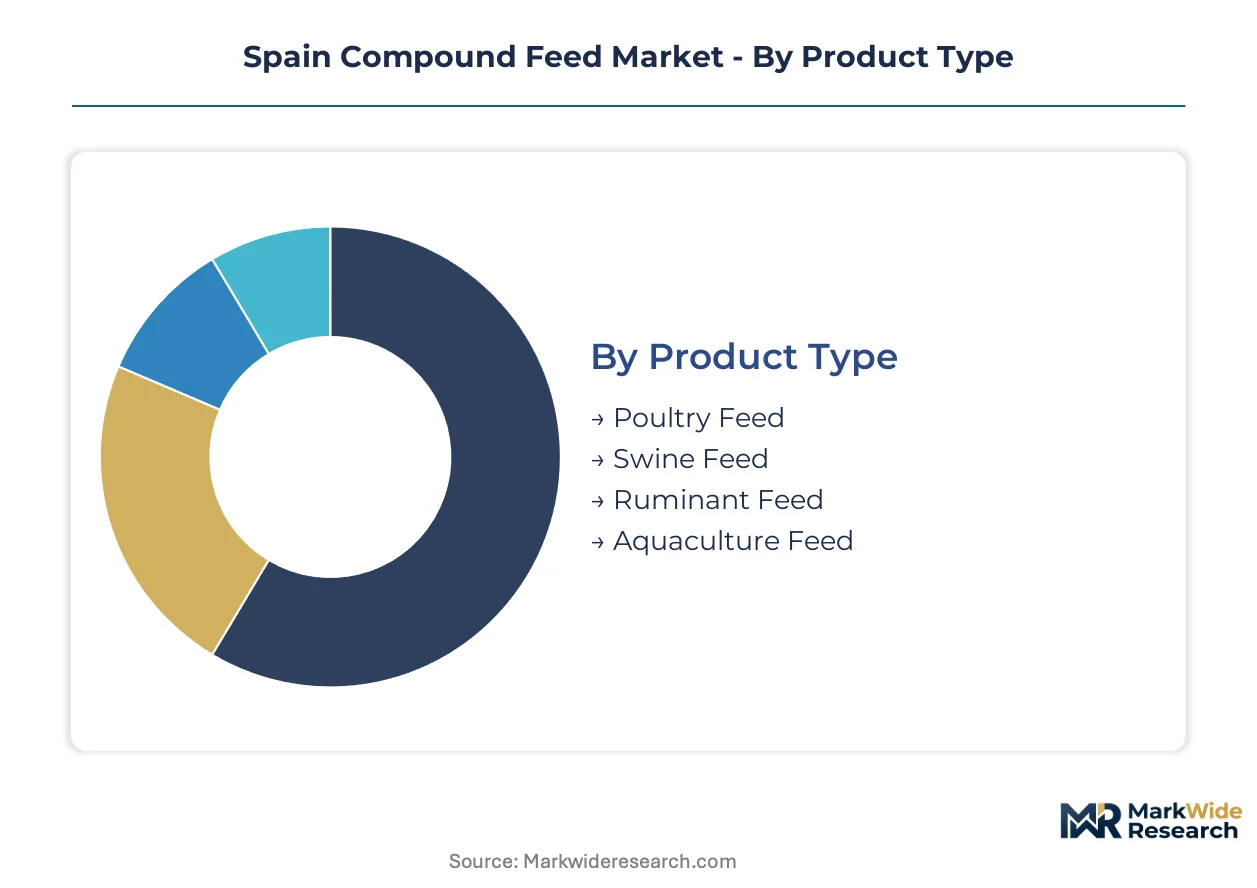
Compound feed segmentation in Spain reveals how formulation standards, procurement patterns, and channel economics diverge across livestock species and supply chain tiers. Understanding these divides exposes where margin pools concentrate and where EU Green Deal compliance costs bite hardest.
Product Type:
Poultry feed buyers prioritize volume consistency and feed conversion efficiency, while swine feed purchasers demand amino acid precision tied to genetic line performance.
- Poultry Feed:Broiler and layer formulations combine maize, soybean meal, and synthetic amino acids to maximize protein deposition rates. Murcia's vertically integrated poultry operations drive concentrated demand for heat-pelleted starter and grower diets with specified metabolizable energy densities. The EU F-Gas Regulation elevates cooling costs for pelleting operations serving this segment.
- Swine Feed:Multi-phase formulations span nursery, grower, and finisher stages with lysine-to-energy ratios calibrated to Duroc and Pietrain genetic lines. Aragon's pork cluster expansion generates pull for high-performance diets with optimized feed conversion ratios. Precision nutrition systems now enable real-time ration adjustments at the barn level.
- Ruminant Feed:Dairy concentrates and beef fattening rations incorporate bypass proteins and protected fats for high-yielding Holstein herds in Galicia.
- Aquaculture Feed:Extruded floating and sinking pellets for sea bream and sea bass farms along the Mediterranean coast carry premium marine protein specifications.
Poultry feed leads volumes today; swine feed is gaining share fastest.
Raw Material:
Cost tier differentiation separates commodity grains from imported protein meals, with origin traceability becoming a procurement discriminator.
- Corn:Domestic yellow maize from Castile and León supplies energy-dense formulations for poultry and swine rations. Spanish millers blend imported Ukrainian and French origins to balance moisture and mycotoxin profiles.
- Soybean Meal:Dehulled solvent-extracted meal from Brazilian crushers provides standardized protein content for amino acid formulation. Over seventy percent import dependency exposes compounders to Atlantic shipping volatility and currency fluctuation.
- Wheat:Soft milling wheat from Andalusia and Castile-La Mancha serves as a partial corn substitute in ruminant feeds when price spreads justify substitution.
- Barley:Two-row spring barley from northern Spain supplies fiber and fermentable energy for dairy cow rations in the Basque Country.
Corn leads volumes today; soybean meal commands the steepest price volatility exposure.
End User:
Customer scale and technical sophistication determine whether buyers source commodity blends or precision-formulated premix systems.
- Farmers:Small-to-midscale operators in Extremadura purchase bagged complete feeds through agricultural cooperatives with seasonal credit terms.
- Livestock Producers:Integrated pork and poultry operations in Catalonia contract direct with premix suppliers for customized additive packages and volume commitments.
- Aquaculture Facilities:Marine fish farms along the Valencia and Murcia coasts specify extruded pellet durability and leaching resistance for offshore cage systems.
- Feed Manufacturers:Regional compounders in Castile and León blend base mixes with purchased premixes to serve localized livestock concentrations.
Livestock producers lead volumes today; aquaculture facilities are expanding procurement most quickly.
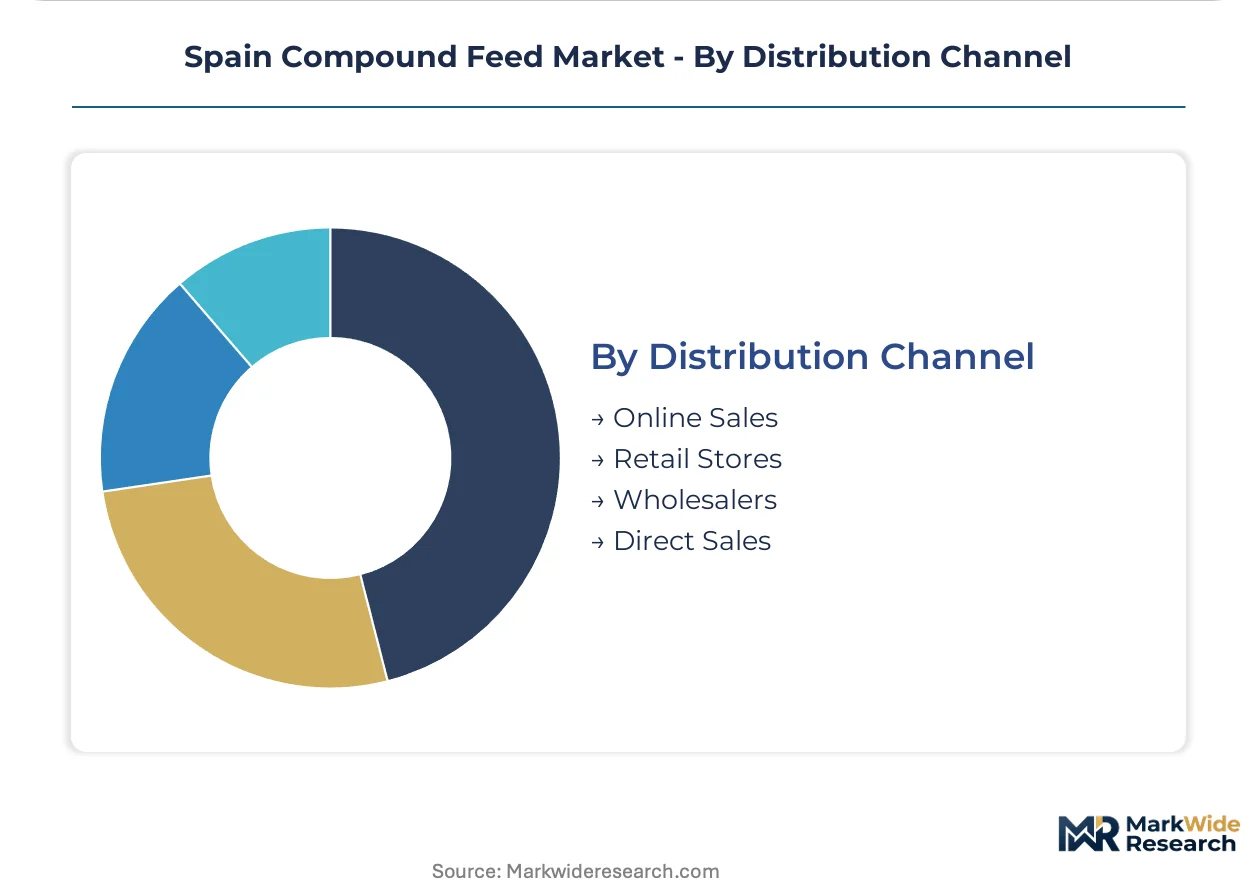
Distribution Channel:
Channel choice reflects buyer scale, with direct relationships displacing wholesale layers for large integrated operations.
- Online Sales:Digital platforms enable small farmers to compare commodity feed prices and arrange delivery scheduling without cooperative intermediation.
- Retail Stores:Agricultural supply cooperatives in rural Castile-La Mancha stock bagged poultry and rabbit feeds for hobby farmers and smallholders.
- Wholesalers:Regional distributors consolidate volumes from multiple mills to serve fragmented dairy operations in Galicia with mixed-truck delivery.
- Direct Sales:Premix suppliers contract volume commitments directly with Galician cooperatives, bypassing traditional wholesale layers entirely.
Wholesalers lead volumes today; direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized feed formulators and nutritionists cluster in Catalonia and Aragon, anchoring Spain's technical workforce for precision livestock nutrition. These talent concentrations drive regional specialization in high-performance swine and poultry formulations. Their expertise shapes procurement patterns across Iberian production corridors.
Aragon
Finishing capacity expansion across northeastern pork operations generates concentrated demand for amino acid-optimized grower and finisher diets. Spain's Ministry of Agriculture channels CAP subsidies toward farms sourcing verified low-carbon ingredients. Zaragoza's integrated pork cluster now contracts directly with premix suppliers for multi-phase formulations calibrated to Duroc genetic lines.
Catalonia
Vertically integrated broiler and layer operations in Lleida and Girona provinces drive volume pull for heat-pelleted starter diets with specified metabolizable energy densities. The EU F-Gas Regulation elevates cooling costs for pelleting operations serving this segment. Barcelona's logistics platforms coordinate just-in-time delivery to automated feeding systems at cooperative dairy herds.
Galicia
High-yielding Holstein herds in A Coruña and Lugo provinces create stable demand for dairy concentrates incorporating bypass proteins and protected fats. EFSA standards regulate additive approvals for rumen-protected nutrient categories. Local cooperatives deploy sensor-based ration optimization, creating pull for real-time formulated premix adjustments tied to milk yield monitoring.
Andalusia
Expanding free-range poultry operations in Seville and Córdoba provinces generate premium positioning for certified organic feed formulations. EU organic farming targets condition subsidy payments on verified sustainable sourcing. Jaén's olive oil mills supply underutilized pomace for locally sourced fiber and fat in ruminant rations, reducing import dependency.
Castile and León
Consolidating livestock cooperatives in Valladolid and Burgos recalibrate procurement power across northern grain belts. National climate plans mandate energy efficiency retrofits for aging grinding infrastructure. Regional compounders blend base mixes with purchased premixes to serve localized cattle and sheep concentrations.
Spain Compound Feed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's compound feed sector, creating a tiered structure where scale advantages clash with technical agility. The market consolidates around premix technology leadership and direct distribution capabilities. Three archetypes dominate: multinational nutrition conglomerates with integrated supply chains, regional compounders serving localized livestock clusters, and specialty additive houses licensing enzyme and probiotic technologies. Competitive intensity centers on M&A activity targeting cooperative feed manufacturing assets and strategic partnerships bypassing traditional wholesale layers.
Among multinational nutrition specialists, Trouw Nutrition España SA and Cargill Inc. occupy anchor positions exemplifying divergent channel strategies. Trouw Nutrition represents the premix technology archetype securing long-term supply contracts through formulation expertise. Cargill anchors the direct-to-farm distribution model that compresses wholesale intermediation. Nutreco NV sits within the precision nutrition specialization tier, targeting high-performance dairy herd requirements with sensor-integrated ration systems.
| Leading Market Players |
|---|
| ForFarmers |
| Trouw Nutrition España SA |
| Cargill Inc. |
| ADM Animal Nutrition |
| Alltech Inc. |
| Nutreco NV |
| Royal Agrifirm Group |
| Biomin |
| Koninklijke De Heus BV |
| Others |
Value Network & Pricing Analysis
Specialized feed formulators clustering in Catalonia and Aragon create labor-cost differentials that widen pricing-tier spreads between commodity blends and precision-formulated premix systems across Spain's compound feed sector.
Pricing Analysis
Bundled premix-plus-technical-service contracts command premium positioning against unbundled commodity feed transactions. Three-tier pricing structure across premium, standard, and economy levels separates amino acid-optimized formulations for Aragon's integrated pork operations from basic grower diets for Extremadura's smallholders. Cost compression in standard-tier rations is intensifying because Brazilian soybean meal import costs feed directly into base formulation economics. Small-to-midscale farmers in Castile-La Mancha exhibit highest price sensitivity, while Galician dairy cooperatives prioritize feed conversion performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian and Argentine soybean crushers supplying over seventy percent of Spain's protein meal requirements. Raw material flows draw from Ukrainian corn origins, French wheat alternatives, and domestic Castile and León yellow maize harvests. Atlantic shipping volatility and currency fluctuation expose compounders to commodity price volatility. Distribution runs through direct-to-farm contracts with Galician cooperatives alongside traditional wholesale layers serving fragmented Extremadura livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
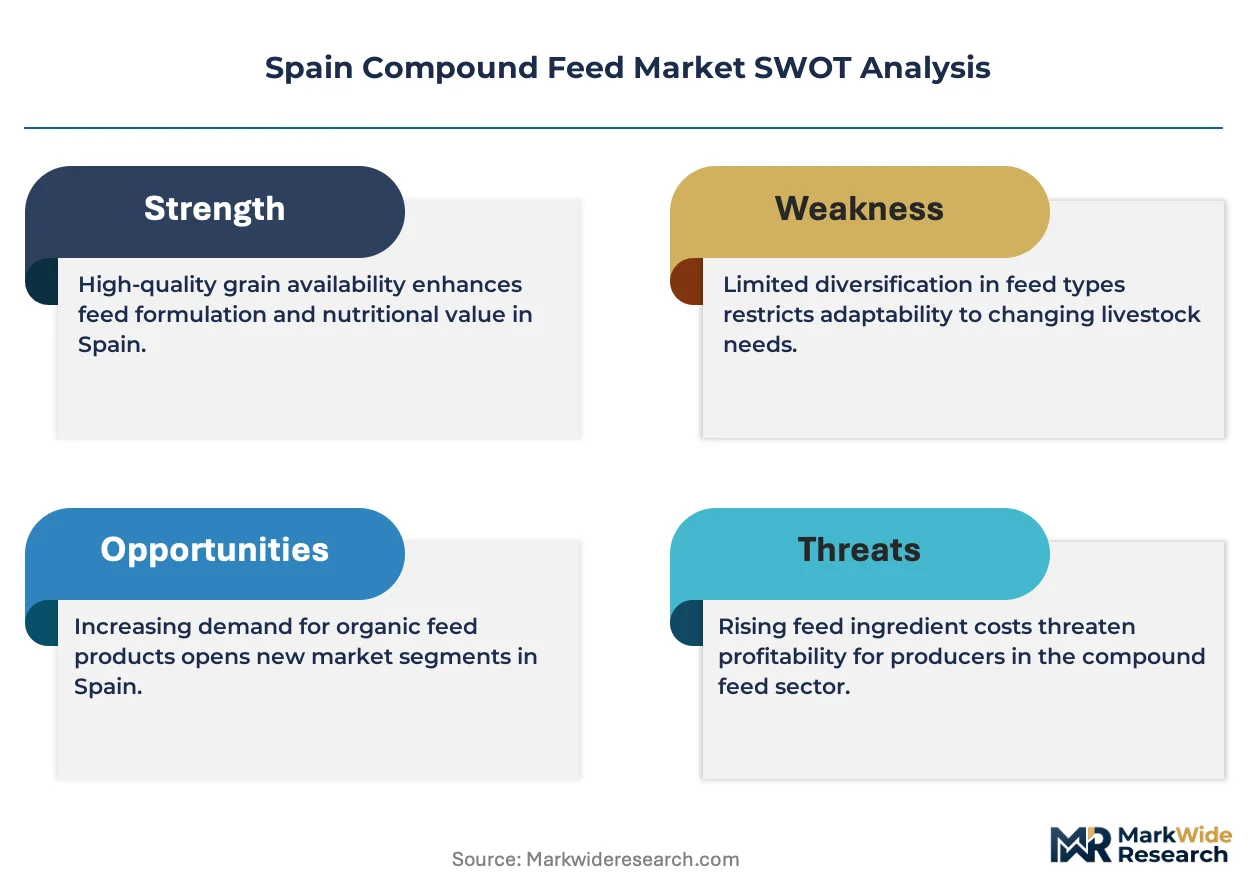
Spain's compound feed sector offers margin-expansion pathways through Andalusian olive cake integration reducing import-dependent protein costs and organic certification premiums capturing Catalonia's free-range poultry shift.
For Market Incumbents: Anticipate EU F-Gas Regulation compliance deadlines by retrofitting Murcia and Catalonia pelleting operations with ammonia cooling systems before cost penalties activate. Secure backward integration into Jaén olive pomace sourcing to lock fiber and fat inputs for ruminant formulations. EFSA additive approval delays threaten competitive positioning against North American enzyme suppliers already commercialized in alternative markets. For New Entrants and Emerging Players: Capture white-space opportunity in on-farm mobile blending technology for Castile-La Mancha pig producers seeking barn-level diet customization without centralized mill dependency. Target aquaculture feed expansion along Valencia and Murcia coastlines where marine protein specifications command technical barriers incumbents have underdeveloped. Lead with precision nutrition software partnerships rather than capital-intensive milling assets. For Investors and Strategic Acquirers: Multinational nutrition conglomerates are the most active acquirer in this space, consolidating cooperative feed manufacturing assets to compress wholesale intermediation. Long-term viability hinges on climate-aligned sourcing credentials qualifying for EU CAP subsidy conditioning. Watch EFSA novel feed additive approval timelines as inflection indicator for Spanish innovators' competitive access to enzyme and probiotic categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Olive Pomace Sourcing | Jaén oil mill partnerships reduce Brazilian protein meal dependency for Andalusian ruminant feed. |
| Direct-to-Farm Distribution Expansion | Galician cooperative contracts bypass wholesale layers Cargill has already established. |
| Precision Nutrition Software Licensing | Sensor-integrated ration systems capture Nutreco's high-performance dairy herd positioning. |
| Organic Feed Certification Buildout | EU organic farming targets condition subsidy payments Seville and Córdoba poultry operations demand. |
| Ammonia Cooling Retrofit Acceleration | EU F-Gas Regulation phase-down elevates compliance costs for Murcia pelleting operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feed mill operations managers, cooperative procurement directors, agricultural university nutrition program leads, and EFSA regulatory affairs specialists with secondary validation against EU CAP strategic plan filings, Spanish Ministry of Agriculture subsidy disbursement records, Brazilian customs export data, and SEC 10-K disclosures from listed nutrition conglomerates. Bottom-up volume modeling across Extremadura, Aragon, Catalonia, and Galicia production clusters triangulated against top-down macroeconomic agricultural input demand projections.
Segment-weighting approaches distributed value and volume across poultry feed, swine feed, ruminant feed, and aquaculture feed product types, further stratified by corn, soybean meal, wheat, and barley raw material dependencies, and calibrated by farmer, livestock producer, aquaculture facility, and feed manufacturer end-user categories. CAGRs were derived from historical trajectory analysis adjusted for EU Green Deal implementation pacing and Aragon pork cluster capacity expansion schedules across the projection horizon. Modeled inputs incorporated EFSA additive approval pipeline status and F-Gas Regulation retrofit cost curves.
Regulatory enforcement variance, Atlantic shipping route disruption, and Brazilian harvest yield fluctuation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding CAP subsidy continuity and precision nutrition technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Brazil Cashew Market