
 Cervical Artificial Discs Market | 2026-2036
Cervical Artificial Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Artificial Discs Market Analysis
China is narrowing its reliance on imported cervical disc implants through domestic manufacturing scale-up in Suzhou and Changzhou medical device clusters. Medtronic leverages integrated spine portfolios to sustain hospital contract loyalty across North American and European accounts. Zimmer Biomet anchors its position through specialized cobalt-chromium and PEEK material expertise in motion-preserving cervical constructs. Globus Medical differentiates via controlled distribution networks that limit third-party markup exposure.
Cervical artificial discs are implantable prosthetic devices designed to replace damaged intervertebral discs in the cervical spine while preserving segmental motion, typically constructed from biocompatible combinations of polyethylene cores, titanium endplates, or cobalt-chromium alloys with surface coatings that promote osseointegration. These devices function to maintain physiological range of motion, reduce adjacent segment degeneration risk, and eliminate the need for fusion hardware in indicated patients with radiculopathy or myelopathy. Single-level discs occupy the dominant revenue position due to established clinical evidence and broader surgeon training penetration, while multi-level systems represent the fastest-growing category as bilateral and multilevel indications gain regulatory traction. PEEK and titanium material segments command premium positioning based on radiolucency advantages and fatigue resistance profiles that support long-term implant survival.
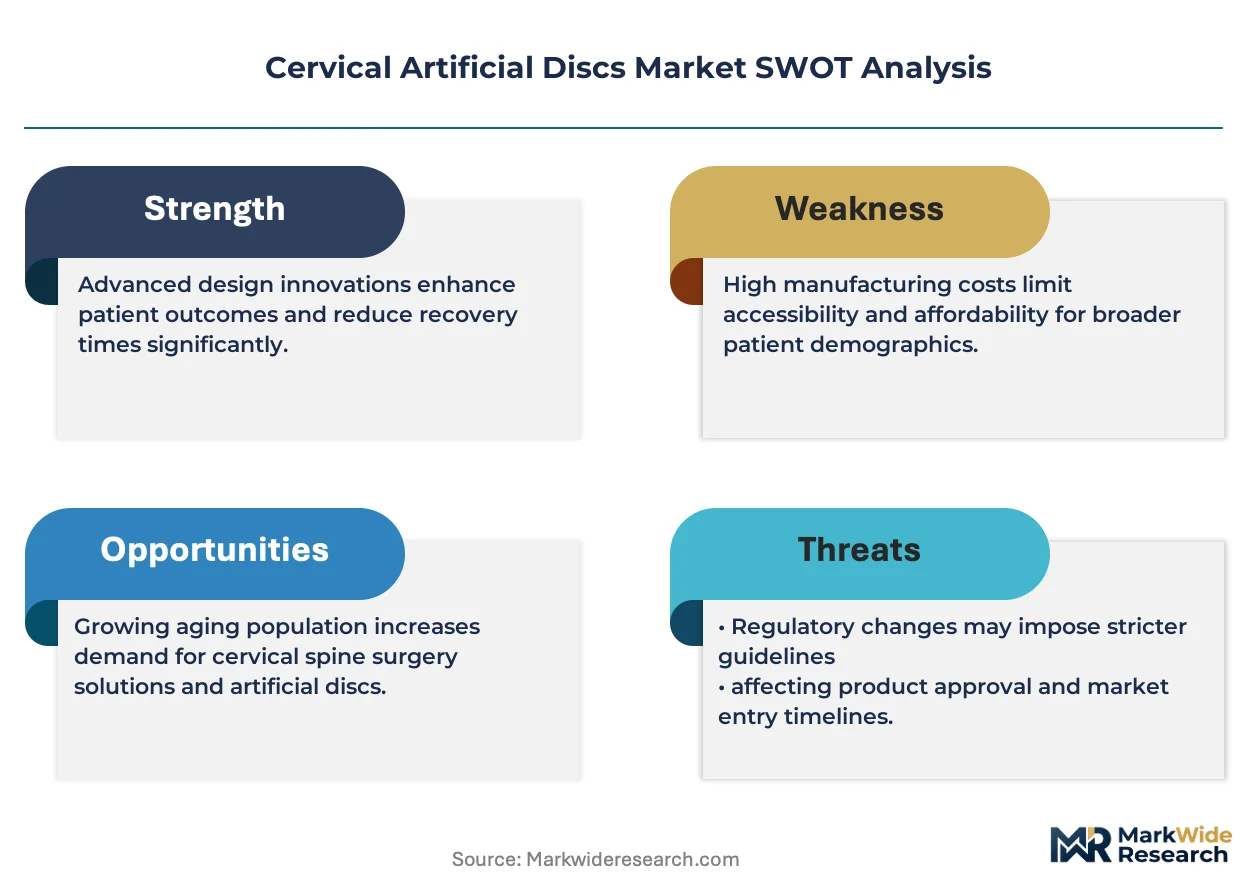
FDA premarket approval pathways and EU MDR conformity requirements impose substantial clinical trial and post-market surveillance obligations that filter market access to well-capitalized manufacturers. Japan's PMDA and China's NMPA maintain distinct biocompatibility and mechanical testing standards that necessitate jurisdiction-specific regulatory strategies for commercial entry. Stakeholders must monitor evolving reimbursement decisions by Germany's G-BA and France's HAS, as these determinations directly shape addressable patient volumes across Europe's largest spine surgery markets.
Market Dynamics
Hospital systems in the United States are consolidating purchasing authority into centralized value analysis committees, compressing vendor access and forcing manufacturers to demonstrate total cost-of-ownership superiority over fusion alternatives through long-term motion preservation data.
Growth Catalysts
- Statutory health insurance reimbursement:Germany's G-BA has expanded reimbursement codes for cervical disc arthroplasty, enlarging eligible patient pools and normalizing motion-preserving procedures within standard care pathways.
- PEEK and titanium material platforms:Advanced polymer and alloy compositions with optimized fatigue resistance profiles are extending implant survival timelines and supporting premium positioning in device selection protocols.
- Suzhou and Changzhou manufacturing clusters:Domestic production scale-up in China's medical device corridors is reducing import dependency and accelerating regulatory approval timelines for locally manufactured cervical constructs.
Market Restraints
- FDA PMA pathway duration:Class III premarket approval requirements impose multi-year clinical trial obligations and substantial capital outlays that filter competitive entry to well-capitalized manufacturers with established evidence-generation capabilities.
- Cobalt-chromium alloy supply concentration:Specialized metallurgical feedstock for motion-preserving endplates concentrates among limited specialty suppliers, creating input cost volatility exposure for device fabricators.
- Anterior cervical discectomy and fusion substitution:Established fusion procedures with decades of surgeon training penetration and predictable reimbursement pathways retain preference in conservative treatment hierarchies at non-academic centers.
Strategic Opportunities
- Multi-level arthroplasty indications:Bilateral and multilevel cervical disc replacement systems are gaining regulatory traction as clinical evidence accumulates, opening addressable volumes beyond single-level dominance.
- France HAS reimbursement expansion:Pending favorable technology assessment determinations by the national health authority would unlock statutory coverage for motion-preserving cervical interventions across Europe's second-largest spine surgery market.
- Direct-to-hospital distribution models:Controlled distribution networks that bypass traditional distributor markups are enabling manufacturers to capture margin compression and strengthen clinical training relationships with surgical teams.
Industry Challenges
- Biostatistics and clinical evidence generation:Randomized controlled trial design and long-term follow-up execution for adjacent segment degeneration endpoints require specialized epidemiological expertise that concentrates among contracted research organizations with orthopedic device experience.
- EU MDR conformity transition:Enhanced post-market surveillance obligations and notified body capacity constraints are extending recertification timelines for legacy cervical disc systems and demanding upgraded quality management system documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Artificial Discs Market |
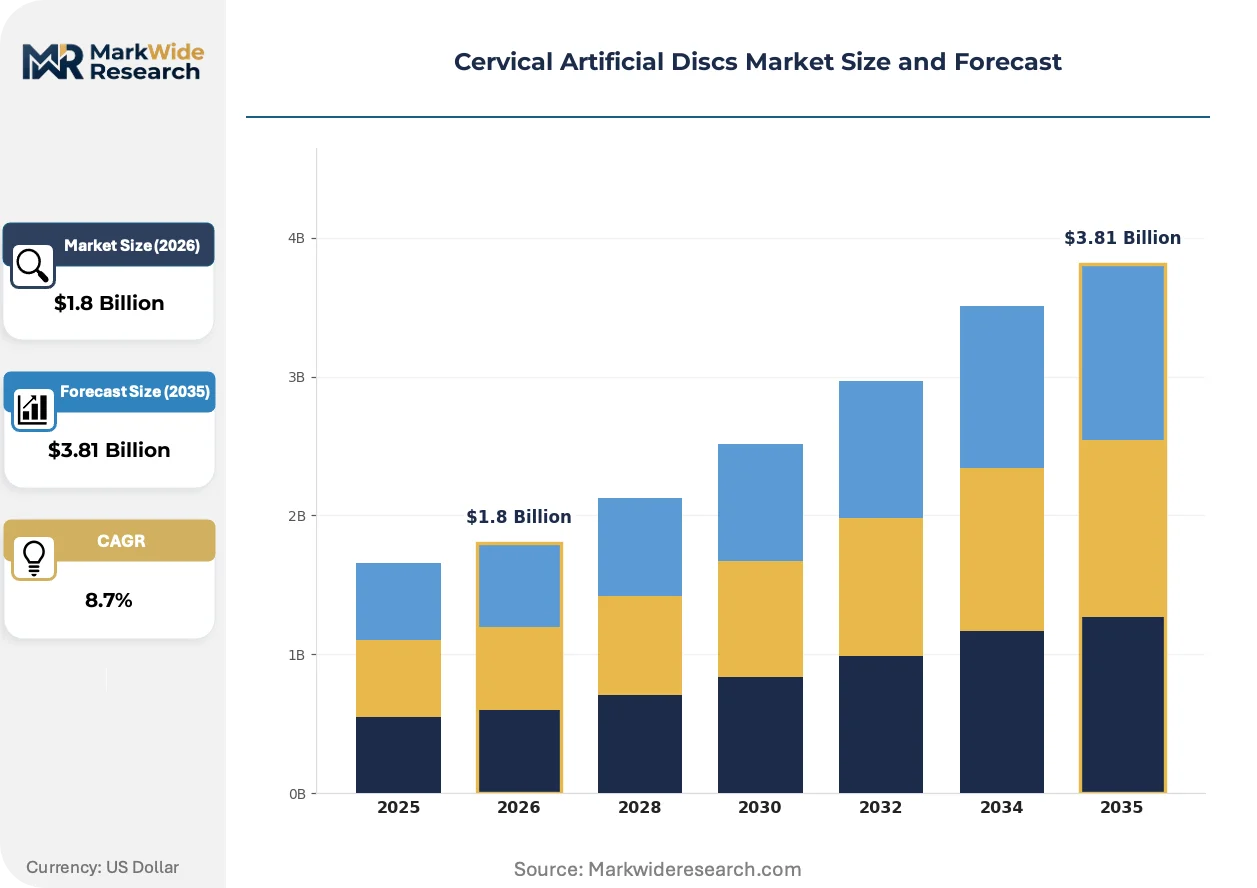
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Level Discs, Multi-Level Discs, Hybrid Discs, Expandable Discs Material: Polyethylene, Titanium, Cobalt-Chromium, PEEK End User: Hospitals, Outpatient Surgery Centers, Rehabilitation Clinics, Private Practices Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Centinel Spine, Orthofix Company, Medtronic, Stryker Corporation, DePuy Synthes, Zimmer Biomet, Globus Medical, Alphatec Spine, NuVasive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Artificial Discs Market Emerging Trajectories
Motion-preserving spine surgery is undergoing material and procedural recalibration as radiolucent polymers, surface-engineered alloys, and multilevel implant platforms reshape competitive differentiation and surgeon training requirements.
Polyetheretherketone core technologies with titanium plasma-sprayed endplates are collapsing the historical trade-off between radiolucency and osseointegration performance that constrained polyethylene-only designs. Academic medical centers with advanced imaging protocols are adopting these hybrid constructs at accelerated cadences to enable postoperative motion assessment without metal artifact interference. The structural consequence is compressing differentiation space for legacy metal-on-polyethylene configurations in premium device tiers.
EU MDR conformity requirements for Class III implantable devices are extending clinical evidence obligations and notified body review timelines across European markets. Manufacturers must now maintain active implant registries and submit periodic safety update reports that exceed predecessor Medical Device Directive surveillance intensity. Cervical disc portfolios with pre-2021 CE markings face compressed renewal windows and upgraded technical documentation demands that favor organizations with dedicated regulatory affairs infrastructure.
Hospital value analysis committees are consolidating implant selection authority away from individual surgeon preference and toward standardized vendor contracts with volume-tiered pricing and outcomes accountability provisions. Integrated delivery networks in the United States are displacing open procurement with committed partnership arrangements that bundle device supply with clinical training and complication management protocols. This concentration is most visible in tertiary referral centers where spine service line administrators negotiate multi-year agreements with motion-preserving portfolio suppliers.
Cervical Artificial Discs Market Segmentation
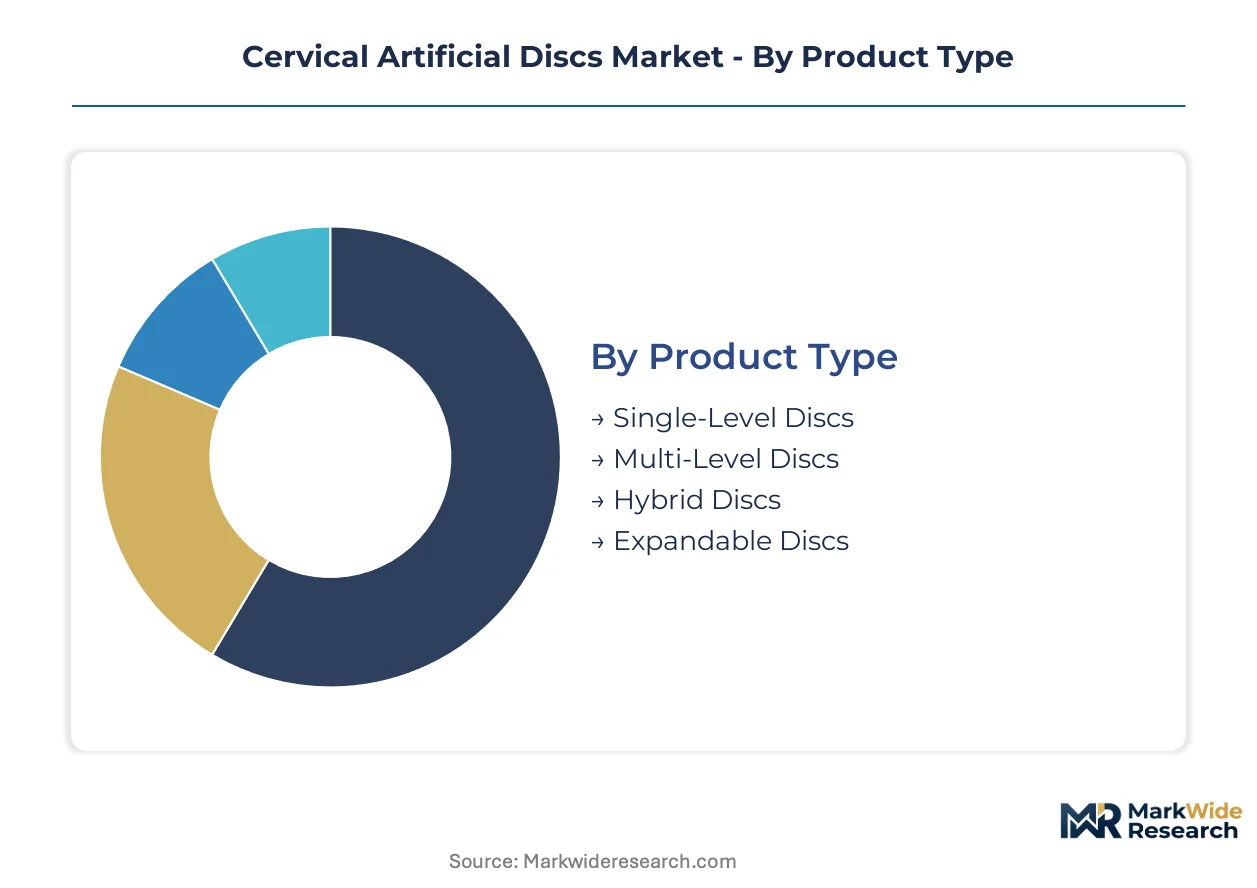
Cervical artificial discs segment across procedural complexity, material engineering, care setting, and supply chain configuration. Each dimension shapes reimbursement pathways, surgeon training requirements, and manufacturer margin structures differently.
Product Type:
Procedural indication breadth spans from straightforward single-level replacement to complex multilevel reconstruction and salvage scenarios.
- Single-Level Discs:These devices address one cervical disc space with established biomechanical profiles and the deepest surgeon training penetration. Hospital systems in the United States concentrate procurement volume here due to predictable outcomes and streamlined value analysis committee approval.
- Multi-Level Discs:Bilateral and multilevel configurations preserve motion across contiguous segments in more complex degenerative presentations. Germany's statutory health insurance reimbursement expansion is accelerating eligible patient access for these technically demanding procedures.
- Hybrid Discs:Constructs combining disc replacement with fusion elements address mixed pathology presentations in single surgical episodes.
- Expandable Discs:Height-adjustable designs accommodate intraoperative sizing refinement and revision scenarios.
Established volume favors single-level systems; emerging adoption favors multi-level platforms.
Material:
Biocompatibility and imaging performance requirements drive material selection trade-offs between osseointegration speed and radiolucency.
- PEEK:Polyetheretherketone cores deliver superior radiolucency for postoperative motion assessment without metal artifact interference. Suzhou and Changzhou manufacturing clusters are scaling domestic PEEK processing capabilities to reduce China's import dependency.
- Titanium:Plasma-sprayed titanium endplates accelerate bone integration through optimized surface topography. FDA premarket approval pathways for titanium constructs demand extensive fatigue resistance documentation.
- Polyethylene:Conventional bearing surfaces dominate legacy device portfolios with proven wear characteristics.
- Cobalt-Chromium:Alloy compositions provide exceptional fatigue resistance for long-term implant survival under cyclic loading.
PEEK and titanium command premium positioning; polyethylene retains cost-sensitive volume.
End User:
Care setting determines reimbursement intensity, capital equipment requirements, and surgeon credentialing standards.
- Hospitals:Tertiary referral centers with integrated spine service lines manage the highest procedural complexity and device procurement volumes. Value analysis committees at these institutions are consolidating vendor contracts toward multi-year partnership arrangements.
- Outpatient Surgery Centers:Ambulatory settings capture migrating single-level cases as anesthesia and surgical technique advances enable same-day discharge protocols.
- Rehabilitation Clinics:Postoperative recovery facilities coordinate with implanting surgeons on motion preservation outcomes tracking.
- Private Practices:Individual surgeon-owned entities maintain selective referral relationships with hospital-based surgical suites.
Hospital systems anchor revenue concentration; outpatient surgery centers are expanding most quickly.
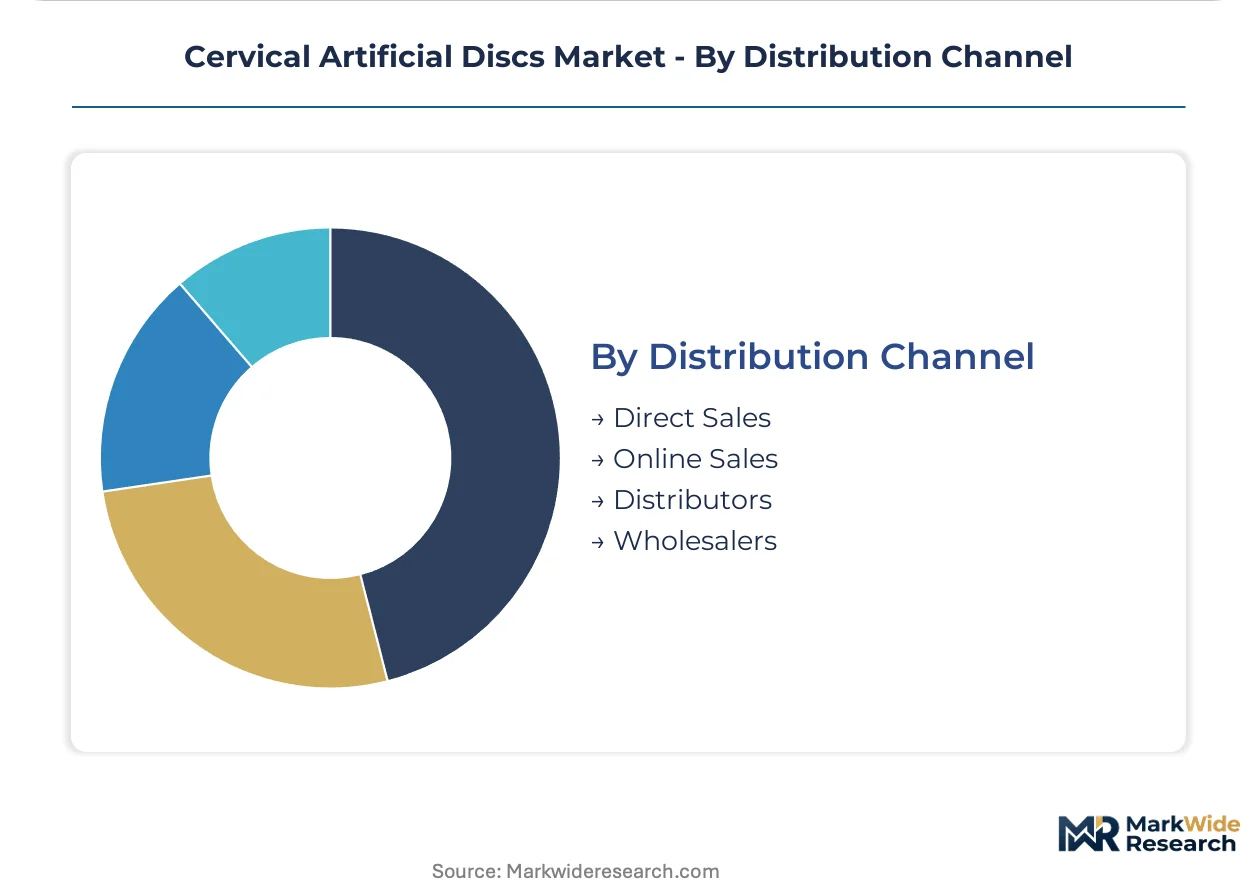
Distribution Channel:
Supply chain configuration determines margin capture, clinical training access, and inventory carrying costs.
- Direct Sales:Manufacturer-controlled field organizations bypass intermediary markups and enable dedicated surgeon education programs. Globus Medical leverages this model to limit third-party exposure.
- Distributors:Regional specialty distributors maintain localized inventory and relationships with non-academic centers.
- Online Sales:Digital procurement platforms serve smaller practices with standardized device configurations.
- Wholesalers:Broad-line medical supply wholesalers aggregate demand across multiple orthopedic categories.
Direct sales maximize margin retention; distributor networks sustain geographic coverage breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical feedstock for motion-preserving endplates concentrates among limited suppliers in Germany, the United States, and Japan, creating geographic dependencies that shape device fabrication economics and regulatory submission strategies across the cervical artificial discs market.
United States
Hospital systems consolidate purchasing authority into centralized value analysis committees that compress vendor access and demand total cost-of-ownership superiority. FDA premarket approval pathways for Class III devices impose multi-year clinical trial obligations that filter competitive entry. Tertiary referral centers in metropolitan clusters negotiate multi-year partnership arrangements with motion-preserving portfolio suppliers.
Germany
Statutory health insurance reimbursement expansion by G-BA has enlarged eligible patient pools and normalized motion-preserving procedures within standard care pathways. EU MDR conformity requirements extend clinical evidence obligations and notified body review timelines for implantable devices. Manufacturing concentration in Baden-Württemberg and Bavaria sustains precision machining capabilities for cobalt-chromium alloy processing.
China
Domestic manufacturing scale-up in Suzhou and Changzhou medical device clusters reduces import dependency for PEEK and titanium constructs. NMPA maintains distinct biocompatibility and mechanical testing standards that necessitate jurisdiction-specific regulatory strategies. Yangtze River Delta production corridors accelerate regulatory approval timelines for locally manufactured cervical implants.
Japan
PMDA regulatory frameworks maintain specialized requirements for long-term implant survival documentation under cyclic loading conditions. Academic medical centers in Kanto and Kansai regions adopt hybrid PEEK-titanium constructs with advanced imaging protocols for postoperative motion assessment. Domestic fabricators concentrate in Nagoya and Osaka industrial zones with established orthopedic device heritage.
France
Pending HAS technology assessment determinations would unlock statutory coverage for motion-preserving cervical interventions across Europe's second-largest spine surgery market. ANSM oversight aligns with EU MDR transition timelines for Class III implantable device recertification. Île-de-France and Auvergne-Rhône-Alpes hospital networks evaluate motion-preserving alternatives within conservative treatment hierarchies.
Cervical Artificial Discs Market Vendor Landscape
Integrated spine portfolio suppliers and specialized motion-preservation specialists split the market between breadth-driven contract loyalty and focused technical differentiation. Consolidated purchasing authority at hospital systems favors organizations with dedicated regulatory affairs infrastructure and established evidence-generation capabilities. Two dominant competitive moves include direct-to-hospital distribution models that bypass traditional markups, and multi-level arthroplasty platform development to capture indications beyond single-level dominance.
Among diversified orthopedic conglomerates, Medtronic and Zimmer Biomet exemplify integrated portfolio strategies that sustain hospital contract loyalty across North American and European accounts. Globus Medical anchors the specialized distribution archetype through controlled networks that limit third-party markup exposure. Stryker Corporation and DePuy Synthes occupy positions within the scale-driven tier, leveraging broad surgical technology portfolios to secure value analysis committee placement. NuVasive and Alphatec Spine represent focused spine specialists competing on procedural innovation and surgeon training relationships.
| Leading Market Players |
|---|
| Centinel Spine |
| Orthofix Company |
| Medtronic |
| Stryker Corporation |
| DePuy Synthes |
| Zimmer Biomet |
| Globus Medical |
| Alphatec Spine |
| NuVasive |
| Others |
Supply Flow & Price Mechanics
Cobalt-chromium alloy feedstock concentration in German and Japanese specialty metallurgical suppliers anchors margin capture at the device fabrication tier, forcing manufacturers to absorb input volatility or pass through costs to hospital procurement committees with consolidated bargaining power.
Pricing Analysis
FDA premarket approval pathways dictate the pricing tier structure across cervical artificial disc portfolios. Three-tier pricing structure across premium, standard, and economy levels separates PEEK-titanium hybrid constructs with advanced fatigue documentation from polyethylene-bearing legacy systems and uncoated titanium alternatives. Cost compression in standard-tier devices is intensifying because Suzhou manufacturing clusters are scaling domestic PEEK processing capabilities. Academic medical centers with advanced imaging protocols exhibit the least price sensitivity; ambulatory surgery centers migrating single-level cases demonstrate the highest.
Supply Chain Analysis
Specialized cobalt-chromium alloy billets and titanium plasma-spray feedstock draw from concentrated suppliers in Germany, the United States, and Japan. Raw material dependencies center on high-purity cobalt-chromium ingots, medical-grade PEEK resin, and titanium powder for additive manufacturing. Single-source vulnerability runs through Baden-Württemberg precision machining corridors where legacy orthopedic device heritage concentrates. Distribution runs through direct sales organizations at integrated spine portfolio suppliers and regional specialty distributors serving non-academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term implant survival documentation under cyclic loading conditions represents the scarce capability that separates viable competitors from filtered entrants, with FDA premarket approval pathways and EU MDR conformity requirements acting as capability gates that concentrate market access among well-capitalized manufacturers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Entrench hospital contract loyalty through multi-year partnership arrangements that bundle device supply with clinical training and complication management protocols. Deepen backward integration into cobalt-chromium alloy supply through captive relationships with Baden-Württemberg metallurgical suppliers. Consolidate procurement authority displacement by value analysis committees through outcomes accountability provisions and total cost-of-ownership superiority documentation. For New Entrants and Emerging Players: Build out controlled distribution networks that bypass traditional distributor markups and enable dedicated surgeon education programs in non-academic centers with less consolidated purchasing authority. Target France's pending HAS reimbursement expansion as the most penetrable geography for first commercial traction. Pursue direct-to-hospital contracting models that capture margin compression and strengthen clinical training relationships with surgical teams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed spine specialists that have accumulated FDA premarket approval portfolios and established hospital system contracts but lack integrated orthopedic conglomerate scale. Long-term viability over the extended horizon hinges on multi-level arthroplasty platform development and EU MDR recertification execution. Watch Germany's G-BA reimbursement code expansion velocity as the inflection signal for addressable patient volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III device designation imposes multi-year clinical trial obligations that filter competitive entry to well-capitalized manufacturers. |
| EU MDR Conformity Transition | Enhanced post-market surveillance obligations extend recertification timelines for legacy cervical disc systems. |
| Hospital System Partnership | Value analysis committees at tertiary referral centers consolidate procurement authority into multi-year vendor contracts. |
| Multi-Level Platform Development | Bilateral and multilevel indications gain regulatory traction as clinical evidence accumulates beyond single-level dominance. |
| Reimbursement Strategy | Germany's G-BA and France's HAS determinations directly shape addressable patient volumes across Europe's largest spine surgery markets. |
Methodological Framework
A spread of perspectives from spine surgeons, hospital purchasing committee members, biomedical engineers, and regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary interviews with GPO contracts managers and distributor channel partners were cross-referenced against FDA premarket approval filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation validated segmentation splits across the analysis window.
Demand-supply balance framing anchored the forecast framework throughout the projection horizon. Segmentation dimensions modeled include procedural complexity tier, material engineering platform, care setting intensity, and supply chain configuration. CAGRs were derived from procedure volume trajectories and average selling price evolution assumptions. Industry-specific forecast inputs incorporated G-BA reimbursement code expansion timelines and NMPA domestic manufacturing approval velocity.
Stress conditions across cobalt-chromium alloy supply disruption, EU MDR notified body capacity constraints, and hospital value analysis committee consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding motion-preserving procedure migration and adjacent segment degeneration evidence accumulation. Cross-checking against hospital capital expenditure disclosures and orthopedic device manufacturer SEC filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Power Smart Bed Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Single Lead ECG Equipment Market