
 Organ Care Systems (OCS) Market | 2026-2036
Organ Care Systems (OCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Care Systems (OCS) Market Analytics
Market Context
Multi-source procurement for perfusion consumables and portable device modules is broadening as transplant centers diversify vendor relationships beyond single-platform commitments. TransMedics leverages integrated service contracts to anchor high-volume accounts across major US academic medical centers. Paragonix Technologies Inc competes on temperature-controlled static preservation with specialized cardiac transport devices. OrganOx Limited dominates normothermic liver perfusion with technology leadership in extended criteria donor organ resuscitation.
Technical Definition and Segment Structure
Organ Care Systems comprise electromechanical perfusion platforms that maintain donor organs in a functioning, metabolically active state outside the human body through temperature-controlled pulsatile blood flow with oxygenation, pH monitoring, and nutrient delivery. These systems extend viable preservation time from hours to days while enabling functional assessment before transplantation, primarily serving organ procurement organizations and transplant surgical teams. Portable Devices command the largest revenue share due to emergency transport requirements and air ambulance compatibility, while Consumables generate recurring margin pools through single-use perfusion circuits and proprietary solution cartridges. Software Solutions represent the fastest-expanding segment as remote monitoring capabilities integrate with hospital electronic health record systems.
Regulatory Framework and Outlook
FDA premarket notification and EU MDR Class III device pathways impose extensive clinical validation requirements on normothermic perfusion systems, directly shaping product development timelines and market access costs for manufacturers. Health Canada and the UK's MHRA maintain aligned but distinct approval frameworks that demand separate quality management system audits and post-market surveillance protocols. Stakeholders must monitor evolving reimbursement decisions from national transplant authorities regarding whether machine perfusion costs qualify for bundled procurement funding or require separate technology assessment approvals.
Market Dynamics
Portable perfusion platforms are forcing transplant centers to reconfigure procurement workflows around single-use consumable dependencies, creating vendor lock-in risks that procurement committees now actively mitigate through multi-source qualification programs.
Growth Catalysts
- Extended Criteria Donor Expansion:Aging donor pools in the United States and Germany drive demand for organ resuscitation capabilities that normothermic perfusion uniquely delivers. Transplant networks report higher utilization rates for marginal organs when functional assessment precedes implantation.
- FDA Breakthrough Device Designation:Expedited review pathways for novel perfusion technologies compress development-to-commercialization timelines. Manufacturers leverage this framework to secure conditional coverage agreements with transplant procurement organizations.
- Air Ambulance Integration:Portable device miniaturization enables inter-hospital organ transport via rotorcraft and fixed-wing medical evacuation. Flight surgeons now specify perfusion compatibility in equipment procurement specifications.
Market Restraints
- Single-Use Circuit Costs:Proprietary perfusion sets and oxygenator modules command premium pricing that strains transplant center operating budgets. Consumables represent recurring expenditure commitments independent of transplantation volume.
- EU MDR Class III Certification Burden:Extended clinical validation requirements for normothermic systems delay market entry and elevate quality management system compliance costs. Notified body capacity constraints extend review timelines.
- Static Cold Storage Persistence:Ice-based preservation remains the default protocol for standard-criteria donors, limiting addressable market expansion. Established clinical workflows resist disruption without compelling outcome differentiation.
Strategic Opportunities
- India Transplant Infrastructure Buildout:The country's national organ allocation network expansion creates first-mover positioning for portable perfusion platforms. Regional transplant centers in Maharashtra and Tamil Nadu seek technology partnerships.
- Hypothermic-to-Normothermic Hybrid Systems:Dual-mode devices bridge sub-zero preservation with metabolic reactivation, addressing donor organ heterogeneity. Engineering convergence attracts cardiovascular and abdominal transplant specialists simultaneously.
- Remote Monitoring Integration:Cloud-connected perfusion telemetry enables centralized oversight of multi-site organ transport operations. Hospital information system vendors pursue embedded module partnerships.
Industry Challenges
- Perfusionist Workforce Scarcity:Specialized training programs for ex-vivo organ management graduate insufficient practitioners to support platform deployment scale. Academic medical centers compete for certified specialists through retention premiums.
- Legacy Cold Chain Infrastructure:Existing organ procurement organization transport containers and vehicle fleets require capital-intensive retrofitting for powered perfusion compatibility. Fleet replacement cycles extend adoption timelines.
- Interoperability Standards Absence:Proprietary data protocols between device manufacturers and hospital electronic health record systems force costly custom integration projects. Health information exchanges demand normalized data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Care Systems (OCS) Market |
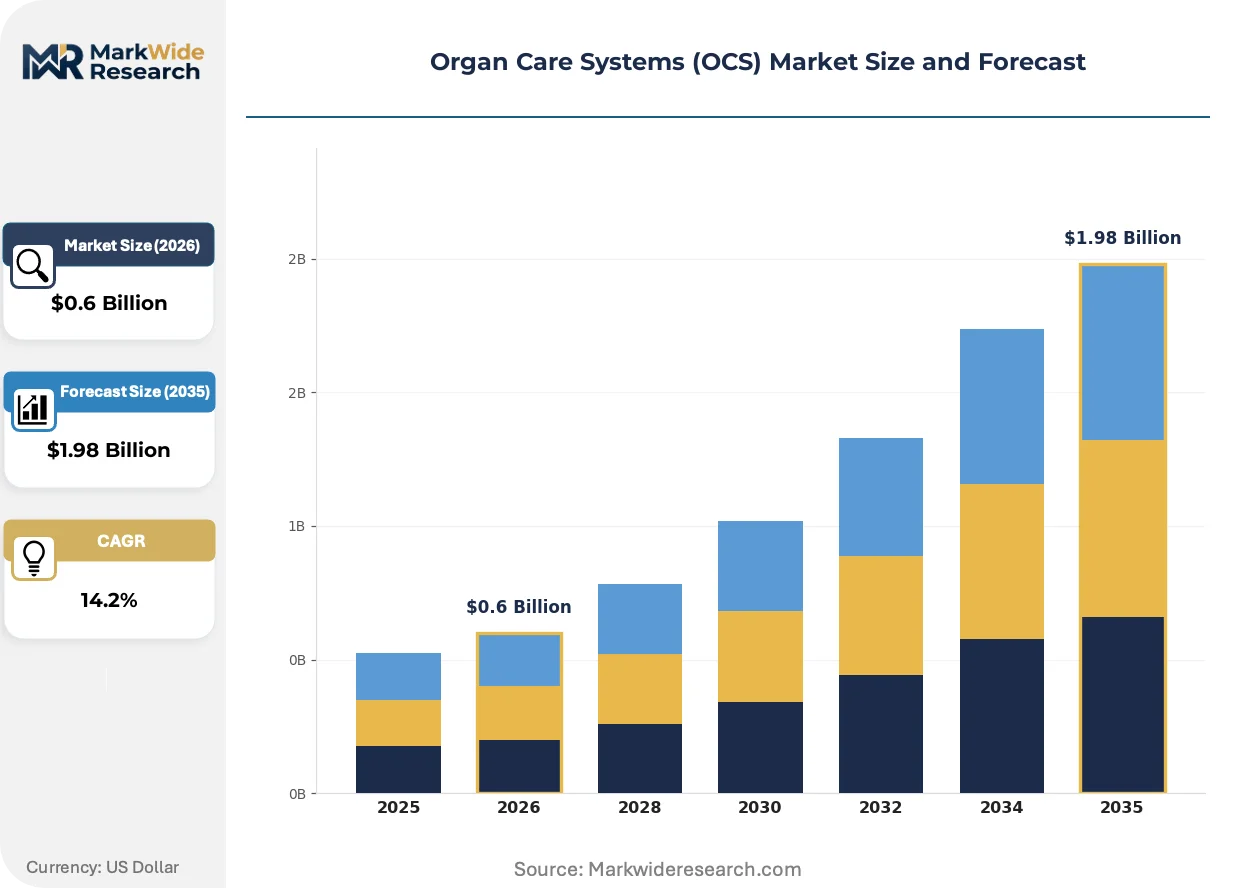
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Static Systems, Consumables, Software Solutions Application: Cardiac, Hepatic, Renal, Pulmonary End User: Hospitals, Transplant Centers, Research Institutions, Biopharmaceutical Companies Delivery Mode: Direct Delivery, Mobile Services, Remote Monitoring, In-Hospital |
| Companies Covered | TransMedics, Paragonix Technologies Inc, OrganOx Limited, Xvivo Perfusion AB, Bridge to Life Ltd, Organ Recovery Systems Inc, Waters Medical Systems LLC, Preservation Solutions Inc, Organ Assist BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Care Systems (OCS) Market Evolving Landscape
Machine perfusion technology is converging with digital health infrastructure, creating new value capture mechanisms beyond device hardware. Transplant stakeholders now evaluate platforms through total cost-of-ownership lenses that incorporate data integration and workforce training dimensions.
Sensor-embedded perfusion circuits are automating real-time metabolic parameter monitoring during organ transport. Transplant procurement organizations in the United States and Germany deploy these systems to reduce cold ischemia time variability. The technology is automating decision support for organ acceptance committees, compressing assessment windows from hours to minutes.
EU MDR post-market surveillance requirements are intensifying clinical evidence collection obligations for normothermic perfusion device manufacturers. Extended follow-up protocols for recipient outcomes now accompany initial device approval. Liver transplant programs across France, Germany, and the United Kingdom face expanded documentation burdens that favor established vendors with regulatory affairs scale.
Transplant center purchasing committees are consolidating vendor relationships around integrated service contracts that bundle device placement, consumable supply, and technical support. Single-platform commitments displace multi-vendor evaluations that previously characterized procurement. Academic medical centers in the United States lead this consolidation, negotiating multi-year agreements that lock in volume commitments and service level guarantees.
Organ Care Systems (OCS) Market Segmentation
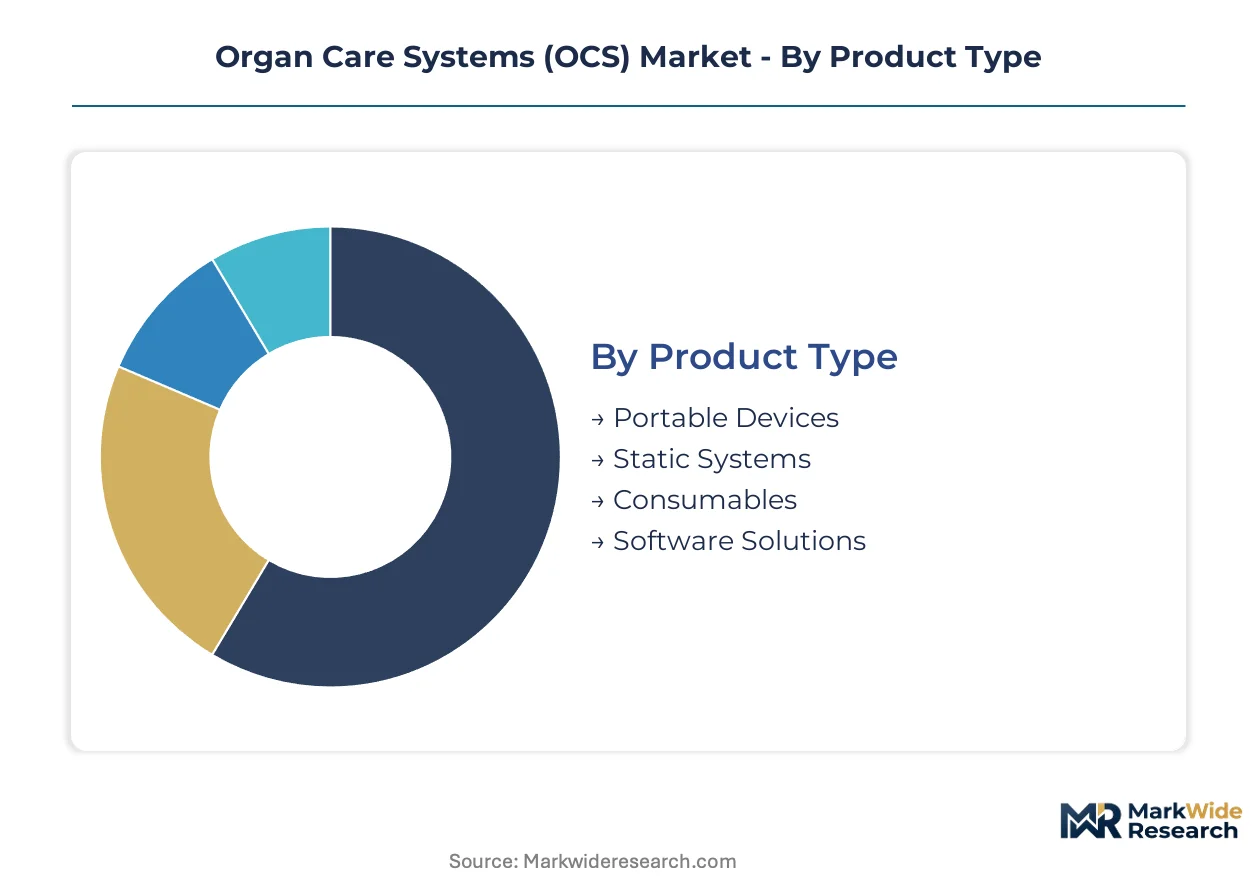
Segmentation in organ care systems reveals how procurement committees weight portability against infrastructure investment, and how clinical applications dictate technical specifications across perfusion platforms. Understanding these divides exposes where vendor lock-in risks concentrate and where multi-source qualification programs can unlock negotiating leverage.
Product Type:
Procurement committees prioritize total cost-of-ownership calculations that balance capital expenditure against recurring consumable commitments and workforce training requirements.
- Portable Devices:Electromechanical platforms designed for air ambulance compatibility and inter-hospital transport, featuring miniaturized pumps, battery power systems, and vibration-dampened enclosures. Demand concentrates in United States academic medical centers and German transplant networks where flight surgeons specify perfusion compatibility in rotorcraft procurement. Single-use circuit dependencies create vendor lock-in risks that committees now mitigate through multi-source qualification.
- Consumables:Single-use perfusion circuits, proprietary solution cartridges, and oxygenator modules that generate recurring revenue streams independent of device placement volume. Transplant centers in the United Kingdom and United States face premium pricing that strains operating budgets, driving consolidated procurement negotiations.
- Static Systems:Hospital-based normothermic perfusion platforms with expanded monitoring capabilities and extended preservation durations for marginal organ assessment.
- Software Solutions:Cloud-connected telemetry and electronic health record integration modules enabling centralized multi-site oversight.
Volume sits with Consumables; growth tilts toward Software Solutions.
Application:
Organ-specific perfusion requirements create divergent engineering priorities around pulsatile flow patterns, oxygenation parameters, and metabolic monitoring sensitivity.
- Cardiac:Pulsatile perfusion systems maintaining coronary perfusion pressure and electrophysiological stability during transport, with specialized pressure-sensing catheters and defibrillation readiness. United States transplant networks report highest utilization for extended criteria donor hearts where functional assessment precedes implantation.
- Hepatic:Normothermic platforms enabling bile production monitoring and synthetic function assessment, critical for marginal liver utilization. German and French transplant programs lead adoption following EU MDR post-market surveillance requirements for recipient outcome documentation.
- Renal:Hypothermic-to-normothermic hybrid systems addressing donor organ heterogeneity through dual-mode temperature management.
- Pulmonary:Ventilated ex-vivo lung perfusion with recruitment maneuver capabilities and gas exchange assessment.
Cardiac commands procurement volume; hepatic applications are climbing the fastest.
End User:
Facility type determines capital allocation authority, regulatory compliance burden, and integration complexity with existing transplant workflows.
- Transplant Centers:Specialized surgical programs with direct organ procurement organization relationships, bundled reimbursement negotiations, and perfusionist workforce retention challenges. United States academic medical centers consolidate vendor relationships around integrated service contracts with multi-year volume commitments.
- Hospitals:General medical centers expanding transplant capabilities through technology partnerships, facing interoperability standards absence that forces costly custom electronic health record integration projects.
- Research Institutions:Preclinical validation sites for novel perfusion protocols and extended preservation duration studies.
- Biopharmaceutical Companies:Drug-device combination development programs utilizing perfusion platforms for organ-targeted therapeutic delivery research.
Transplant Centers dominate installed base; Research Institutions show steepest expansion trajectory.
Delivery Mode:
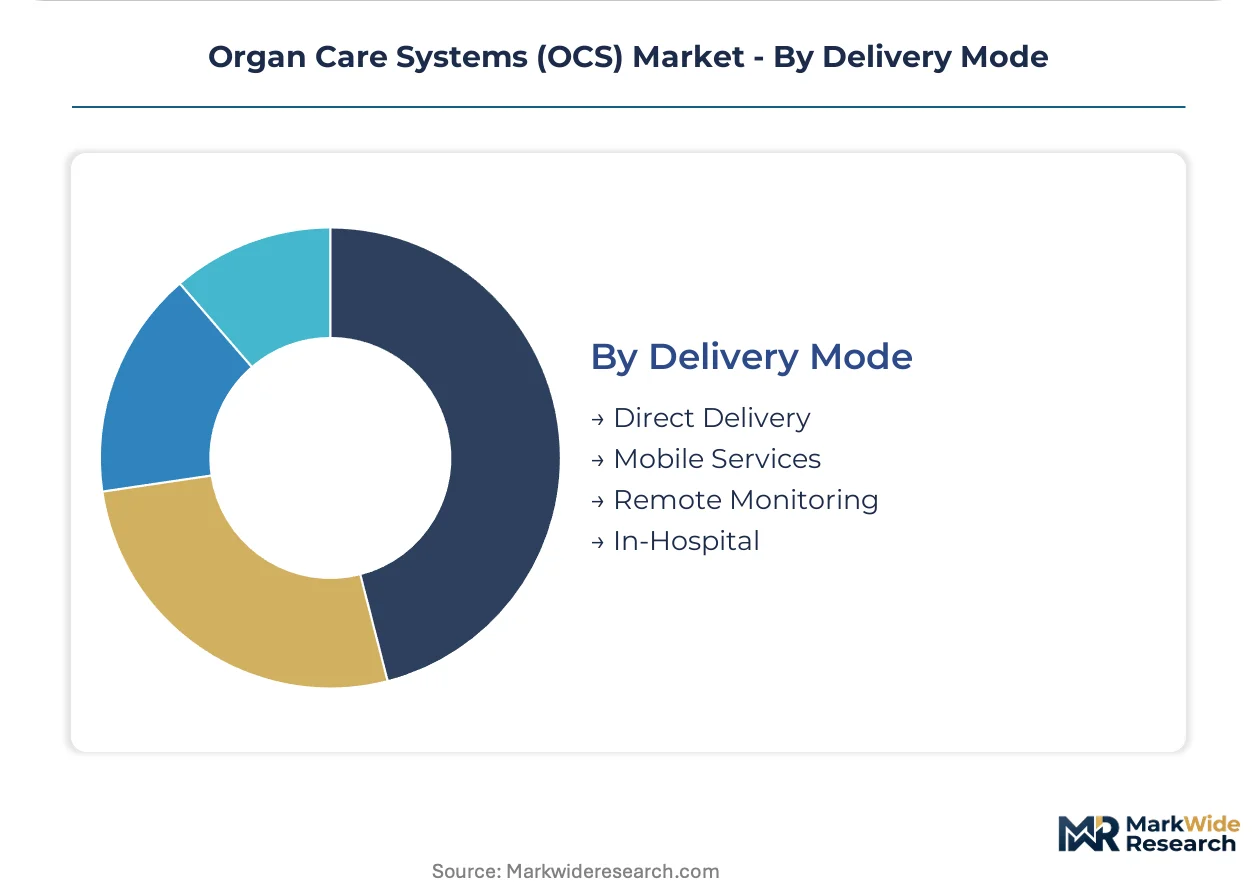
Service configuration choices reflect geographic dispersion of donor pools, fleet retrofitting capital requirements, and centralized versus distributed clinical oversight preferences.
- Mobile Services:Third-party perfusion teams deploying with portable devices to donor hospitals, enabling organ resuscitation prior to transport. Air ambulance operators in Germany and the United Kingdom specify equipment compatibility in fleet procurement, avoiding capital-intensive vehicle retrofitting for transplant centers.
- Direct Delivery:Manufacturer-coordinated logistics for consumable replenishment and device placement, anchoring high-volume accounts through integrated service contracts.
- Remote Monitoring:Cloud-connected telemetry enabling centralized oversight of multi-site organ transport operations.
- In-Hospital:Static platform operation within transplant center perfusion suites for marginal organ assessment and recipient matching.
Direct Delivery captures current volume; Remote Monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transplant procurement organizations in the United States, Germany, and the United Kingdom command the highest machine perfusion procurement budgets, while emerging transplant networks in India and Japan represent the fastest-expanding addressable markets for portable platform vendors.
United States
FDA Breakthrough Device Designations accelerate commercialization timelines for novel perfusion technologies. Academic medical centers in Massachusetts and California consolidate vendor relationships through multi-year integrated service contracts. Air ambulance operators specify portable perfusion compatibility in rotorcraft fleet procurement specifications.
Germany
EU MDR Class III certification requirements impose extended clinical validation timelines on normothermic system manufacturers. The country's national transplant authority evaluates bundled reimbursement frameworks for machine perfusion costs. Transplant networks in Bavaria and North Rhine-Westphalia lead European adoption of extended criteria donor resuscitation protocols.
United Kingdom
MHRA post-market surveillance protocols demand recipient outcome documentation alongside device approval. NHS England procurement committees negotiate consolidated consumable supply agreements to mitigate single-use circuit cost pressures. Liver transplant programs in London and Birmingham deploy normothermic platforms for marginal organ assessment.
India
The national organ allocation network expansion creates first-mover positioning for portable perfusion vendors. CDSCO medical device registration pathways require quality management system audits for imported electromechanical platforms. Regional transplant centers in Maharashtra and Tamil Nadu pursue technology partnerships for infrastructure buildout.
Japan
PMDA premarket approval frameworks emphasize clinical evidence standards for novel preservation technologies. METI industrial policy supports domestic medical device manufacturing capabilities. Transplant centers in the Kanto and Kansai regions evaluate portable platforms for inter-hospital organ transport networks.
Organ Care Systems (OCS) Market Competitive Landscape
Integrated service contracting dominates the current landscape as vendors anchor high-volume accounts through multi-year agreements bundling device placement, consumable supply, and technical support. The vendor base stratifies between integrated platform developers, specialized preservation device manufacturers, and consumable suppliers. Three strategic archetypes emerge: full-stack perfusion platform vendors, organ-specific technology specialists, and third-party logistics coordinators. M&A activity concentrates on consumable supply chain consolidation, while technology licensing agreements proliferate around remote monitoring software modules.
Among North American platform developers, TransMedics exemplifies the integrated service contract archetype through its anchoring of academic medical center accounts. Paragonix Technologies Inc represents the organ-specific specialist positioning with temperature-controlled cardiac transport devices. OrganOx Limited occupies the normothermic liver perfusion leadership tier through extended criteria donor resuscitation capabilities. These three companies illustrate how vendor lock-in risks concentrate around proprietary consumable dependencies, driving procurement committees toward multi-source qualification programs.
| Leading Market Players |
|---|
| TransMedics |
| Paragonix Technologies Inc |
| OrganOx Limited |
| Xvivo Perfusion AB |
| Bridge to Life Ltd |
| Organ Recovery Systems Inc |
| Waters Medical Systems LLC |
| Preservation Solutions Inc |
| Organ Assist BV |
| Others |
Value Network & Pricing Analysis
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing power for normothermic perfusion device manufacturers, forcing transplant centers to absorb elevated compliance costs through bundled procurement contracts or risk exclusion from high-margin service tiers.
Pricing Analysis
The volume-vs-margin split in organ care systems favors consumables over hardware, with single-use perfusion circuits and proprietary solution cartridges generating recurring revenue independent of transplantation volume. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Breakthrough Device designation status, EU MDR certification tier, and after-sales service bundling intensity. Cost compression in standard-tier portable devices is intensifying because procurement committees consolidate vendor relationships around integrated service contracts. Academic medical centers in the United States exhibit lowest price sensitivity due to bundled reimbursement negotiations, while regional transplant centers in emerging markets face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with specialized oxygenator membrane suppliers concentrated in Germany and the United States, where proprietary polymer formulations anchor device performance claims. Electromechanical pump assemblies, battery power systems, and sensor-embedded monitoring modules draw from precision manufacturing clusters in Japan and Switzerland. Tariff exposure on medical-grade polymers and semiconductor components threatens margin stability for portable platform vendors. Distribution runs through manufacturer-coordinated direct delivery networks that anchor high-volume accounts through multi-year consumable supply commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR Class III certification burdens and perfusionist workforce scarcity force subscale competitors toward exit or acquisition.
For Market Incumbents: Anchor high-volume accounts through integrated service contracts bundling device placement, consumable supply, and technical support to defend against emerging hybrid hypothermic-normothermic platform developers. Deepen backward integration into proprietary oxygenator membrane production to reduce single-source supplier dependency and capture margin pools currently leaking to German and US polymer specialists. For New Entrants and Emerging Players: Begin with remote monitoring software modules that integrate with hospital electronic health record systems, exploiting interoperability standards absence that forces costly custom integration projects for established hardware vendors. India's national organ allocation network expansion offers the most penetrable geography, where CDSCO registration pathways favor technology partnerships over direct device importation. For Investors and Strategic Acquirers: FDA Breakthrough Device Designation awards to novel perfusion technologies are the leading indicator that conditional coverage agreements with transplant procurement organizations will accelerate commercialization timelines and validate platform economics. Target acquisition candidates with EU MDR quality management system infrastructure already deployed, as notified body capacity constraints extend review timelines for de novo entrants. Watch for consolidation signals in consumable supply chain roll-ups as vendors seek captive supply of single-use circuits.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses development-to-commercialization timelines for novel perfusion platforms. |
| EU MDR Class III Certification | Extended clinical validation requirements delay market entry and elevate compliance costs for manufacturers. |
| Hospital System Partnership | Integrated service contracts with academic medical centers lock in multi-year volume commitments. |
| Software Companion Development | Cloud-connected telemetry modules enable centralized oversight of multi-site organ transport operations. |
| Reimbursement Strategy | National transplant authority bundled funding decisions determine machine perfusion cost recovery. |
Research Methodology
Document review covered FDA premarket notification filings, EU MDR technical documentation, and hospital procurement database records, complemented by interviews with transplant surgeons, perfusionists, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, notified body approval registries, and air ambulance operator equipment procurement specifications. Bottom-up installed base modeling and top-down addressable market sizing were triangulated against transplant volume projections.
Segment-level revenue and unit forecasts across the projection horizon incorporated product type, application, end user, and delivery mode dimensions, with organ-specific perfusion requirements modeled as a cross-cutting technical variable. CAGRs were derived from trend extrapolation of historical procurement patterns and scenario-weighted regulatory timeline assumptions. Forecast inputs included EU MDR notified body capacity constraints, perfusionist training program graduation rates, and air ambulance fleet retrofitting cycles.
Underlying measurement precision varies by segment; consumables and software solutions carry tighter precision than emerging hybrid device categories due to established procurement reporting. Forecasts reflect assumptions about regulatory approval timelines, reimbursement policy continuity, and workforce expansion rates. Deviation in EU MDR post-market surveillance enforcement intensity or FDA breakthrough designation criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Airway Management Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Global Ileostomy Market