
 Sweden Data Center Server Market | 2026-2036
Sweden Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Server Market Insights
Hyperscale cloud services is broadening its share of Sweden's data center server procurement. Dell Technologies anchors Nordic enterprise contracts through direct sales channels and localized support infrastructure. Hewlett Packard Enterprise differentiates with composable infrastructure platforms targeting AI training workloads. Supermicro competes on power-density engineering for facilities constrained by Sweden's renewable energy grid capacity.
Data center servers are high-performance computing systems engineered for continuous operation in controlled environments, typically rated between 500W and 2000W and housed in standardized 19-inch rack enclosures. These systems process, store, and distribute digital workloads across enterprise networks and internet-facing services. Rack servers occupy the dominant volume position among Swedish deployments due to their compatibility with existing raised-floor facilities. Liquid cooling segments are gaining traction as Stockholm-area data centers approach thermal limits of conventional air handling. Blade server configurations retain relevance in telecommunications central offices where space efficiency outweighs per-unit cost premiums.
Swedish data center construction falls under Boverket building codes and EU Energy Efficiency Directive standards, while electrical installations require Elsäkerhetsverket certification for grid interconnection. The EU Green Deal and national fossil-free electricity targets shape procurement specifications toward servers with verified power usage effectiveness ratings. Stakeholders must monitor how forthcoming EU AI Act infrastructure requirements intersect with existing F-Gas Regulation constraints on cooling system refrigerants.
Market Dynamics
Swedish data center operators face mounting pressure from the EU Green Deal's energy efficiency mandates, which compel server procurement teams to prioritize verified power usage effectiveness ratings over upfront capital costs.
Growth Catalysts
- EU Green Deal implementation:Boverket building codes and EU Energy Efficiency Directive standards mandate fossil-free electricity targets, driving replacement cycles toward certified efficient infrastructure.
- Real-time financial transaction processing:Swedish banks are expanding server deployments to support instant payment settlement systems required by the European Payments Council.
- Hyperscale facility concentration:Stockholm's metropolitan cluster anchors Nordic digital infrastructure, attracting cloud providers seeking proximity to renewable energy grids.
Market Restraints
- Grid interconnection bottlenecks:Elsäkerhetsverket certification requirements for electrical installations create extended approval timelines for facility expansion.
- Liquid cooling supply concentration:Specialized heat exchanger manufacturing concentrates among German and Finnish suppliers, exposing Swedish operators to cross-border logistics friction.
- F-Gas Regulation constraints:EU restrictions on synthetic refrigerants limit cooling system options for facilities unable to transition to water-based thermal management.
Strategic Opportunities
- AI training workload specialization:Composable infrastructure platforms enable resource pooling for machine learning clusters, creating service differentiation in Stockholm-area facilities.
- Gothenburg secondary market emergence:Lower land costs and proximity to submarine cable landing stations attract edge computing deployments outside the capital region.
- EU AI Act infrastructure preparation:Early compliance with forthcoming compute transparency requirements positions Swedish operators for regulated AI hosting contracts.
Industry Challenges
- Thermal engineering skill scarcity:Liquid cooling system design and maintenance expertise remains concentrated among a narrow specialist workforce in the Nordic region.
- Legacy raised-floor retrofit complexity:Existing Stockholm facilities face structural constraints when adapting air-cooled environments for direct-to-chip cooling architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Server Market |
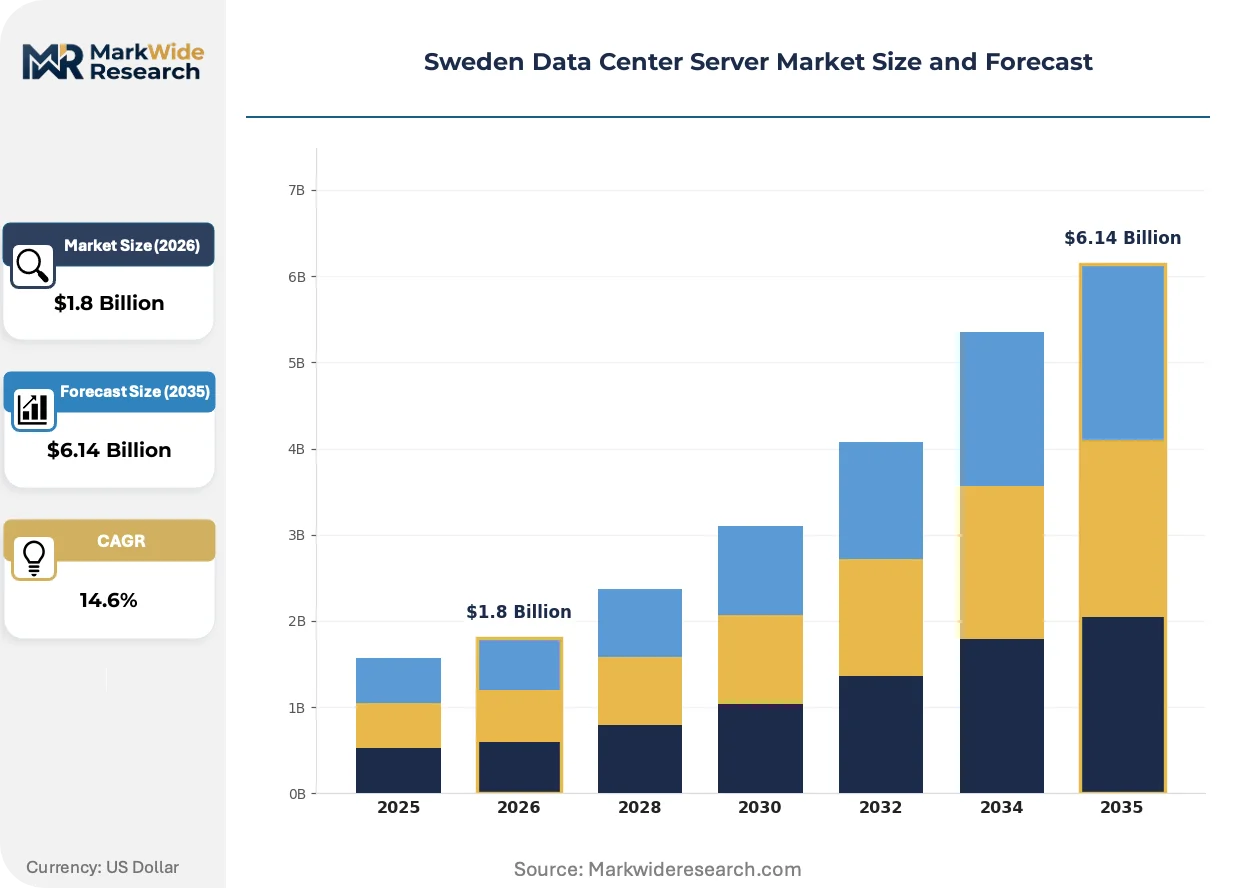
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Blade Servers, Rack Servers, Tower Servers, Micro Servers Power Rating: 500W, 1000W, 1500W, 2000W End User: Telecommunications, BFSI, Government, Healthcare Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling |
| Companies Covered | Cisco Systems, Supermicro, Dell Technologies, Huawei Technologies, Kingston Technology, Hewlett Packard Enterprise, Fujitsu, NVIDIA, Lenovo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Server Market Trends and Innovations
Swedish data center architecture is undergoing fundamental redesign as thermal density limits and regulatory pressure converge, forcing operators to reconsider every layer from server form factor to grid interconnection strategy.
Direct liquid cooling is overtaking conventional air handling in Stockholm-area hyperscale facilities. Cold plate and immersion systems transfer heat more efficiently than raised-floor air distribution. AtNorth and other Nordic operators are adopting these systems to maintain rack densities above 30kW without expanding physical footprints.
The EU AI Act's infrastructure transparency requirements are reshaping procurement documentation. Server purchasers must now track and report compute resource allocation for high-risk AI applications. Swedish financial services data centers are implementing asset-level monitoring to satisfy these disclosure obligations before enforcement begins.
Colocation buyers are consolidating vendor relationships and demanding integrated sustainability reporting. Single-source contracts covering hardware, power, and carbon accounting are displacing fragmented procurement across separate server, facility, and energy suppliers. This pattern is most pronounced among Stockholm-based fintech firms subject to ECB climate risk disclosure rules.
Sweden Data Center Server Market Segmentation
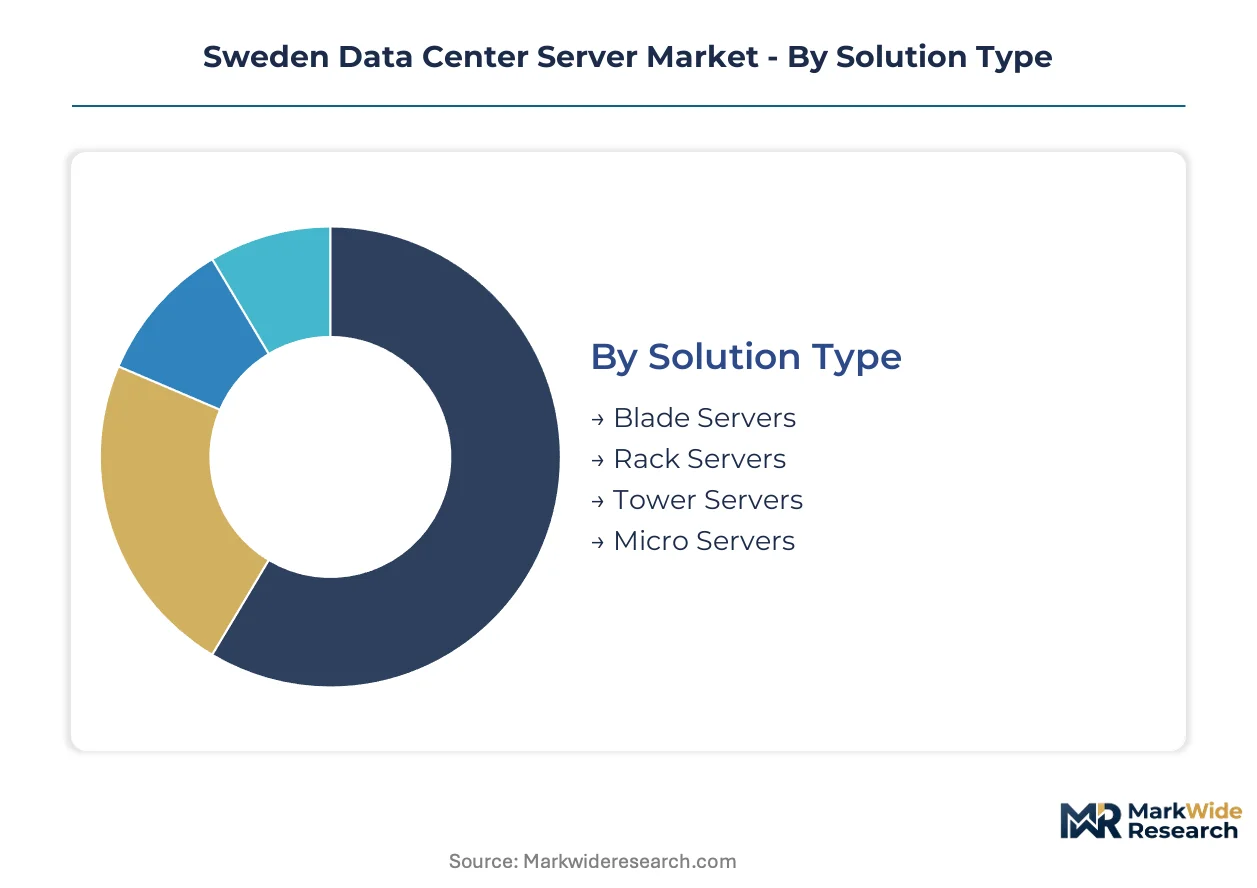
Server form factor selection in Sweden hinges on facility vintage and thermal density targets. Procurement teams weigh rack compatibility against power envelope constraints imposed by Stockholm's renewable grid capacity limits.
Solution Type:
Standalone rack configurations dominate legacy facility retrofits, while blade and micro variants embed into integrated infrastructure stacks for greenfield hyperscale builds.
- Rack Servers:Standardized 19-inch enclosures rated 500W to 2000W accommodate the majority of Swedish enterprise workloads. Stockholm metropolitan facilities specify these units for compatibility with raised-floor air distribution systems and Elsäkerhetsverket-certified electrical infrastructure.
- Blade Servers:High-density modular chassis consolidate compute, storage, and networking into shared power and cooling backplanes. Swedish telecommunications central offices favor blade configurations where physical footprint constraints outweigh per-unit cost premiums in urban colocation environments.
- Tower Servers:Vertical standalone enclosures suit edge computing deployments and small-scale government installations outside Stockholm's hyperscale cluster. Boverket building code compliance is simpler for these lower-power units in retrofit scenarios.
- Micro Servers:Ultra-compact single-socket systems target distributed processing nodes and lightweight virtualization workloads. Gothenburg-area edge facilities deploy micro servers for submarine cable landing station interconnection points.
Rack servers lead volumes today; liquid-cooled rack variants are gaining share fastest.
Power Rating:
Procurement patterns split between conservative 500W-1000W units for legacy air-cooled facilities and 1500W-2000W systems for direct liquid cooling deployments.
- 500W:Entry-level dual-socket configurations serve Swedish government data centers with strict Boverket energy efficiency certification requirements and limited rack density needs.
- 1000W:Mid-range enterprise workhorses balance performance against Stockholm grid interconnection constraints. BFSI institutions standardize on this envelope for real-time transaction processing clusters.
- 1500W:High-performance nodes with GPU acceleration support AI training workloads. AtNorth and other Nordic operators specify 1500W units for cold plate liquid cooling integration.
- 2000W:Maximum-density servers enable 30kW-plus rack configurations. These units require immersion or direct-to-chip cooling unavailable in legacy Swedish facilities without structural retrofit.
1000W ratings anchor procurement volumes; 1500W configurations are climbing the fastest as AI workload density rises.
End User:
Demand concentration varies by regulatory exposure and latency sensitivity across Swedish digital infrastructure.
- BFSI:Swedish banks deploy high-availability clusters for instant payment settlement systems mandated by the European Payments Council. EU AI Act transparency requirements are reshaping procurement documentation for algorithmic trading infrastructure.
- Telecommunications:Telia and other carriers centralize network function virtualization on blade server platforms. Central office consolidation drives demand for space-optimized form factors in Stockholm, Gothenburg, and Malmö metro areas.
- Government:National agencies prioritize Boverket-certified efficient infrastructure under EU Green Deal procurement guidelines. Data sovereignty requirements favor domestic colocation over hyperscale cloud for sensitive workloads.
- Healthcare:Regional health authorities process patient imaging and electronic records on air-cooled rack systems. GDPR compliance and ISO 27001 certification dominate vendor selection criteria.
BFSI leads current deployment volumes; telecommunications is expanding most quickly through 5G core network virtualization.
Cooling Technology:
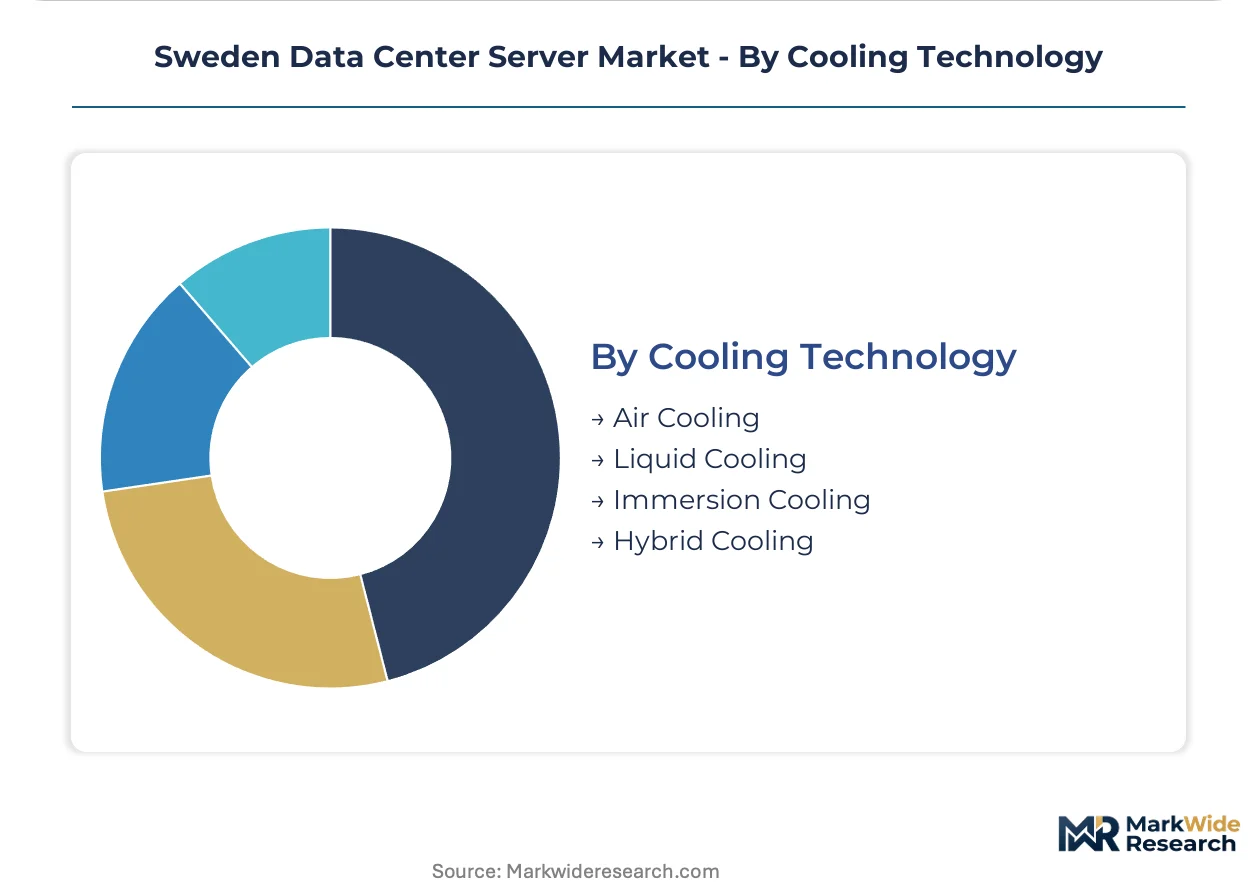
Thermal management selection determines facility expansion feasibility as Stockholm-area operators approach air handling capacity limits.
- Liquid Cooling:Cold plate and pumped refrigerant systems transfer heat directly from processors to facility water loops. AtNorth's Stockholm facilities deploy liquid cooling to maintain rack densities above 30kW within existing physical footprints.
- Air Cooling:Conventional raised-floor distribution remains prevalent in legacy Swedish data centers. Boverket energy efficiency codes are accelerating replacement cycles toward more efficient air handling units.
- Immersion Cooling:Dielectric fluid submersion enables maximum power density for AI training clusters. F-Gas Regulation constraints on synthetic refrigerants are driving interest in water-based immersion alternatives.
- Hybrid Cooling:Combined air and liquid systems optimize for mixed workload environments. Swedish operators pilot hybrid architectures during phased transitions from air-cooled legacy infrastructure.
Air cooling retains volume leadership; liquid cooling is gaining share fastest as thermal density thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center server procurement patterns shift across Nordic geographies based on renewable energy availability, submarine cable connectivity, and national regulatory implementation timelines for EU directives.
Sweden
Stockholm's metropolitan cluster anchors Nordic hyperscale capacity with proximity to fossil-free electricity grids and Elsäkerhetsverket-certified interconnection infrastructure. Boverket building codes enforce strict energy efficiency standards under the EU Green Deal. AtNorth and other operators deploy liquid-cooled rack systems above 30kW density in Stockholm-area facilities.
Norway
Abundant hydroelectric capacity attracts power-intensive AI training workloads seeking carbon-neutral compute. The Norwegian Water Resources and Energy Directorate regulates grid access for data center developments. Oslo and Stavanger harbor zones concentrate submarine cable landing stations linking Nordic infrastructure to continental Europe.
Finland
Helsinki metropolitan data centers leverage district heating integration to monetize waste heat from server operations. Finnish Safety and Chemicals Agency oversees F-Gas Regulation compliance for cooling system deployments. Espoo and Vantaa suburbs host Microsoft and Google hyperscale campuses serving Eastern European latency requirements.
Denmark
Copenhagen's proximity to continental European fiber routes positions Danish facilities as edge computing gateways. Danish Energy Agency permitting processes prioritize renewable grid interconnection for new data center construction. Odense and Aarhus secondary markets emerge for distributed processing nodes outside capital region constraints.
Iceland
Geothermal and hydroelectric resources enable Iceland to offer among Europe's lowest carbon intensity electricity for server operations. National Energy Authority certifies power purchase agreements for international operators seeking verified renewable sourcing. Reykjanes Peninsula concentrates submarine cable infrastructure connecting to North America and Europe.
Sweden Data Center Server Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated infrastructure vendors commanding premium positioning in hyperscale procurement while component suppliers capture volume through server builder relationships. The vendor landscape organizes around three archetypes: full-stack infrastructure platforms, power-density engineering specialists, and memory and acceleration component suppliers. Competitive maneuvering concentrates on sustainability certification differentiation and liquid cooling system integration partnerships.
Within the full-stack infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions representing integrated platform approaches, while Supermicro exemplifies power-density specialization for thermal-constrained deployments. Cisco Systems anchors networking-integrated server architectures. These named entities sit within broader competitive dynamics where Nordic procurement teams prioritize verified power usage effectiveness ratings and localized support infrastructure over pure hardware specifications.
| Leading Market Players |
|---|
| Cisco Systems |
| Supermicro |
| Dell Technologies |
| Huawei Technologies |
| Kingston Technology |
| Hewlett Packard Enterprise |
| Fujitsu |
| NVIDIA |
| Lenovo |
| Others |
Pricing and Supply Chain Analysis
Direct liquid cooling adoption in Stockholm-area facilities simultaneously compresses operational expenditure curves and concentrates procurement leverage among Nordic thermal engineering specialists. This technology transition reshapes supplier-buyer power dynamics as specialized heat exchanger vendors capture margin pools previously distributed across conventional air-handling equipment distributors.
Pricing Analysis
Distributor markups on rack server configurations compress under direct-to-OEM volume contracting by hyperscale operators. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers differentiates on verified power usage effectiveness ratings and Elsäkerhetsverket certification bundling. Cost compression in the standard tier intensifies because BFSI procurement teams consolidate vendor relationships for integrated sustainability reporting. Government data centers exhibit highest price sensitivity due to Boverket-mandated efficiency thresholds, while AI training clusters prioritize density performance over unit economics.
Supply Chain Analysis
Advanced processor supply rests on Taiwanese foundry capacity and South Korean memory fabrication, with Swedish operators sourcing specialized cold plate assemblies from German and Finnish thermal component specialists. Critical dependencies span high-bandwidth memory modules, GPU accelerators, and precision-machined copper heat spreaders. Single-source vulnerability concentrates in immersion cooling dielectric fluids subject to EU F-Gas Regulation phase-down schedules. Distribution runs through Nordic value-added resellers with localized Elsäkerhetsverket compliance support, bypassing traditional broadline electronics distributors for enterprise-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden data center server market compounds steadily as EU Green Deal mandates force replacement cycles toward certified efficient infrastructure regardless of macroeconomic cycles.
For Market Incumbents: Anchor defensive positioning through backward integration into liquid cooling system design capabilities, countering margin erosion from specialized thermal engineering vendors. Consolidate channel control by acquiring Nordic value-added resellers with established Elsäkerhetsverket certification relationships. Prioritize R&D investment in direct-to-chip cooling architectures compatible with legacy raised-floor retrofit scenarios. For New Entrants and Emerging Players: Regional health authorities outside Stockholm's hyperscale cluster represent an underserved buyer archetype with unmet demand for Boverket-compliant air-cooled rack systems with simplified compliance documentation. Gothenburg-area edge computing deployments offer penetrable geographic white space with lower incumbent concentration. Pursue go-to-market positioning through submarine cable landing station operators seeking integrated micro server and networking infrastructure bundles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale colocation operators with stranded air-cooled capacity and underutilized Elsäkerhetsverket-certified grid interconnection rights. Long-term viability hinges on thermal engineering talent acquisition and liquid cooling transition execution rather than pure real estate positioning. Monitor EU AI Act infrastructure transparency requirement enforcement timelines as the critical inflection signal for regulated AI hosting contract availability.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling System Integration | Enables AtNorth and Nordic operators to maintain 30kW-plus rack densities within Stockholm's constrained physical footprints. |
| EU AI Act Compliance Preparation | Positions Swedish operators for algorithmic trading and high-risk AI hosting contracts before transparency enforcement begins. |
| Backward Integration into Thermal Engineering | Captures margin pools from German and Finnish heat exchanger suppliers while reducing cross-border logistics exposure. |
| Gothenburg Edge Facility Expansion | Leverages submarine cable landing station proximity for distributed processing nodes outside capital region land cost constraints. |
| Sustainability Reporting Consolidation | Meets ECB climate risk disclosure rules for Stockholm-based fintech through single-source hardware-power-carbon contracts. |
Research Methodology
Direct dialogue with data center facility directors, server procurement officers at Swedish banks, thermal engineering specialists, and Elsäkerhetsverket certification consultants grounded qualitative assessment. Secondary validation drew from Boverket building code filings, EU Energy Efficiency Directive implementation reports, European Payments Council instant settlement infrastructure disclosures, and hyperscaler capital expenditure announcements. Bottom-up server shipment estimates by form factor and power rating triangulated against top-down facility capacity expansion tracking across the Stockholm metropolitan cluster.
Segment-level projections across rack, blade, tower, and micro server configurations incorporated power rating distributions, cooling technology adoption curves, and end-user procurement patterns. Modeled dimensions spanned solution type, power envelope, cooling architecture, and buyer vertical with regulatory exposure weighting. CAGRs derived from facility pipeline analysis, grid interconnection approval timelines, and replacement cycle acceleration under EU Green Deal mandates. AI training workload density assumptions and liquid cooling penetration rates served as key sensitivity inputs.
Underlying measurement precision varies by segment; hyperscale cloud provider deployments carry tighter precision than distributed government installations. Forecasts reflect documented assumptions regarding Elsäkerhetsverket certification timeline stability and F-Gas Regulation phase-down schedule adherence. Supply chain disruption from thermal component logistics friction or EU AI Act infrastructure requirement acceleration warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Israel Data Center Server Market