
 Data Center Monitoring Systems Market | 2026-2036
Data Center Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Monitoring Systems Market Outlook
India is tilting toward massive data center construction across Mumbai, Hyderabad, and Chennai, creating fresh demand for environmental and power monitoring infrastructure. Schneider Electric leverages its integrated hardware-software portfolio to anchor large-scale deployments across South Asian facilities. Cisco Systems Inc. competes through network-centric monitoring architectures that extend visibility into hybrid cloud environments. Siemens AG differentiates via digital twin platforms that simulate thermal behavior before physical commissioning.
Data center monitoring systems encompass sensor networks, software platforms, and analytics engines that track temperature, humidity, power usage effectiveness, and equipment health across facility layers. These systems typically operate through IP-connected sensor arrays sampling environmental parameters at intervals under one minute, with edge gateways preprocessing telemetry before cloud or on-premises aggregation. Software and integrated solutions capture the dominant margin pools as vendors bundle predictive analytics with hardware deployment. Hyperscale data centers represent the fastest-expanding end user category, driven by tenant SLA requirements and energy compliance obligations. IoT-enabled sensor fabrics and machine learning-based anomaly detection are displacing legacy threshold-alert architectures in new builds.
The EPA Energy Star program and OSHA electrical safety standards shape equipment specifications and installation protocols in the United States. India's BIS certification requirements and the EU Energy Efficiency Directive impose mandatory monitoring and reporting thresholds on facility operators. Stakeholders must weigh cloud-native versus on-premises deployment architectures as sovereignty requirements and latency constraints diverge across jurisdictions.
Market Dynamics
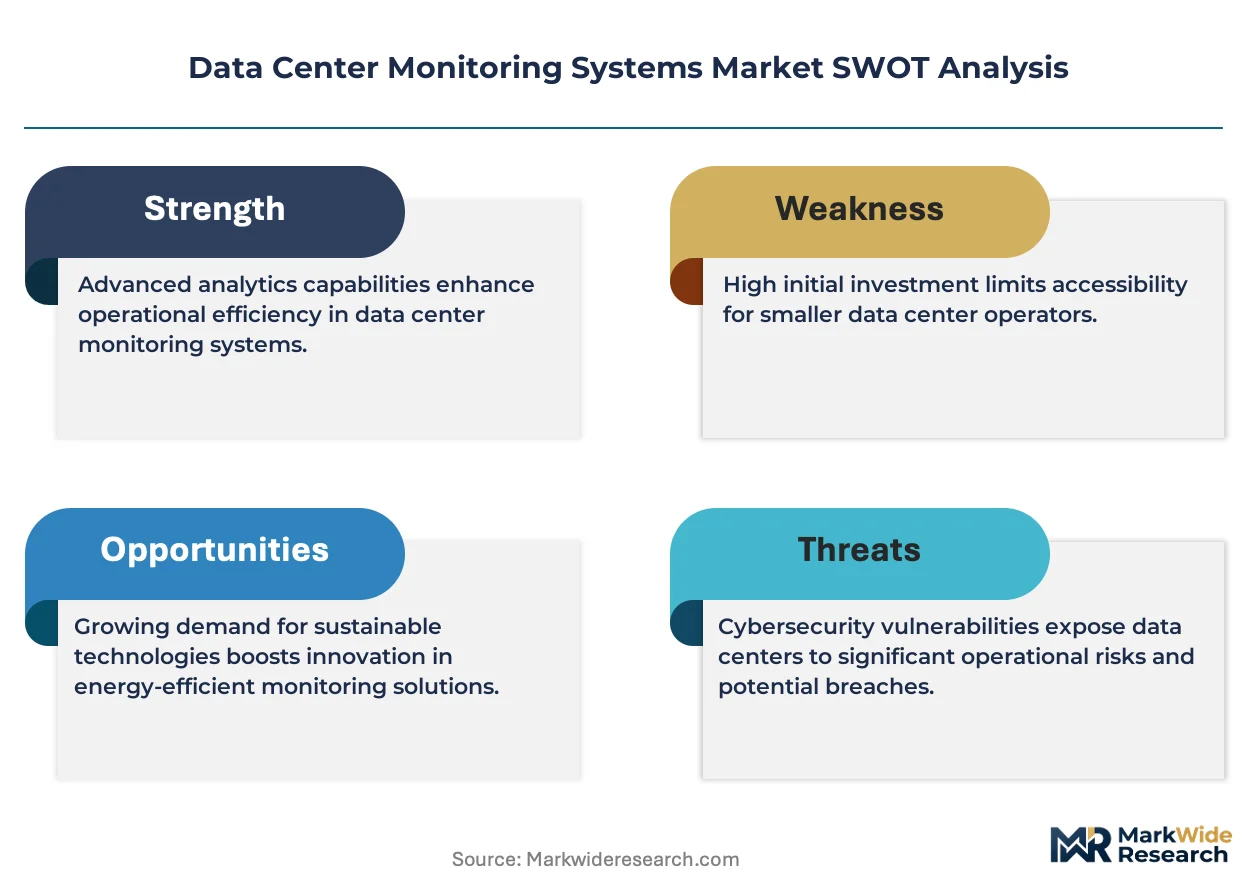
Hyperscale operators are consolidating monitoring infrastructure around AI-driven predictive platforms that compress mean-time-to-detection from hours to seconds, forcing legacy threshold-alert vendors to re-architect or exit.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates real-time power usage tracking across facilities exceeding 500kW capacity, compelling retrofits of legacy infrastructure in Germany, France, and the Netherlands.
- IoT sensor fabrics:Wireless mesh networks sampling environmental parameters at sub-minute intervals enable granular thermal mapping previously achievable only through wired installations.
- Cloud service provider SLAs:Tenant contracts now specify 99.999% uptime with financial penalties, driving hyperscale operators to deploy redundant monitoring layers across compute, power, and cooling stacks.
Market Restraints
- Semiconductor supply concentration:Edge gateway chipsets depend on TSMC and Samsung foundry capacity, exposing lead times to geopolitical friction in Taiwan and South Korea.
- Copper and rare earth price volatility:Sensor cabling and magnet components in power monitoring hardware face input cost swings that compress hardware margins.
- Legacy protocol fragmentation:BACnet, Modbus, and SNMP coexistence requirements extend integration timelines and inflate professional services costs for brownfield deployments.
Strategic Opportunities
- India data center construction:Mumbai, Hyderabad, and Chennai clusters lack mature monitoring infrastructure, creating first-mover advantage for integrated hardware-software vendors.
- Digital twin convergence:Physics simulation engines merging with live sensor feeds enable pre-commissioning thermal validation, reducing commissioning risk for hyperscale builds.
- OSHA electrical safety standards:Updated arc flash monitoring requirements in the United States mandate retrofit of power distribution monitoring, opening replacement cycles in aging facilities.
Industry Challenges
- Edge-to-cloud cybersecurity certification:IEC 62443 compliance timelines extend 12-18 months, delaying product launches and freezing procurement decisions at security-conscious buyers.
- Multivendor integration complexity:Facilities mixing Schneider, Siemens, and Cisco hardware require custom middleware development, inflating deployment costs and post-sale support burdens.
- Thermal engineering talent scarcity:Computational fluid dynamics expertise for digital twin calibration concentrates among aerospace and automotive veterans, commanding premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Monitoring Systems Market |
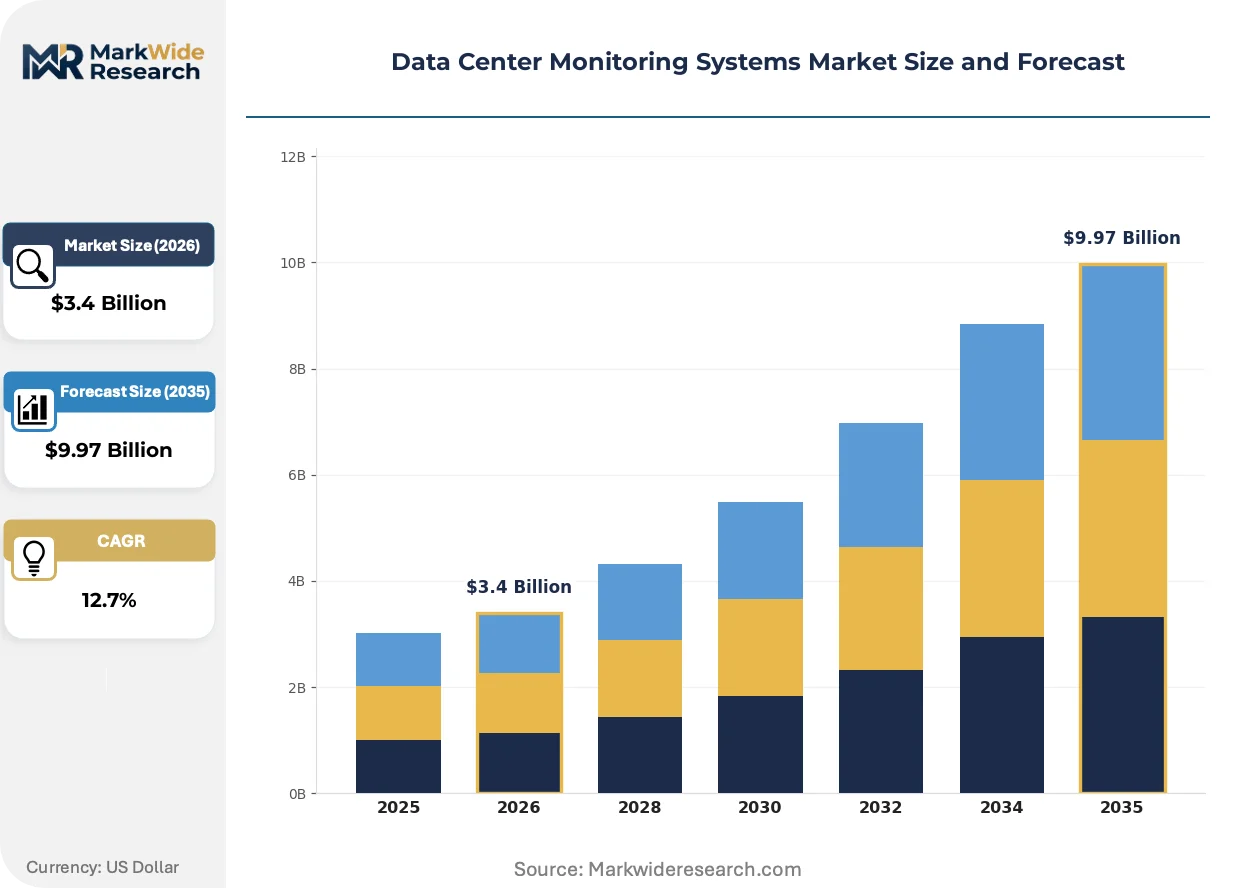
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Solutions, Services Technology: IoT, Artificial Intelligence, Machine Learning, Cloud Computing End User: Enterprise, Colocation Providers, Hyperscale Data Centers, Edge Data Centers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Schneider Electric, Cisco Systems Inc., ABB, Siemens AG, Eaton, SolarWinds Worldwide LLC, Panduit Corp, Hewlett-Packard Enterprise, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Monitoring Systems Market Strategic Shifts
Machine learning inference at the edge is compressing response latency and enabling autonomous control loops that bypass human intervention for routine thermal adjustments.
Neural network-based anomaly detection trained on facility-specific thermal signatures is rendering obsolete rule-based threshold alerting that floods operators with false positives during seasonal load variations. Hyperscale operators in Northern Virginia and Frankfurt are deploying these models within six-month rollout cycles. The shift is compressing vendor differentiation around algorithm accuracy rather than sensor hardware specifications.
The EU AI Act's risk classification framework for autonomous infrastructure management systems imposes documentation and audit requirements on predictive control algorithms. Facility operators must maintain model provenance records and human oversight protocols for safety-critical thermal decisions. German data center clusters are responding by segregating AI-driven recommendations from direct actuator control, adding manual approval gates that slow response times.
Colocation buyers are unbundling monitoring software from hardware procurement, demanding API-first platforms that aggregate multi-vendor telemetry into single-pane dashboards. This procurement pattern disrupts traditional bundled sales models and elevates pure-play analytics vendors. The behavior is most pronounced in Singapore and Amsterdam, where multi-tenant facilities prioritize tenant-visible transparency over vendor loyalty.
Data Center Monitoring Systems Market Segmentation
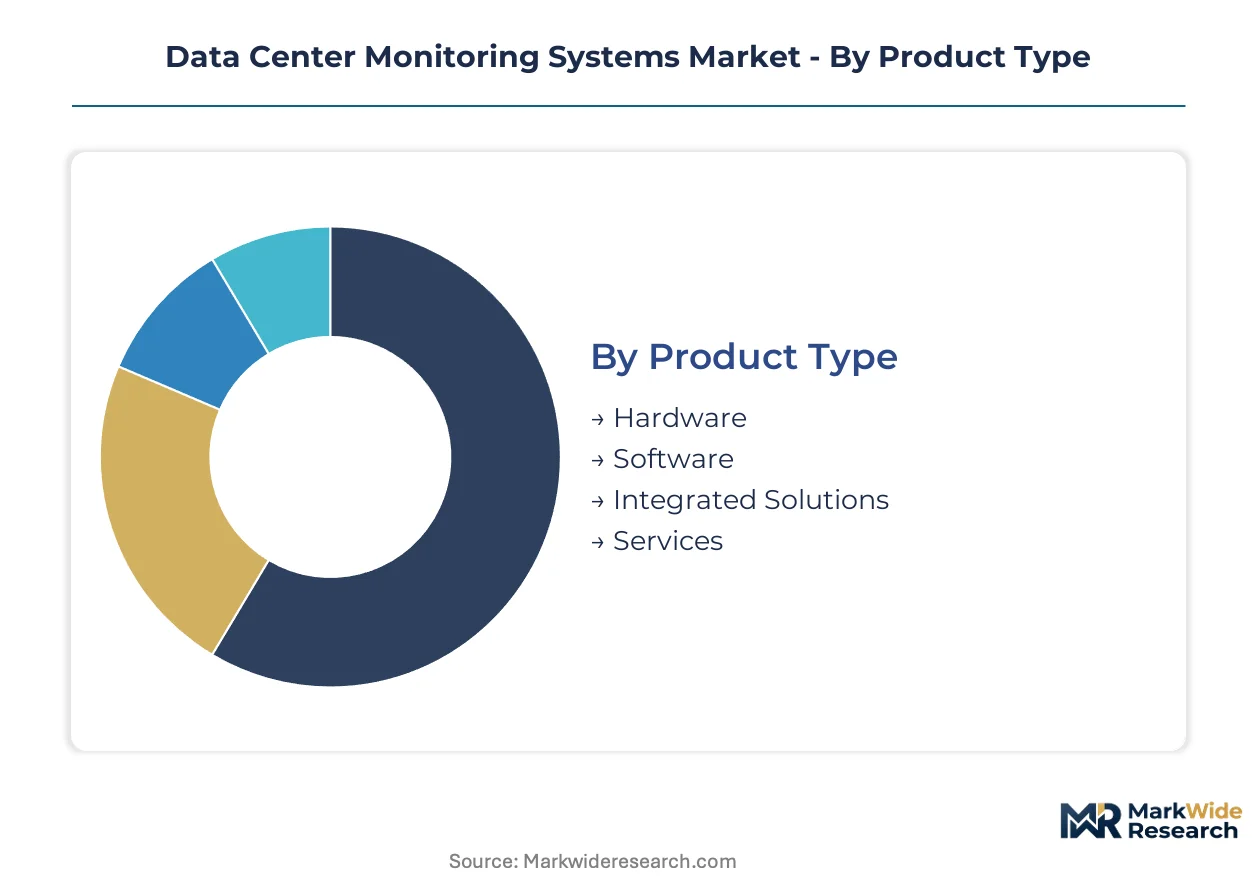
Data center monitoring systems fragment across four critical dimensions that determine procurement priorities, margin structures, and integration complexity. Product type governs upfront capital allocation and recurring revenue potential. Technology selection dictates response latency and predictive capability. End user scale shapes redundancy requirements and compliance intensity. Deployment architecture determines sovereignty compliance and operational control.
Product Type:
Cost tier stratification separates capital-intensive hardware from high-margin software and bundled service offerings.
- Hardware:Sensor arrays, edge gateways, and power distribution monitoring units form the physical telemetry layer. Hyperscale operators in Northern Virginia and Frankfurt are standardizing on IP-connected environmental sensors sampling at sub-minute intervals to meet EU Energy Efficiency Directive mandates.
- Software:Analytics platforms, visualization dashboards, and predictive algorithms command premium pricing through subscription models. Demand concentrates among colocation providers in Singapore and Amsterdam seeking API-first aggregation of multi-vendor telemetry into single-pane tenant visibility.
- Integrated Solutions:Bundled hardware-software packages reduce procurement friction for greenfield deployments. These packages dominate new construction in Mumbai, Hyderabad, and Chennai where mature vendor relationships accelerate commissioning timelines.
- Services:Professional implementation, calibration, and ongoing managed monitoring support brownfield retrofits. Services revenue expands where legacy protocol fragmentation—BACnet, Modbus, SNMP coexistence—extends integration complexity.
Hardware holds installed capacity. Software is rotating up the share rankings.
Technology:
Maturity curves diverge sharply across the technology stack, with established sensor networking giving way to inference-heavy AI layers.
- IoT:Wireless mesh sensor fabrics enable granular thermal mapping without wired infrastructure costs. These deployments are climbing the fastest in hyperscale facilities across Germany, France, and the Netherlands where real-time power usage tracking is now mandatory.
- Artificial Intelligence:Neural network-based anomaly detection trained on facility-specific thermal signatures compresses mean-time-to-detection from hours to seconds. German operators are segregating AI recommendations from direct actuator control to comply with EU AI Act documentation requirements.
- Machine Learning:Edge inference models enable autonomous control loops that bypass human intervention for routine thermal adjustments. Edge ML adoption concentrates in Northern Virginia where tenant SLA penalties demand sub-second response.
- Cloud Computing:Cloud-native aggregation platforms support distributed visibility across hybrid infrastructure. Sovereignty requirements in India and latency constraints in financial services are tempering pure cloud deployment in favor of hybrid architectures.
IoT sensor networks represent the most mature technology layer. AI-driven predictive platforms are gaining share fastest as differentiation shifts from hardware specifications to algorithm accuracy.
End User:
Customer scale determines redundancy depth, compliance burden, and vendor negotiation leverage.
- Hyperscale Data Centers:Operators running multi-hundred-megawatt facilities deploy redundant monitoring layers across compute, power, and cooling stacks. These operators are consolidating around AI-driven predictive platforms and unbundling software from hardware procurement.
- Colocation Providers:Multi-tenant facilities prioritize tenant-visible transparency through API-first dashboards. Demand in Singapore and Amsterdam is driving pure-play analytics vendors to displace traditional bundled sales models.
- Enterprise:Corporate-owned facilities balance operational control against capital efficiency. These deployments favor hybrid architectures that retain sensitive telemetry on-premises while leveraging cloud analytics.
- Edge Data Centers:Distributed micro-facilities require lightweight monitoring with minimal on-site expertise. Edge deployments favor integrated solutions with remote managed services to offset staffing constraints.
Hyperscale operators command vendor attention. Edge data centers are climbing the priority rankings as distributed infrastructure accelerates.
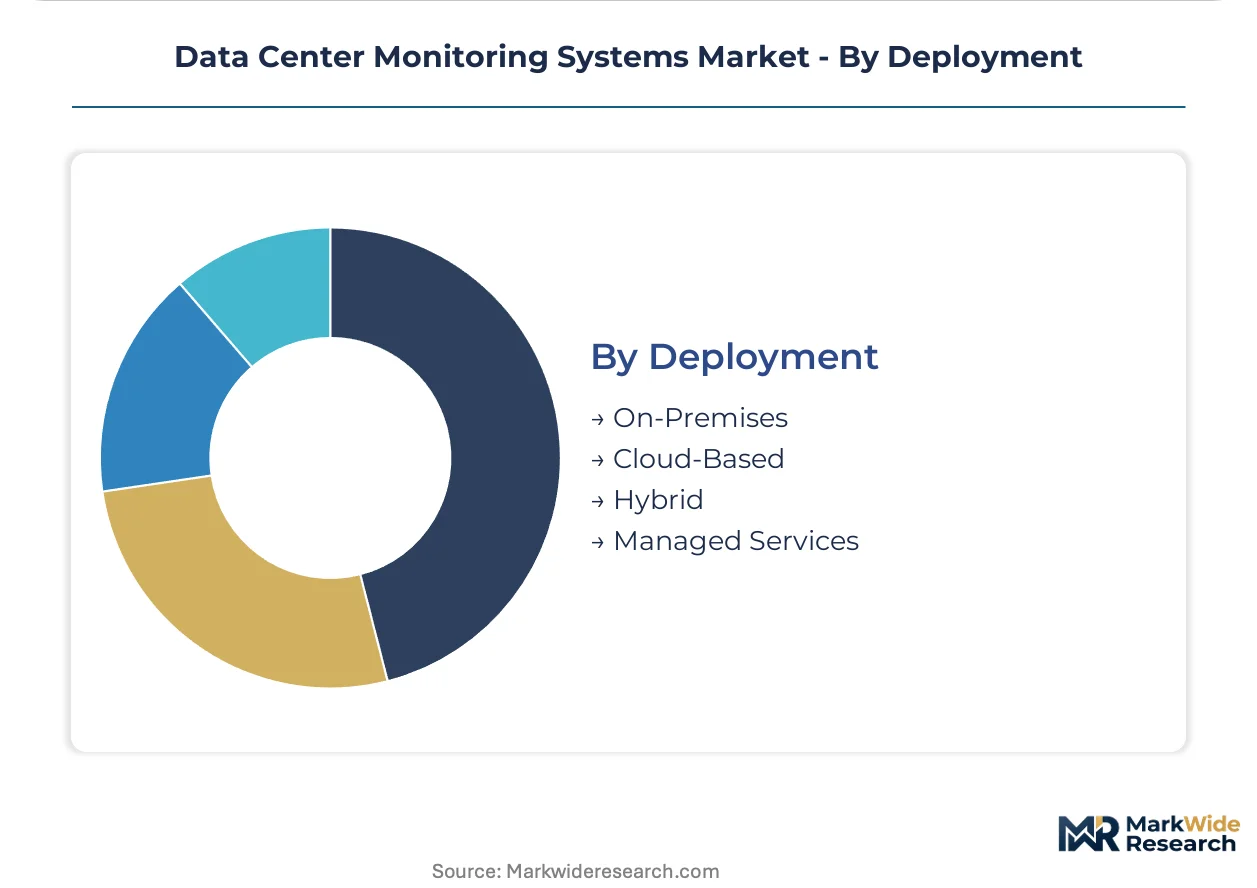
Deployment:
Architecture choice reflects the tension between operational sovereignty and scalability.
- On-Premises:Full local control over telemetry aggregation and model training. Financial services and defense contractors in the United States mandate on-premises deployment to satisfy data sovereignty and IEC 62443 cybersecurity certification timelines.
- Cloud-Based:Scalable compute for predictive analytics without capital infrastructure. Pure cloud deployment faces headwinds where latency constraints or national data localization laws—India's BIS certification requirements among them—mandate local processing.
- Hybrid:Edge preprocessing with cloud aggregation balances responsiveness and scale. Hybrid architectures are expanding most quickly in jurisdictions with divergent sovereignty and latency requirements.
- Managed Services:Third-party monitoring operations offload expertise requirements. These services attract edge data center operators and enterprises lacking internal thermal engineering talent.
On-premises retains share in regulated sectors. Hybrid deployment is rotating up the rankings as architectural flexibility becomes decisive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Energy Efficiency Directive anchors regulatory intensity across Germany, France, and the Netherlands, mandating real-time power usage tracking that drives hyperscale monitoring deployment. Facility operators in Frankfurt and Amsterdam retrofit legacy infrastructure to comply with sub-minute telemetry sampling requirements.
United States
Hyperscale construction in Northern Virginia and Dallas-Fort Worth generates concentrated demand for redundant monitoring layers across compute, power, and cooling stacks. OSHA electrical safety standards and the EPA Energy Star program shape equipment specifications and installation protocols. Phoenix and Silicon Valley clusters deploy edge inference models to satisfy tenant SLA penalties demanding sub-second thermal response.
Germany
Industrial data center density and regulatory stringency converge to create Europe's most demanding compliance environment for infrastructure tracking. The EU AI Act imposes documentation and audit requirements on predictive control algorithms, compelling German operators to segregate AI recommendations from direct actuator control. Frankfurt's hyperscale cluster responds by adding manual approval gates that slow response times while maintaining compliance.
India
Mumbai, Hyderabad, and Chennai clusters lack mature monitoring infrastructure, creating first-mover advantage for integrated hardware-software vendors. BIS certification requirements and national data localization laws mandate local processing, tempering pure cloud deployment in favor of hybrid architectures. Construction timelines accelerate as operators retrofit facilities to meet tenant expectations for 99.999% uptime guarantees.
Singapore
Multi-tenant colocation facilities prioritize tenant-visible transparency through API-first dashboards that aggregate multi-vendor telemetry. Procurement patterns here disrupt traditional bundled sales models and elevate pure-play analytics vendors. The city-state's position as a regional cloud hub drives demand for redundant monitoring layers capable of supporting financial services latency constraints.
Netherlands
Amsterdam's data center cluster faces EU Energy Efficiency Directive mandates requiring real-time power usage tracking across facilities exceeding 500kW capacity. Colocation buyers unbundle monitoring software from hardware procurement, demanding single-pane visibility across hybrid infrastructure. The country's advanced fiber connectivity supports edge-to-cloud architectures that balance sovereignty requirements with scalability.
Data Center Monitoring Systems Market Competitive Environment
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: integrated hardware-software bundlers commanding greenfield construction, network-centric platforms extending visibility into hybrid environments, and pure-play analytics vendors displacing traditional sales models. Strategic moves concentrate on portfolio diversification through predictive algorithm development and geographic expansion into underpenetrated construction clusters.
Among diversified industrial conglomerates, Schneider Electric and Siemens AG exemplify the integrated hardware-software archetype, while Cisco Systems Inc. occupies a position representing network-centric monitoring architectures. These three anchors demonstrate how vendor differentiation rotates from sensor hardware specifications toward algorithm accuracy and API-first platform design.
| Leading Market Players |
|---|
| Schneider Electric |
| Cisco Systems Inc. |
| ABB |
| Siemens AG |
| Eaton |
| SolarWinds Worldwide LLC |
| Panduit Corp |
| Hewlett-Packard Enterprise |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting Taiwan to Frankfurt and South Korea to Northern Virginia transmit semiconductor cost volatility directly into sensor hardware pricing, while hyperscale buyers in Germany and the United States extract volume discounts that compress margins for second-tier suppliers.
Pricing Analysis
Geographic price spreads of 15-25% separate German hyperscale deployments from Indian greenfield projects, reflecting divergent certification burdens and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithm sophistication and sensor density, with AI-enabled predictive platforms commanding subscription premiums. Cost compression in hardware tiers is intensifying because TSMC foundry capacity constraints extend edge gateway lead times. Colocation providers in Singapore and Amsterdam exhibit highest price sensitivity as they unbundle software from hardware procurement, while hyperscale operators in Northern Virginia prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for edge gateway chipsets concentrates at TSMC and Samsung foundries, with Foxconn and Jabil holding assembly capacity for sensor housings and power monitoring units. Component sourcing draws from Taiwan for semiconductors, China for rare earth magnets and sensor cabling, and Germany for precision thermal sensors. Single-source vulnerability in TSMC advanced node production exposes lead times to geopolitical friction. Distribution runs through direct vendor relationships for hyperscale accounts and regional systems integrators for mid-market enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center monitoring systems market represents a high-growth disruption as EU AI Act compliance mandates reshape competitive differentiation around algorithm documentation and human oversight protocols.
For Market Incumbents: Build predictive algorithm moats through facility-specific thermal signature training datasets that compound accuracy advantages. Incumbent vendors must secure IEC 62443 cybersecurity certification for edge-to-cloud architectures to defend against pure-play analytics vendors unbundling software from hardware. Capacity addition in Mumbai and Hyderabad accelerates commissioning timelines and anchors relationships with construction-phase buyers. For New Entrants and Emerging Players: Mid-market edge data centers in secondary Indian cities represent the most penetrable entry point, as these facilities lack internal thermal engineering talent and favor remote managed services. API-first platform positioning enables aggregation of multi-vendor telemetry without competing on sensor hardware specifications. Channel partnerships with regional systems integrators in Chennai and Hyderabad accelerate customer acquisition without direct sales infrastructure. For Investors and Strategic Acquirers: Specialist thermal engineering boutiques with computational fluid dynamics expertise and digital twin calibration capabilities offer acquisition targets as talent scarcity commands premium compensation. Long-term viability centers on algorithm accuracy differentiation displacing hardware specification competition. Monitor EU AI Act enforcement patterns in Frankfurt and Amsterdam for early signals of compliance cost escalation that favors consolidated vendors with dedicated regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures aggregate multi-vendor telemetry for colocation transparency demands in Singapore. |
| Acquisition of Specialist Firm | Thermal engineering boutiques with CFD expertise address talent scarcity in digital twin calibration. |
| Geographic Expansion | Mumbai, Hyderabad, and Chennai construction clusters lack mature monitoring infrastructure and vendor relationships. |
| Product Launch | Edge inference models enable autonomous thermal control loops for sub-second SLA compliance in Northern Virginia. |
| Strategic Partnership | Systems integrator alliances accelerate brownfield retrofit timelines where legacy protocol fragmentation inflates deployment costs. |
Study Parameters
A spread of perspectives from hyperscale facility operators, colocation procurement managers, thermal engineering consultants, and systems integration specialists converged on the working assumptions underpinning this analysis. Primary interviews with data center infrastructure executives, IT procurement officers at financial services firms, and edge facility operators combined with secondary validation against SEC filings from Schneider Electric and Cisco Systems, hyperscaler capex disclosures from Amazon and Microsoft, and EU regulatory documentation. Bottom-up sensor deployment estimates and top-down facility construction pipelines were triangulated to anchor volume assumptions.
Demand-supply balance framing shaped the analytical framework across the analysis window, with segmentation dimensions spanning deployment architecture, end user scale, technology maturity, and product type. CAGRs were derived from facility construction pipeline analysis and retrofit obligation tracking under EU Energy Efficiency Directive mandates. Forecast inputs incorporated hyperscale tenant SLA penalty structures and BIS certification timelines for Indian data center localization requirements.
Practitioners should monitor TSMC foundry capacity allocation, EU AI Act enforcement patterns, and copper price volatility for early signals of forecast revision. Quarterly review of hyperscale construction permitting in Northern Virginia and Frankfurt, alongside edge gateway chipset lead time indicators, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Italy Data Center Server Market