
 Italy Data Center Server Market | 2026-2036
Italy Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Server Market Insights
Edge computing architectures and AI-optimized accelerators are reshaping server procurement patterns across Italian data center operators. Dell Technologies leverages vertical integration in storage-class memory to sustain pricing power in enterprise rack deployments. Huawei Technologies anchors its position through captive silicon design for high-density blade configurations. Hewlett Packard Enterprise differentiates via composable infrastructure software that extends hardware lifecycle value for colocation providers.
Data center servers are enterprise-grade computing systems built around x86 or ARM processor architectures with redundant power supplies, ECC memory, and hot-swappable component bays designed for continuous operation in controlled environments. These systems process transactional workloads, host virtualized applications, and serve as the physical substrate for cloud service delivery. Rack servers dominate volume procurement among telecommunications operators building 5G core networks across the peninsula. Blade servers capture premium positioning in financial services due to density requirements for high-frequency trading floors. Hyper-converged infrastructure technology segments expand fastest as mid-market enterprises consolidate storage and compute silos.
Italy's AgID (Agenzia per l'Italia Digitale) enforces cybersecurity certification frameworks for public sector server procurement under the EU Cybersecurity Act. CE marking and EU Code of Conduct for Data Centre Energy Efficiency constrain power density specifications for new builds in Lombardy and Lazio. BIS-equivalent conformity assessments for electromagnetic compatibility shape import pathways for non-EU manufacturers. Stakeholders must monitor whether proposed EU AI Act infrastructure requirements will mandate dedicated inference-optimized server classes for regulated industry deployments.
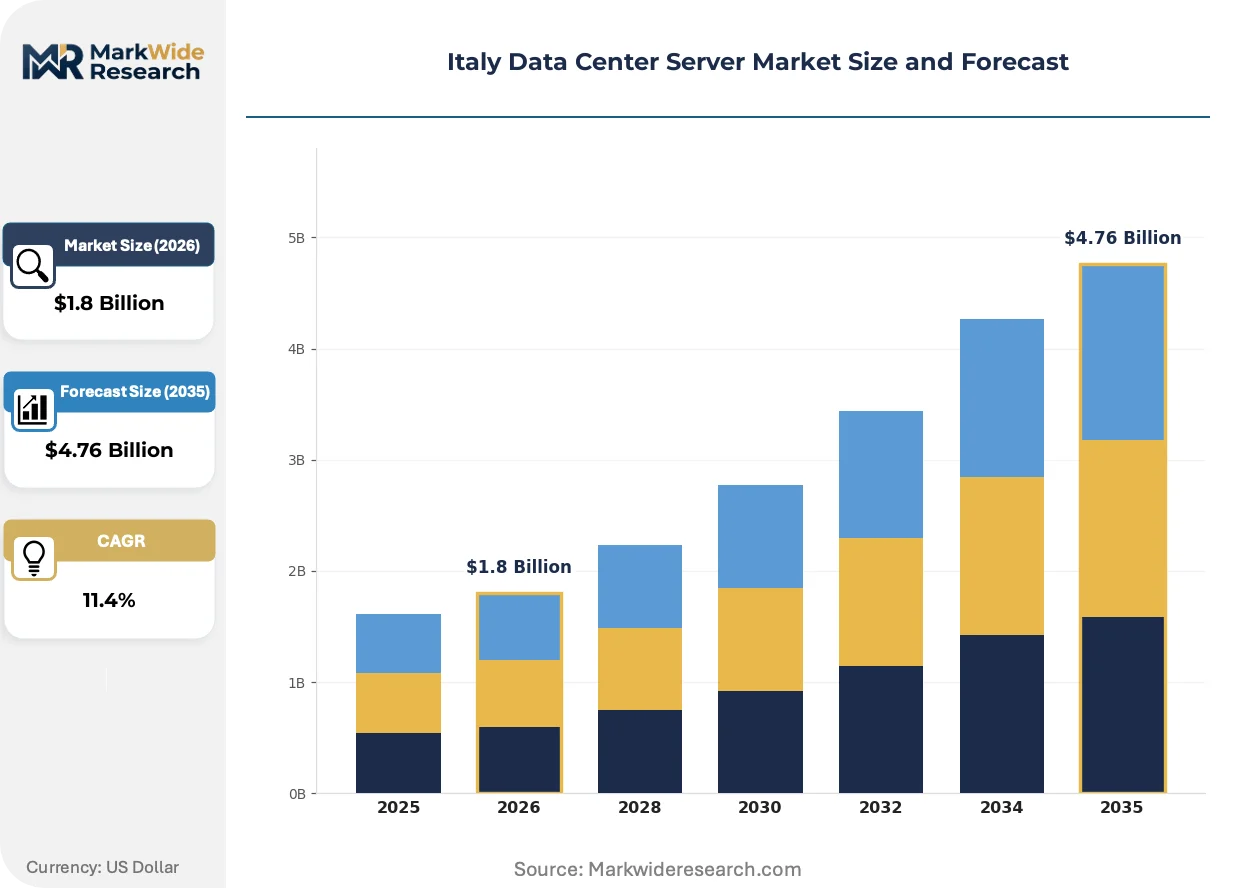
Market Dynamics
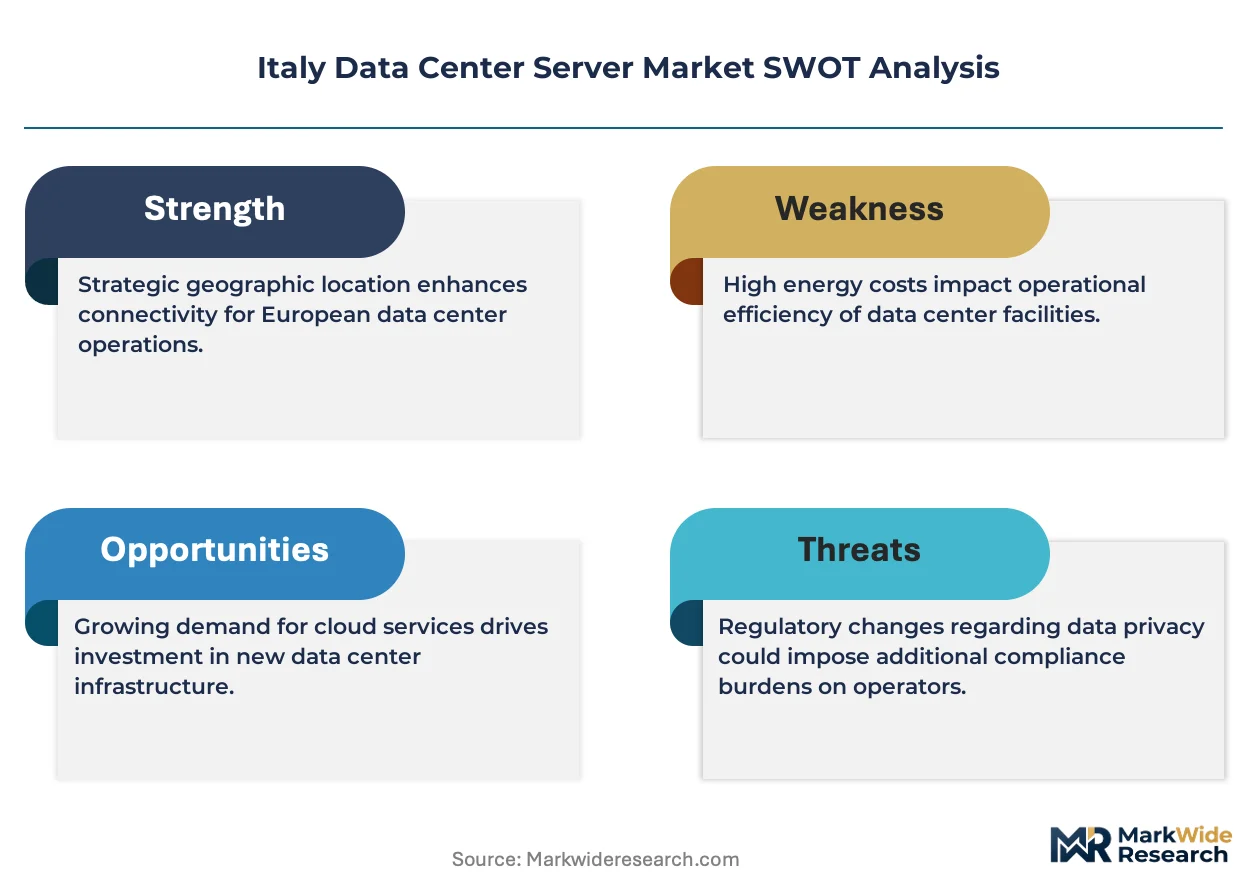
Italy's data center server market is being fundamentally restructured by the PNRR's energy-efficiency mandates, which compel public sector buyers to prioritize liquid-cooled and high-density configurations while phasing out legacy air-cooled infrastructure.
Growth Catalysts
- Algorithmic Trading Expansion:Financial services firms in Milan are deploying specialized servers for low-latency trading platforms, creating concentrated demand for high-frequency optimized hardware.
- EU Cybersecurity Act Certification:AgID's mandatory cybersecurity frameworks for public procurement are accelerating replacement cycles among government data center operators.
- Hyperscale Clustering:Fiber interconnection nodes near Milan are attracting concentrated hyperscale facility development, driving volume server procurement from colocation providers.
Market Restraints
- Silicon Supply Concentration:Dependence on non-EU foundries for advanced x86 and ARM processors creates vulnerability in server supply chains serving Italian enterprises.
- Energy Density Limits:Lombardy and Lazio regional authorities enforce strict power density caps under EU Code of Conduct for Data Centre Energy Efficiency, constraining high-performance server deployments.
- Electromagnetic Compatibility Barriers:BIS-equivalent conformity assessments for non-EU manufacturers extend import timelines and compliance costs for certain server classes.
Strategic Opportunities
- AI Inference Infrastructure:Proposed EU AI Act requirements for regulated industries are expected to create dedicated demand for inference-optimized server classes in banking and healthcare.
- Edge Computing Deployment:5G core network buildouts by telecommunications operators across the peninsula present underpenetrated demand for distributed edge server nodes.
- Hyper-Converged Consolidation:Mid-market enterprises are converging storage and compute silos, opening white space for integrated server-storage appliances outside Milan's hyperscale core.
Industry Challenges
- Liquid Cooling Expertise Gap:Deployment of immersion and direct-to-chip cooling systems requires specialized thermal engineering skills that remain scarce among Italian systems integrators.
- Legacy Virtualization Migration:Enterprises running traditional three-tier architectures face complex workload portability challenges when transitioning to composable infrastructure platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Server Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Modular Servers End User: Telecommunications, Government, Retail, Financial Services Service Type: Managed Services, Colocation, Hosting Services, Cloud Services Technology: Virtualization, Direct Attached Storage, Network Attached Storage, Hyper-Converged Infrastructure |
| Companies Covered | Lenovo, Huawei Technologies, Dell Technologies, NetApp, Atos, Hewlett Packard Enterprise, IBM, Oracle, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Server Market Trends and Innovations
Server procurement patterns across Italian data centers are being actively restructured by three converging forces: thermal design evolution, regulatory certification expansion, and procurement model rationalization.
Direct liquid cooling technologies are penetrating high-performance computing deployments as rack power densities exceed 50 kilowatts. Hyperscale operators in the Milan metropolitan area are adopting immersion cooling for AI training clusters. Air-cooled server architectures are rendering obsolete for workloads above 30 kilowatts per rack.
CE marking requirements under the EU Cybersecurity Act are expanding to cover server firmware and management interfaces. AgID is enforcing these standards through public sector procurement guidelines. Financial services and healthcare providers face the steepest compliance timelines for infrastructure refresh cycles.
Colocation buyers are unbundling hardware acquisition from managed services contracts, shifting toward direct server ownership with software-defined lifecycle management. This pattern disrupts traditional channel relationships between distributors and value-added resellers. The trend is most visible among mid-market enterprises in Turin and Bologna consolidating from fragmented server estates.
Italy Data Center Server Market Segmentation
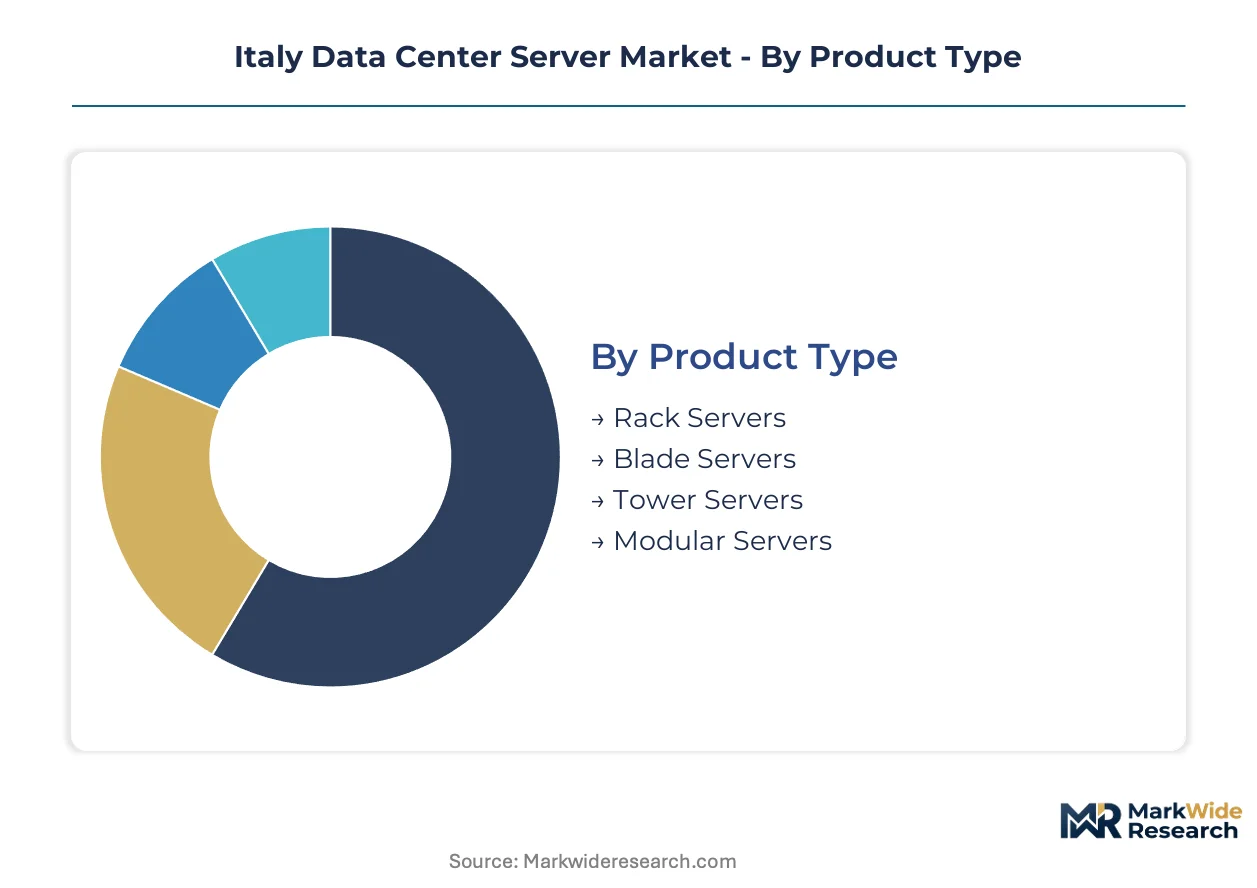
Server procurement patterns across Italian data centers diverge sharply across product architectures, buyer categories, and technology layers. Each segmentation axis reveals distinct concentration points that shape vendor go-to-market priorities and infrastructure investment timelines.
Product Type:
Mature rack configurations anchor enterprise volume while emerging density-optimized form factors capture premium positioning in financial and hyperscale deployments.
- Rack Servers:Standard 19-inch chassis with redundant hot-swappable power supplies and ECC memory banks dominate telecommunications infrastructure buildouts. Telecom operators across the peninsula deploy these for 5G core network functions, driven by AgID procurement frameworks mandating certified hardware for public digital assets.
- Blade Servers:High-density shared infrastructure enclosures with midplane interconnects serve Milan's algorithmic trading floors where space constraints and thermal loads concentrate. Financial services firms prioritize these for low-latency co-location near fiber interconnection nodes, constrained by Lombardy's strict power density caps under EU energy efficiency codes.
- Tower Servers:Standalone pedestal configurations with limited scalability serve small and mid-market enterprises in Turin and Bologna consolidating fragmented server estates.
- Modular Servers:Disaggregated compute sleds with pooled resource architectures appeal to colocation providers seeking hardware lifecycle flexibility.
Rack servers retain volume leadership; blade servers hold the steepest expansion curve.
End User:
Customer concentration patterns reflect sector-specific workload requirements and regulatory exposure to PNRR energy mandates.
- Telecommunications:Operators building 5G standalone core networks drive standardized rack server procurement across the peninsula. TIM and Vodafone Italia deploy virtualized network functions requiring continuous operation certification, accelerated by national broadband coverage targets.
- Financial Services:Milan-based trading houses and retail banks generate concentrated demand for liquid-cooled high-frequency infrastructure. UniCredit and Intesa Sanpaolo refresh data center footprints to meet algorithmic latency requirements while navigating AgID cybersecurity certification timelines.
- Government:Central and regional public administrations face compelled replacement cycles under PNRR energy-efficiency mandates for public digital assets.
- Retail:Omnichannel commerce platforms in the mid-market segment adopt hyper-converged appliances to collapse storage and compute silos.
Telecommunications commands procurement volume; financial services generates the highest per-unit value concentration.
Service Type:
Delivery model preferences are splintering as buyers unbundle hardware ownership from operational management.
- Managed Services:Comprehensive operational outsourcing including remote monitoring, patch management, and capacity planning. Mid-market enterprises in Bologna favor this model to address liquid cooling expertise gaps without building in-house thermal engineering capabilities.
- Colocation:Physical facility leasing with buyer-owned server deployment dominates hyperscale clustering near Milan's fiber nodes. Providers like Aruba and INWIT attract volume server commitments from cloud operators seeking proximity to interconnection infrastructure.
- Hosting Services:Dedicated single-tenant server provisioning with limited customization serves legacy application workloads.
- Cloud Services:Abstracted compute consumption models gain traction among retail and government segments with variable demand profiles.
Colocation absorbs the largest hardware commitment volumes; managed services is climbing the fastest as skills scarcity bites.
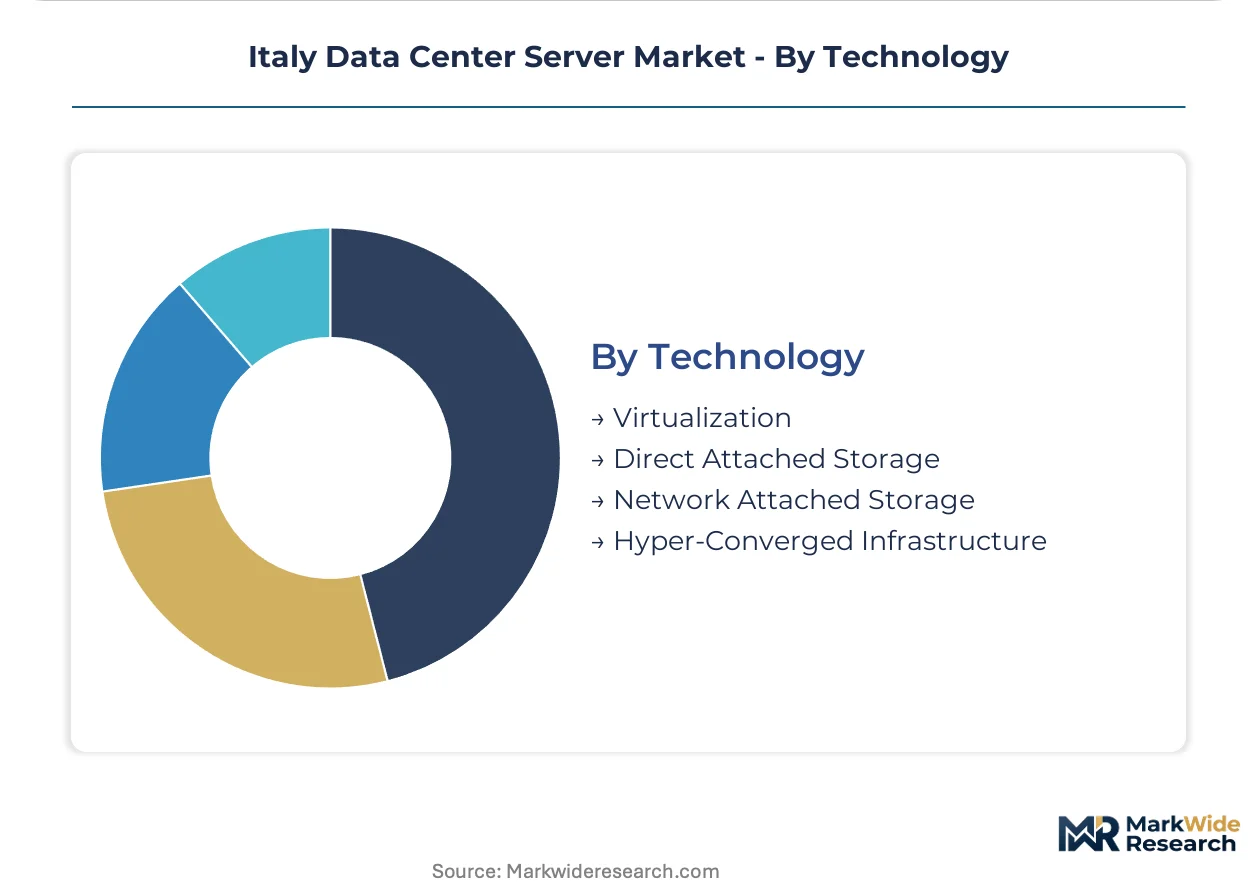
Technology:
Architecture choices determine consolidation economics and compliance posture across buyer segments.
- Hyper-Converged Infrastructure:Integrated compute-storage-networking software-defined stacks collapse traditional three-tier architectures. Mid-market enterprises outside Milan's hyperscale core adopt these appliances to simplify legacy virtualization migrations, constrained by workload portability challenges.
- Virtualization:Hypervisor abstraction layers remain foundational for telecommunications operators deploying network function virtualization, though container displacement pressures mount.
- Direct Attached Storage:Server-internal disk arrays persist in latency-sensitive trading applications where external storage latency is unacceptable.
- Network Attached Storage:File-level shared storage serves departmental workloads with moderate performance requirements.
Virtualization retains installed base dominance; hyper-converged infrastructure is gaining share fastest among consolidation-driven buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications operators and financial services firms concentrate server procurement in northern industrial corridors, with public sector mandates driving replacement cycles across central regions. Regional variations reflect fiber infrastructure density, regulatory enforcement intensity, and sector-specific workload requirements.
Lombardy
Milan's fiber interconnection nodes attract hyperscale facility clustering from colocation providers. AgID cybersecurity certification frameworks accelerate server refresh cycles among public digital asset operators. Algorithmic trading houses in the metropolitan area deploy liquid-cooled high-density configurations constrained by regional power density caps.
Piedmont
Automotive suppliers and industrial automation firms generate steady demand for edge-optimized rack servers. The region's manufacturing base adopts hyper-converged appliances to consolidate legacy virtualization estates. Turin-based mid-market enterprises favor managed service delivery models to address liquid cooling expertise gaps.
Emilia-Romagna
Machine tool manufacturers and packaging automation specialists drive modular server procurement for factory floor data processing. Bologna's enterprise cluster shows fastest adoption of direct server ownership with software-defined lifecycle management. Regional systems integrators struggle to source thermal engineering talent for immersion cooling deployments.
Lazio
Central government data centers face compelled infrastructure replacement under PNRR energy-efficiency mandates for public digital assets. Rome's public administration cluster prioritizes certified hardware for classified workload processing. Regional authorities enforce strict EU Code of Conduct compliance for new facility power density specifications.
Veneto
Fashion and luxury goods supply chain operators deploy edge servers for real-time inventory synchronization. Padua and Verona host growing colocation presence serving mid-market enterprises consolidating from fragmented server estates. Regional demand concentrates in tower-to-rack migration projects among family-owned industrial groups.
Italy Data Center Server Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement pathways in the Italian market. The vendor base separates into three strategic tiers: vertically integrated full-stack providers, component-specialist fabricators, and systems integrators with captive deployment capabilities. Dominant competitive moves include strategic partnerships with colocation operators and portfolio diversification into liquid-cooled configurations.
Among Asia-based technology conglomerates, Huawei Technologies occupies a position exemplifying captive silicon design approaches for high-density blade configurations. Dell Technologies and Hewlett Packard Enterprise represent the vertically integrated tier, with the former anchoring storage-class memory integration and the latter exemplifying composable infrastructure software positioning for colocation providers. These three companies illustrate distinct archetype strategies for sustaining pricing power in enterprise rack deployments.
| Leading Market Players |
|---|
| Lenovo |
| Huawei Technologies |
| Dell Technologies |
| NetApp |
| Atos |
| Hewlett Packard Enterprise |
| IBM |
| Oracle |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwan's leading-edge foundry nodes is compressing server processor allocation timelines for Italian system integrators, forcing buyers toward longer-term offtake contracts with embedded price indexation clauses.
Pricing Analysis
Cost-plus contracts with quarterly indexation to DRAM and NAND spot markets dominate enterprise rack procurement. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled AI-optimized configurations from air-cooled legacy hardware. Pricing pressure stems from hyperscale buyers consolidating vendor panels and demanding volume rebates. Mid-market enterprises in Turin and Bologna exhibit highest price sensitivity due to fragmented procurement budgets, while Milan financial services firms prioritize latency performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese ODMs including Foxconn Industrial Internet and Wistron for server motherboard fabrication. Processor supply draws from Taiwan, South Korea, and the United States for x86 and ARM silicon. Memory components hinge on South Korean and Chinese fab output. Single-source vulnerability concentrates in advanced packaging capacity for AI accelerators. Distribution runs through authorized distributors with value-added reseller networks serving regional system integrators across Lombardy and Lazio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent scarcity constrains deployment velocity for liquid-cooled infrastructure, creating a structural bottleneck that rewards early capability investments in direct-to-chip and immersion cooling competencies.
For Market Incumbents: Insulate margin position by deepening captive silicon design capabilities for high-density blade configurations and securing exclusive distribution agreements with Milan colocation operators. Threat from Huawei's integrated supply chain demands accelerated certification investment under AgID cybersecurity frameworks to maintain public sector access. Priority lever centers on vertical integration into liquid cooling component supply.
For New Entrants and Emerging Players: Build out edge-optimized rack server offerings targeting telecommunications operators deploying 5G standalone core networks across southern Italian regions underserved by incumbent channel coverage. White space concentrates in managed service delivery for mid-market enterprises in Emilia-Romagna lacking in-house thermal engineering. Go-to-market angle emphasizes software-defined lifecycle management tools that simplify legacy virtualization migration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation providers with captive hyperscale commitments near Milan fiber interconnection nodes. Long-term viability favors asset-light managed service operators with demonstrated liquid cooling deployment expertise. Acquisition target archetype includes regional systems integrators with AgID certification credentials and established relationships with public digital asset operators. Signal to watch is PNRR funding disbursement velocity for energy-efficiency infrastructure mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Capability Buildout | Addresses 50+ kilowatt rack density requirements now standard for Milan AI training clusters. |
| AgID Cybersecurity Certification Investment | Unlocks public sector procurement pathways under EU Cybersecurity Act enforcement timelines. |
| Hyperscale Colocation Partnership | Secures volume server commitments from cloud operators clustering near fiber interconnection nodes. |
| Composable Infrastructure Software Development | Extends hardware lifecycle value for colocation providers unbundling managed services from hardware. |
| Edge Server Geographic Expansion | Captures 5G core network buildouts across underserved southern Italian telecommunications markets. |
Research Methodology
The analysis maps rack, blade, and hyper-converged server architectures, each validated through data center operators, systems integrators, and procurement officers at financial services firms. Primary interviews with thermal engineering specialists, AgID certification consultants, and colocation facility managers combined with secondary validation against SEC filings from Dell Technologies and Hewlett Packard Enterprise, hyperscaler capex disclosures, and EU procurement databases. Bottom-up shipment estimates triangulated against top-down infrastructure investment tracking across the analysis window.
Assumptions held fixed include PNRR energy-efficiency mandate enforcement intensity and EU AI Act infrastructure requirement finalization timing. Variables included hyperscale facility buildout pace near Milan fiber nodes and telecommunications operator 5G standalone core deployment schedules. Segmentation dimensions modeled encompass product architecture, end-user sector, service delivery model, and technology layer. CAGRs derived from regression analysis of historical procurement patterns against infrastructure investment commitments. Forecast inputs incorporated foundry capacity allocation forecasts and regional power density regulatory enforcement trajectories.
Sensitivities concentrate around Taiwan semiconductor supply disruptions and Lombardy regional authority power density cap adjustments. Forecasts reflect documented assumptions regarding PNRR disbursement timelines and EU regulatory finalization. Quarterly review of foundry utilization rates, AgID certification backlog data, and hyperscale facility permitting approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Ireland Data Center Rack Market