
 South America Data Center Power Market | 2026-2036
South America Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Power Market Insights
Electrical engineering talent scarcity is collapsing project timelines across the Andes and Southern Cone. Schneider Electric leverages its regional training academies to sustain installation capacity in Brazil and Chile. Vertiv anchors critical power delivery through its localized UPS assembly operations. ABB competes on medium-voltage switchgear specialization for hyperscale campuses.
Data center power encompasses the generation, conditioning, distribution, and backup infrastructure that maintains continuous electrical supply to server halls, typically operating at 380-480V three-phase with redundancy tiers from N to 2N+1 architecture. Its primary purpose is eliminating downtime for digital service delivery across financial, cloud, and enterprise workloads. UPS systems dominate capital allocation among power type segments due to their non-negotiable role in bridging utility interruptions. Liquid-cooled deployments are pulling the fastest growth within cooling technology as rack densities exceed 30kW per cabinet. Colocation providers concentrate procurement volume among end users, though cloud service providers are capturing margin pools through direct utility contracting.
ANEEL in Brazil mandates renewable energy quotas for new industrial connections, while Chile's SEC enforces seismic resilience standards for electrical infrastructure. These frameworks elevate upfront equipment specifications but unlock green financing channels for compliant developers. Argentina's CNE prioritizes grid stability agreements before permitting large loads, creating procedural bottlenecks. Stakeholders must monitor regulatory divergence between Mercosur members when standardizing procurement templates.
Market Dynamics
ANEEL's renewable energy integration mandates are forcing hyperscale developers in Brazil to redesign procurement specifications for medium-voltage switchgear and transformer infrastructure, compressing traditional equipment selection timelines.
Growth Catalysts
- Cloud service provider expansion:Hyperscalers are commissioning multi-megawatt facilities across São Paulo's metropolitan corridor, pulling transformer and switchgear orders from local manufacturers.
- ANEEL renewable quotas:Brazil's national electric energy regulator mandates renewable sourcing for new industrial connections, unlocking green financing channels for compliant data center developers.
- Liquid cooling adoption:Rack densities exceeding 30kW per cabinet are accelerating deployment of integrated power-thermal systems in high-performance computing environments.
Market Restraints
- Electrical engineering talent scarcity:Project timelines across the Andes and Southern Cone are collapsing due to insufficient certified installation technicians for 380-480V three-phase systems.
- Argentina's CNE grid stability protocols:The national electricity regulator requires binding grid stability agreements before permitting large loads, creating procedural bottlenecks for facility commissioning.
- Copper and silicon steel price volatility:Raw material input costs for transformer cores and busbar assemblies are destabilizing equipment procurement budgets.
Strategic Opportunities
- Chile's SEC seismic resilience standards:The electrical regulator's earthquake-hardening requirements for switchgear create premium specification tiers that unlock specialized financing for compliant developers.
- Colombia's underpenetrated Andean corridor:Bogotá's emerging cloud node concentration offers first-mover positioning for UPS and generator set providers before hyperscaler cluster formation.
- Direct utility contracting by cloud operators:Hyperscalers bypassing colocation intermediaries to negotiate power purchase agreements creates margin capture opportunities for equipment vendors with energy advisory capabilities.
Industry Challenges
- 2N+1 redundancy certification timelines:Uptime Institute tier certification for dual-corded power architectures is extending project delivery schedules by eight to fourteen months in markets with limited local assessor presence.
- Legacy 208V infrastructure integration:Retrofitting existing facilities with 380-480V distribution requires phased load migration strategies that complicate live-environment upgrades for financial services tenants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Power Market |
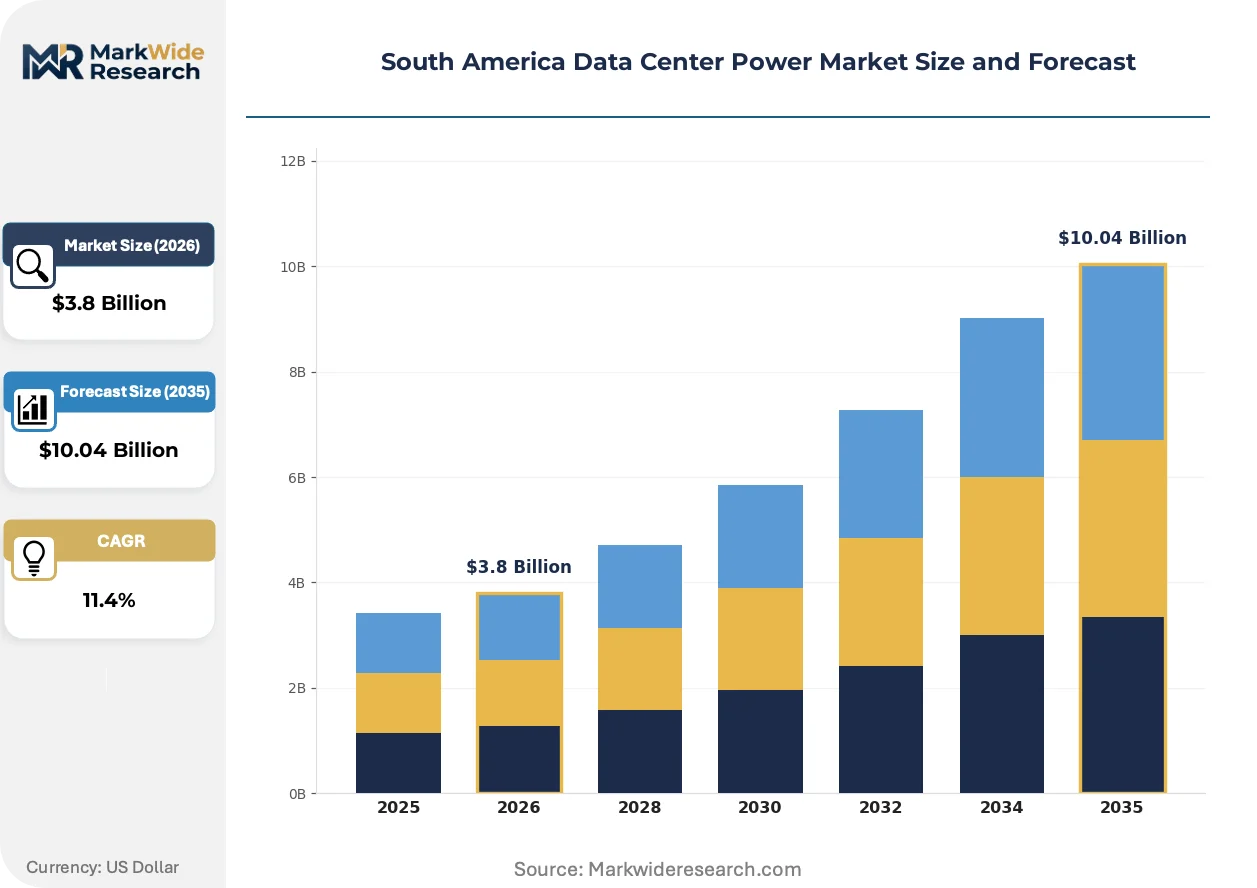
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: Utility Supply, Diesel Generators, UPS Systems, Renewable Energy End User: Colocation Providers, Enterprises, Cloud Service Providers, Financial Institutions Cooling Technology: Air-Cooled, Liquid-Cooled, Evaporative Cooling, Hybrid Cooling Deployment Model: On-Premises, Cloud, Hybrid, Edge |
| Companies Covered | Schneider Electric, Vertiv, ABB, Eaton, Delta Electronics, Ascenty, Equinix, Scala Data Centres, OData, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Power Market Trends and Innovations
Liquid-cooled power infrastructure is actively reshaping capital allocation patterns as thermal and electrical systems converge at the rack level. Equipment vendors are reconfiguring product architectures to capture this integration premium.
Modular UPS architectures with lithium-ion battery integration are bifurcating the backup power market. Hyperscale operators in São Paulo are specifying containerized 2.5MW blocks with 15-minute ride-through capacity. This technology compression is collapsing the traditional separation between short-duration UPS and long-duration generator sets, forcing vendors to reposition around integrated microgrid controllers rather than discrete product categories.
ANEEL's renewable energy quotas are mandating power purchase agreement structures that tie grid connection permits to documented clean energy sourcing. Developers must now contract directly with wind and solar generators before receiving industrial connection authorization. Colocation providers in Brazil's Southeast region are responding by forming energy trading consortia to aggregate procurement volume and meet minimum contract thresholds.
Buyer concentration among cloud service providers is compressing equipment specification diversity. Amazon Web Services, Microsoft Azure, and Google Cloud are harmonizing their South American facility designs around standardized 48V DC bus architectures with integrated lithium battery racks. This standardization is marginalizing traditional 480V AC distribution vendors who lack DC power conversion portfolios, particularly in São Paulo's hyperscaler corridor where procurement decisions are increasingly centralized at global engineering headquarters.
South America Data Center Power Market Segmentation
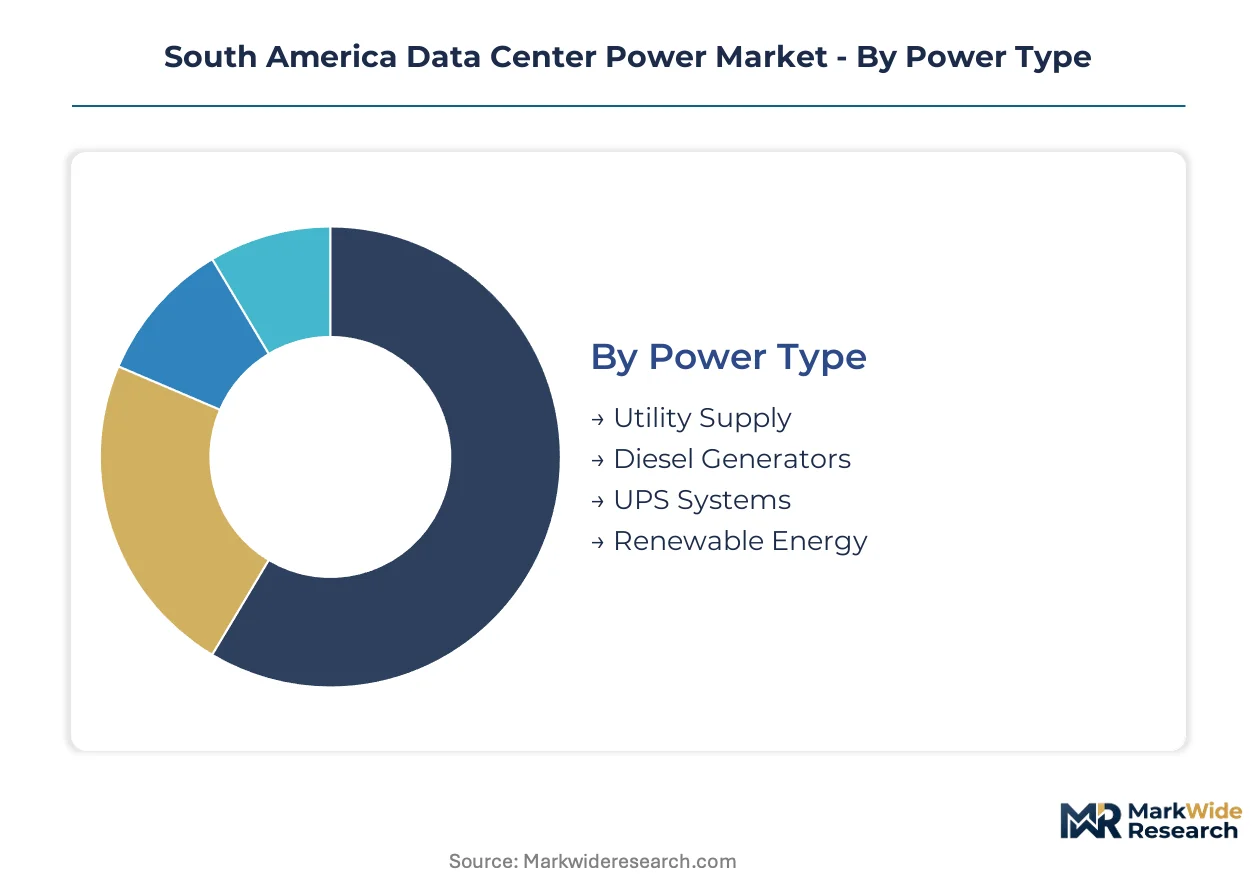
Power infrastructure segmentation in South America reflects divergent regulatory pressures across Brazil, Chile, and Argentina. Procurement patterns cluster around compliance pathways rather than pure technical optimization.
Power Type:
Brazil's ANEEL mandates renewable energy quotas for new industrial connections, while Chile's SEC enforces seismic resilience standards for backup systems. These frameworks reshape equipment specification tiers across the region.
- Utility Supply:Grid-sourced power operating at 380-480V three-phase forms the primary feed for São Paulo's hyperscale corridor. ANEEL's renewable sourcing requirements force developers to secure documented clean energy contracts before receiving industrial connection permits.
- UPS Systems:Uninterruptible power supply units bridge utility interruptions through battery-backed conditioning, typically configured in N to 2N+1 redundancy architectures. Cloud service providers in Brazil's Southeast region are specifying containerized 2.5MW lithium-ion blocks with 15-minute ride-through capacity.
- Diesel Generators:Long-duration backup engines for extended outages.
- Renewable Energy:Direct solar and wind integration for compliance.
UPS Systems handles the majority of throughput; Renewable Energy is expanding most quickly on share.
End User:
Customer concentration determines procurement volume and specification standardization. Cloud operators bypass intermediaries to negotiate direct utility contracts.
- Cloud Service Providers:Hyperscale operators including Amazon Web Services, Microsoft Azure, and Google Cloud commission multi-megawatt facilities with harmonized 48V DC bus architectures. These buyers centralize procurement decisions at global engineering headquarters, marginalizing vendors lacking DC conversion portfolios.
- Colocation Providers:Multi-tenant facility operators aggregate demand from smaller enterprises. Brazil's Southeast colocation sector is forming energy trading consortia to meet ANEEL's minimum contract thresholds for renewable procurement.
- Enterprises:Single-occupant corporate data centers with custom requirements.
- Financial Institutions:Banks and exchanges demanding 2N+1 uptime certification.
Cloud Service Providers dominate capital deployment; Colocation Providers capture the steepest volume climb as intermediaries aggregate fragmented demand.
Cooling Technology:
Thermal management selection tracks rack density escalation. Liquid-cooled deployments are pulling the fastest growth as densities exceed 30kW per cabinet.
- Liquid-Cooled:Direct-to-chip and immersion cooling systems integrate power and thermal infrastructure at the rack level. High-performance computing environments in São Paulo's metropolitan corridor are accelerating deployment of these integrated power-thermal systems.
- Air-Cooled:Conventional raised-floor CRAC and CRAH units for standard densities.
- Evaporative Cooling:Water-based adiabatic systems for dry climates.
- Hybrid Cooling:Combined liquid-air architectures for transitional loads.
Air-Cooled retains installed base dominance; Liquid-Cooled is gaining share fastest on new deployment.
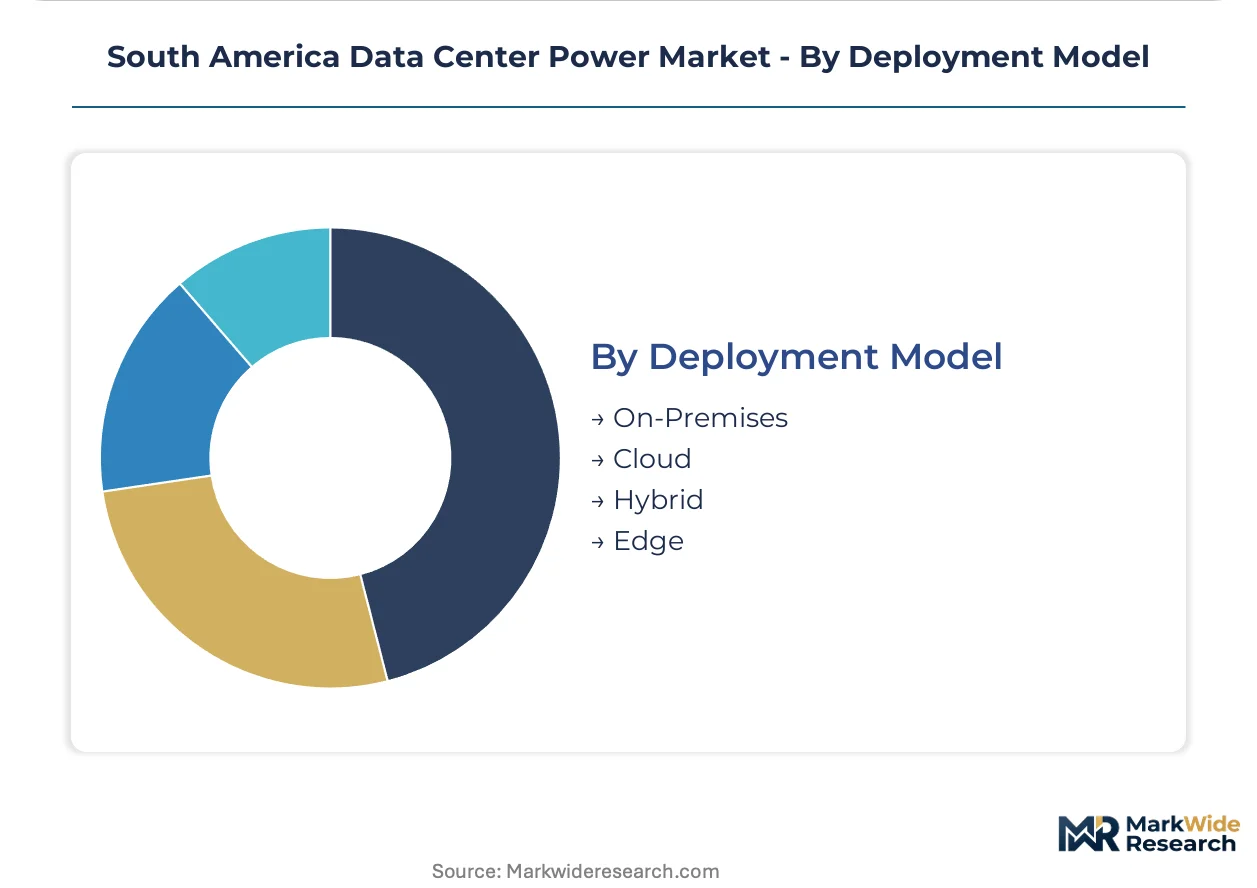
Deployment Model:
Facility architecture selection reflects workload latency requirements and data sovereignty constraints across Mercosur markets.
- Cloud:Hyperscale centralized facilities with standardized designs. Argentina's CNE requires binding grid stability agreements before permitting these large loads, creating procedural bottlenecks for facility commissioning.
- On-Premises:Enterprise-owned facilities with custom infrastructure.
- Hybrid:Split workloads across owned and leased capacity.
- Edge:Distributed micro-data centers for low-latency processing.
Cloud deployment absorbs the bulk of new power capacity; Edge is climbing fastest on project count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANEEL's renewable energy mandates in Brazil anchor regulatory momentum across South America's data center power sector. Chile's SEC and Argentina's CNE impose complementary compliance frameworks that reshape equipment procurement patterns. Each national regulator elevates distinct technical specifications for electrical infrastructure.
Brazil
Hyperscale cloud operators commission multi-megawatt facilities across São Paulo's metropolitan corridor, pulling transformer and switchgear orders from local manufacturers. ANEEL mandates documented renewable energy contracts before granting industrial grid connections, forcing developers to secure wind and solar power purchase agreements. Colocation providers in Brazil's Southeast region form energy trading consortia to aggregate procurement volume and meet minimum contract thresholds.
Chile
Seismic resilience requirements from SEC reshape switchgear and backup system specifications for data center developers in Santiago's emerging cloud node concentration. The electrical regulator's earthquake-hardening standards create premium equipment tiers that unlock specialized green financing channels. High-performance computing deployments in the capital region accelerate adoption of integrated power-thermal systems as rack densities escalate.
Argentina
Binding grid stability agreements required by CNE before permitting large electrical loads create procedural bottlenecks for facility commissioning timelines in Buenos Aires. The national electricity regulator prioritizes documented utility coordination for hyperscale connections. Financial services tenants in the capital drive demand for 2N+1 redundancy certification despite extended Uptime Institute assessment schedules.
Colombia
Bogotá's underpenetrated Andean corridor offers first-mover positioning for UPS and generator set providers before hyperscaler cluster formation accelerates. The country's central bank and energy planning unit coordinate on data center load forecasting for grid investment programs. Emerging cloud node concentration in the capital region attracts preliminary equipment specification discussions from international vendors.
South America Data Center Power Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South America's data center power market structure. The upper tier commands specification-setting authority through direct relationships with hyperscale cloud operators. Specialist vendors compete on localized assembly capacity and regulatory compliance expertise. Dominant competitive moves include strategic partnerships with renewable energy developers and portfolio diversification into integrated microgrid controllers.
Among the integrated equipment suppliers, Schneider Electric, Vertiv, and ABB exemplify distinct strategic archetypes in regional market positioning. Schneider Electric leverages established training academies to sustain installation capacity for medium-voltage infrastructure across Brazil and Chile. Vertiv anchors critical power delivery through localized UPS assembly operations that compress delivery timelines for São Paulo's hyperscaler corridor. ABB occupies a position emphasizing medium-voltage switchgear specialization for seismic-resilient campus designs under Chile's SEC framework.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| ABB |
| Eaton |
| Delta Electronics |
| Ascenty |
| Equinix |
| Scala Data Centres |
| OData |
| Others |
Pricing and Supply Chain Analysis
ANEEL's renewable energy integration mandates gate both supplier qualification and price differentiation in Brazil's data center power sector, forcing equipment vendors to certify clean energy sourcing before bidding on hyperscale projects while enabling premium pricing tiers for compliant manufacturers. Cloud service providers concentrate procurement volume through long-term offtake structures that compress margins for non-compliant suppliers.
Pricing Analysis
Long-term power purchase agreements dominate procurement structures as hyperscalers lock in renewable supply before ANEEL grants industrial connection permits. Price differentiation hinges on seismic certification grade under Chile's SEC framework and volume scale across São Paulo's metropolitan corridor. Cost compression in standard switchgear tiers is intensifying because copper and silicon steel volatility destabilizes transformer core budgets. Colocation providers exhibit highest price sensitivity due to margin pressure from direct utility contracting by cloud operators.
Supply Chain Analysis
Extended lead times for medium-voltage switchgear and lithium-ion battery racks are stretching project timelines across the Andes corridor. Manufacturing concentrates in Brazil, Chile, and China for core electrical infrastructure. Supply chains draw from copper mining in Peru, silicon steel from East Asian mills, and semiconductor components from Taiwan. Single-source vulnerability around specialized transformer cores creates bottlenecks when hyperscaler clusters synchronize expansion waves. Distribution runs through authorized integrators with ANEEL certification rather than direct vendor-to-developer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where integrated microgrid controller deployments and energy advisory retainers expand faster than discrete UPS hardware sales. Recurring revenue from predictive maintenance contracts on lithium-ion battery systems captures margin pools that capital equipment transactions cannot sustain.
For Market Incumbents: Secure backward integration into localized UPS assembly capacity to compress delivery timelines for São Paulo's hyperscaler corridor against emerging Chinese competitors. Anchor medium-voltage switchgear portfolios with SEC seismic certification to capture premium specification tiers in Santiago. Defend position by expanding training academy footprints to address electrical engineering talent scarcity collapsing installation timelines across Brazil and Chile. For New Entrants and Emerging Players: Anchor in Bogotá's underpenetrated Andean corridor before hyperscaler cluster formation accelerates, targeting colocation providers with containerized 2.5MW UPS blocks. Target Argentina's CNE procedural bottlenecks by offering grid stability agreement advisory bundled with generator set procurement. Lead with energy trading consortium formation services to help Brazilian colocation providers meet ANEEL minimum contract thresholds. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled power infrastructure as thermal-electrical integration at the rack level demands specialized manufacturing footprints. Long-term viability favors vertically integrated players controlling both UPS assembly and microgrid controller software stacks. Acquisition targets should demonstrate ANEEL compliance pathways and SEC seismic certification capabilities. Watch for inflection when cloud providers centralize procurement decisions at global engineering headquarters, marginalizing regional distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Certification Program | ANEEL compliance unlocks green financing channels for Brazilian developers securing grid connections. |
| Localized UPS Assembly Expansion | Vertiv's São Paulo operations demonstrate how regional manufacturing compresses hyperscaler delivery timelines. |
| Seismic Resilience Specialization | SEC earthquake-hardening standards in Chile create premium equipment tiers with specialized financing access. |
| Energy Trading Consortium Formation | Brazilian colocation providers aggregate procurement volume to meet ANEEL minimum renewable contract thresholds. |
| Integrated Microgrid Controller Development | Modular UPS with lithium-ion integration collapses traditional separation between short-duration backup and long-duration generation. |
Research Methodology
A standing panel of data center engineering directors, electrical contractors certified for 380-480V three-phase systems, ANEEL regulatory affairs specialists, and hyperscaler procurement managers provided ongoing calibration across primary interview programs. Secondary validation drew from SEC seismic standard filings, ANEEL renewable integration mandates, Uptime Institute tier certification databases, and copper futures exchange data. Bottom-up equipment shipment tracking triangulated against top-down utility interconnection permit analysis.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures and transformer manufacturer order backlogs across the projection horizon. Segmentation modeling spanned power type, end user concentration, cooling technology density tiers, and deployment model architecture. CAGRs derived from equipment procurement pipeline analysis and grid connection permit trajectories. Forecast inputs incorporated ANEEL mandate compliance timelines and SEC certification backlog durations.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscaler expansion in São Paulo's corridor and stable copper pricing; material deviation in cloud provider capital allocation or raw material volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Europe Hyperscale Data Center Market